
 Commercial Glazing Market | 2026-2036
Commercial Glazing Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Glazing Market Intelligence
The EU Green Deal's focus on building energy performance is restructuring demand for advanced glazing systems across Europe. Permasteelisa dominates complex, large-scale curtain wall projects, particularly for landmark towers. Harmon Inc. leverages its extensive North American footprint to secure major contracts in the corporate and institutional sectors. W&W Glass LLC specializes in intricate custom facade solutions for high-profile architectural designs in the United States.
Commercial glazing refers to the glass systems used in the exterior envelopes of non-residential structures. These systems are engineered to manage light transmission, solar heat gain, and thermal insulation, often specified by U-value and Solar Heat Gain Coefficient (SHGC). Within product types, Low-E glass commands a significant share due to stringent energy codes. Office buildings and shopping complexes represent the largest application segments, driven by both new construction and energy-efficiency retrofits.
Regulatory frameworks like the US EPA’s ENERGY STAR program and the EU's Construction Products Regulation set performance benchmarks. China’s GB standards for building energy conservation also dictate glazing specifications, creating regional product requirements. These mandates directly influence material selection and system design. Stakeholders must now balance the higher initial investment in dynamic or smart glass against its long-term operational savings and occupant comfort benefits.
Market Dynamics
The central tension in the commercial glazing market is the interplay between tightening government energy efficiency mandates, such as the EU Green Deal, and the material science innovations required to meet these performance benchmarks at scale.
Growth Catalysts
- Energy Code Stringency:The EU Green Deal and similar regulations mandate deep energy retrofits for commercial buildings, directly boosting demand for high-performance glazing with low U-values.
- Dynamic Glass Adoption:Expanding use in corporate headquarters and transportation hubs provides occupants with on-demand control over glare and solar heat, improving comfort and productivity.
- Retrofit Programs:Government and utility incentives for upgrading existing office and retail building envelopes accelerate the replacement of older, inefficient single-pane or non-coated glass systems.
Market Restraints
- High Initial Cost:The significant upfront investment for advanced systems like electrochromic or vacuum-insulated glass remains a barrier for projects with constrained capital budgets.
- Manufacturing Complexity:Production of large, custom-shaped, multi-layer insulated glass units for curtain walls requires specialized equipment and quality control, limiting the supplier base.
- System Integration Hurdles:Integrating dynamic glazing controls with legacy Building Automation Systems (BAS) can be complex and costly, deterring adoption in some retrofit projects.
Strategic Opportunities
- Building-Integrated Photovoltaics (BIPV):The convergence of glazing with solar cell technology creates an opportunity for facades to become active power-generating assets, not just passive envelopes.
- Emerging Market Codes:As nations in Southeast Asia and the Middle East implement stricter building energy standards, it opens new markets for advanced Low-E and spectrally selective coatings.
- Data Center Glazing:Specialized glazing solutions designed for the unique thermal management and security requirements of data centers represent a high-value niche application.
Industry Challenges
- Installer Skill Gap:A shortage of technicians trained to install and commission complex curtain wall systems and integrated smart glass technologies leads to project delays and quality issues.
- Fragmented Certification:Navigating disparate performance testing and certification requirements, such as US ENERGY STAR versus EU CE marking, adds complexity and cost for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Glazing Market |
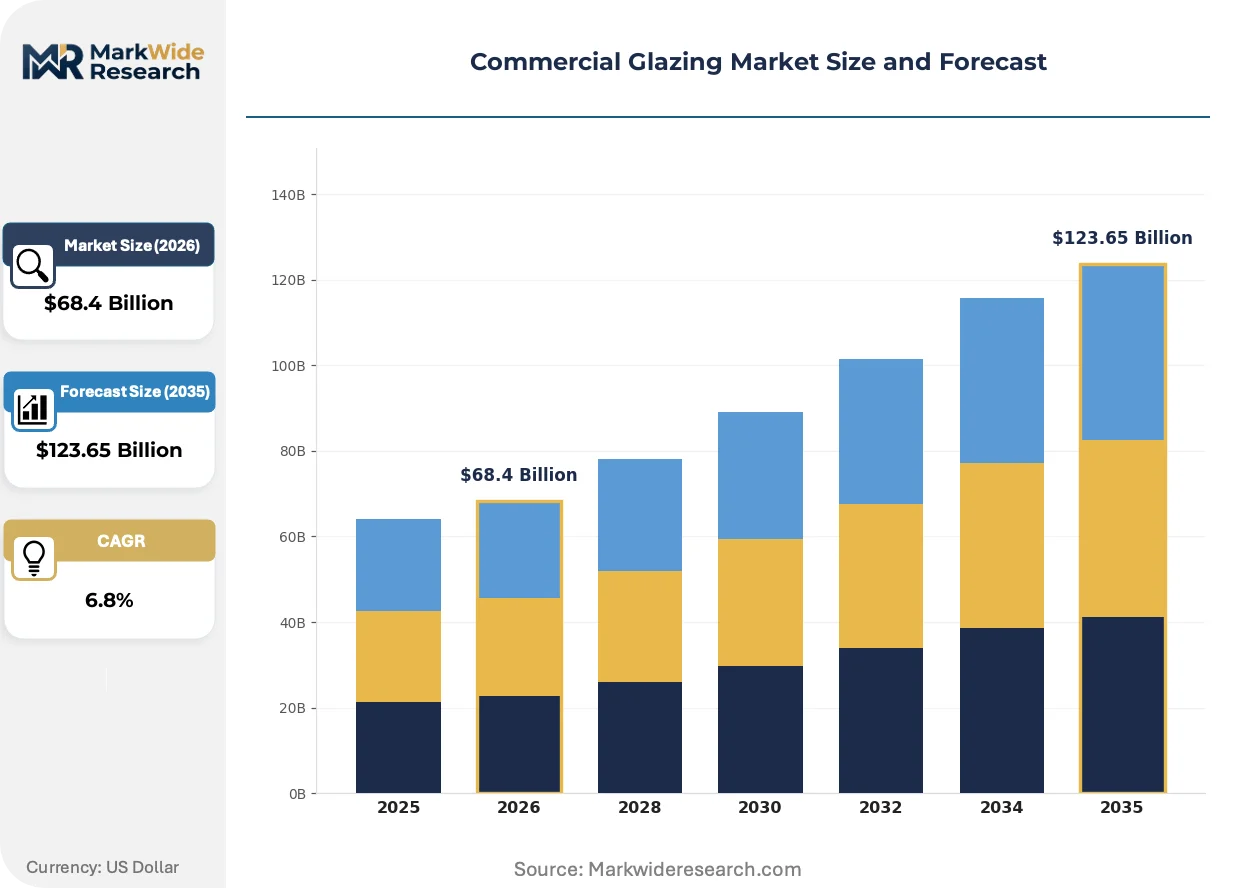
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Insulated Glass, Tinted Glass, Low-E Glass Application: Office Buildings, Shopping Complexes, Educational Institutions, Airports, Hospitality Venues Installation Type: Frameless, Structural Sealant, Curtain Wall, Storefront Systems, Skylights End User: Property Developers, Construction Firms, Facility Managers, Architects, Renovation Experts |
| Companies Covered | W&W Glass LLC, Flynn Group of Companies, Harmon Inc., Permasteelisa, Crown Corr Inc., New Hudson Facades, Enclos Corp., Giroux Glass Inc., Reflection Window + Wall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Glazing Market Strategic Shifts & Innovations
Product development is shifting focus from purely passive thermal performance to active, intelligent building envelope management. This evolution is driven by the convergence of material science, digital controls, and a new understanding of occupant-centric design.
Electrochromic glass uses a low-voltage electrical charge to control its tint level, managing light transmission and solar heat gain. Premium corporate offices and airports are the primary adopters, seeking to enhance occupant comfort and reduce HVAC load. This technology is automating the building's response to changing sun conditions, reducing the need for mechanical shades and manual adjustments.
The US EPA’s ENERGY STAR program continually raises the performance bar for its "Most Efficient" designation for windows and glass systems. This directive compels manufacturers to invest in R&D for better thermal breaks, advanced Low-E coatings, and multi-cavity designs. The commercial retrofit segment is most impacted, with building owners specifying certified products to secure incentives.
A shift in project specification involves evaluating glazing on total lifecycle cost and occupant wellness, not just upfront price. This trend elevates the influence of facade consultants over general contractors in procurement decisions for high-performance buildings. The practice is most visible in new institutional and Class-A office construction in North America.
Commercial Glazing Market Segmentation
Understanding the commercial glazing market through segmentation reveals how product innovation, application-specific demands, and end-user priorities shape purchasing decisions. This granular view helps stakeholders identify key growth pockets and tailor solutions to specific market needs across diverse commercial environments.
Product Type:
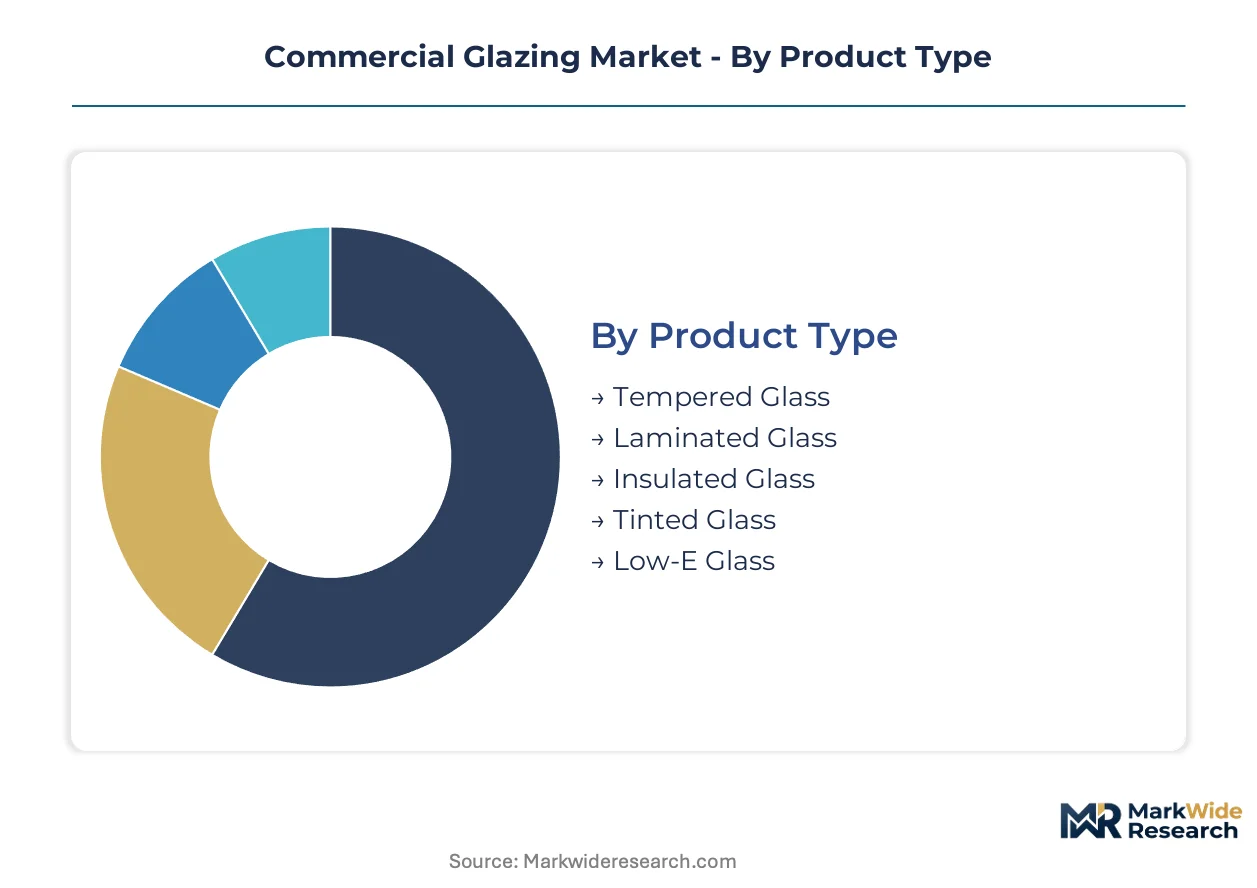
Segmentation by product type highlights the varying levels of material integration, from foundational glass panels to advanced, system-embedded solutions.
- Low-E Glass:Low-emissivity (Low-E) glass features microscopic metallic coatings that reflect infrared light while allowing visible light to pass, significantly reducing heat transfer. Demand for Low-E glass is particularly strong in the United States, driven by stringent energy codes and building owners seeking to minimize HVAC loads.
- Insulated Glass:Insulated glass units (IGUs) consist of two or more glass panes separated by a sealed air or gas-filled space, providing enhanced thermal and acoustic insulation. Office buildings across Europe increasingly specify IGUs to comply with EU Green Deal energy performance directives and enhance occupant comfort.
- Tempered Glass:Tempered glass undergoes a controlled thermal process, making it four times stronger than annealed glass and shattering into small, blunt fragments for safety.
- Laminated Glass:Laminated glass incorporates a polyvinyl butyral (PVB) interlayer between two glass sheets, offering superior security, sound attenuation, and UV protection for commercial facades.
- Tinted Glass:Tinted glass contains additives that absorb solar radiation, reducing glare and heat gain, commonly used in areas requiring passive solar control.
Volume placements concentrate in Tempered Glass; the faster expansion belongs to Low-E Glass.
Application:
The commercial glazing market's application segments reflect diverse performance requirements across various building types and their operational needs.
- Office Buildings:Office buildings require glazing solutions balancing natural light, thermal comfort, and acoustic performance to optimize occupant productivity and energy efficiency. Retrofitting existing office buildings in the United States with high-performance glazing is a significant driver, propelled by energy efficiency standards.
- Shopping Complexes:Shopping complexes utilize extensive glazing for natural light, visual merchandising, and facade aesthetics, while managing solar heat gain and security. New construction projects for large retail developments in China are increasingly adopting advanced glazing to meet GB standards for energy conservation.
- Educational Institutions:Educational institutions prioritize durable, safe, and energy-efficient glazing to create conducive learning environments and reduce operational costs.
- Airports:Airports demand robust, secure, and acoustically insulated glazing systems for large-span facades, controlling noise and managing solar exposure in expansive terminals.
- Hospitality Venues:Hospitality venues employ glazing for aesthetic appeal, panoramic views, and guest comfort, often incorporating dynamic glass for privacy and glare control.
Office buildings and shopping complexes represent the largest application segments, with airports exhibiting a strong growth trajectory due to specialized demands.
Installation Type:
Installation types delineate the structural and aesthetic approaches to integrating glass into building envelopes, ranging from visible frames to seamless facades.
- Curtain Wall:Curtain wall systems are non-load-bearing exterior walls attached to the building structure, providing weather protection, thermal insulation, and architectural expression. Large-scale curtain wall projects for landmark towers across major global cities demand these systems, meeting high aesthetic and performance standards.
- Structural Sealant:Structural sealant glazing (SSG) uses high-strength silicone sealants to bond glass directly to the building's structure, creating a flush, frameless exterior appearance. High-profile architectural designs in the United States frequently utilize SSG for its sleek aesthetics, enhancing the visual impact of modern commercial buildings.
- Frameless:Frameless glazing relies on minimal hardware and direct glass-to-glass connections, often used for interior partitions or specific exterior applications requiring maximum transparency.
- Storefront Systems:Storefront systems are typically non-load-bearing, aluminum-framed glass assemblies designed for ground-floor retail and commercial entrances, offering quick installation.
- Skylights:Skylights integrate glazing into roof structures, providing overhead natural light and contributing to energy efficiency, particularly in large commercial spaces and atriums.
Curtain wall systems command significant project value, while structural sealant glazing is gaining traction in architecturally driven designs.
End User:
End-user categories reflect the primary decision-makers and stakeholders influencing glazing procurement, each with distinct priorities and purchasing criteria.
- Property Developers:Property developers focus on maximizing asset value, aesthetic appeal, and long-term operational efficiency, often balancing initial cost with marketability and tenant appeal. New Class-A office construction in North America sees property developers specifying high-performance glazing to attract premium tenants and meet sustainability certifications.
- Architects:Architects drive material selection based on design vision, performance specifications, and aesthetic integration, influencing facade solutions from concept to completion. The increasing influence of facade consultants, often working with architects, shifts procurement decisions towards total lifecycle cost and occupant wellness.
- Construction Firms:Construction firms execute glazing installation, prioritizing ease of integration, project timelines, and adherence to structural and safety specifications.
- Facility Managers:Facility managers oversee building operations, focusing on durability, maintenance costs, energy performance, and occupant comfort throughout the building's lifecycle.
- Renovation Experts:Renovation experts specialize in upgrading existing building envelopes, assessing the feasibility and benefits of replacing older glazing with modern, energy-efficient systems.
Property developers initiate large-scale projects, while architects increasingly influence the specification of advanced glazing technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global commercial glazing demand outpaces localized production capabilities, creating distinct regional growth patterns. Stringent energy efficiency mandates in developed economies drive innovation for high-performance systems. Meanwhile, rapid urbanization and infrastructure development in emerging markets fuel demand for foundational glazing solutions.
United States
Demand for advanced glazing in the United States is propelled by both new construction and extensive renovation projects. The US EPA’s ENERGY STAR program sets performance benchmarks, influencing material selection for energy-efficient buildings. Major metropolitan areas like New York City and Chicago actively retrofit office buildings to meet updated energy codes.
Germany
Building energy performance directives from the EU Green Deal are restructuring demand for advanced glazing systems across Germany. German building codes mandate low U-values, increasing specification of high-performance insulated glass units. Cities such as Frankfurt, a financial hub, see significant investment in green building certifications for commercial properties.
China
China’s commercial glazing market is driven by large-scale new construction projects, particularly for shopping complexes and office towers. The country's GB standards for building energy conservation dictate glazing specifications, creating specific product requirements. Major urban centers like Shanghai and Beijing are adopting advanced glazing to meet national energy efficiency targets.
India
Rapid urbanization and infrastructure development are primary demand drivers for commercial glazing across India. The Bureau of Indian Standards (BIS) promotes energy-efficient building materials, influencing glazing choices in new developments. Tier-1 cities such as Mumbai and Delhi experience a surge in high-rise commercial and retail construction.
United Arab Emirates
The United Arab Emirates exhibits strong growth in commercial glazing due to ambitious architectural projects and a hot climate. Local regulations, including the Dubai Green Building Regulations, mandate energy-efficient facades for new constructions. Dubai and Abu Dhabi feature numerous landmark towers requiring specialized, high-performance glazing solutions.
Commercial Glazing Market Key Industry Players
The competitive structure tilts toward a blend of specialized solution providers and large-scale project integrators. Strategic archetypes include niche custom facade fabricators, comprehensive curtain wall system suppliers, and regional installation specialists. Dominant competitive moves involve both geographic expansion into high-growth urban centers and technology integration for smart glazing systems.
Among the prominent players, Permasteelisa, an Italian-based firm, exemplifies global leadership in complex, large-scale curtain wall projects for landmark towers, showcasing advanced engineering capabilities. Harmon Inc., a prominent North American entity, anchors the segment for major corporate and institutional contracts across its extensive regional footprint, leveraging established client relationships. Specialists in intricate custom facade solutions, W&W Glass LLC represents precision engineering for high-profile architectural designs within the United States, catering to bespoke client needs.
| Leading Market Players |
|---|
| W&W Glass LLC |
| Flynn Group of Companies |
| Harmon Inc. |
| Permasteelisa |
| Crown Corr Inc. |
| New Hudson Facades |
| Enclos Corp. |
| Giroux Glass Inc. |
| Reflection Window + Wall |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's energy performance mandates significantly gate access to qualified supply and premium-tier pricing for advanced commercial glazing systems. These regulations drive demand for highly specialized glass products that meet stringent thermal and energy efficiency benchmarks, commanding higher prices.
Pricing Analysis
Value-based pricing on long-term operational savings anchors commercial glazing procurement decisions. Project-based pricing models dominate, reflecting the custom nature of large-scale facade installations. Price differentiation stems from performance certifications, such as specific U-values and Solar Heat Gain Coefficients, and the degree of customization required for architectural integration. Cost compression for standard insulated glass units intensifies due to increased manufacturing capacity in Asia. Property developers and architects generally exhibit lower price sensitivity for high-performance systems, while renovation experts prioritize cost-effectiveness in retrofitting projects.
Supply Chain Analysis
Mandatory dual-sourcing requirements for critical components often characterize large commercial glazing projects. Core glass manufacturing concentrates in China, Germany, and the United States. The supply chain draws from specialized input materials, including advanced Low-E coatings from European chemical firms and polyvinyl butyral (PVB) interlayers from global polymer producers. Logistics chokepoints for transporting oversized, custom-shaped glass panels pose a structural risk to project timelines. Distribution runs through a network of specialized fabricators and project-specific direct delivery to construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installer skill gaps represent the primary capacity bottleneck in the commercial glazing market, propping up pricing for complex system installations. This scarcity creates project delays and quality control challenges across regions.
For Market Incumbents: Deploy strategic partnerships with vocational training institutions to develop certified installer programs. This addresses the critical skill gap impacting complex curtain wall and smart glass installations. Invest in advanced automation for insulated glass unit manufacturing to reduce labor dependency and improve consistency. Acquire smaller, specialized facade engineering firms to broaden design capabilities and secure niche market access. This strategy mitigates the threat from emerging custom facade fabricators.
For New Entrants and Emerging Players: Underserved mid-tier commercial building owners in secondary US cities present a penetrable segment for energy-efficient glazing retrofits. Focus on offering standardized, high-performance insulated glass units with simplified installation protocols. A direct-to-installer distribution model, coupled with comprehensive technical support, can accelerate market entry. Target educational institutions and healthcare facilities with solutions emphasizing durability and long-term cost savings, leveraging government incentives.
For Investors and Strategic Acquirers: Widespread adoption of Building-Integrated Photovoltaics (BIPV) is the leading indicator that the market is shifting towards active energy generation facades. This signals a long-term opportunity for integrated solutions providers within a 5-10 year window. Target specialized manufacturers of electrochromic glass or vacuum-insulated glass with proprietary coating technologies. A significant increase in government funding for green building incentives in Southeast Asia would serve as a key signal to watch for regional expansion opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in automated fabrication lines | Enhances precision and reduces labor costs for complex insulated glass units. |
| Acquire smart glass technology developers | Integrates advanced dynamic control capabilities into building envelopes. |
| Expand installer training programs | Addresses the critical skill gap for high-performance curtain wall systems. |
| Form strategic alliances with facade consultants | Secures early involvement in high-value, architecturally driven projects. |
| Develop region-specific product certifications | Ensures compliance with diverse regulatory frameworks in emerging markets. |
Research Approach
Document review covered industry reports, company financial filings, and government energy efficiency standards, complemented by interviews with commercial glazing manufacturers, facade engineering consultants, property developers, and facility managers. Secondary validation involved analysis of trade association publications, academic studies on building science, and regulatory updates from the US EPA, EU, and China. The analysis employed both bottom-up and top-down triangulation to ensure data consistency.
Volume and value projections were developed using a robust analytical framework across the analysis window. The model segmented demand by product type, application, installation type, end-user, and key geographic regions. Compound Annual Growth Rates were derived from historical data, current market dynamics, and projected technological advancements. Key forecast inputs included projected new commercial construction starts and anticipated energy code stringency changes.
Revisions become necessary when significant shifts in regulatory mandates or material science breakthroughs materialize. Forecasts reflect assumptions documented at the time of publication. Deviation in global economic growth or unexpected changes in building material costs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Metal Roofing Market