
 Industrial Insulation Testers Market | 2026-2036
Industrial Insulation Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Insulation Testers Market Outlook
IEC 61557-2 compliance tier upgrades is unwinding legacy analog tester inventories across European utilities and Asian manufacturing plants. Fluke Corporation leverages its digital platform architecture to sustain premium positioning in North American electrical safety testing programs. Megger anchors its competitive stance through deep calibration service networks that bind maintenance contractors to long-term instrumentation contracts. Yokogawa Electric Corporation specializes in time-domain reflectometry integration, differentiating its offerings for cable-intensive infrastructure operators.
Industrial insulation testers are instruments designed to measure electrical resistance between conductive parts and insulating materials, typically applying test voltages from 250V to 15kV DC to detect degradation, moisture ingress, or contamination that compromises dielectric integrity. These devices serve the primary commercial purpose of preventing catastrophic equipment failure, unplanned downtime, and personnel injury in energized industrial environments. Digital insulation testers are capturing margin pools from analog predecessors as manufacturing plants mandate data-logging capabilities for predictive maintenance workflows. Multifunction insulation testers represent the fastest-expanding product configuration, combining resistance measurement with continuity, voltage, and loop testing to reduce tool proliferation for maintenance contractors.
The US Occupational Safety and Health Administration enforces electrical safe work practices that mandate periodic insulation verification, while the International Electrotechnical Commission publishes IEC 61557 standards governing test method accuracy and voltage ranges. IEEE 43 provides additional guidance for rotating machinery insulation resistance interpretation, shaping product specification requirements for motor assessment applications. Stakeholders must monitor evolving harmonization between regional electrical safety codes and emerging smart grid communication protocols that could redefine field tester connectivity requirements.
Market Dynamics
Multifunction insulation tester adoption is compressing replacement cycles across power generation and heavy manufacturing sectors as facilities consolidate testing protocols into single-platform instruments. IEC 61557-2 compliance mandates are accelerating analog inventory obsolescence while digital platform investments reshape procurement specifications for maintenance contractors and utility operators.
Growth Catalysts
- Grid Modernization Mandates:Germany's industrial maintenance outsourcing programs are accelerating replacement demand for aging transformer testing equipment. Utility operators prioritize instruments with integrated data-logging for predictive maintenance workflows.
- IEC 61557-2 Standardization:European and Asian manufacturing plants face compliance-driven obsolescence of legacy analog testers. Digital insulation testers with automated voltage stepping capture specification priority in medium-voltage equipment assessments.
- Aging Infrastructure Replacement:Power generation facilities across North America and Europe expand procurement of multifunction units to manage deteriorating transformer fleets. Time-domain reflectometry integration addresses cable-intensive infrastructure diagnostic requirements.
Market Restraints
- Semiconductor Supply Concentration:Precision analog-to-digital converters and high-voltage switching components face sourcing bottlenecks from concentrated East Asian foundry capacity. Lead times for critical ICs extend tester manufacturing cycles.
- Calibration Service Network Density:Deep calibration infrastructure binds maintenance contractors to incumbent suppliers, creating switching friction for new entrants. Geographic coverage gaps in emerging markets limit instrument deployment.
- High-Voltage Safety Certification Costs:IEC 61010-1 third-party testing and regional electrical safety approvals impose substantial fixed costs on product development. Smaller manufacturers face margin compression from compliance expenditure requirements.
Strategic Opportunities
- Smart Grid Communication Integration:Convergence of insulation testing platforms with IEC 61850 protocols enables automated data transmission to asset management systems. Utilities in Germany and the US pilot connected diagnostic workflows.
- Rental and Subscription Channels:Equipment-as-a-service models reduce capital barriers for small electrical contractors. North American industrial distributors expand short-term rental fleets for seasonal maintenance peaks.
- Renewable Energy Installation Surge:Wind turbine generator and solar inverter commissioning drives demand for portable 5-15kV testers. Offshore wind projects in the North Sea specify marine-rated multifunction instruments.
Industry Challenges
- Field Technician Skill Stratification:Advanced diagnostic functions require interpretation training that outpaces vocational program curricula. Manufacturers absorb support costs from misapplied time-domain reflectometry analysis.
- Legacy System Integration Complexity:Digital testers with proprietary data formats create friction against existing maintenance management software. Open API development demands engineering resources that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Insulation Testers Market |
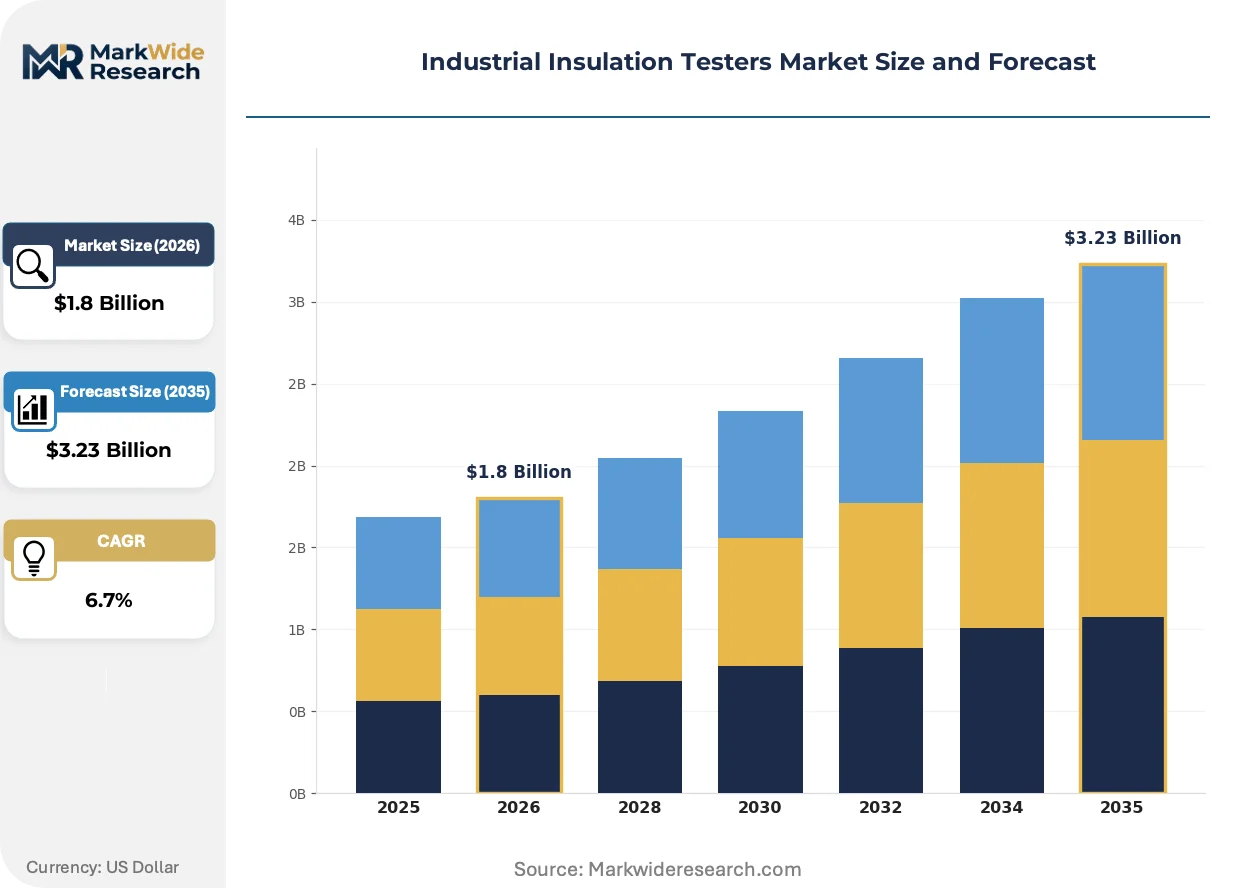
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Insulation Testers, Digital Insulation Testers, Insulation Resistance Testers, Multifunction Insulation Testers Technology: High Voltage Test, Low Voltage Test, Time Domain Reflectometry, Insulation Integrity Testing End User: Manufacturing Plants, Power Generation Facilities, Maintenance Contractors, Industrial Equipment Suppliers Application: Electrical Safety Testing, Cable Insulation Testing, Motor Insulation Assessment, Transformer Insulation Testing |
| Companies Covered | Fluke Corporation, Megger, Yokogawa Electric Corporation, Hioki Corporation, Kyoritsu Electrical Instruments, Chauvin Arnoux, B&K Precision Corporation, Meco Instruments Pvt. Ltd, TES Electrical Electronic Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Insulation Testers Market Strategic Shifts
Digital platform architectures are displacing analog measurement cores across industrial insulation testing, enabling automated test sequencing and cloud-connected asset tracking. This technological transition reconfigures value capture toward software-enabled service bundles and away from discrete hardware margins.
Time-domain reflectometry integration is bifurcating product positioning between cable-focused infrastructure operators and rotating machinery specialists. Offshore wind developers and metropolitan rail networks adopt TDR-equipped testers for fault location in complex cable topologies. Motor maintenance contractors resist feature complexity, preserving demand for simplified resistance-only instruments. The market is bifurcating into premium diagnostic platforms and streamlined compliance tools.
REACH substance restrictions and RoHS recast directives are tightening material composition requirements for high-voltage probe assemblies and molded enclosures. European manufacturers reformulate insulating plastics to eliminate restricted phthalates and brominated flame retardants. Asian component suppliers face qualification delays as they re-engineer legacy material specifications for EU market access.
Maintenance contractors are consolidating instrument purchases through integrated supplier agreements that bundle calibration, training, and firmware updates. Industrial distributors in Germany and the US displace traditional electrical wholesalers for high-value testing equipment transactions. Power generation utilities negotiate enterprise pricing that subordinates individual site procurement autonomy to centralized category management.
Industrial Insulation Testers Market Segmentation
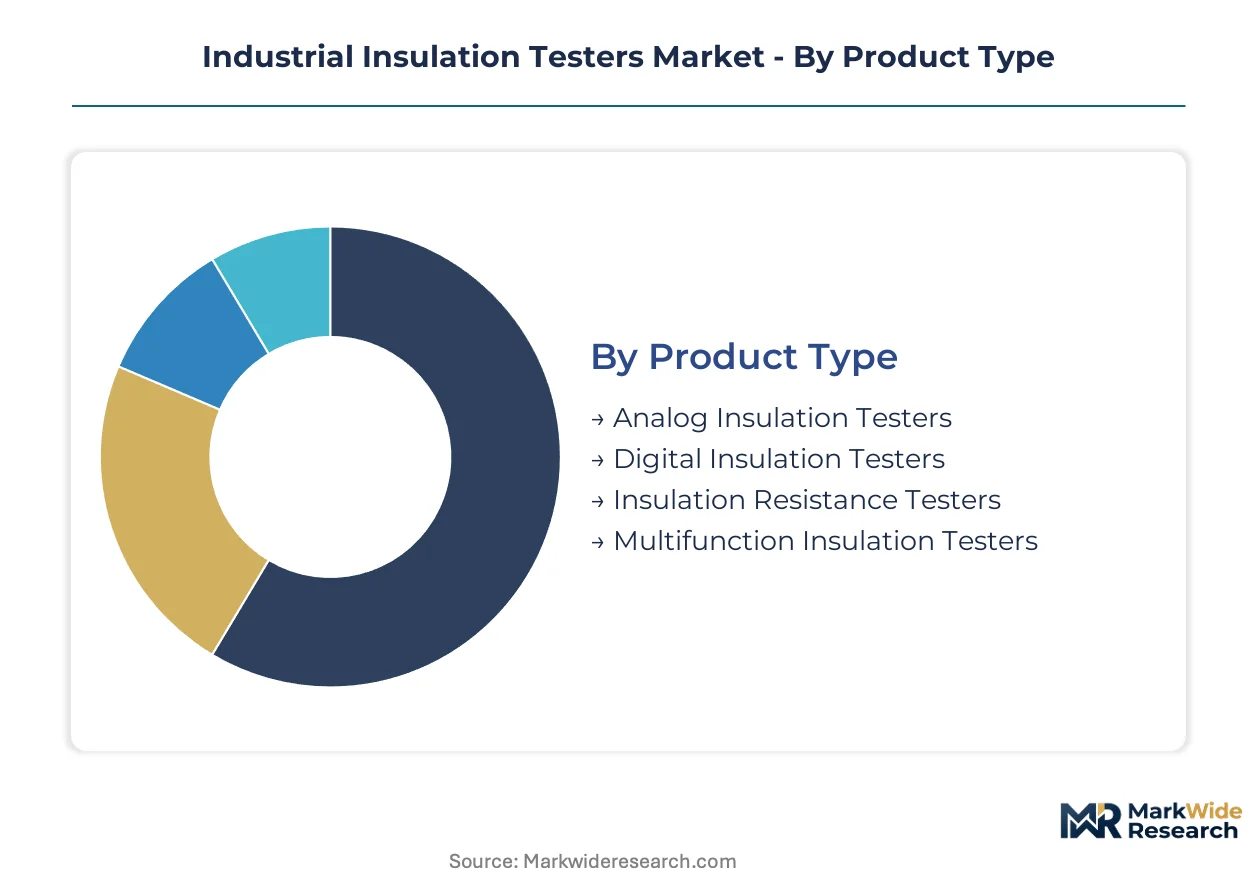
Industrial insulation testers serve distinct operational requirements across voltage classes, diagnostic methodologies, and end-use environments. Segmentation reveals how procurement priorities diverge between compliance-driven replacement cycles and predictive maintenance technology investments.
Product Type:
Domestic production concentrates in Germany and Japan for precision digital platforms, while analog tester manufacturing has migrated to lower-cost Asian supply bases serving price-sensitive maintenance contractors.
- Digital Insulation Testers:These instruments employ precision analog-to-digital converters with automated voltage stepping and integrated data-logging for IEC 61557-2 compliance documentation. German utilities and North American power generation facilities specify these units for transformer fleet management programs requiring predictive maintenance integration.
- Multifunction Insulation Testers:Combining resistance measurement with continuity, voltage, and loop testing capabilities, these platforms reduce tool proliferation for field technicians. Maintenance contractors in Germany and the US favor consolidated instruments that streamline electrical safety testing protocols across diverse equipment types.
- Analog Insulation Testers:Legacy electromechanical measurement cores persist in developing markets where capital constraints outweigh data-logging requirements.
- Insulation Resistance Testers:Dedicated resistance-only instruments serve motor maintenance specialists resisting feature complexity.
Multifunction insulation testers hold the largest share; momentum sits with digital insulation testers.
Technology:
Cost tiers stratify sharply between commodity low-voltage validation tools and premium diagnostic platforms incorporating advanced signal processing.
- Time Domain Reflectometry:TDR integration enables precise fault location in complex cable topologies through pulse propagation analysis. Offshore wind developers in the North Sea and metropolitan rail networks specify TDR-equipped testers for cable-intensive infrastructure diagnostics.
- High Voltage Test:Applying 5-15kV DC potentials, these systems detect dielectric degradation in medium-voltage transformers and rotating machinery. Power generation facilities mandate high-voltage capability for aging asset assessment per IEEE 43 interpretation guidelines.
- Low Voltage Test:250-1000V instruments address routine electrical safety verification in commercial and light industrial settings.
- Insulation Integrity Testing:Comprehensive diagnostic suites combine multiple measurement modalities for asset condition trending.
High voltage test technology dominates current procurement volumes; time domain reflectometry is expanding most quickly.
End User:
Customer type determines purchasing modality, with utilities favoring enterprise agreements and contractors prioritizing rental flexibility.
- Power Generation Facilities:These operators deploy multifunction and high-voltage platforms for transformer fleet management and rotating machinery assessment. Aging infrastructure replacement programs across Germany and the US drive specification of instruments with IEC 61850 protocol compatibility.
- Maintenance Contractors:Electrical service providers consolidate testing protocols through portable multifunction units reducing truck inventory. German industrial maintenance outsourcing programs accelerate replacement demand for consolidated instrument platforms.
- Manufacturing Plants:Production facilities mandate data-logging capabilities for quality documentation and predictive maintenance workflows.
- Industrial Equipment Suppliers:OEMs specify validation instruments for factory acceptance testing and commissioning services.
Power generation facilities command the deepest instrument specifications; maintenance contractors are gaining share fastest.
Application:
Application focus shapes voltage range requirements and determines whether resistance-only or multifunction platforms satisfy operational needs.
- Transformer Insulation Testing:Medium-voltage transformer assessment demands 10-15kV test capability with automated voltage stepping for IEC 61557-2 compliance. German grid modernization programs and North American utility asset management initiatives concentrate procurement in this application.
- Cable Insulation Testing:Complex cable topologies in offshore wind and rail infrastructure require TDR-integrated fault location. North Sea wind projects specify marine-rated multifunction instruments for subsea cable commissioning.
- Motor Insulation Assessment:IEEE 43 guidance shapes resistance interpretation for rotating machinery, preserving demand for simplified measurement tools.
- Electrical Safety Testing:OSHA-mandated periodic verification drives baseline demand across industrial facilities.
Transformer insulation testing anchors current revenue; cable insulation testing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in industrial insulation testers tilt toward net exporters with precision manufacturing bases, while import dependency characterizes emerging markets with expanding infrastructure programs but limited domestic instrument production.
Germany
Industrial maintenance outsourcing and grid modernization programs accelerate replacement cycles for transformer testing equipment. IEC 61557-2 compliance mandates drive specification of digital platforms with automated voltage stepping. The Ruhr industrial cluster concentrates procurement for aging asset assessment programs.
United States
OSHA-enforced electrical safe work practices mandate periodic insulation verification across power generation facilities. Utility asset management initiatives prioritize instruments with integrated data-logging for predictive maintenance workflows. Texas and California anchor demand from oil-refining and technology manufacturing sectors respectively.
China
Domestic manufacturing plants face compliance-driven obsolescence of legacy analog testers as export-oriented facilities adopt IEC standards. MIIT industrial upgrading programs support precision instrument development. The Yangtze River Delta concentrates production capacity for both domestic consumption and regional export.
Japan
METI energy efficiency directives push power utilities toward predictive maintenance investments in aging transformer fleets. JIS standards alignment with IEC protocols facilitates instrument interoperability. The Chubu region around Nagoya hosts concentrated electrical equipment manufacturing demanding validation instruments.
United Kingdom
Offshore wind development in the North Sea drives specification of marine-rated multifunction instruments for subsea cable commissioning. HSE electrical safety enforcement maintains baseline demand across industrial facilities. Scottish renewable energy clusters represent the fastest-expanding regional demand pocket.
Industrial Insulation Testers Market Competitive Environment
Concentration sits with diversified electrical testing conglomerates and specialized precision instrument manufacturers rather than fragmented regional assemblers. The vendor base stratifies across three tiers: premium diagnostic platforms with integrated software ecosystems, mid-range multifunction instruments for maintenance contractors, and price-optimized units for developing market penetration. Two dominant competitive moves define current positioning: calibration service network expansion to create switching friction, and digital platform architecture investments to capture recurring software revenue streams.
Within the premium diagnostic tier, Fluke Corporation and Megger occupy anchor positions representing North American and European instrumentation heritage respectively. Yokogawa Electric Corporation exemplifies the Asia-Pacific specialist archetype with concentrated expertise in signal processing applications. These three entities collectively illustrate how geographic origin and historical specialization shape competitive positioning without predetermining technology adoption trajectories.
| Leading Market Players |
|---|
| Fluke Corporation |
| Megger |
| Yokogawa Electric Corporation |
| Hioki Corporation |
| Kyoritsu Electrical Instruments |
| Chauvin Arnoux |
| B&K Precision Corporation |
| Meco Instruments Pvt. Ltd |
| TES Electrical Electronic Corp. |
| Others |
Value Chain & Pricing Dynamics
IEC 61010-1 third-party testing requirements simultaneously gate supplier qualification and stratify price tiers, forcing manufacturers to absorb fixed compliance costs that concentrate margin pressure on mid-range instrument portfolios while premium diagnostic platforms capture returns through bundled calibration services.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with IEC 61557-2 compliant digital platforms commanding substantial premiums over legacy analog alternatives. Cost compression in the economy tier is intensifying because East Asian foundry capacity constraints extend component lead times. Maintenance contractors exhibit the highest price sensitivity, while power generation utilities prioritize total cost of ownership over unit acquisition costs.
Supply Chain Analysis
Extended lead times for precision analog-to-digital converters and high-voltage switching components have stretched manufacturing cycles across the industry. Component sourcing concentrates in Japan, Taiwan, and South Korea for critical semiconductors, with final assembly distributed across Germany, China, and the United States. Supply chain risk centers on single-source vulnerability for specialized high-voltage ICs. Distribution runs through industrial distributors in Germany and the United States, displacing traditional electrical wholesalers for high-value testing equipment transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified calibration technicians and IEC 61557-2 certification expertise are scarce relative to expanding demand, creating durable competitive moats for incumbents with established service infrastructure while constraining new entrant scalability.
For Market Incumbents: Shield installed base relationships by deepening calibration service network density in Germany and the United States, creating switching friction against emerging competitors. Expand backward integration into high-voltage semiconductor sourcing to mitigate foundry concentration risk. Prioritize firmware update subscriptions to capture recurring revenue streams as hardware margins compress. For New Entrants and Emerging Players: Differentiate on TDR-integrated diagnostic platforms for offshore wind cable commissioning, where specification complexity outpaces incumbent product refresh cycles. Target maintenance contractor rental channels in North America, where capital barriers favor equipment-as-a-service models. Pursue marine-rated instrument certification as a go-to-market wedge against established terrestrial-focused portfolios. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital platform development, favoring scaled players with existing software ecosystems over hardware-only specialists. Acquisition targets should demonstrate captive calibration infrastructure and IEC 61850 protocol integration capabilities. Watch for inflection signals in utility smart grid pilot programs converting to production deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | Deep service infrastructure binds maintenance contractors to long-term instrumentation contracts in Germany. |
| Digital Platform Architecture Investment | Cloud-connected asset tracking enables recurring software revenue capture from predictive maintenance workflows. |
| TDR Integration Development | Time-domain reflectometry capability addresses cable-intensive infrastructure diagnostics for North Sea wind projects. |
| IEC 61850 Protocol Certification | Smart grid communication integration qualifies instruments for utility enterprise procurement specifications. |
| Equipment-as-a-Service Launch | Short-term rental fleets reduce capital barriers for seasonal maintenance peaks among electrical contractors. |
Study Parameters
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration against secondary validation from SEC filings, customs trade data, IEC standard documentation, and utility procurement databases. Primary fieldwork combined structured interviews with electrical testing equipment users and channel partners. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across voltage class, technology integration level, and end-user category.
Consistency checks validated volume and value outputs against external benchmarks throughout the modeling period. The analytical framework modeled product type, technology tier, end-user segment, and application focus dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating infrastructure replacement cycle timing, regulatory compliance mandate phasing, and renewable energy installation forecasts.
Forecasts assume regulatory continuity in OSHA electrical safety enforcement and IEC standard harmonization; material policy shifts would require re-modeling. Semiconductor supply constraints, calibration technician availability, and utility capital expenditure cycles represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Dedicated Outdoor Air System Market