
 Traffic Road Marking Coatings Market | 2026-2036
Traffic Road Marking Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Road Marking Coatings Market Analysis
Performance-based maintenance contracts for retroreflectivity guarantees is decoupling coating sales from simple material volume. The Sherwin-Williams Company leverages its North American distribution network to dominate municipal specification channels. 3M Company sustains technology leadership through proprietary glass bead formulations that anchor premium pricing. Geveko Markings specializes in cold-climate thermoplastic systems that extend operational seasons across Nordic geographies.
Traffic road marking coatings are polymer-based surface treatments applied to asphalt or concrete substrates to delineate traffic lanes, pedestrian crossings, and hazard zones, typically formulated with binders such as alkyd resins, thermoplastic hydrocarbons, or epoxy-acrylate hybrids and retroreflective glass beads engineered to return headlight illumination to drivers. These coatings must achieve specified dry film thickness, skid resistance values, and luminance coefficients to satisfy safety mandates for nighttime visibility and wet-weather performance. Thermoplastic formulations command the largest share of material volume due to superior durability and application speed on high-traffic highways, while tape products capture premium margin pools in airport precision-marking applications where installation windows are severely constrained. Spray application technology leads equipment sales among contractors serving urban road networks, though extrusion systems are displacing conventional methods on federal highway contracts requiring uniform thickness profiles.
Federal Highway Administration (FHWA) Manual on Uniform Traffic Control Devices (MUTCD) minimum retroreflectivity standards, EPA VOC emission limits for architectural and industrial maintenance coatings, and state-level Department of Transportation qualification testing protocols collectively determine product eligibility for public infrastructure spending. Compliance with evolving low-VOC mandates is forcing reformulation investments that favor manufacturers with captive resin production capabilities. Stakeholders must monitor pending MUTCD revision cycles and state DOT prequalification changes to anticipate specification shifts that will reorder competitive standing before contract awards.
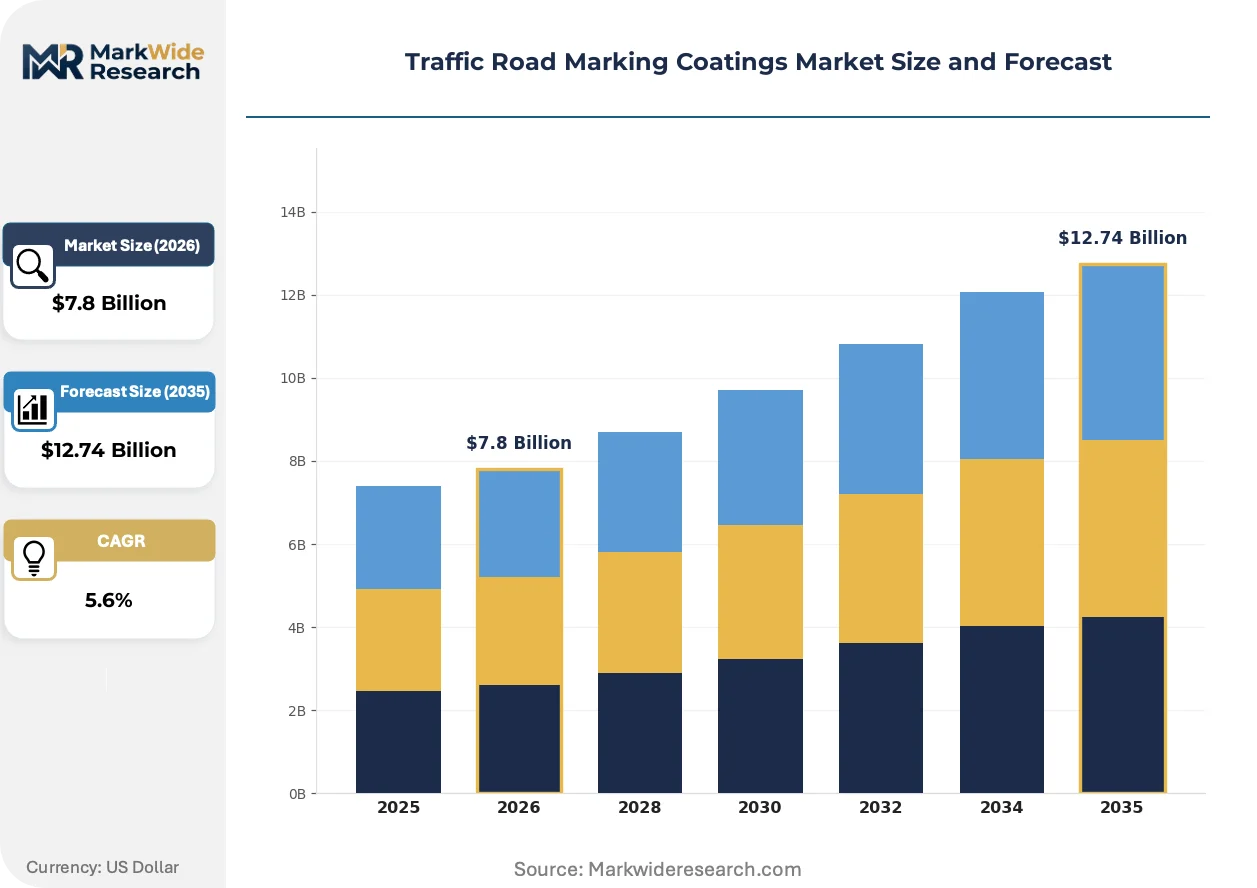
Market Dynamics
Performance-based maintenance contracts are decoupling coating sales from material volume, forcing manufacturers to guarantee retroreflectivity outcomes over multi-year horizons rather than transactional product shipments.
Growth Catalysts
- EU Green Deal low-VOC mandates:European highway agencies are accelerating procurement of waterborne and bio-based formulations, redirecting R&D investment toward compliant resin systems.
- India's National Highway Development Program:Federal road expansion targets are concentrating demand for thermoplastic markings across 13,000 kilometers of new corridor construction annually.
- Retroreflective glass bead technology:Advanced index-of-refraction formulations are extending nighttime visibility performance, justifying premium pricing in airport and tunnel applications.
Market Restraints
- Petroleum-derived binder cost volatility:Thermoplastic hydrocarbon feedstocks track crude oil indices, compressing margins during energy price spikes.
- Titanium dioxide supply concentration:Chinese producers control 45% of global TiO2 capacity, creating input risk for white pigment-dependent formulations.
- Application seasonality in Nordic regions:Sub-zero temperatures constrain thermoplastic installation windows to 6-7 months annually, depressing equipment utilization rates.
Strategic Opportunities
- Smart city integration:Photoluminescent and LED-embedded markings are converging with traffic management systems in Singapore and Dubai, opening IoT-enabled maintenance revenue streams.
- Rural Indian district roads:Underpenetrated secondary networks present volume expansion potential as federal funding shifts from national corridors to state connectivity projects.
- California SB 743 VMT compliance:Complete streets mandates are forcing municipalities to restripe urban corridors with high-visibility bicycle and pedestrian markings.
Industry Challenges
- Retroreflectivity certification timelines:State DOT prequalification testing protocols require 18-24 month validation cycles, delaying new product commercialization.
- Skilled applicator shortages:Extrusion equipment operation demands specialized training that contractor workforces lack, constraining quality consistency on federal highway contracts.
- Legacy alkyd inventory stranding:Reformulation investments for EPA VOC compliance are rendering existing solvent-based product stocks obsolete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Road Marking Coatings Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Paint, Tape, Preformed Markings Application: Highways, Parking Lots, Airports, Urban Roads Technology: Spray Application, Extrusion, Hand Application, Machine Application End User: Government, Contractors, Airport Authorities, Municipalities |
| Companies Covered | Dow Inc., Geveko Markings, The Sherwin-Williams Company, Nippon Paint Holdings Co., Ltd., Berger Paints, 3M Company, Asian Paints PPG Pvt. Ltd., Swarco, PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Road Marking Coatings Market Emerging Trajectories
Material science breakthroughs and procurement model reinvention are compressing product lifecycles and redefining value capture in road marking systems.
Waterborne epoxy-acrylate hybrid formulations are electrifying specification channels by combining low-VOC compliance with durability metrics approaching solvent-borne standards. German KBA certification requirements are accelerating adoption among European highway maintenance contractors. This chemistry is compressing the performance gap between regulatory-compliant and premium-performance tiers.
REACH Annex XVII restrictions on chromium VI pigments are forcing reformulation of yellow and orange traffic markings across EU member states. Pigment suppliers are commercializing organic alternatives with comparable weathering resistance at 15-20% cost premiums. Nordic marking contractors report the tightest compliance timelines, with Denmark and Sweden enforcing 2026 phase-out deadlines.
Asset management software integration is reshaping how state DOTs contract for marking services. Texas and Florida transportation departments now bundle material supply with 3-5 year performance warranties, displacing transactional bidding. Municipal procurement teams lack technical capacity to evaluate outcome-based contracts, creating advisory service opportunities for specialized engineering firms.
Traffic Road Marking Coatings Market Segmentation
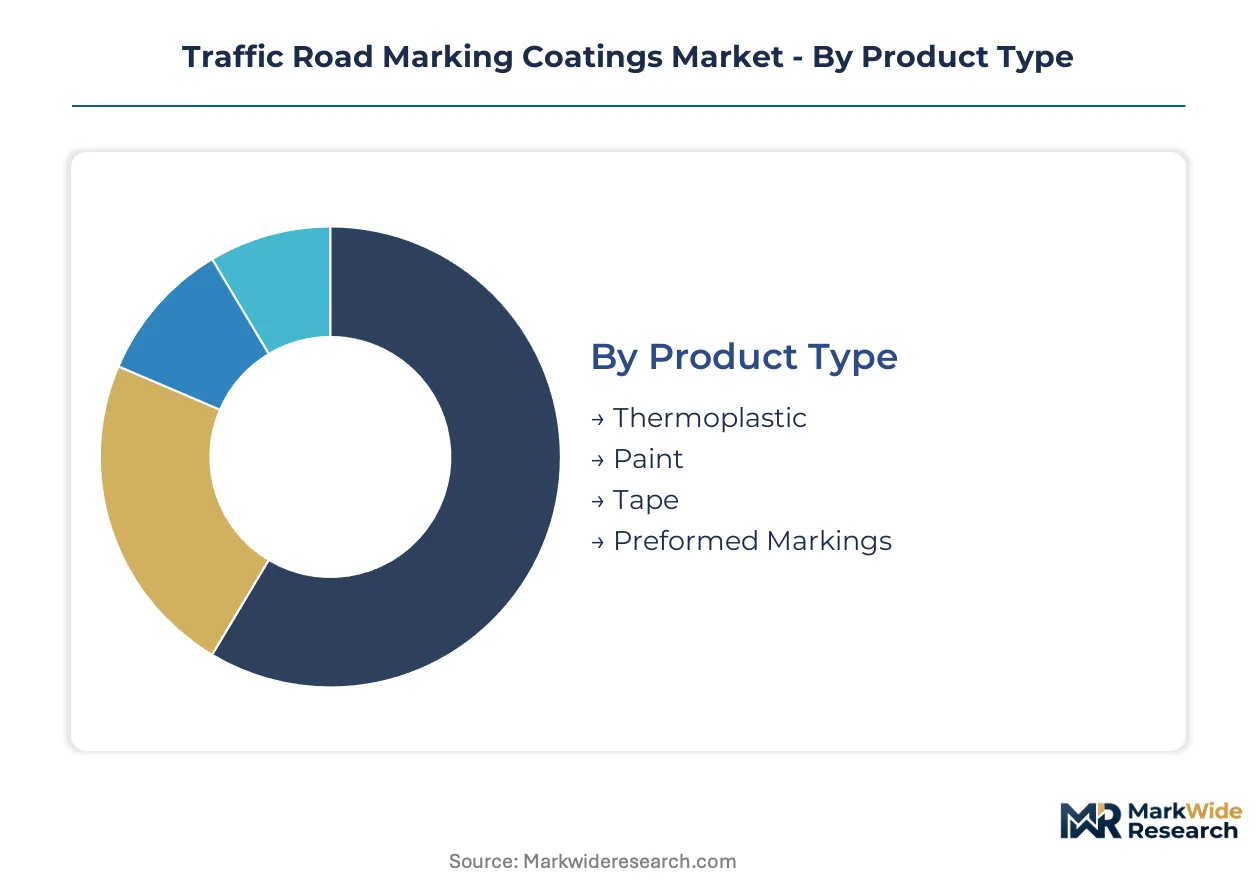
Traffic road marking coatings segment across material chemistry, installation method, and procurement channel. Specification requirements diverge sharply between federal highway contracts and municipal maintenance programs, creating distinct competitive arenas within each category.
Product Type:
Thermoplastic formulations dominate procurement specifications for high-traffic corridors due to durability metrics.
- Thermoplastic:Hydrocarbon and alkyd resin-based systems applied at elevated temperatures achieve superior wear resistance on interstate highways. India's National Highway Development Program concentrates annual procurement of these formulations across thousands of kilometers of new corridor construction.
- Paint:Waterborne and solvent-borne alkyd or epoxy-acrylate coatings serve lower-traffic urban networks and maintenance restriping. EPA VOC emission limits and EU Green Deal mandates are accelerating reformulation toward compliant resin systems.
- Tape:Preformed adhesive-backed markings enable rapid installation in airport precision zones where operational windows are severely constrained.
- Preformed Markings:Factory-manufactured symbols and legends deliver consistent geometry for regulatory compliance in pedestrian crossing applications.
Thermoplastic leads on scale; tape leads on momentum through airport specification capture.
Application:
End-use environments dictate performance thresholds for retroreflectivity, skid resistance, and installation speed.
- Highways:Federal and state DOT contracts demand thermoplastic extrusion with guaranteed retroreflectivity over multi-year performance windows. FHWA MUTCD minimum standards determine product eligibility for infrastructure spending.
- Urban Roads:Municipal restriping programs favor spray-applied paint for cost efficiency on secondary arterials. California SB 743 complete streets mandates are expanding bicycle and pedestrian marking volumes.
- Airports:FAA precision-marking specifications require tape systems with rapid cure times to minimize runway closure duration.
- Parking Lots:Commercial property managers prioritize initial cost over durability, sustaining demand for lower-specification paint formulations.
Highways anchor procurement value; urban roads are climbing the fastest as complete streets mandates proliferate.
Technology:
Equipment selection determines application quality, labor requirements, and seasonal throughput capacity.
- Spray Application:Airless and air-assisted systems dominate municipal contractor fleets for paint-based markings on urban networks.
- Extrusion:Automated thickness control satisfies federal highway contracts requiring uniform profile specifications. Skilled operator shortages constrain quality consistency on large-scale projects.
- Hand Application:Manual placement of preformed tape and symbols serves specialized airport and intersection configurations.
- Machine Application:Self-propelled thermoplastic equipment maximizes lane-mile output during constrained installation seasons in Nordic geographies.
Spray systems hold installed base dominance; extrusion gains share fastest through federal specification tightening.
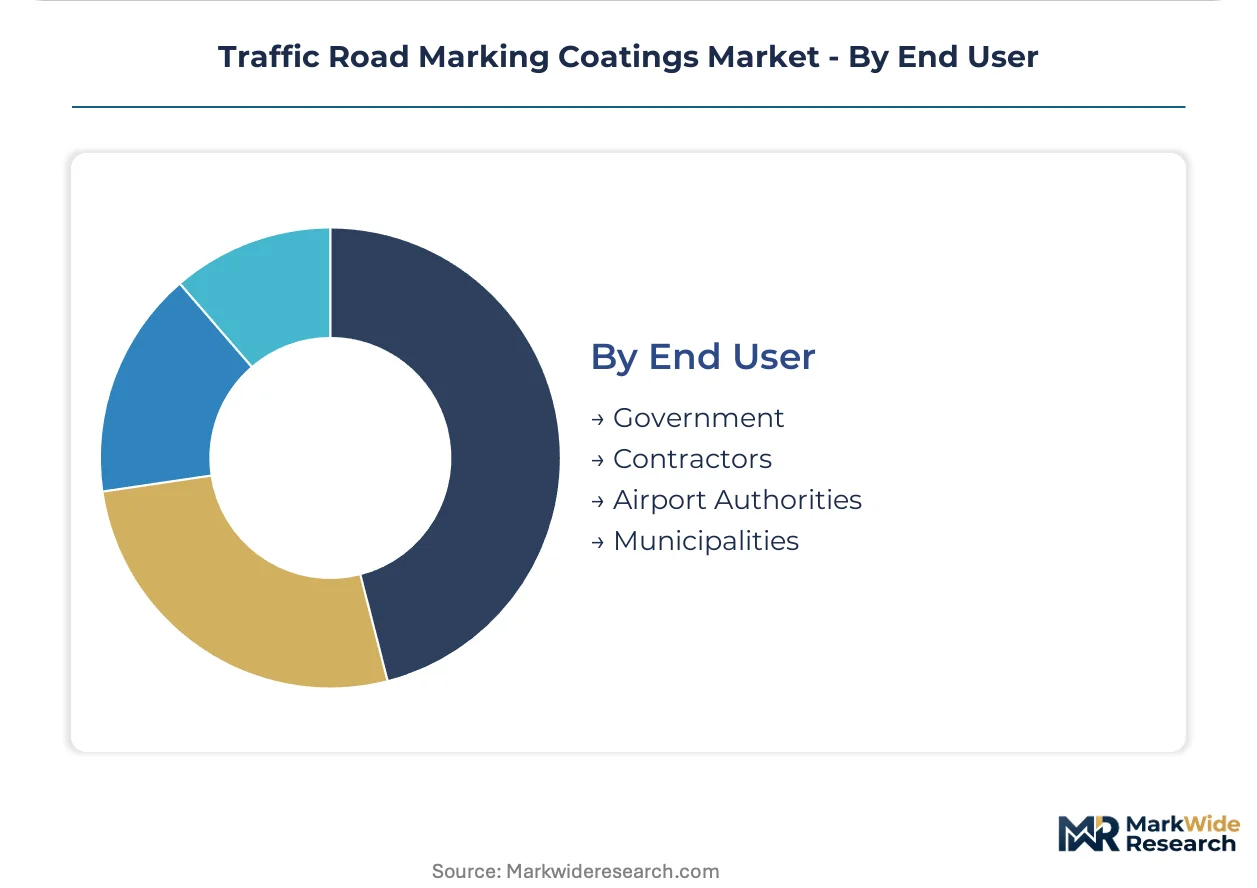
End User:
Procurement authority concentration shapes pricing power and contract structure evolution.
- Government:Federal and state transportation departments bundle material supply with performance warranties, displacing transactional bidding. Texas and Florida DOTs now contract 3-5 year retroreflectivity guarantees.
- Contractors:Private applicators serving municipal markets lack technical capacity to evaluate outcome-based contracts, creating advisory service openings for engineering specialists.
- Airport Authorities:FAA-regulated facilities demand rapid-cure systems that minimize operational disruption, justifying premium pricing for certified products.
- Municipalities:City maintenance departments operate on annual budget cycles that favor lowest-first-cost procurement over lifecycle value optimization.
Government procurement commands contract value; contractors represent the steepest expansion trajectory as performance-based models spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Highway Development Program is concentrating procurement volumes faster than Germany's KBA-certified maintenance contractors can expand capacity. Federal road agencies in both markets are rewriting specification protocols. This divergence is fragmenting supplier strategies across high-growth and replacement-demand corridors.
United States
State DOTs in Texas and Florida now bundle thermoplastic supply with 3-5 year retroreflectivity performance warranties. FHWA MUTCD minimum standards determine product eligibility for federal infrastructure spending. California's SB 743 complete streets mandates are expanding high-visibility bicycle and pedestrian marking volumes across Los Angeles and San Francisco Bay Area corridors.
Germany
KBA certification requirements are accelerating adoption of waterborne epoxy-acrylate formulations among highway maintenance contractors. REACH Annex XVII restrictions on chromium VI pigments are forcing reformulation of yellow and orange markings with 2026 phase-out deadlines. Industrial coating clusters in North Rhine-Westphalia are pivoting resin production toward low-VOC compliant systems.
India
The National Highway Development Program is concentrating annual demand for thermoplastic markings across 13,000 kilometers of new corridor construction. BIS qualification protocols and state-level prequalification testing are extending validation timelines for foreign suppliers. Mumbai-Pune Expressway and Delhi-Mumbai Industrial Corridor projects are anchoring procurement volume.
China
MIIT standards and provincial transportation bureaus are tightening retroreflectivity specifications on national expressway networks. Dual carbon goals are redirecting municipal procurement toward waterborne formulations in Beijing-Tianjin-Hebei and Yangtze River Delta clusters. Titanium dioxide supply concentration among domestic producers is creating input cost volatility for white pigment-dependent formulations.
Sweden
Sub-zero temperatures constrain thermoplastic installation windows to 6-7 months annually, depressing equipment utilization rates. REACH Annex XVII chromium VI phase-out deadlines are tightest in Nordic markets, with 2026 enforcement. Stockholm and Gothenburg metropolitan road authorities are piloting photoluminescent markings for smart city integration.
Traffic Road Marking Coatings Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation technology holders commanding premium positions in federal highway specifications while regional applicators capture municipal maintenance volumes. The vendor base organizes around three strategic archetypes: integrated resin-coating manufacturers with captive feedstock control, precision-application technology licensors, and regional distribution specialists with DOT prequalification depth. M&A activity concentrates on acquiring state-level specification approvals, while backward integration into glass bead production is emerging as a margin defense mechanism.
Among North American integrated coating manufacturers, The Sherwin-Williams Company and PPG Industries, Inc. occupy positions defined by municipal specification channel dominance and distribution network density. 3M Company anchors the precision-application technology tier through proprietary retroreflective systems. These three exemplify how specification control and captive technology create defensive positioning against commodity formulation competitors.
| Leading Market Players |
|---|
| Dow Inc. |
| Geveko Markings |
| The Sherwin-Williams Company |
| Nippon Paint Holdings Co., Ltd. |
| Berger Paints |
| 3M Company |
| Asian Paints PPG Pvt. Ltd. |
| Swarco |
| PPG Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Performance-warranty bifurcation between federal highway contracts and municipal maintenance programs drives divergent pricing architectures and sourcing configurations across the traffic road marking coatings market. Premium thermoplastic formulations with guaranteed retroreflectivity outcomes command contract structures that bundle material supply with multi-year service obligations, while commodity paint sales to city maintenance departments transact on spot-market terms with minimal technical support.
Pricing Analysis
Capacity additions in India are reshaping price floors for thermoplastic hydrocarbon formulations as domestic resin production scales to serve National Highway Development Program procurement volumes. Three-tier pricing structure across certified-premium, state-DOT-qualified, and unqualified-economy levels segments buyer segments by risk tolerance and specification stringency. Cost compression in municipal paint tiers intensifies because EPA VOC compliance investments cannot be passed through to budget-constrained city maintenance departments. Airport authorities exhibit lowest price sensitivity due to operational disruption costs, while parking lot managers prioritize first-cost minimization over lifecycle value.
Supply Chain Analysis
Direct-to-state-DOT channels handle hyperscale federal highway demand, bypassing distributor markups for qualified manufacturers with captive specification approvals. Geographic supply concentration centers on China for titanium dioxide pigment, Germany for epoxy-acrylate resin intermediates, and India for thermoplastic hydrocarbon binders. Raw material dependencies include petroleum-derived hydrocarbons, glass bead retroreflective media, and chromium VI pigment alternatives facing REACH phase-out deadlines. Single-source vulnerability in TiO2 feedstock creates margin volatility for white marking formulations. Distribution runs through municipal contractor networks for urban restriping volumes and specialized airport applicators for precision-marking segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EU Green Deal low-VOC mandates and India's infrastructure volume expansion creates geographic-arbitrage opportunities for formulation specialists with dual-qualification capabilities. Cost differentials in resin production between European environmental compliance investments and Indian scale economies reward flexible manufacturing footprints.
For Market Incumbents: Deepen backward integration into glass bead production to defend margin position against commodity formulation competitors entering through state-DOT prequalification pathways. Secure captive supply of retroreflective media to offset titanium dioxide cost volatility. Invest in waterborne epoxy-acrylate R&D to maintain specification control as REACH Annex XVII pigment restrictions accelerate reformulation cycles.
For New Entrants and Emerging Players: California SB 743 complete streets mandates open a window for bicycle and pedestrian marking specialists with rapid-cure application capabilities. Target underpenetrated rural Indian district roads where federal funding shifts from national corridors to state connectivity projects. Pursue advisory-service positioning to municipal procurement teams lacking technical capacity to evaluate outcome-based contract structures.
For Investors and Strategic Acquirers: Consolidation pressure builds where state-level specification approvals concentrate competitive advantage among limited qualified supplier pools. Five-to-ten-year viability favors manufacturers with captive resin production and distribution network density. Acquisition target archetype: regional specialists with DOT prequalification depth in high-growth corridors. Signal to watch: pending FHWA MUTCD revision cycles that will reorder competitive standing before major contract awards.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Bead Production | Captive retroreflective media supply insulates margins from commodity price spikes in imported inputs. |
| Waterborne Formulation Certification Investment | KBA and EPA compliance unlocks specification channels in Germany and California DOT procurement. |
| Performance-Warranty Contract Structuring | Texas and Florida DOT bundled service models displace transactional bidding with multi-year revenue visibility. |
| Rural Indian Distribution Network Expansion | District road connectivity programs concentrate volume in underpenetrated secondary networks. |
| Photoluminescent Smart City Pilot Participation | Stockholm and Dubai IoT-enabled marking trials open advisory and maintenance revenue streams. |
Methodological Framework
Direct dialogue with state DOT procurement officers, thermoplastic applicator contractors, resin plant managers, and airport maintenance directors grounded qualitative findings in operational reality across the value chain. Secondary validation drew from FHWA MUTCD documentation, EPA VOC emission filings, REACH Annex XVII regulatory texts, and state-level transportation budget appropriations. Bottom-up and top-down triangulation cross-checked contractor fleet capacity estimates against federal highway obligation data.
Bottom-up modeling segmented volume and value projections by material chemistry, application environment, and procurement channel across the analysis window. Segmentation dimensions included thermoplastic versus paint versus tape formulations, federal highway versus urban road versus airport end-uses, and government direct procurement versus contractor-mediated distribution. CAGRs were derived from corridor construction pipeline data and maintenance cycle frequency assumptions. Industry-specific inputs incorporated BIS qualification timelines, KBA certification adoption curves, and petroleum feedstock price elasticity.
Revisions become necessary when REACH enforcement timelines accelerate, MUTCD standards tighten retroreflectivity thresholds, or India's National Highway Development Program procurement schedules shift. Forecasts reflect documented assumptions regarding state DOT prequalification approval rates and skilled applicator workforce expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Vitrified Tiles Market