
 Japan Oriented Strand Board Market | 2026-2036
Japan Oriented Strand Board Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Oriented Strand Board Market Insights
The gap between premium structural grades and commodity OSB is realigning procurement patterns across Japan. West Fraser Timber leverages its coastal British Columbia timber access to supply high-performance panels for seismic-rated buildings. LP Building Products anchors its position through proprietary strand alignment technology that meets JIS structural standards. Kronospan competes on scale, operating multiple production lines optimized for Japan's exacting moisture-resistant specifications.
Oriented Strand Board is an engineered wood panel manufactured from cross-oriented layers of wax-coated wood strands bonded under heat and pressure with phenolic or isocyanate resins, typically achieving bending strengths of 25-50 MPa depending on grade and density. Its primary purpose is to replace plywood and solid wood in load-bearing wall sheathing, roof decking, and subfloor systems where dimensional stability and cost efficiency matter. Structural OSB commands the dominant volume position due to Japan's stringent earthquake-resistant building codes, while moisture-resistant grades represent the fastest-expanding margin pool as humid climate zones drive specification upgrades. The 18 mm thickness segment occupies the premium tier in flooring installation, whereas 9 mm and 12 mm variants sustain higher turnover in residential wall applications.
METI enforces building energy efficiency standards that elevate thermal performance requirements for structural envelope materials, directly shaping OSB insulation-grade demand. JIS standards for wood-based structural panels govern bond durability and formaldehyde emission limits, creating compliance barriers for non-certified imports. The country's national forestry regulator promotes domestic timber utilization through certified sustainable sourcing frameworks. Stakeholders must monitor evolving seismic retrofit mandates and cross-laminated timber integration trends that could redirect structural panel specification decisions.
Market Dynamics
Seismic retrofit mandates and cross-laminated timber integration are redirecting structural panel procurement across Japan's earthquake-resistant construction sector. METI's tightening energy efficiency standards are compressing specification windows for thermal performance, forcing material substitution decisions at the design phase.
Growth Catalysts
- Earthquake-resistant building codes:Japan's stringent seismic standards mandate structural OSB for shear wall applications in residential construction, creating baseline demand for certified panels.
- Urban redevelopment in Tokyo:Kanto region infrastructure projects are accelerating procurement of 18 mm flooring-grade OSB for high-density housing stock replacement.
- Moisture-resistant grade innovation:Phenolic resin formulations with enhanced wax coating are expanding OSB adoption into humid climate zones previously served by plywood.
Market Restraints
- Phenol price volatility:Petrochemical feedstock fluctuations compress margin stability for domestic OSB manufacturers reliant on imported resin binders.
- Import concentration risk:Coastal British Columbia suppliers dominate high-performance structural grades, exposing Japanese buyers to trans-Pacific shipping disruption.
- Cross-laminated timber substitution:Mass timber systems are capturing mid-rise commercial structural envelope share from conventional panelized construction.
Strategic Opportunities
- Osaka-Kobe industrial corridor:Underpenetrated commercial renovation activity in Kansai presents volume expansion potential for moisture-resistant subfloor systems.
- Prefabricated housing integration:Factory-built component manufacturers are specifying OSB for wall sheathing in modular earthquake-resistant units.
- METI carbon-neutral building incentives:Certified sustainable sourcing frameworks create procurement preference for domestically manufactured panels with verified lifecycle credentials.
Industry Challenges
- JIS certification timelines:Bond durability testing protocols extend product qualification cycles, delaying market entry for modified resin formulations.
- Strand alignment technician shortage:Specialized operators for automated pressing line calibration are concentrated among legacy plywood industry workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Oriented Strand Board Market |
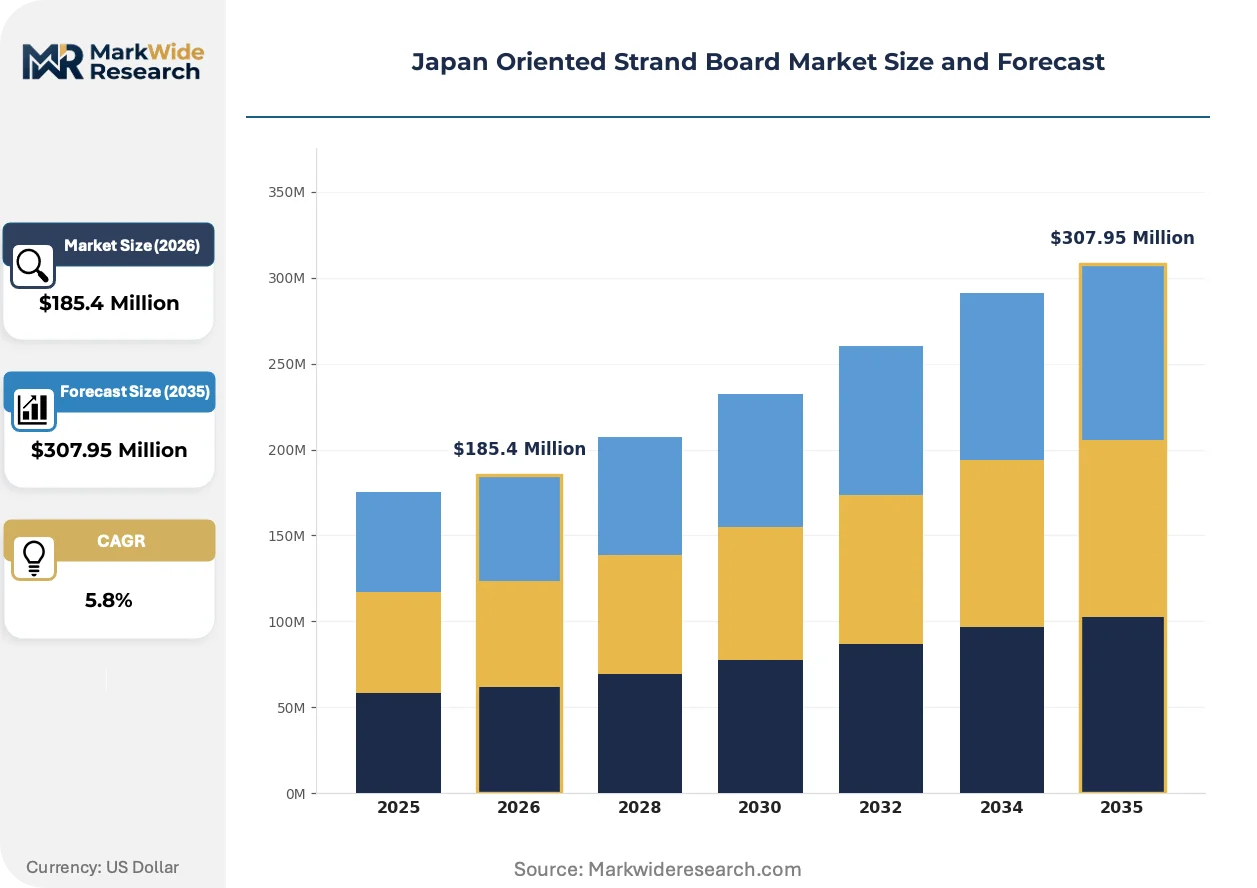
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard OSB, Structural OSB, Edge Coated OSB, Moisture Resistant OSB Application: Residential Construction, Commercial Buildings, Furniture Manufacturing, Flooring Installation End User: Construction Companies, Furniture Manufacturers, DIY Enthusiasts, Retailers Thickness: 6 mm, 9 mm, 12 mm, 18 mm |
| Companies Covered | West Fraser Timber, Weyerhaeuser, LP Building Products, Kronospan, Egger Group, SWISS KRONO Group, Sonae Arauco, Georgia-Pacific, Louisiana-Pacific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Oriented Strand Board Market Trends and Innovations
Strand orientation technology and resin chemistry are converging to compress performance gaps between commodity and premium structural grades. Japanese builders are reassessing procurement criteria as panel manufacturing precision improves.
Automated strand alignment systems with real-time density monitoring are unifying structural consistency across production batches. Seismic-rated housing developers in Tokyo are adopting these panels for shear wall applications at accelerating specification rates. The technology is compressing quality variance between import and domestic supply sources.
METI's building energy efficiency standards are elevating thermal performance requirements for structural envelope materials. JIS formaldehyde emission limits are tightening compliance windows for phenolic-bonded panels. Moisture-resistant grades face the steepest reformulation pressure as humid climate specifications harden.
Builder procurement is consolidating around certified sustainable sourcing frameworks. Prefabricated housing manufacturers are displacing spot-market purchasing with long-term supply agreements tied to verified chain-of-custody documentation. This pattern is most visible in Kanto region urban redevelopment projects where ESG disclosure requirements penetrate municipal contracting.
Japan Oriented Strand Board Market Segmentation
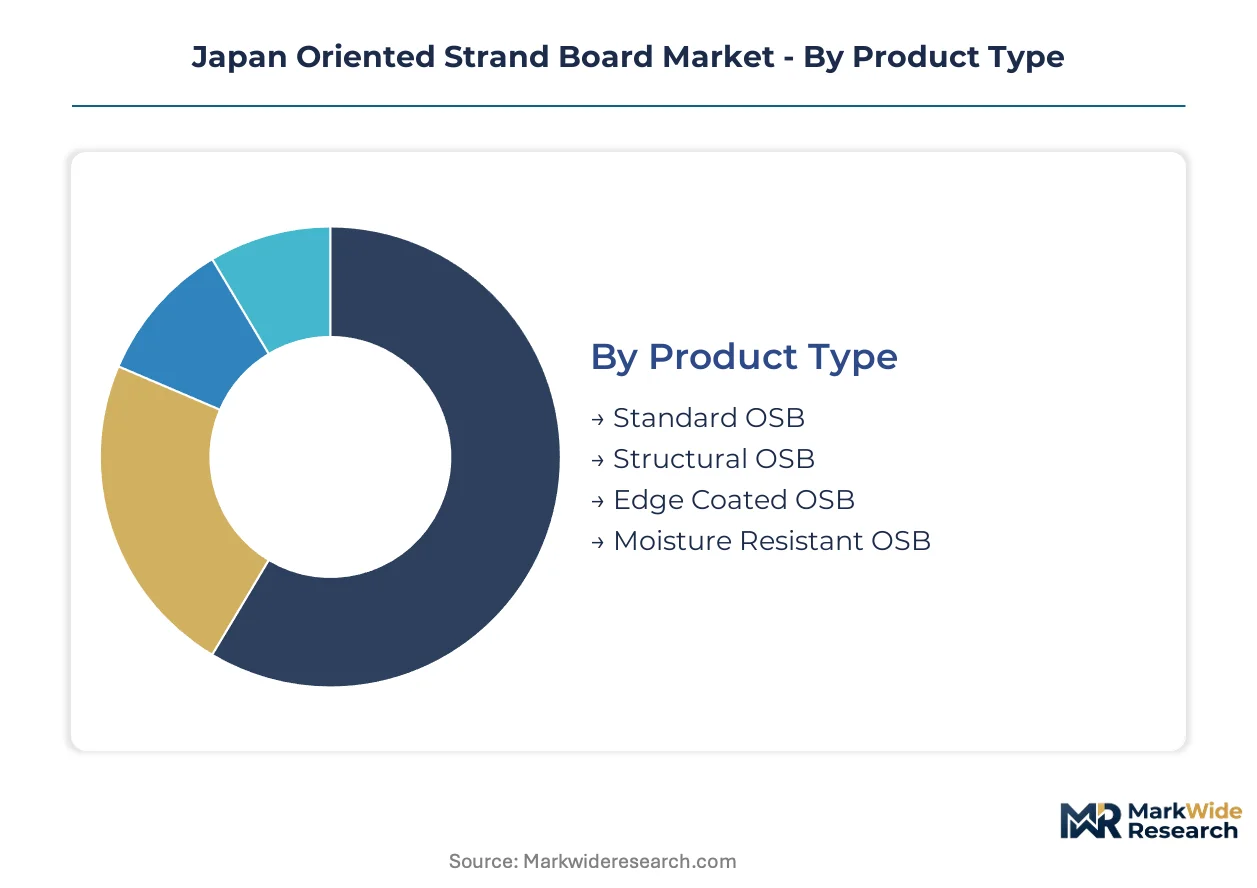
OSB specification in Japan fractures across seismic performance tiers, moisture exposure zones, and fabrication integration depth. Procurement patterns diverge sharply between standalone structural applications and embedded subfloor systems where dimensional stability requirements dominate.
Product Type:
Structural grades operate as standalone shear wall elements, while moisture-resistant variants embed into humid-zone building envelopes requiring continuous protection.
- Structural OSB:Cross-oriented strand layers bonded with phenolic resin achieve 25-50 MPa bending strength under JIS structural standards. Tokyo's earthquake-resistant housing developers specify this grade for shear wall applications where seismic load transfer demands certified bond durability.
- Moisture Resistant OSB:Enhanced wax coating and modified phenolic formulations create dimensional stability in humid climate zones. Osaka-Kobe industrial corridor renovation projects are driving specification upgrades as humid subfloor conditions displace standard-grade alternatives.
- Standard OSB:Commodity-grade panels serve interior non-structural applications where cost efficiency outweighs seismic certification requirements.
- Edge Coated OSB:Perimeter sealing treatments extend moisture protection to cut edges, supporting field-fabricated installations in retrofit applications.
Volume placements concentrate in Structural OSB; the faster expansion belongs to Moisture Resistant OSB.
Application:
Cost tier stratification separates premium seismic-rated systems from commodity interior finishes, with fabrication integration depth determining margin capture.
- Residential Construction:Shear wall sheathing and roof decking consume the dominant volume share as METI building codes mandate earthquake-resistant structural envelopes. Kanto region urban redevelopment accelerates procurement of certified panels for high-density housing replacement.
- Flooring Installation:18 mm thickness specifications dominate subfloor systems where dimensional stability under cyclic loading determines performance. Prefabricated housing manufacturers integrate these panels into modular floor cassettes.
- Commercial Buildings:Mid-rise structural envelopes face displacement pressure from cross-laminated timber systems in seismic-rated commercial construction.
- Furniture Manufacturing:Non-structural panel consumption concentrates in domestic cabinetry and fixture fabrication where surface quality requirements diverge from construction grades.
Residential Construction absorbs the highest shipment volumes; Flooring Installation is climbing the fastest as prefabrication adoption accelerates.
End User:
Customer type fragmentation separates project-scale procurement from fragmented retail demand, with supply chain configuration determining service intensity.
- Construction Companies:Large-scale developers in Tokyo and Osaka metropolitan areas negotiate long-term supply agreements tied to verified chain-of-custody documentation. ESG disclosure requirements in municipal contracting favor certified sustainable sourcing frameworks.
- Furniture Manufacturers:Domestic producers specify surface-grade panels with controlled formaldehyde emissions for interior fixture applications.
- Retailers:Distribution channels serve renovation contractors and DIY segments with spot-market purchasing patterns.
- DIY Enthusiasts:Fragmented demand concentrates in home improvement retail for small-scale renovation projects.
Construction Companies command the largest procurement volumes; Furniture Manufacturers are gaining share fastest as interior fixture specifications tighten.
Thickness:
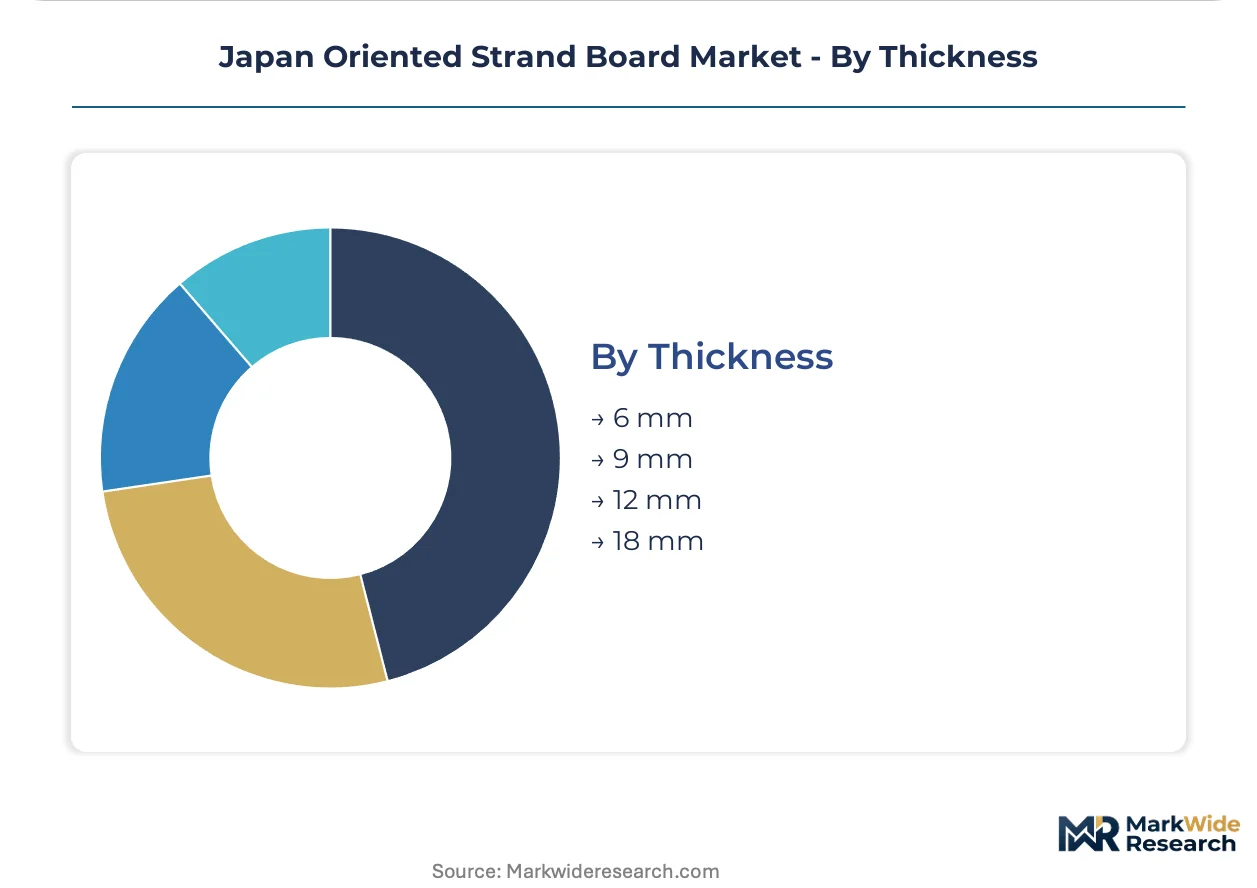
Application maturity separates established wall sheathing formats from emerging premium flooring specifications, with volume scale inversely correlated to margin per panel.
- 18 mm:Premium-tier flooring subfloor systems achieve maximum dimensional stability under concentrated loads. Tokyo high-density housing replacement projects specify this thickness for modular floor cassettes in prefabricated construction.
- 9 mm:Standard wall sheathing thickness dominates residential shear wall applications where seismic load distribution requires consistent panel performance. Kanto region builders specify this grade for conventional stick-frame construction.
- 12 mm:Intermediate thickness serves roof decking and secondary structural applications where load requirements moderate.
- 6 mm:Thin-grade panels concentrate in non-structural interior applications and packaging fabrication where material cost minimization dominates.
9 mm thickness sustains the highest turnover velocity; 18 mm specifications capture the steepest expansion trajectory as flooring-grade demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's urban redevelopment corridor anchors Japan's OSB procurement concentration, with seismic-rated construction driving specification intensity across the Kanto metropolitan cluster.
Kanto Region
Tokyo's high-density housing replacement and commercial retrofit projects consume the dominant volume share of structural OSB. METI's building energy efficiency standards mandate thermal performance upgrades for envelope materials in new construction. Chiba and Saitama prefectures host prefabricated housing manufacturers integrating 18 mm flooring-grade panels into modular floor cassettes.
Kansai Region
Osaka-Kobe industrial corridor renovation activity is accelerating moisture-resistant subfloor system specifications. Humid climate conditions in coastal zones displace standard-grade alternatives with wax-coated phenolic formulations. Kyoto's traditional timber architecture preservation programs create niche demand for certified sustainable sourcing frameworks.
Chubu Region
Nagoya's automotive supplier ecosystem generates secondary OSB demand for packaging and industrial fixture fabrication. Aichi prefecture's manufacturing density supports spot-market purchasing patterns among small-scale construction contractors. Toyota's supply chain sustainability mandates ripple into packaging material procurement specifications.
Kyushu Region
Fukuoka's semiconductor equipment manufacturing cluster drives non-structural panel consumption for cleanroom fixture applications. Kumamoto's earthquake reconstruction programs sustain baseline structural OSB demand for residential rebuilding. Regional forestry cooperatives promote domestic timber utilization through certified chain-of-custody documentation.
Tohoku Region
Sendai's post-2011 reconstruction infrastructure maintains steady procurement of seismic-rated shear wall panels. Miyagi prefecture's coastal housing stock replacement prioritizes moisture-resistant grades for salt-air exposure conditions. Regional building codes incorporate stricter seismic retrofit mandates than national baselines.
Japan Oriented Strand Board Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with JIS structural standards creating tiered entry barriers. Coastal British Columbia suppliers dominate high-performance structural grades through timber access advantages, while European manufacturers compete on moisture-resistant formulation scale. Three archetypes populate the vendor landscape: coastal timber-access specialists, resin-chemistry innovators, and scale-driven continental producers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with domestic qualification timelines favoring incumbents with established JIS certification.
Among North American timber-access specialists, West Fraser Timber and Louisiana-Pacific Corporation occupy positions anchored by coastal British Columbia fiber supply. LP Building Products exemplifies the resin-chemistry innovator archetype through proprietary strand alignment technology. Kronospan represents the scale-driven continental producer model with multiple production lines optimized for exacting moisture-resistant specifications.
| Leading Market Players |
|---|
| West Fraser Timber |
| Weyerhaeuser |
| LP Building Products |
| Kronospan |
| Egger Group |
| SWISS KRONO Group |
| Sonae Arauco |
| Georgia-Pacific |
| Louisiana-Pacific Corporation |
| Others |
Pricing and Supply Chain Analysis
Strand alignment technician concentration in the Kanto region feeds labor-cost differentials into pricing-tier spreads, compressing margins for domestic manufacturers competing against British Columbia imports while elevating premiums for JIS-certified seismic grades.
Pricing Analysis
Seismic performance certification anchors value-based pricing, with JIS structural grade panels commanding substantial premiums over commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by bond durability testing status and formaldehyde emission tier. Cost compression in standard-grade segments is intensifying because phenol feedstock volatility squeezes resin-dependent domestic producers. Project-scale construction companies exhibit lowest price sensitivity due to ESG-mandated sustainable sourcing requirements, while spot-market retailers face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with coastal British Columbia timber suppliers dominating high-performance structural grades. Raw material procurement draws from Canadian softwood fiber, imported phenolic resin binders, and domestic wax coating formulations. Tariff exposure on cross-Pacific shipments creates structural risk for Japanese buyers dependent on Vancouver-port loading. Distribution runs through prefabricated housing manufacturers consolidating long-term supply agreements with verified chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's OSB market functions as a supply-constrained environment where JIS certification bottlenecks prop pricing premiums for qualified domestic and import sources.
For Market Incumbents: Cement market position through backward integration into phenolic resin production, insulating margin structures from petrochemical feedstock volatility. Expand Kanto-region pressing line capacity to capture prefabricated housing procurement consolidation. Cross-laminated timber substitution in mid-rise commercial segments demands defensive positioning in seismic-rated residential shear wall applications. For New Entrants and Emerging Players: The premium-to-economy price-point gap in moisture-resistant grades offers white-space entry through Osaka-Kobe industrial corridor renovation contracts. Target underpenetrated Kansai commercial subfloor specifications where humid climate conditions displace standard alternatives. Pursue JIS qualification partnerships with legacy plywood workforce pools to compress certification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with resin-chemistry innovators given METI carbon-neutral building incentive acceleration. Long-term viability centers on domestic manufacturing footprints with verified lifecycle credentials and established municipal ESG contracting relationships. Monitor cross-laminated timber commercial adoption rates as inflection signal for structural panel displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Investment | Accelerates market entry timelines for modified phenolic formulations in seismic-rated applications. |
| Backward Integration into Resin | Captive phenolic production insulates margin structures from trans-Pacific petrochemical volatility. |
| Prefabricated Housing Partnership | Long-term supply agreements with Chiba and Saitama manufacturers displace spot-market purchasing. |
| Moisture-Resistant Formulation R&D | Enhanced wax coating specifications capture Osaka-Kobe humid-zone renovation volume expansion. |
| Sustainable Sourcing Certification | Verified chain-of-custody documentation meets municipal ESG disclosure requirements in Tokyo contracting. |
Research Methodology
Multi-period observation of JIS certification timelines, resin import volumes, and prefabricated housing procurement patterns anchored the trend analysis, supplemented by interviews with plant managers at domestic pressing facilities, procurement leads at Kanto-region construction developers, distribution channel partners in Osaka, technical R&D directors at resin formulation specialists, and municipal contracting officers. Secondary validation drew from METI building energy efficiency standard filings, customs trade data on phenolic resin imports, Forestry Agency sustainable sourcing documentation, and SEC disclosures from North American timber-access suppliers. Bottom-up shipment volume estimates triangulated against top-down construction spending allocations.
Input-output matrices modeled demand drivers across product type, application depth, end-user procurement scale, and regional seismic code stringency. CAGRs were derived from segmented growth rate reconciliation against aggregate construction output projections. Forecast inputs incorporated strand alignment automation adoption curves and cross-laminated timber commercial penetration assumptions.
Inputs from municipal procurement databases and prefabricated housing manufacturer disclosures were available through the study window; gaps in real-time resin pricing transparency introduce uncertainty bands around margin compression scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Prefabricated Building System Market