
 Global Solar Shading Systems Market | 2026-2036
Global Solar Shading Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Shading Systems Market Intelligence
A shift in procurement from individual residential projects to large-scale commercial and institutional contracts is rebalancing the customer landscape for solar shading systems. Hunter Douglas Inc. leverages its extensive brand recognition and distribution network to serve both segments effectively. WAREMA Renkhoff SE specializes in sophisticated, automated solutions tailored for large commercial buildings in Europe. Lutron Electronics Co. Inc. competes on the integration of its shading systems with its broader smart building and lighting control platforms.
Solar shading systems are architectural elements designed to control the amount of solar heat gain and visible light entering a building. These systems, which can be external or internal, often incorporate materials with specific solar absorptance and reflectance properties to optimize thermal performance. Their primary purpose is to enhance building energy efficiency and improve occupant comfort. While traditional product types like venetian blinds and awnings form a mature base, the smart automation technology segment is where significant value creation occurs.
Regulatory frameworks are a primary catalyst, with Europe's Green Deal and China's dual carbon goals mandating higher energy performance in buildings. Standards from bodies like the ISO and specific national building codes in the United States directly influence product specifications and material choices. Vendor success will depend on navigating this complex web of regional standards while scaling production of automated and integrated systems.
Market Dynamics
The convergence of stringent energy efficiency regulations and smart building technologies is the central force shaping the solar shading systems market. Mandates like the EU Green Deal are compelling architects to specify advanced, automated systems over traditional manual solutions in new commercial construction.
Growth Catalysts
- Energy Performance Mandates:Regulatory frameworks, including Europe's Green Deal and specific building codes in the United States, require significant reductions in building energy consumption. This directly stimulates demand for high-performance solar shading to manage solar heat gain and reduce HVAC loads.
- Smart Automation Technology:The integration of IoT sensors, predictive algorithms, and automated controls allows systems to respond dynamically to environmental conditions. This enhances energy savings and occupant comfort, driving adoption in premium commercial and institutional buildings.
- Green Building Certifications:The pursuit of certifications like LEED and BREEAM encourages developers to invest in solutions that contribute to sustainability scores. Solar shading systems are a key component in achieving credits related to energy performance and indoor environmental quality.
Market Restraints
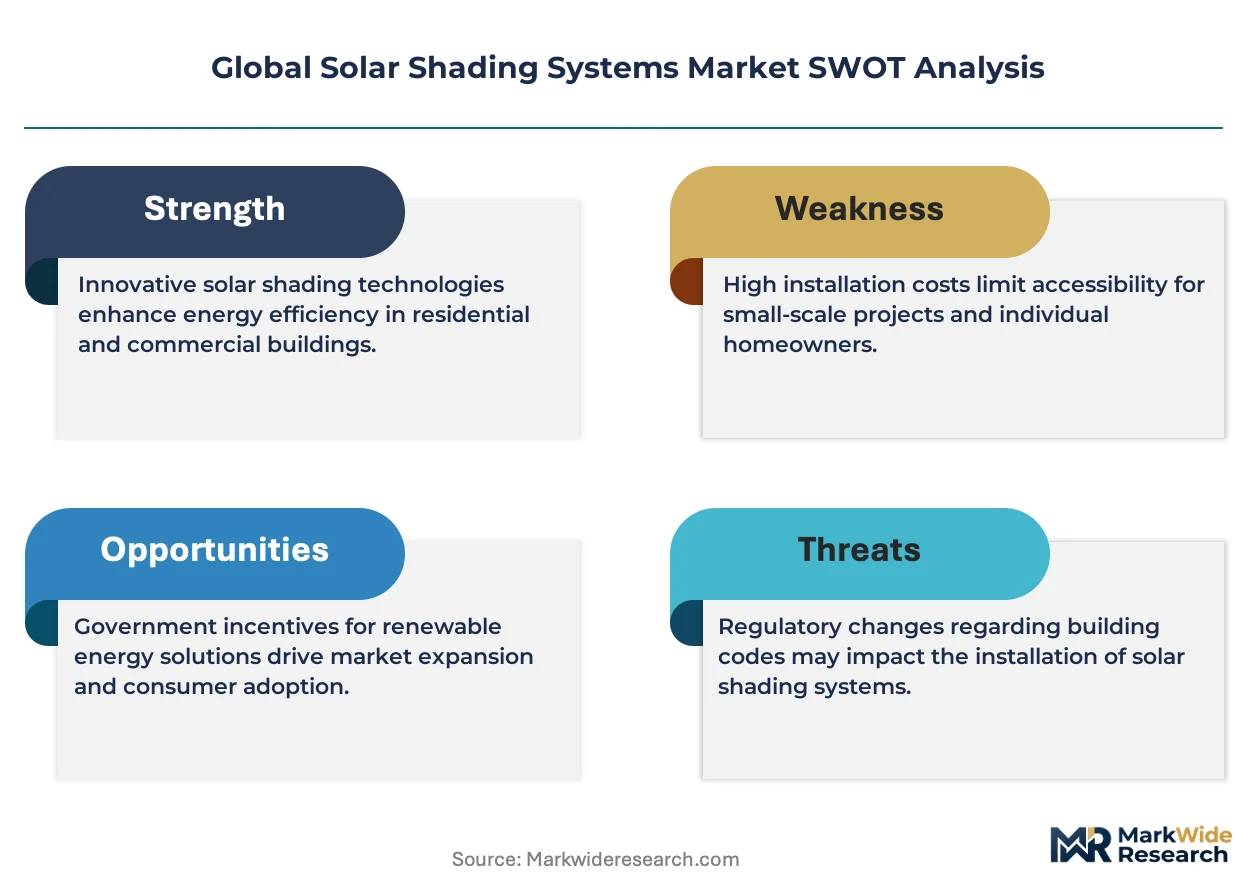
- High Initial Capital Outlay:The upfront cost of sophisticated, automated, and integrated solar shading systems is substantially higher than for conventional blinds or awnings. This can be a significant barrier for projects with tight budgets, particularly in the residential and small commercial sectors.
- Integration Complexity:Ensuring seamless interoperability between shading systems and a building's broader HVAC and lighting control platforms presents a technical hurdle. Lack of standardization across vendor protocols can complicate installation and limit functionality.
- Competition from Glazing Technologies:Advances in dynamic glazing, such as electrochromic and thermochromic glass, offer an alternative method for controlling solar gain without mechanical components. This presents a long-term substitution threat, especially in high-end architectural projects.
Strategic Opportunities
- Retrofit Market for Existing Buildings:A vast stock of older commercial buildings requires energy efficiency upgrades to comply with new regulations. This creates a substantial opportunity for vendors to supply automated shading solutions tailored for retrofitting projects.
- Building-Integrated Photovoltaics (BIPV):The convergence of shading systems with photovoltaic technology offers a pathway to create products that both control solar gain and generate electricity. This creates a new value proposition for building owners focused on net-zero energy goals.
- Expansion in Warm Climate Regions:Markets in the Middle East, Southeast Asia, and Latin America with high solar irradiance and new construction activity represent significant growth potential. Tailoring products for extreme heat and humidity is a key opportunity.
Industry Challenges
- Skilled Labor Shortage:A deficit of technicians with the expertise to install, commission, and maintain complex automated and networked shading systems creates project delays and increases service costs. This challenge is particularly acute for integrated smart building projects.
- Fragmented Regulatory Standards:Vendors must navigate a complex and inconsistent web of national and municipal building codes, energy performance standards, and material safety regulations. This fragmentation increases compliance costs and complicates product development for a global market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Shading Systems Market |
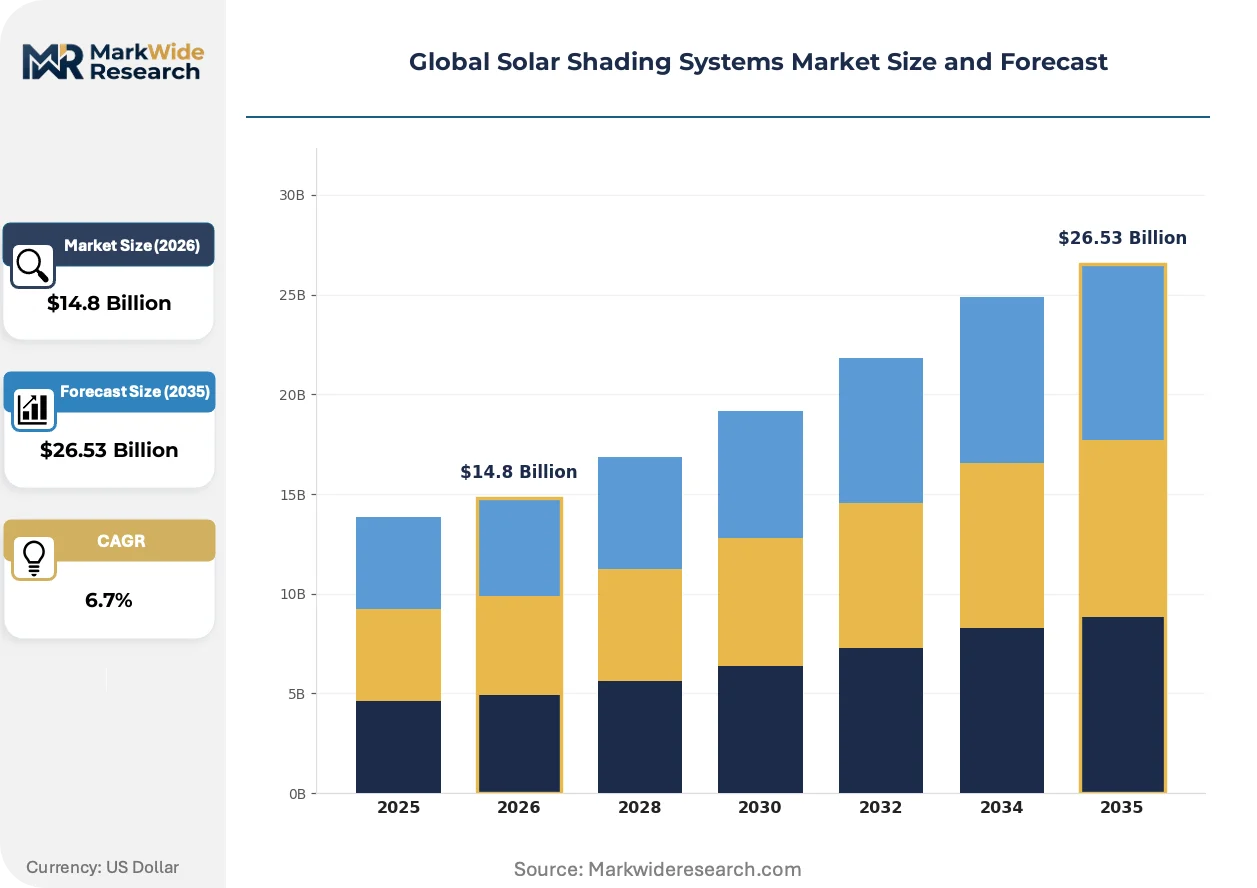
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Venetian Blinds, Roller Blinds, Awnings, Outdoor Shutters, Pleated Shades, Panel Track Blinds Technology: Manual Operation, Motorized Control, Smart Automation, Solar-Powered Actuators, Remote Control Systems, Sensor-Based Adjustment Application: Commercial Buildings, Institutional Facilities, Residential Complexes, Recreational Centers, Hospitality Establishments, Educational Campuses End User: Property Developers, Facility Managers, Architects, Interior Designers, Construction Firms, Energy Consultants |
| Companies Covered | Springs Window Fashions, Skyco Shading Systems Inc., Lutron Electronics Co. Inc., Unicel Architectural Corp., Duco Ventilation & Sun Control, Hunter Douglas Inc., GLASSCON GmbH, Insolroll Corporate, WAREMA Renkhoff SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Shading Systems Market Strategic Shifts & Innovations
The market is being redefined by the fusion of architectural elements with intelligent building automation. This shift elevates solar shading from a passive component to an active, data-driven system for managing a building's energy consumption and interior environment.
Dynamic automation, which uses sensors for solar tracking and occupancy, allows shading to adjust in real time. Commercial facility managers and architects are rapidly adopting these systems in new high-performance buildings to optimize daylighting and thermal comfort. This technology is integrating shading controls directly into centralized Building Management Systems (BMS), creating a unified platform for building performance management.
China's dual carbon goals are driving stricter GB standards for energy performance in new construction. The policy directly compels the use of advanced building envelopes, including automated solar shading solutions to mitigate heat gain. Commercial real estate developments in major economic hubs like Shanghai and Beijing are most affected, accelerating the specification of these systems.
A move toward specifying solar shading as part of a holistic building performance contract is becoming more common. This displaces the traditional procurement process led by interior designers with one driven by energy consultants and mechanical, electrical, and plumbing (MEP) engineers. This change in purchasing behavior is most visible within large-scale institutional projects across North America and Europe.
Global Solar Shading Systems Market Segmentation
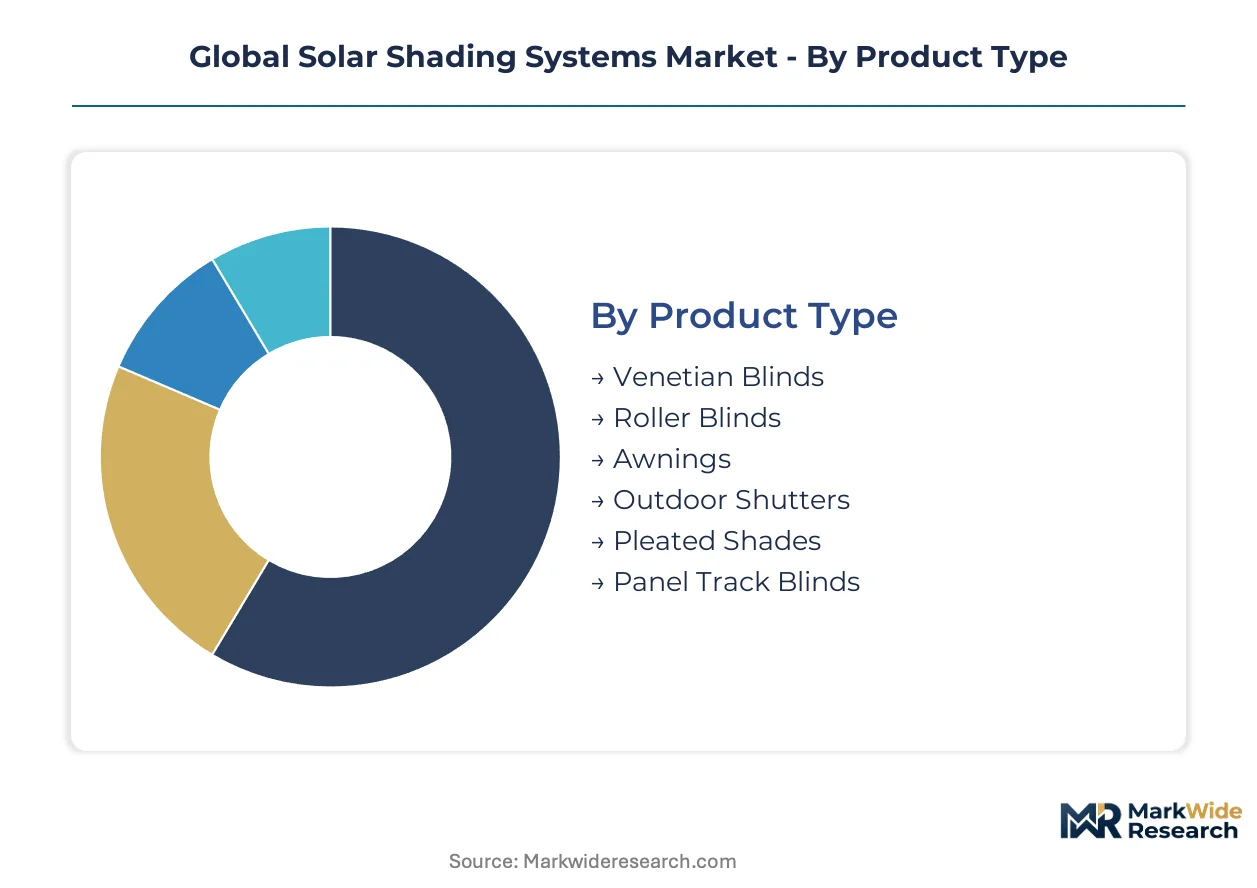
The segmentation of the global solar shading systems market reveals distinct product offerings, technological advancements, diverse applications, and influential end-user groups. Understanding these segments is crucial for manufacturers to tailor solutions that meet specific performance requirements and procurement channels across different building types.
Product Type:
The product type segmentation highlights the spectrum from highly customizable architectural solutions to standardized, mass-produced shading units.
- Venetian Blinds:These systems feature horizontal slats that can be tilted to control light and privacy, often made from aluminum, wood, or PVC. Demand concentrates in both residential and commercial projects seeking versatile light management solutions.
- Roller Blinds:Comprising a single piece of fabric that rolls up or down, these offer a clean aesthetic and effective solar control. Commercial buildings in Europe frequently specify roller blinds for their simplicity and integration into modern facades.
- Awnings:External structures providing shade over windows or outdoor areas, awnings are common in hospitality establishments for occupant comfort.
- Outdoor Shutters:Durable external systems offering security, insulation, and significant solar heat gain reduction, particularly in regions with extreme climates like the Middle East.
- Pleated Shades:Characterized by their accordion-like folds, these provide a softer aesthetic and good insulation properties for residential applications.
- Panel Track Blinds:Wide fabric panels that slide along a track, ideal for large windows and patio doors in contemporary commercial spaces.
Leading the category by volume: Roller Blinds. Representing the fastest-growing trajectory: Outdoor Shutters.
Technology:
Technology segmentation illustrates the evolution from basic manual operation to sophisticated, integrated smart systems.
- Smart Automation:These systems integrate IoT sensors, predictive algorithms, and central building management systems for dynamic, real-time adjustments. High-performance commercial buildings and institutional facilities in Germany increasingly adopt smart automation for optimal energy efficiency.
- Motorized Control:Operated via remote controls or wall switches, motorized systems offer convenience and precise positioning without manual effort. Commercial real estate developments in China commonly incorporate motorized shading for enhanced occupant experience.
- Manual Operation:Traditional, hand-operated shading solutions remain prevalent in budget-sensitive residential projects and smaller commercial spaces.
- Solar-Powered Actuators:Utilizing integrated photovoltaic cells, these systems power the motor directly, reducing wiring complexity and energy consumption. Green building certifications often favor these sustainable solutions.
- Remote Control Systems:Dedicated handheld devices or wall-mounted keypads allow users to operate individual or groups of shading units.
- Sensor-Based Adjustment:Systems that automatically react to environmental factors like sunlight intensity, temperature, and wind speed to maintain indoor comfort.
Manual Operation remains a significant segment, while Smart Automation shows substantial expansion.
Application:
Application segments differentiate between high-volume, cost-sensitive projects and value-driven, performance-centric installations.
- Commercial Buildings:This segment includes offices, retail spaces, and corporate campuses, which are primary adopters of advanced solar shading for energy efficiency and occupant well-being. Regulatory frameworks like the EU Green Deal compel specification in new commercial construction.
- Institutional Facilities:Encompassing educational campuses, healthcare facilities, and government buildings, these sites prioritize durability, energy savings, and controlled environments. LEED certifications often drive solar shading investments in US institutional projects.
- Residential Complexes:Multi-unit dwellings and large housing developments represent a growing market for standardized and integrated shading solutions.
- Recreational Centers:Sports arenas, gyms, and community centers utilize shading to manage glare and heat gain in large, open spaces.
- Hospitality Establishments:Hotels, resorts, and restaurants invest in shading for guest comfort, aesthetic appeal, and energy cost reduction.
- Educational Campuses:Schools and universities install shading to optimize daylighting, reduce HVAC loads, and improve learning environments.
Commercial Buildings drive the highest demand, with Hospitality Establishments demonstrating strong growth.
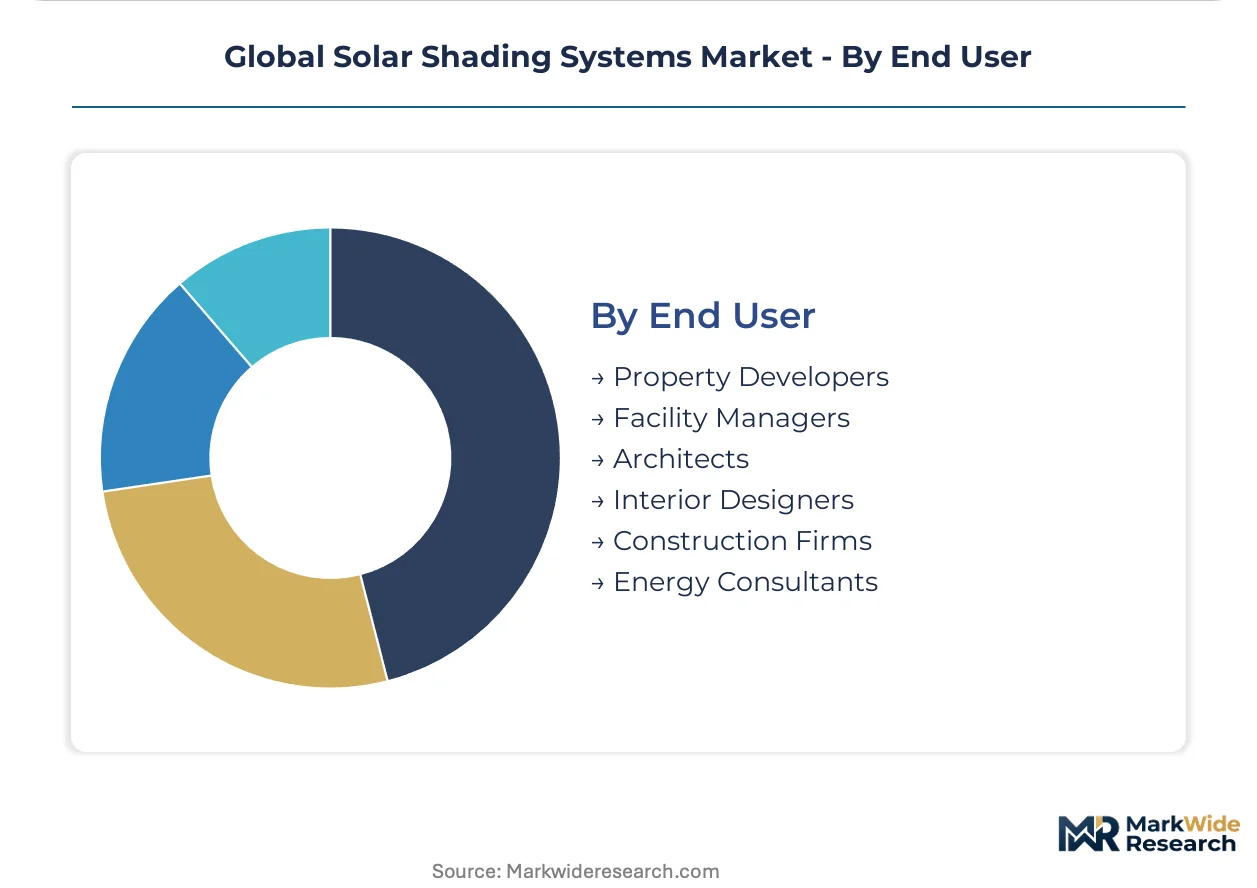
End User:
The end-user segmentation distinguishes between key influencers of product specification and direct procurement decision-makers.
- Architects:These professionals play a critical role in specifying solar shading systems during the design phase, integrating them into the building's aesthetic and performance goals. Architects in North America often consult energy consultants for optimal shading designs.
- Facility Managers:Responsible for the operational efficiency and maintenance of commercial and institutional buildings, they influence system selection based on long-term performance and integration capabilities. Facility managers in major economic hubs like Shanghai seek systems that integrate with Building Management Systems.
- Property Developers:These entities make procurement decisions for large-scale projects, balancing initial cost with long-term value and market appeal.
- Interior Designers:Focusing on aesthetics and occupant comfort, interior designers specify shading solutions that align with the internal design scheme.
- Construction Firms:Involved in the installation and integration of shading systems, these firms often work closely with manufacturers and specifiers.
- Energy Consultants:Specialists who advise on optimizing building energy performance, often recommending specific solar shading technologies to meet efficiency targets.
Architects significantly influence product selection, while Facility Managers oversee long-term operational integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for solar shading systems remains strongest in regions with stringent energy efficiency regulations and a high prevalence of modern commercial construction. These markets prioritize advanced solutions that contribute to building performance and occupant comfort.
Germany
Energy performance mandates from the EU Green Deal significantly influence solar shading adoption in Germany. Building codes like the German Energy Saving Ordinance (EnEV) compel the integration of high-performance building envelopes. Major commercial real estate developments in cities like Frankfurt and Munich frequently specify automated systems.
United States
The pursuit of green building certifications like LEED drives demand for advanced solar shading solutions across the United States. State and local building codes often include energy efficiency requirements that favor these systems. Institutional projects and corporate campuses in California and New York actively invest in dynamic shading technologies.
China
China's dual carbon goals and stricter GB standards for energy performance are accelerating the adoption of sophisticated solar shading. Government initiatives promote energy-efficient construction practices in new developments. Commercial real estate projects in economic hubs like Shanghai and Beijing integrate automated shading to meet these standards.
United Arab Emirates
High solar irradiance and rapid urban development in the United Arab Emirates create substantial demand for effective solar heat gain management. Building regulations in Dubai and Abu Dhabi emphasize thermal performance to mitigate extreme temperatures. Hospitality establishments and luxury residential towers frequently specify high-end external shading.
India
Growing awareness of energy conservation and the expansion of commercial and institutional infrastructure are stimulating solar shading demand in India. National building codes and green building initiatives encourage the use of passive cooling strategies. Major metropolitan areas like Bangalore and Mumbai are seeing increased specification in new office and educational buildings.
Global Solar Shading Systems Market Key Industry Players
European producers anchor one tier of the competitive landscape, focusing on sophisticated, automated solutions, while North American specialists hold a strong position in both residential and commercial segments. The market structure is moderately fragmented, with a mix of large global players and specialized regional manufacturers. Strategic archetypes include technology integrators, broad-portfolio providers, and niche solution specialists. Dominant competitive moves involve strategic partnerships with building management system providers and continuous product innovation in smart automation.
Specialists in integrated smart building platforms include Lutron Electronics Co. Inc., which leverages its broader lighting and control systems. Hunter Douglas Inc. occupies a position as a broad-portfolio provider, serving diverse segments with extensive brand recognition. WAREMA Renkhoff SE exemplifies a European specialist in sophisticated, automated shading solutions tailored for large commercial applications.
| Leading Market Players |
|---|
| Springs Window Fashions |
| Skyco Shading Systems Inc. |
| Lutron Electronics Co. Inc. |
| Unicel Architectural Corp. |
| Duco Ventilation & Sun Control |
| Hunter Douglas Inc. |
| GLASSCON GmbH |
| Insolroll Corporate |
| WAREMA Renkhoff SE |
| Others |
Cost & Logistics Intelligence
Vertical integration into specialized component manufacturing anchors supply positions for key players, influencing both product quality and pricing power in the solar shading systems market. This strategic choice allows manufacturers to control critical inputs and maintain differentiation in advanced solutions.
Pricing Analysis
Volume-driven segments like manual residential blinds offer lower margins, while sophisticated automated systems for commercial buildings command premium pricing. The dominant pricing model is project-based, tailored to specific building requirements and integration complexities. Price differentiation stems from customization level, brand premium, and the extent of smart automation integration. Pricing softness affects standardized products due to robust competition from glazing technologies. Residential buyers and small commercial projects exhibit the highest price sensitivity, prioritizing initial capital outlay over long-term operational savings.
Supply Chain Analysis
Direct-to-specifier channels handle demand for advanced commercial shading, while distributors serve residential and smaller-scale projects. Geographic supply concentration for components like aluminum, specialized fabrics, and electronic controls centers in China, Germany, and the United States. Raw material dependencies include specialized polymers for fabrics and precision-engineered metal alloys for frames. A significant supply chain risk is the skilled labor shortage, impacting installation and commissioning of complex integrated systems. Distribution runs through a mix of direct sales teams for large projects and a network of authorized dealers for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled labor shortages and specialized component availability frame this market as a supply-constrained story, propping pricing for advanced, integrated solar shading solutions.
For Market Incumbents: Extend existing smart building platform integrations to offer comprehensive, unified control solutions. This defensive move counters the threat from specialized technology integrators and enhances customer stickiness. Invest in R&D for next-generation BIPV shading systems, leveraging existing manufacturing capabilities. Strengthen channel control through exclusive partnerships with energy consultants and MEP engineers, especially in Europe's regulated commercial sector.
For New Entrants and Emerging Players: Launch via strategic partnerships with property developers in warm climate regions like the Middle East, focusing on tailored, high-performance external shading. Target the retrofit market for existing buildings with cost-effective, easily deployable automated solutions. Penetrate the multi-unit residential complex segment by offering standardized, integrated shading packages that meet green building certifications. Emphasize value propositions tied to measurable energy savings and occupant comfort.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology providers and regional market leaders with strong distribution networks. The long-term viability favors entities capable of scaling automated system production and navigating fragmented regulatory landscapes. Acquire firms with deep expertise in smart automation software or building-integrated photovoltaic (BIPV) shading. A key signal to watch is the increasing adoption rate of centralized Building Management Systems (BMS) in new commercial construction.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Automation | Scaling production of automated shading systems addresses growing demand from commercial projects. |
| Product Launch: BIPV Shading | Introducing building-integrated photovoltaic shading creates new value streams for net-zero construction. |
| Strategic Partnership with BMS Providers | Integrating shading controls with broader building management platforms enhances system functionality and market reach. |
| Geographic Expansion: Warm Climates | Entering high solar irradiance regions captures demand for extreme heat management solutions. |
| Investment in Skilled Labor Training | Addressing the technician shortage ensures proper installation and maintenance of complex shading systems. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational understanding of the global solar shading systems market. This was complemented by primary interviews with architects, facility managers, property developers, and energy consultants to gather qualitative insights. The comprehensive data collection involved both bottom-up market sizing and top-down validation, ensuring robust triangulation across diverse sources.
Data-stream reconciliation integrated various market parameters into a coherent analytical framework across the projection horizon. The quantitative model segmented the market by product type, technology, application, end-user, and key geographic regions. Compound annual growth rates were derived from historical trends and projected market drivers, with energy efficiency mandates and smart building technology adoption rates serving as critical forecast inputs.
Regulatory shifts, technological advancements, and economic fluctuations are the dominant revision risks for future market projections. Forecasts reflect assumptions regarding these external factors, recognizing their potential to alter market trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
North America Building Automation System Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
AEC Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Smart Garage Door Opener and Controller Market