
 Insulated Wall Panels Market | 2026-2036
Insulated Wall Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Wall Panels Market Analysis
Mineral wool is expanding its share in high-rise commercial envelopes as fire-safety codes tighten across jurisdictions. Kingspan Group leverages captive foam chemistry expertise to sustain margin on sandwich panel lines in European cold-chain projects. Tata Steel anchors its position through integrated coil-to-panel production, while Nucor Corporation competes on domestic steel supply security for North American industrial builds.
Insulated wall panels are factory-engineered envelope assemblies combining rigid facing sheets with bonded thermal cores, typically achieving U-values below 0.25 W/m²K depending on thickness and core chemistry. Their primary purpose is to reduce operational energy loss in climate-controlled buildings while accelerating construction speed through prefabrication. Structural insulated panels occupy the premium tier in residential and light commercial work where speed and air-tightness justify cost. Foam core panels dominate cold storage applications because of superior thermal resistance per inch, though mineral wool faces are gaining share where fire ratings exceed sixty minutes. Composite panels lead industrial retrofit volumes where existing steel frames accept lightweight bolt-on systems without foundation upgrades.
The EU Green Deal and F-Gas Regulation are reshaping polyurethane formulation requirements across European manufacturing bases. The EPA and OSHA frameworks in the United States govern worker exposure limits during panel fabrication and on-site cutting, influencing plant location and automation investment decisions. Stakeholders must monitor evolving embodied-carbon disclosure rules under CSRD and comparable frameworks, as these will increasingly determine specification eligibility in public and institutional procurement cycles.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing formulation timelines for polyurethane core chemistry, forcing European manufacturers to retool blowing-agent systems while cold-storage operators simultaneously tighten thermal envelope specifications. This dual regulatory-demand squeeze is restructuring competitive positioning across factory-engineered envelope assemblies.
Growth Catalysts
- Cold-chain infrastructure expansion:Food safety mandates and pharmaceutical distribution networks are pulling specification upgrades for sub-zero storage envelopes across Germany, France, and the Netherlands.
- REACH-compliant mineral wool substitution:Fire-safety code revisions in high-rise commercial construction are accelerating specification shifts away from combustible foam cores in envelope assemblies above twenty meters.
- Industrial retrofit cycles:Aging manufacturing facilities in the Ruhr Valley and northern Italy are driving bolt-on panel replacement demand as energy audit deadlines approach.
Market Restraints
- Polyol and MDI price volatility:Petrochemical feedstock fluctuations compress margin predictability for polyurethane core manufacturers, particularly affecting mid-tier panel assemblers without captive resin supply.
- Steel coil supply concentration:European flat-rolled steel production clusters in northwest Germany and northern Spain create geographic chokepoints for facing sheet procurement during mill maintenance cycles.
- Fire-rating test protocol fragmentation:Divergent national certification requirements between Germany's DIN standards and France's CSTB processes extend product approval timelines by eight to fourteen months.
Strategic Opportunities
- Poland and Czech Republic industrial zones:Underpenetrated automotive supplier parks and logistics hubs present first-mover positioning for sandwich panel specification in new-build manufacturing envelopes.
- CSRD-aligned embodied-carbon disclosure:Corporate sustainability reporting mandates are creating procurement eligibility filters favoring manufacturers with verified environmental product declarations and cradle-to-gate carbon accounting.
- Prefabrication-to-site logistics integration:Just-in-time panel delivery coordination with crane-equipped construction teams is compressing installation schedules and opening specification channels with design-build contractors.
Industry Challenges
- Polyurethane formulation chemistry expertise:Shortage of technicians trained in low-GWP blowing-agent processing is constraining production line conversion rates at second-tier manufacturing facilities.
- CE marking and fire-reaction testing backlog:Accredited laboratory capacity limitations in southern Europe are extending product certification timelines and delaying commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Wall Panels Market |
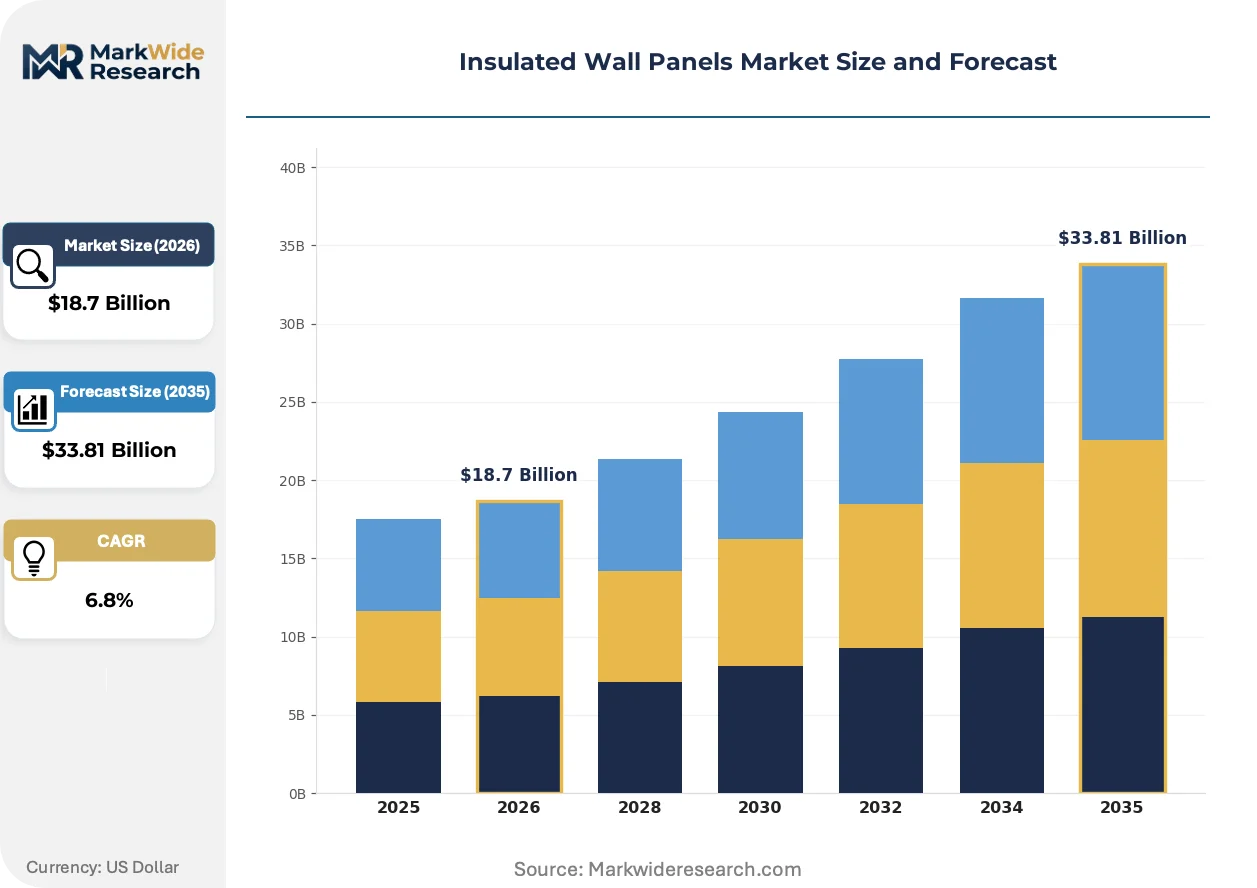
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Insulated Panels, Foam Core Panels, Composite Panels, Sandwich Panels Application: Commercial Construction, Cold Storage Facilities, Residential Buildings, Industrial Applications Material: Polyurethane, Polystyrene, Mineral Wool, EPS Installation Method: Pre-fabricated, On-site Assembly, Modular Construction, Traditional Construction |
| Companies Covered | Tata Steel, Metl-Span, Kingspan Group, Lattonedil, Isopan, Nucor Corporation, Metecno, Assan Panel, ArcelorMittal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Wall Panels Market Emerging Trajectories
Refrigerated logistics operators are compressing thermal bridge tolerances while facade engineers integrate active monitoring systems into envelope assemblies. These parallel developments are reshaping how factory-built panels are specified, fabricated, and warranted across climate-controlled buildings.
Vacuum-insulated panels are overtaking conventional polyurethane foam in ultra-low-temperature pharmaceutical storage applications where thermal resistance per inch determines usable floor area. Cold-chain operators in Belgium and the Netherlands are specifying these systems for minus-eighty-degree cell banks. The technology is compressing achievable envelope U-values by forty percent versus legacy foam cores, enabling smaller mechanical plant footprints in urban distribution centers.
The F-Gas Regulation is mandating phase-down of hydrofluorocarbon blowing agents in polyurethane core production across EU manufacturing bases. Panel producers are reformulating with hydro-olefin or water-blown systems to maintain thermal performance while meeting GWP thresholds. German and Austrian plants are furthest along conversion curves, while southern European facilities face compressed compliance deadlines through 2027.
Design-build contractors are consolidating envelope specification authority previously dispersed among architects and mechanical engineers. Single-source responsibility for thermal performance, air-tightness, and fire safety is displacing fragmented procurement across multi-trade bidding. This concentration is most visible in Dutch and Danish industrial construction, where integrated panel-and-installation packages now capture sixty percent of cold-storage new-build volume.
Insulated Wall Panels Market Segmentation
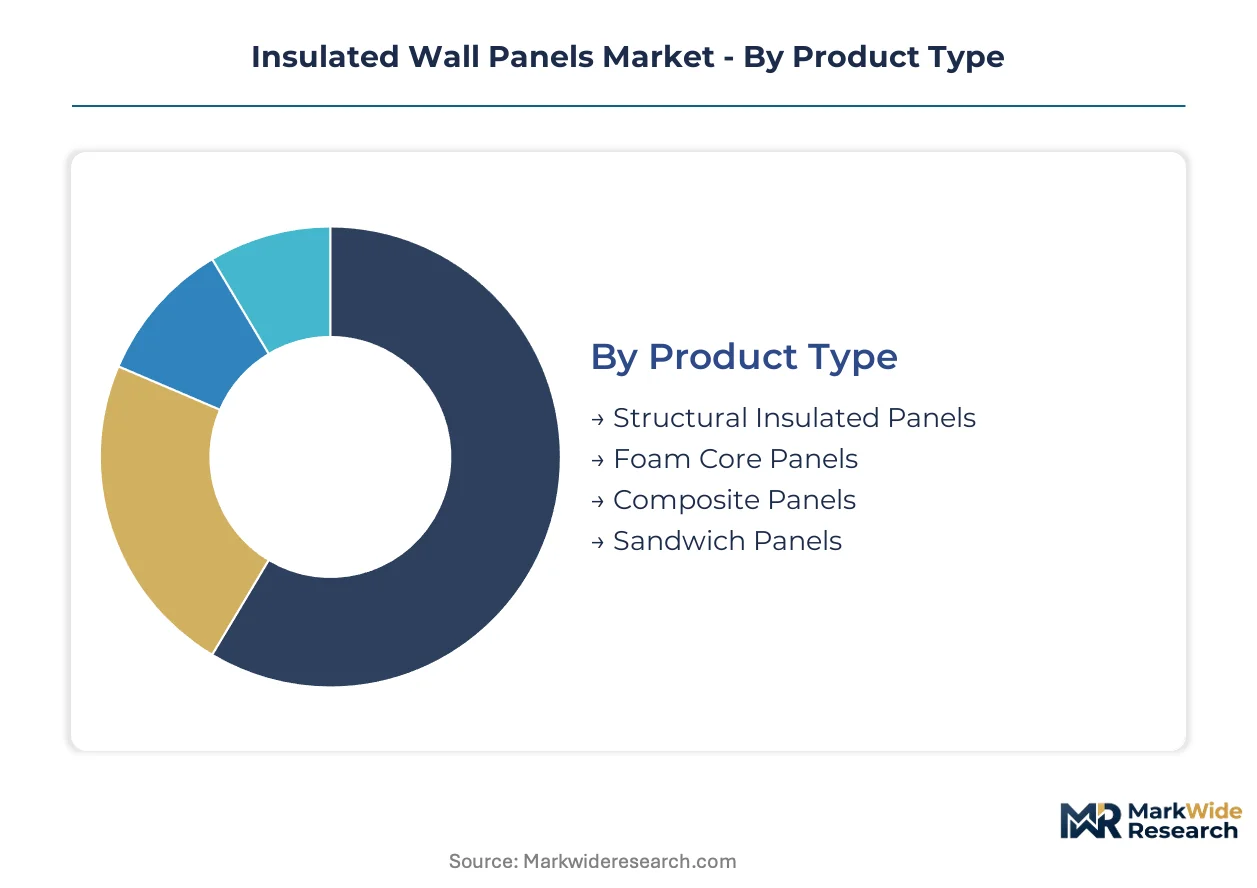
Insulated wall panel buyers sort across four distinct dimensions: structural performance requirements, thermal envelope specifications, core chemistry constraints, and construction logistics. Each segmentation axis reveals divergent specification authority and margin structures across factory-engineered envelope assemblies.
Product Type:
Buyers differentiate primarily by load-bearing requirements versus speed-to-enclosure priorities.
- Structural Insulated Panels:Rigid oriented strand board facings bonded to expanded polystyrene or polyurethane cores create load-bearing wall assemblies. Residential and light commercial projects in Germany and Austria specify these for air-tightness targets below 0.6 air changes per hour under passive house protocols.
- Foam Core Panels:Non-structural metal facings laminated to polyurethane or polyisocyanurate cores dominate cold-storage envelopes where thermal resistance per inch determines usable cube. Operators in Belgium and the Netherlands specify these for minus-thirty-degree distribution centers.
- Composite Panels:Thin-gauge steel or aluminum skins over low-density cores suit industrial retrofit applications where existing frames cannot support additional dead load. Northern Italian manufacturing facilities deploy these for energy audit compliance without foundation reinforcement.
- Sandwich Panels:Symmetrical metal facings with homogenous mineral wool or foam cores provide balanced thermal and acoustic performance. German automotive supplier parks specify these for assembly plant envelopes requiring sixty-minute fire ratings.
Foam core panels lead volumes today; structural insulated panels are gaining share fastest.
Application:
End-use thermal envelopes impose distinct fire-safety, hygiene, and energy-code compliance burdens.
- Commercial Construction:High-rise office and retail envelopes above twenty meters face stringent fire-reaction classifications under Germany's DIN 4102 and France's Euroclass requirements. Mineral wool cores are displacing polyurethane in these specifications.
- Cold Storage Facilities:Sub-zero pharmaceutical and food distribution networks demand envelope U-values below 0.20 W/m²K. Vacuum-insulated panels are penetrating minus-eighty-degree cell banks in Belgian logistics hubs.
- Residential Buildings:Single-family and multi-family construction favors structural insulated panels for speed of enclosure. Dutch design-build contractors specify factory-cut panels to compress weather-tight schedules.
- Industrial Applications:Aging manufacturing envelopes in the Ruhr Valley and northern Italy drive bolt-on panel replacement as energy audit deadlines approach. Lightweight composite systems dominate this retrofit volume.
Cold storage facilities lead volumes today; commercial construction is expanding most quickly.
Material:
Core chemistry selection hinges on thermal performance targets, fire-rating requirements, and regulatory compliance timelines.
- Polyurethane:Closed-cell chemistry delivers superior thermal resistance per inch but faces F-Gas Regulation phase-down mandates across EU manufacturing bases. German and Austrian plants have converted to hydro-olefin blowing agents; southern European facilities face compressed deadlines.
- Polystyrene:Expanded and extruded variants offer cost-positioned thermal cores for residential and light commercial work. REACH-compliant formulations are displacing legacy grades in high-rise specifications.
- Mineral Wool:Non-combustible stone or glass fiber cores achieve fire ratings exceeding ninety minutes without additional intumescent layers. French and German commercial envelopes above twenty meters specify these for Euroclass A1 compliance.
- EPS:Moldable expanded polystyrene suits complex architectural profiles and curved envelope geometries. Italian facade specialists specify these for heritage building retrofits requiring aesthetic continuity.
Polyurethane leads volumes today; mineral wool is climbing the fastest.
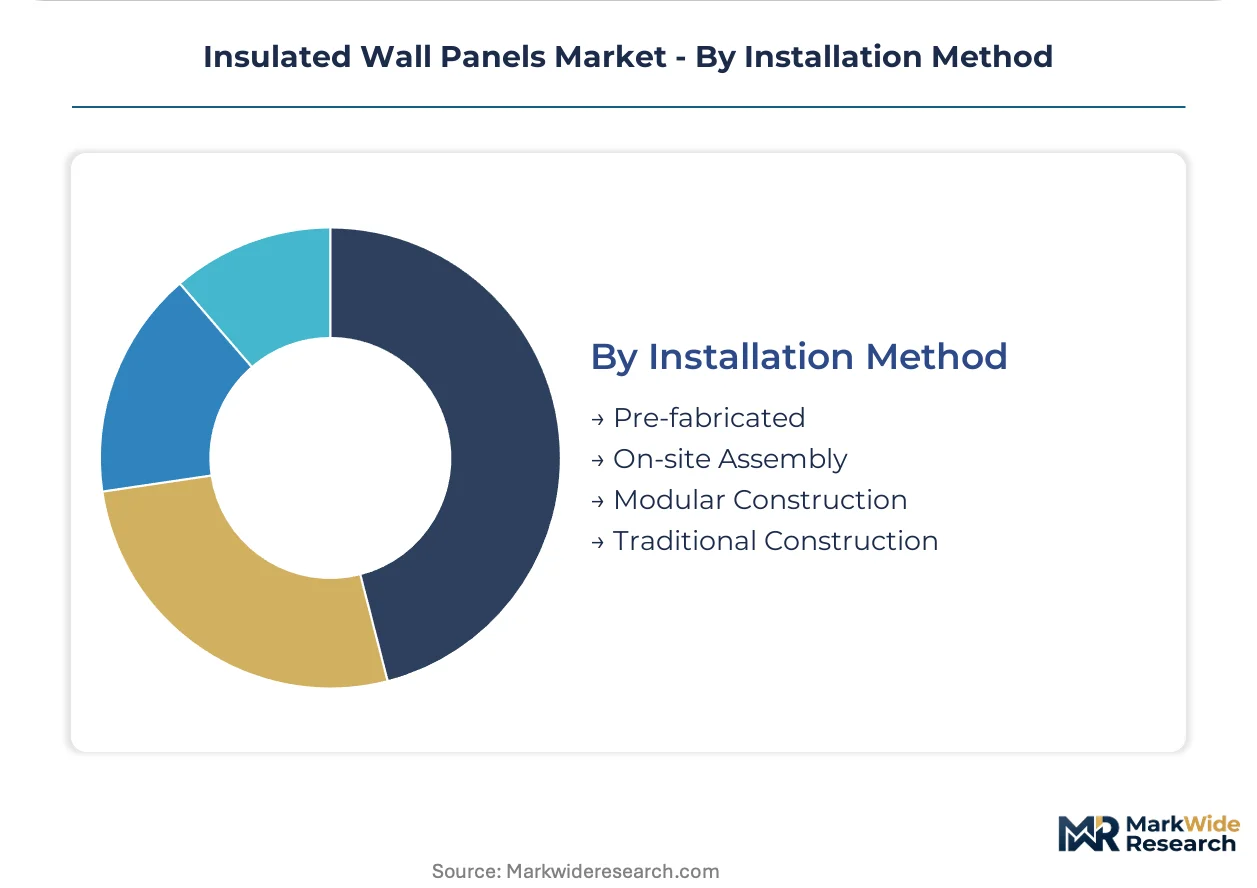
Installation Method:
Construction logistics determine specification channels and margin capture for panel producers.
- Pre-fabricated:Factory-complete wall assemblies with integrated windows, doors, and MEP rough-ins ship to site for crane-assisted placement. Dutch industrial contractors specify these to compress installation schedules by forty percent versus stick-built alternatives.
- On-site Assembly:Panel components arrive flat-packed for field assembly by trained crews. German mid-tier panel assemblers compete on this model where transport geometry limits pre-fabricated unit sizes.
- Modular Construction:Volumetric units incorporating insulated wall panels as primary envelope elements suit repetitive hospitality and healthcare programs. Polish and Czech logistics hubs are adopting these for rapid-deployment cold storage.
- Traditional Construction:Stud-framed walls with site-applied insulation and cladding retain share in bespoke residential and heritage work. Italian Alpine regions specify these where dimensional tolerances preclude panelized systems.
Pre-fabricated installation leads volumes today; modular construction is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr Valley industrial corridor anchors European specification pull for insulated wall panels, with cold-chain operators and automotive suppliers driving envelope upgrade cycles. German building energy codes and F-Gas Regulation compliance deadlines compress formulation timelines across manufacturing bases. Five national markets concentrate distinct demand patterns and regulatory pressures.
Germany
Cold-storage operators in the Ruhr Valley and Bavaria pursue sub-zero envelope specifications for pharmaceutical distribution networks. The F-Gas Regulation mandates hydro-olefin blowing-agent conversion at polyurethane core plants by 2027. Stuttgart automotive supplier parks specify sixty-minute fire-rated sandwich panels for assembly plant retrofits.
France
High-rise commercial construction above twenty meters accelerates mineral wool core substitution under Euroclass A1 fire-reaction requirements. CSTB certification protocols extend product approval timelines for imported panel systems. Lyon logistics hubs deploy vacuum-insulated panels for minus-eighty-degree pharmaceutical cell banks.
Netherlands
Design-build contractors consolidate envelope specification authority for industrial cold-storage new-builds, capturing sixty percent of project volume through integrated panel-and-installation packages. Rotterdam distribution centers compress thermal bridge tolerances for refrigerated logistics operators. Dutch just-in-time delivery coordination with crane-equipped teams compresses installation schedules.
Belgium
Pharmaceutical storage facilities in the Antwerp-Brussels corridor specify ultra-low-temperature envelopes with U-values below 0.20 W/m²K. REACH-compliant blowing-agent formulations dominate procurement eligibility for public health infrastructure. Liège logistics clusters adopt vacuum-insulated technology for space-constrained urban distribution centers.
Poland
Underpenetrated automotive supplier parks and logistics hubs in the Silesian and Greater Poland voivodeships present first-mover positioning for sandwich panel specification. EU Green Deal funding streams accelerate industrial envelope retrofits at aging manufacturing facilities. Warsaw-area cold-chain operators specify prefabricated modular construction for rapid-deployment storage capacity.
Insulated Wall Panels Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers retool blowing-agent chemistry and add coil-to-panel integration lines. The vendor base concentrates among integrated steel producers, captive foam chemistry specialists, and regional fabricators serving national specification channels. Three archetypes define competitive positioning: steel-integrated multinationals with captive resin supply, foam chemistry specialists leveraging formulation expertise, and mid-tier assemblers competing on logistics proximity. M&A activity and geographic expansion into underpenetrated industrial zones represent the dominant competitive vectors.
Among steel-integrated fabricators, Tata Steel and ArcelorMittal exemplify the coil-to-panel production archetype, anchoring positions through facing sheet supply security and mill-direct cost structures. Kingspan Group and Nucor Corporation occupy positions at the chemistry-integrated and domestic-supply ends of the spectrum respectively, representing divergent responses to regulatory compression and logistics-driven specification channels.
| Leading Market Players |
|---|
| Tata Steel |
| Metl-Span |
| Kingspan Group |
| Lattonedil |
| Isopan |
| Nucor Corporation |
| Metecno |
| Assan Panel |
| ArcelorMittal |
| Others |
Supply Flow & Price Mechanics
Platts hot-rolled coil index fluctuations cascade through European insulated wall panel supply chains, compressing margin buffers for mid-tier assemblers while integrated steel producers capture pricing power through mill-direct cost structures. The pass-through lag between coil procurement and panel quotation creates working capital pressure that stratifies competitive tiers.
Pricing Analysis
Input-cost pass-through dominates pricing architecture, with petrochemical feedstock volatility in polyol and MDI markets transmitting directly to polyurethane core panel quotations. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked fire-rated systems from uncertified commodity panels. Cost compression in the economy tier is intensifying because second-tier assemblers lack captive resin supply. Cold-storage operators demonstrate lowest price sensitivity due to thermal performance warranties, while industrial retrofit buyers prioritize landed cost over specification grade.
Supply Chain Analysis
Dual-sourcing requirements for steel facing sheets mandate qualification of mills in Germany, Spain, and Italy to mitigate geographic concentration risk in northwest European flat-rolled production. Raw material dependencies center on MDI, polyols, and mineral wool feedstock from BASF, Covestro, and Rockwool supply bases. Single-source vulnerability in accredited fire-testing laboratory capacity extends certification timelines. Distribution runs through design-build contractor networks in the Netherlands and Germany, displacing traditional multi-trade procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by cold-storage operators compressing thermal bridge tolerances and specifying vacuum-insulated panels for ultra-low-temperature pharmaceutical storage.
For Market Incumbents: Anchor coil-to-panel integration through backward control over facing sheet supply, insulating margin from petrochemical volatility. Prioritize captive blowing-agent chemistry expertise to defend positioning against REACH-compliant mineral wool substitution in high-rise commercial envelopes. Accelerate CE marking pre-qualification to capture share from competitors facing CSTB and DIN protocol fragmentation.
For New Entrants and Emerging Players: Design-build contractors represent the most accessible specification channel for unproven panel producers, particularly in Dutch and Danish industrial construction where single-source envelope responsibility concentrates procurement authority. Target Polish and Czech automotive supplier parks for first-mover positioning in underpenetrated sandwich panel markets. Lead with prefabricated modular construction packages to bypass established distributor relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with foam chemistry specialists possessing verified environmental product declarations under CSRD-aligned procurement filters. Long-term viability hinges on formulation conversion timelines for F-Gas Regulation compliance across southern European manufacturing footprints. Watch laboratory accreditation backlogs as the inflection signal—capacity constraints extending certification timelines will compress valuations for unprepared mid-tier assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Supply | Captive steel production secures facing sheet cost structures against Platts index volatility. |
| Low-GWP Blowing-Agent Conversion | Hydro-olefin formulation investment maintains EU manufacturing eligibility under F-Gas Regulation deadlines. |
| CE Marking Pre-Qualification | Early fire-reaction testing completion opens specification channels before competitor launches. |
| Design-Build Contractor Partnerships | Integrated panel-and-installation packages capture sixty percent of Dutch cold-storage new-build volume. |
| Environmental Product Declaration Verification | CSRD-aligned carbon accounting qualifies manufacturers for public and institutional procurement cycles. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at polyurethane core facilities, procurement leads at cold-storage operators, design-build contractor specification directors, and distribution channel partners with secondary validation through customs data, ECHA REACH registrations, SEC filings of listed panel producers, and Eurostat construction output indices. Bottom-up volume builds across core chemistry types and installation methods triangulated against top-down envelope demand estimates from national building energy code compliance schedules.
Comparable historical periods anchored growth rate derivation across the projection horizon, with segmentation modeling spanning structural performance requirements, thermal envelope specifications, core chemistry constraints, and construction logistics dimensions. CAGRs emerged from fitted trend analysis calibrated to regulatory compliance deadlines and industrial retrofit cycle timing. Forecast inputs incorporated F-Gas Regulation phase-down schedules, REACH amendment timelines, and CSRD disclosure mandate rollouts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, steel mill maintenance cycle disruptions, and fire-testing laboratory capacity constraints. Deviation in EU Green Deal implementation pacing or F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Brick Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market