
 US Exterior Wall Systems Market | 2026-2036
US Exterior Wall Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Exterior Wall Systems Market Insights
Buyer concentration among national homebuilders is realigning procurement strategies across the exterior wall value chain. Owens Corning leverages its insulation-to-cladding integration to capture bundled specifications from top-ten builders. James Hardie Industries anchors the fiber cement segment through dedicated distribution centers in Texas and Florida. CertainTeed competes on color-matched system warranties that reduce contractor callback risk.
Exterior wall systems comprise the non-load-bearing outer envelope of buildings, integrating weather-resistant barriers, insulation layers, and finished cladding surfaces engineered to achieve specified R-values and air infiltration rates. These assemblies control thermal transfer, moisture intrusion, and structural wind loads while enabling aesthetic customization across construction types. Fiber cement and vinyl siding occupy mature volume positions with stable margin pools, while rain screen systems and composite panels represent faster-growing specification categories driven by stringent energy code compliance. Metal panels dominate commercial and institutional applications where large-format installation speed offsets material premiums.
FHA, Fannie Mae, and Freddie Mac green building standards shape residential financing incentives for high-performance wall assemblies, while local jurisdictions adopt IECC stretch codes that exceed baseline requirements. OSHA fall protection mandates and EPA lead-safe renovation rules alter contractor labor deployment and material handling protocols on retrofit projects. Stakeholders must monitor evolving state-level stretch codes and utility rebate programs that increasingly tie incentive eligibility to whole-wall U-factor performance rather than insulation R-value alone.
Market Dynamics
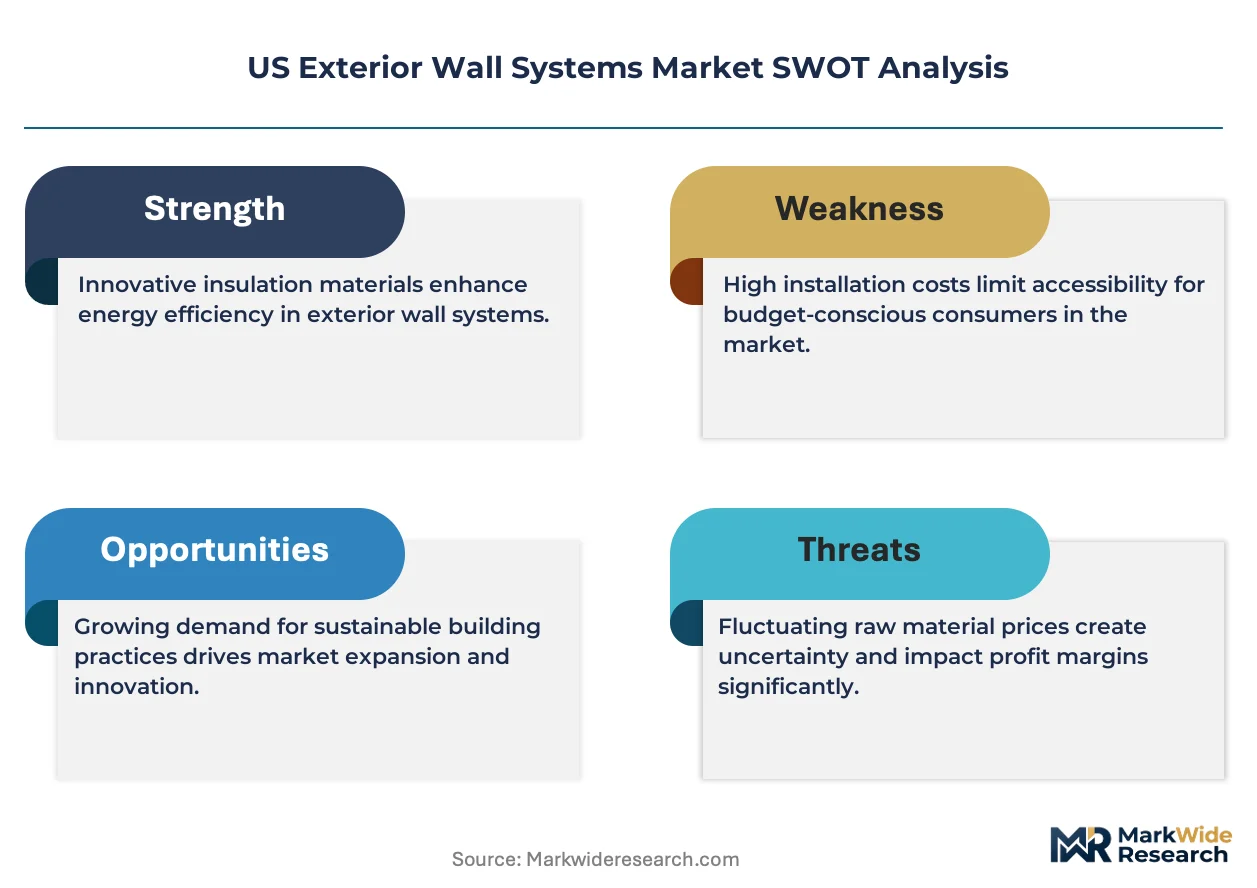
US Exterior Wall Systems Market dynamics center on the Department of Energy's tightening thermal bridging requirements, which are forcing manufacturers to redesign cladding-to-insulation interfaces and compressing specification timelines for builders seeking code compliance.
Growth Catalysts
- IECC Stretch Codes:Local jurisdictions across the Sun Belt are adopting building envelope standards that exceed baseline requirements, compelling builders to upgrade wall assembly specifications to maintain permitting speed.
- FHA Green Building Standards:Federal housing finance incentives for high-performance wall assemblies are redirecting residential construction toward insulated cladding systems that qualify for preferential mortgage terms.
- Composite Panel Technology:Rain screen systems incorporating advanced weather-resistant barriers are capturing specification share from conventional siding in commercial projects requiring accelerated installation cycles.
Market Restraints
- Petrochemical Input Volatility:Vinyl siding and polymer-based weather barriers face margin compression from fluctuating resin and plasticizer feedstock costs that manufacturers cannot fully pass through to price-sensitive residential segments.
- Specialized Labor Scarcity:OSHA fall protection mandates on retrofit projects have reduced contractor crew productivity, extending project timelines and limiting installer availability in high-demand Sun Belt metros.
- Metal Panel Substitution Ceiling:Large-format commercial metal panels face demand elasticity constraints in institutional segments where total installed cost premiums exceed budget allocation flexibility.
Strategic Opportunities
- Utility Rebate Programs:State-level incentive structures are shifting eligibility criteria toward whole-wall U-factor performance, creating first-mover advantage for manufacturers with integrated insulation-cladding testing capabilities.
- EPA Lead-Safe Renovation Compliance:Retrofit contractors seeking certified wall replacement services present a channel expansion opportunity for distributors with trained installation networks.
- Texas and Florida Distribution Density:Dedicated cladding distribution centers in high-growth housing markets enable specification capture through reduced lead times and localized color-matched inventory.
Industry Challenges
- Certification Timeline Compression:Whole-wall assembly testing for IECC compliance requires extended laboratory validation cycles that delay product launches and strain R&D resource allocation.
- Installer Skill Specialization:Multi-layer rain screen systems demand trained crews proficient in both air barrier continuity and drainage plane detailing, creating bottlenecks in markets with thin qualified labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Exterior Wall Systems Market |
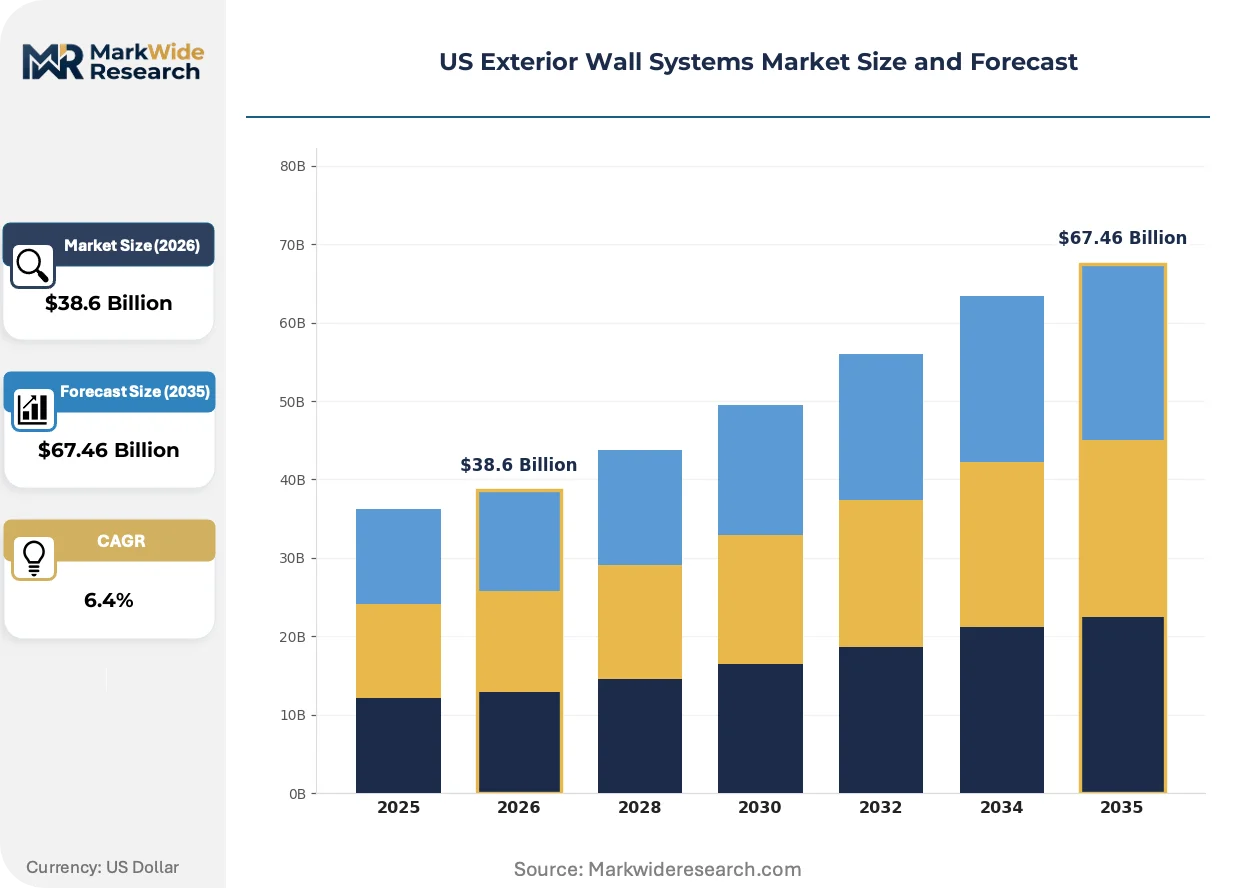
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Siding, Fiber Cement, Brick Veneer, Stucco, Metal Panels, Composite Panels Application: Residential Buildings, Commercial Complexes, Institutional Structures, Hospitality Facilities, Educational Campuses, Government Buildings Installation Method: Stick-Build, Panelized Systems, Curtain Wall, Unitized Systems, Rain Screen Systems, Precast Panels End User Type: Construction Contractors, Building Developers, Architectural Firms, Facility Managers, Property Owners, Renovation Specialists |
| Companies Covered | Owens Corning, James Hardie Industries, CertainTeed, GAF, Louisiana Pacific Corporation, Cornerstone Building Brands, Nichiha Corporation, PPG Industries, DuPont, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Exterior Wall Systems Market Trends and Innovations
Material convergence and regulatory stringency are compressing traditional product category boundaries in exterior wall systems, with specification decisions increasingly driven by whole-assembly performance metrics rather than component-level attributes.
Advanced composite cladding panels with integrated insulation layers are absorbing specification volume from conventional fiber cement and vinyl siding in mid-rise commercial and multifamily residential projects. National homebuilders are accelerating adoption of these systems to compress enclosure schedules and reduce trade coordination complexity. The technology is absorbing risk from thermal bridging liability while compressing the competitive window for standalone insulation suppliers.
OSHA fall protection mandates and EPA lead-safe renovation rules are restructuring contractor labor deployment on retrofit wall replacement projects. These regulations are extending project timelines and elevating compliance costs for smaller renovation specialists. Residential retrofit segments in older housing stock cities are responding by consolidating around larger contractors with dedicated safety infrastructure.
Buyer concentration among national homebuilders is compressing procurement cycles and elevating bundled specification requirements. Top-ten builders are consolidating vendor relationships around suppliers offering integrated insulation-to-cladding warranties that reduce callback exposure. This concentration is most visible in Sun Belt markets where production homebuilding volume supports dedicated distribution infrastructure and just-in-time delivery contracts.
US Exterior Wall Systems Market Segmentation
Exterior wall system specifications diverge sharply across construction verticals, with product selection driven by thermal performance mandates, installation speed requirements, and lifecycle cost calculations. Procurement patterns concentrate around integrated assemblies that compress enclosure schedules while satisfying IECC stretch code compliance.
Product Type:
Supply concentration in cladding manufacturing favors vertically integrated producers with captive insulation capacity and dedicated distribution footprints in high-volume housing markets.
- Vinyl Siding:Polymer-based cladding dominates single-family residential retrofits and entry-level new construction, with formulations incorporating recycled content to meet EPA procurement guidelines. Sun Belt production homebuilders specify vinyl for cost predictability amid resin price volatility.
- Fiber Cement:James Hardie Industries anchors national production through Texas and Florida distribution centers, capturing bundled specifications from top-ten builders seeking color-matched system warranties. The material absorbs premium residential demand in hurricane-prone coastal jurisdictions.
- Brick Veneer:Clay-based assemblies persist in institutional and heritage-adjacent projects where aesthetic durability outweighs labor intensity.
- Stucco:Cementitious finishes concentrate in Southwest and Florida markets with established installer networks and moisture management expertise.
- Metal Panels:Large-format aluminum and steel cladding dominates commercial and industrial envelopes where rapid installation offsets material premiums.
- Composite Panels:Rain screen-integrated systems with advanced weather-resistant barriers are gaining specification share in mid-rise commercial and multifamily projects requiring accelerated enclosure cycles.
Vinyl siding and fiber cement absorb the bulk of installed capacity; composite panels are expanding most quickly.
Application:
Cost tier stratification separates high-performance institutional envelopes from price-sensitive residential production, with financing incentives redirecting single-family construction toward insulated cladding assemblies.
- Residential Buildings:Single-family and multifamily construction drives volume demand, with FHA green building standards redirecting procurement toward high-R-value wall systems that qualify for preferential mortgage terms. Sun Belt housing starts concentrate specification activity.
- Commercial Complexes:Office and retail envelopes prioritize accelerated installation cycles, with rain screen and unitized systems capturing share from conventional cladding to compress project timelines.
- Institutional Structures:Healthcare and civic buildings mandate extended lifecycle performance, with whole-wall U-factor compliance driving specification of tested assembly systems.
- Hospitality Facilities:Hotel and resort construction balances aesthetic customization with moisture management in coastal and humid climates.
- Educational Campuses:K-12 and university projects incorporate durability specifications that reduce long-term maintenance expenditure.
- Government Buildings:Federal and state procurement adheres to DOE building envelope performance standards with thermal bridging limitations.
Residential buildings command the largest share of annual installations; institutional structures are climbing the fastest as IECC stretch codes tighten.
Installation Method:
Volume concentration in production homebuilding favors panelized and pre-engineered approaches that reduce on-site labor exposure to OSHA fall protection mandates.
- Stick-Build:Conventional site-assembled framing with applied cladding persists in custom residential and renovation segments where design flexibility outweighs speed considerations.
- Panelized Systems:Factory-built wall assemblies with integrated insulation and weather barriers compress enclosure schedules for national homebuilders with repetitive plan libraries. The method reduces trade coordination complexity in Sun Belt production markets.
- Curtain Wall:Non-structural glazed systems dominate commercial high-rise construction, with aluminum framing systems engineered for thermal break performance.
- Unitized Systems:Pre-glazed cladding units accelerate installation in urban commercial towers where crane time constraints drive prefabrication.
- Rain Screen Systems:Pressure-equalized assemblies with drained and ventilated cavities satisfy stringent moisture management requirements in coastal and high-precipitation zones.
- Precast Panels:Concrete-based envelope systems integrate structural and finish functions in institutional and parking structures requiring blast resistance or extended durability.
Stick-build methods retain the widest installer base; panelized systems are gaining share fastest among national production builders.
End User Type:
Customer type determines procurement leverage, with consolidated national builders extracting bundled pricing and warranty terms unavailable to fragmented renovation contractors.
- Construction Contractors:General and specialty contractors execute installation across all building types, with OSHA fall protection compliance and EPA lead-safe certification requirements restructuring labor deployment on retrofit projects.
- Building Developers:Multifamily and commercial developers prioritize whole-building energy modeling that optimizes wall assembly U-factors against HVAC capacity downsizing.
- Architectural Firms:Design professionals specify rain screen and composite systems for projects requiring accelerated installation and aesthetic customization.
- Facility Managers:Building operations personnel influence retrofit decisions based on lifecycle maintenance cost projections and envelope deterioration assessments.
- Property Owners:Single-family homeowners and small commercial landlords respond to utility rebate programs tying incentive eligibility to whole-wall performance metrics.
- Renovation Specialists:EPA-certified contractors capture lead-safe wall replacement demand in older housing stock cities, with consolidation favoring larger operators with dedicated safety infrastructure.
Construction contractors execute the majority of installed volume; renovation specialists are expanding fastest as housing stock ages and utility rebate programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability along the Gulf Coast anchors manufacturing capacity for vinyl siding and polymer-based weather barriers serving Sun Belt construction demand.
Texas
Houston-area resin production supplies raw material for vinyl siding formulations while Dallas-Fort Worth housing starts drive specification volume. IECC stretch code adoption in Austin and San Antonio compels builders to upgrade wall assembly thermal performance. Dedicated distribution centers in Houston and DFW metro areas compress lead times for national homebuilders.
Florida
Miami-Dade wind-borne debris requirements and statewide humidity exposure shape moisture management specifications in coastal construction. Florida Building Code energy provisions exceed baseline IECC standards in multiple jurisdictions. Tampa and Orlando production homebuilding corridors concentrate panelized wall system deployment.
California
Title 24 energy code mandates drive specification of high-R-value assemblies in Los Angeles and San Francisco Bay Area multifamily projects. CALGreen building standards require whole-building energy modeling that optimizes envelope performance. Central Valley production builders balance cost constraints against escalating thermal bridging requirements.
Southeast
Atlanta and Charlotte housing markets absorb fiber cement and vinyl siding volume for entry-level and move-up residential segments. Georgia and North Carolina utility rebate programs tie incentive eligibility to whole-wall U-factor performance. Regional distribution hubs in Atlanta serve expanding production builder procurement consolidation.
Southwest
Phoenix and Las Vegas housing starts concentrate demand for stucco and fiber cement assemblies suited to arid climate exposure. Arizona and Nevada stretch code adoption lags coastal states but accelerates in municipal jurisdictions. Local installer networks in Phoenix maintain specialized expertise in cementitious finish systems.
US Exterior Wall Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated insulation-cladding bundles. The vendor base concentrates around vertically integrated building materials conglomerates with captive distribution infrastructure. Three archetypes dominate: insulation-to-cladding integrators, fiber cement specialists, and polymer-based cladding manufacturers. Competitive moves center on distribution density expansion and warranty-backed specification capture.
Among North American building materials producers, Owens Corning, James Hardie Industries, and CertainTeed exemplify distinct strategic positions within the competitive structure. Owens Corning represents the insulation-to-cladding integration archetype. James Hardie Industries occupies a position as the fiber cement segment anchor. CertainTeed sits within the diversified building products tier with color-matched system warranty capabilities.
| Leading Market Players |
|---|
| Owens Corning |
| James Hardie Industries |
| CertainTeed |
| GAF |
| Louisiana Pacific Corporation |
| Cornerstone Building Brands |
| Nichiha Corporation |
| PPG Industries |
| DuPont |
| Others |
Pricing and Supply Chain Analysis
Top-ten national homebuilder consolidation around bundled insulation-cladding warranties is forcing supply base rationalization and compressing margin pools for standalone component suppliers unable to offer integrated performance guarantees.
Pricing Analysis
Warranty bundling separates pricing tiers in the US Exterior Wall Systems Market, with integrated assembly suppliers commanding premiums for whole-wall U-factor guarantees while unbundled cladding and insulation vendors compete on transactional unit economics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with IECC stretch code compliance costs feeding price escalation in the premium tier. Cost compression in economy vinyl siding is intensifying because resin price volatility outpaces pass-through capacity to price-sensitive production builders. Renovation contractors exhibit highest price sensitivity due to thin project margins, while institutional developers accept material premiums for accelerated enclosure schedules.
Supply Chain Analysis
Dual-sourcing mandates from national homebuilders require manufacturers to qualify secondary resin suppliers and backup weather barrier film producers, extending procurement cycles and elevating qualification costs for tier-two distributors. Gulf Coast petrochemical production anchors North American vinyl compound supply, while South Korean and German engineered polymer operations feed specialty weather-resistant barrier demand. Raw material exposure centers on PVC resin, acrylic modifiers, and fluoropolymer films. Single-source vulnerability concentrates in titanium dioxide pigment supply from Chinese producers. Distribution runs through dedicated cladding distribution centers in Texas and Florida that compress lead times for production builder just-in-time contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite panel technology with integrated insulation layers is displacing conventional fiber cement and vinyl siding in mid-rise commercial and multifamily specifications, compressing the competitive window for legacy standalone products.
For Market Incumbents: Acquire captive weather barrier manufacturing capacity to defend specification share against integrated assembly entrants threatening standalone insulation suppliers. James Hardie Industries anchors fiber cement position through Texas and Florida distribution density; Owens Corning leverages insulation-to-cladding backward integration to capture bundled procurement from consolidated national homebuilders. Certification investment in whole-wall U-factor testing laboratories represents critical defensive leverage as IECC stretch code adoption accelerates. For New Entrants and Emerging Players: Begin with EPA lead-safe certified installation services targeting renovation specialists in older housing stock cities where qualified contractor scarcity creates channel entry opportunity. Underpenetrated utility rebate program administration presents white-space potential, with state-level incentive structures shifting eligibility toward whole-wall performance metrics that favor testing-capable entrants. Direct contractor training partnerships bypass established distribution gatekeepers in Sun Belt metro markets. For Investors and Strategic Acquirers: The window for entry favors vertically integrated building materials conglomerates with captive distribution infrastructure and R&D scale for assembly-level certification. Long-term viability hinges on exposure to IECC stretch code adoption curves and national homebuilder procurement consolidation trends. Watch for state-level stretch code acceleration as inflection signal, particularly in Arizona and Nevada municipal jurisdictions currently lagging coastal adoption patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Weather Barrier Manufacturing | Captures margin pool from standalone membrane suppliers while accelerating IECC compliance certification timelines. |
| Whole-Wall U-Factor Testing Laboratory Investment | Enables first-mover qualification for utility rebate programs shifting incentive eligibility toward assembly-level performance. |
| EPA Lead-Safe Certified Installation Network Expansion | Captures retrofit demand in older housing stock cities where OSHA mandates consolidate activity around larger contractors. |
| Texas and Florida Distribution Center Densification | Compresses lead times for national homebuilder just-in-time contracts in highest-volume Sun Belt construction corridors. |
| Composite Panel Technology Platform Development | Absorbs specification share from conventional siding in mid-rise commercial projects requiring accelerated enclosure cycles. |
Research Methodology
Document review covered building code adoption databases, utility incentive program filings, and petrochemical trade flow data, complemented by interviews with national homebuilder procurement directors, regional distribution center operators, EPA-certified renovation contractors, and weather barrier product managers. Secondary validation drew from Department of Energy building envelope performance standard releases, IECC stretch code municipal adoption records, and OSHA fall protection enforcement patterns. Bottom-up installation volume estimates triangulated against top-down construction spending allocations across residential, commercial, and institutional verticals.
Segment-level projections across the analysis window reflect modeled interactions between housing start trajectories, code adoption curves, and material substitution elasticities. Product type, application, installation method, and end user type dimensions anchored the analytical framework, with rain screen system penetration rates and panelized construction adoption serving as industry-specific forecast inputs. CAGRs derived from regression-weighted scenario probabilities across base, stretch code acceleration, and housing correction cases.
Underlying measurement precision varies by segment; vinyl siding and fiber cement volume estimates carry tighter precision than emerging composite panel categories where specification data remains sparse. Forecasts reflect assumptions regarding IECC stretch code adoption velocity, resin price volatility persistence, and national homebuilder procurement consolidation trajectory. Deviation in federal housing finance agency green building standard enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Acoustic Plasterboard Market