
 Concrete Protective Liners Market | 2026-2036
Concrete Protective Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Protective Liners Market Analysis
Project finance structures for municipal wastewater infrastructure is reconfiguring competitive access, allowing mid-tier suppliers to bid on bundled liner-and-installation contracts previously reserved for integrated giants. GSE Environmental leverages its geosynthetic manufacturing depth to anchor large-scale containment projects across North America. RPM International sustains diversified coating portfolios that compete across waterproofing and chemical-resistant segments. AGRU Kunststofftechnik specializes in precision-extruded polyethylene systems that dominate European specification standards.
Concrete protective liners are impermeable barrier systems, typically 1.5–3.0 mm thick, manufactured from high-density polyethylene or polyvinyl chloride through extrusion or calendering processes, engineered to prevent chemical ingress, abrasion, and freeze-thaw damage in buried or submerged concrete structures. Their primary purpose extends service life of infrastructure assets exposed to aggressive effluents, groundwater pressure, and biological corrosion. Polyethylene formulations command the largest volume share due to weldability and chemical inertia, while geosynthetic clay composites represent the fastest-expanding niche for low-permeability landfill base applications. Extrusion technology leads output volume, though coating methods capture premium margin pools in tunnel and aquaculture retrofit markets where substrate adhesion complexity demands specialized application expertise.
EPA underground storage tank regulations and NSF/ANSI 61 drinking water system standards govern material eligibility in US municipal procurement, while ISO 10318 geosynthetic classification frameworks shape cross-border product equivalency. These compliance layers elevate testing costs but lock in specification loyalty for certified suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated additive bans could force reformulation of select PVC and coating chemistries within the decade.
Market Dynamics
Municipal infrastructure bond financing is reconfiguring procurement authority, transferring specification control from general contractors to municipal engineers who prioritize certified material traceability over bundled installation pricing.
Growth Catalysts
- EPA Corrosion Standards:Underground storage tank regulations mandate liner retrofitting for aging concrete containment structures, creating compliance-driven replacement cycles in municipal wastewater systems.
- Polyethylene Weldability:HDPE formulations enable field-fabricated seams that reduce installation complexity and accelerate project timelines for containment contractors.
- Wastewater Treatment Expansion:Population growth in Sun Belt municipalities drives new facility construction with specified liner systems for primary and secondary containment.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and vinyl chloride monomer prices fluctuate with crude oil indices, compressing margin predictability for extruded liner manufacturers.
- Specialized Installer Scarcity:Certified welding technicians concentrate in Great Lakes and Gulf Coast industrial corridors, creating geographic service gaps for remote project sites.
- Geosynthetic Clay Substitution:Bentonite composite systems capture landfill base applications where ultra-low permeability requirements exceed conventional polymer performance.
Strategic Opportunities
- Federal Infrastructure Spending:Bipartisan legislation directs capital toward buried asset rehabilitation, expanding specification opportunities for NSF/ANSI 61 certified products.
- Aquaculture Retrofit Demand:Recirculating aquaculture systems require chemical-resistant containment, opening non-traditional end-use verticals for liner suppliers.
- Digital Weld Documentation:Automated seam traceability systems align with municipal asset management platforms, creating differentiation for technology-integrated installers.
Industry Challenges
- NSF/ANSI 61 Certification Timelines:Drinking water contact approvals require 18-24 month testing protocols, delaying market entry for reformulated chemistries.
- Legacy Concrete Assessment Complexity:Substrate condition variability demands site-specific engineering, complicating standardized product positioning and quotation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Protective Liners Market |
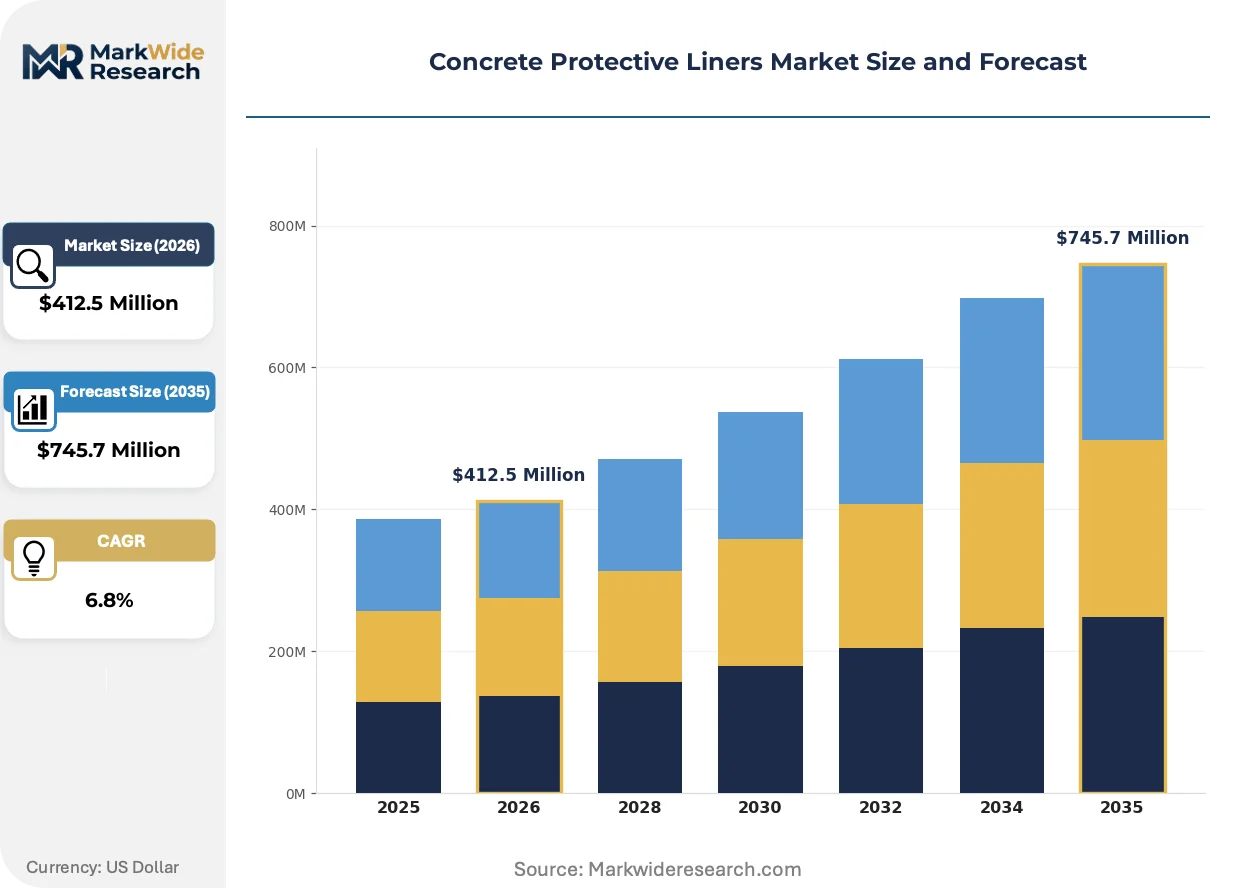
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, PVC, EPDM, Geosynthetic Clay End Use: Waterproofing, Waste Management, Agriculture, Mining Application: Landfills, Aquaculture, Irrigation, Tunnels Technology: Extrusion, Injection Molding, Coating, Laminating |
| Companies Covered | GSE Environmental LLC, RPM International Inc., AGRU Kunststofftechnik GmbH, Layfield Group Ltd., The Sherwin-Williams Company, Sika AG, MAPEI S.p.A., Flexcrete Technologies Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Protective Liners Market Emerging Trajectories
Material science convergence with digital quality assurance is compressing specification cycles and elevating performance verification requirements across municipal procurement channels.
Ultrasonic weld inspection equipment is digitizing quality control protocols for HDPE liner installation. Municipal wastewater authorities in Texas and Florida now require digital seam mapping for projects exceeding 10,000 square meters. This technology is digitizing documentation standards that previously relied on manual destructive testing, reducing verification costs while accelerating project closeout timelines.
EPA's emerging per- and polyfluoroalkyl substance restrictions are forcing PVC formulation reviews. The agency's 2024 testing orders for fluorinated additives signal potential bans on legacy plasticizer chemistries. European ECHA parallel evaluations are accelerating supplier reformulation investments, with drinking water contact applications facing the most compressed compliance deadlines.
Engineer-procure-construct contracting is consolidating specification authority among fewer municipal consulting firms. Large water infrastructure design-build projects in California and Arizona now bundle liner selection with civil works procurement, displacing traditional general contractor material discretion. This concentration is most visible in Southwestern states where water scarcity elevates containment performance priorities in public-private partnership structures.
Concrete Protective Liners Market Segmentation
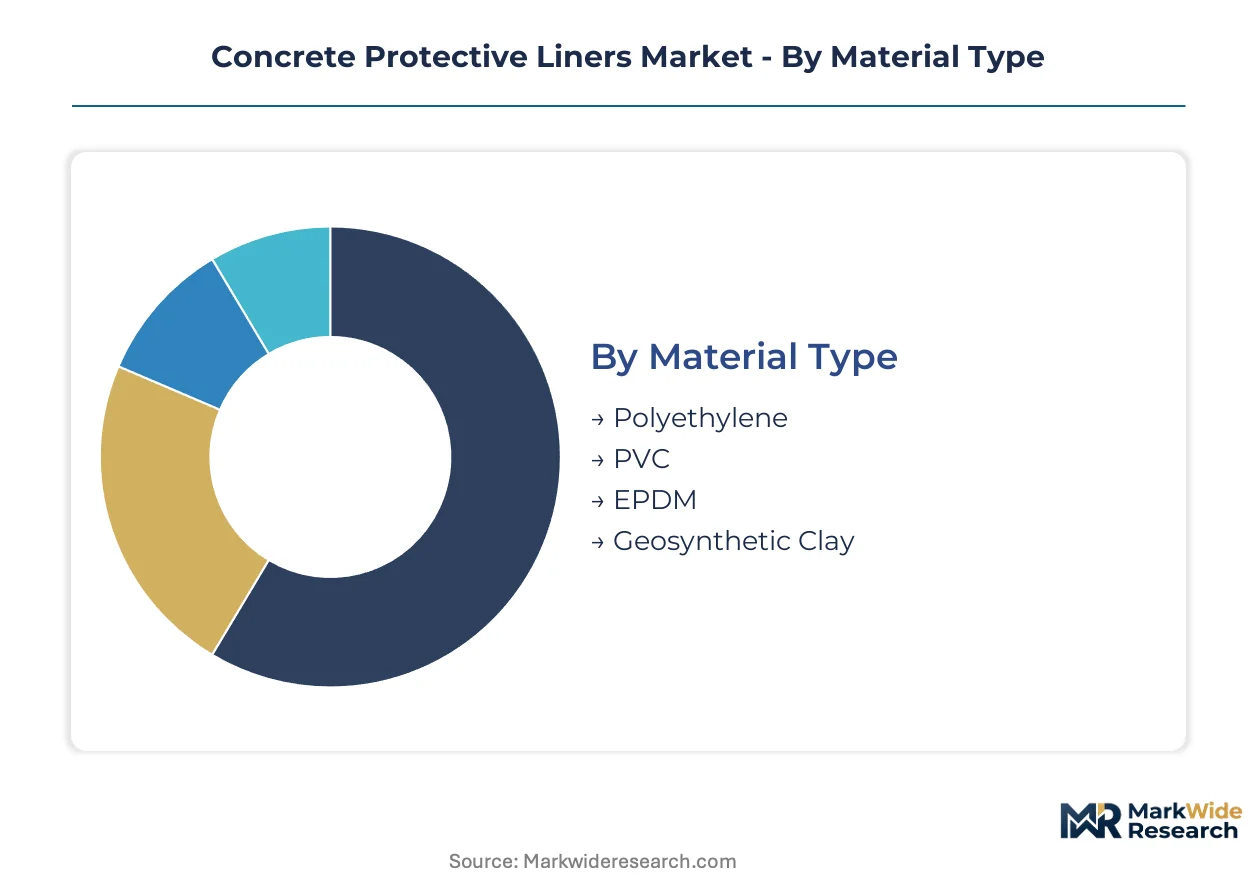
Concrete protective liner specifications diverge sharply across material chemistry and installation context, with each segment demanding distinct technical service protocols. Procurement teams segment specifications by corrosion resistance requirements, seam welding complexity, and regulatory compliance pathways rather than unit cost alone.
Material Type:
After-sales service intensity peaks with material selection, as polyethylene systems require certified welding technicians for field repairs while PVC demands specialized adhesive protocols and EPDM needs vulcanization equipment.
- Polyethylene:High-density formulations dominate municipal wastewater specifications due to thermal fusion weldability and chemical inertia against sulfuric acid corrosion. Demand concentrates in Sun Belt states where EPA underground storage tank regulations drive retrofit cycles for aging concrete containment structures.
- PVC:Calendered polyvinyl chloride sheets offer superior substrate adhesion for tunnel and aquaculture retrofits where irregular concrete surfaces complicate membrane placement. ECHA fluorinated additive restrictions are forcing reformulation investments for drinking water contact applications.
- EPDM:Ethylene propylene diene monomer rubber excels in freeze-thaw cycling environments with elastic recovery properties.
- Geosynthetic Clay:Bentonite-geomembrane composites capture landfill base specifications requiring ultra-low permeability below polymer thresholds.
Polyethylene holds the largest share; momentum sits with geosynthetic clay in engineered containment.
End Use:
Cost tier stratification separates premium waterproofing specifications from commodity waste management applications, with certification requirements driving price spreads.
- Waterproofing:Tunnel and below-grade building applications demand NSF/ANSI 61 certified materials with documented seam traceability for municipal asset management integration. Specifications cluster in coastal cities facing saltwater intrusion and groundwater pressure.
- Waste Management:Landfill primary and secondary containment systems specify 2.0–3.0 mm HDPE with double-seamed welds and electronic leak detection compatibility. Federal infrastructure spending targets buried asset rehabilitation across Midwest and Gulf Coast corridors.
- Agriculture:Irrigation canal lining and manure containment applications prioritize UV-stabilized formulations for exposed service conditions.
- Mining:Heap leach pads and tailings impoundments require chemical-resistant barriers against acidic process solutions.
Waterproofing commands premium pricing; waste management delivers volume scale.
Application:
Application context determines installation methodology and qualified contractor availability, with remote sites facing scarcity of certified welding technicians.
- Landfills:Subtitle D regulations mandate composite liner systems with leachate collection layers, creating bundled procurement opportunities for geosynthetic installers. Texas and Florida authorities now require digital seam mapping for projects exceeding threshold acreage.
- Aquaculture:Recirculating systems for finfish and shellfish production specify food-grade materials with biological fouling resistance. Demand is expanding fastest in coastal zones where land-based aquaculture reduces wild harvest pressure.
- Irrigation:Canal rehabilitation projects in water-stressed regions specify exposed liners with abrasion-resistant surfaces.
- Tunnels:Spray-applied and sheet membrane systems compete based on access constraints and substrate preparation requirements.
Landfills anchor volume demand; aquaculture is climbing the fastest as non-traditional verticals open.
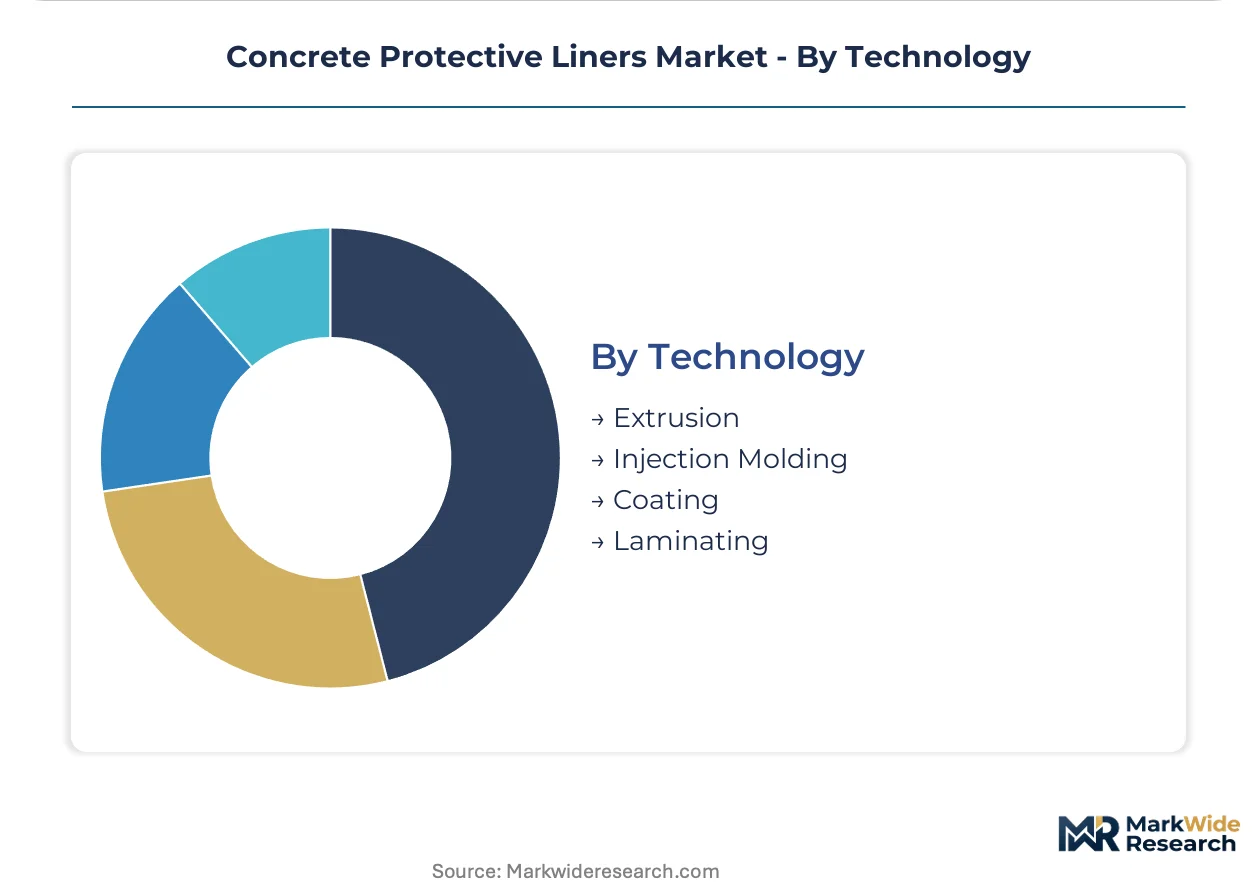
Technology:
Technology selection locks in manufacturing capital requirements and margin profiles, with extrusion dominating volume and coating capturing retrofit premiums.
- Extrusion:Flat-die and blown-film processes produce continuous HDPE sheets with consistent thickness control for large-scale containment projects. Equipment scale economies favor integrated manufacturers serving bundled liner-and-installation contracts.
- Coating:Liquid and powder systems enable field application to irregular substrates in tunnel and aquaculture retrofits where sheet membrane placement proves impractical. Specialized applicator expertise creates service differentiation.
- Injection Molding:Precision-formed fittings and penetration boots complement sheet systems at pipe entries and structural transitions.
- Laminating:Multi-layer composites combine polymer barriers with geotextile protection layers for puncture resistance in aggregate subgrades.
Extrusion leads output volume; coating claims the steepest margin expansion trajectory in retrofit segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure spending and EPA corrosion mandates are reconfiguring procurement authority across municipal wastewater systems. Specification control is shifting from general contractors to municipal engineers who prioritize certified material traceability. Geographic demand concentrates where aging concrete assets face aggressive effluent exposure and regulatory compliance deadlines.
United States
Sun Belt municipalities in Texas and Florida are driving new facility construction with specified liner systems for primary containment. EPA underground storage tank regulations mandate liner retrofitting for aging concrete structures, creating compliance-driven replacement cycles. Houston and Miami-Dade County authorities now require digital seam mapping for projects exceeding 10,000 square meters.
Germany
Precision-extruded polyethylene systems dominate European specification standards for municipal wastewater infrastructure. ECHA evaluations of fluorinated additives are accelerating supplier reformulation investments ahead of potential regulatory bans. The Ruhr industrial corridor hosts concentrated liner fabrication capacity serving Central European containment projects.
China
Dual carbon goals and water scarcity pressures are expanding specification opportunities for chemical-resistant containment in industrial wastewater treatment. The national environmental regulator is tightening discharge standards for heavy industry, forcing concrete asset upgrades. Yangtze River Delta municipalities are bundling liner procurement with civil works contracts.
Canada
Aging municipal infrastructure in Ontario and Quebec is driving federal-provincial cost-shared rehabilitation programs for buried concrete assets. Health Canada drinking water contact standards govern material eligibility in municipal procurement. Toronto's water authority has pioneered automated seam traceability requirements for large-scale containment projects.
Australia
Mining tailings and heap leach pad applications are expanding demand for chemical-resistant barriers against acidic process solutions. Water-stressed regions in New South Wales and Queensland are specifying exposed liners with abrasion-resistant surfaces for irrigation canal rehabilitation. Sydney's infrastructure procurement frameworks emphasize certified material traceability.
Concrete Protective Liners Market Vendor Landscape
Channel-controlling players compete with product-specialist players across specification tiers. The vendor base organizes around three strategic archetypes: integrated geosynthetic manufacturers with installation capabilities, diversified coating portfolio companies spanning waterproofing segments, and precision-extrusion specialists dominating regional specification standards. Competitive moves concentrate on backward integration into polymer resin supply and technology licensing for digital weld documentation systems.
Among North American-based integrated manufacturers, GSE Environmental LLC and RPM International Inc. occupy positions anchoring large-scale containment projects. AGRU Kunststofftechnik GmbH exemplifies the European precision-extrusion archetype. These three entities represent distinct competitive vectors: bundled liner-and-installation contracting, diversified coating portfolio competition, and regional specification standard-setting through manufacturing depth.
| Leading Market Players |
|---|
| GSE Environmental LLC |
| RPM International Inc. |
| AGRU Kunststofftechnik GmbH |
| Layfield Group Ltd. |
| The Sherwin-Williams Company |
| Sika AG |
| MAPEI S.p.A. |
| Flexcrete Technologies Ltd. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Ethylene and vinyl chloride monomer concentration in Gulf Coast petrochemical corridors directly determines margin distribution between extruded sheet manufacturers and specialized coating applicators. Raw material volatility feeds downstream into project-based pricing structures where certified installers capture premium returns over commodity liner suppliers.
Pricing Analysis
Certification level creates the primary spread between NSF/ANSI 61 drinking water contact grades and standard wastewater containment specifications. Project-based contracting dominates municipal procurement, with price differentiation driven by digital weld documentation capabilities and after-sales service bundling. Cost compression in standard HDPE grades is intensifying because geosynthetic clay alternatives capture landfill base applications. Municipal engineers show lowest price sensitivity for potable water infrastructure, while agricultural canal rehabilitation projects prioritize unit cost minimization.
Supply Chain Analysis
Contract manufacturing for precision-extruded polyethylene systems concentrates with integrated geosynthetic specialists in Germany and the United States. Raw material dependencies rest on ethylene feedstock from Gulf Coast crackers, vinyl chloride monomer from integrated chlor-alkali facilities, and bentonite clay from Wyoming deposits. Single-source vulnerability runs through certified welding technician pools concentrated in Great Lakes and Gulf Coast industrial corridors. Distribution feeds from manufacturer-direct project contracting for large-scale containment, with regional distributors serving maintenance and retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal infrastructure spending cycles position this market for municipal wastewater rehabilitation recovery, with EPA underground storage tank mandates creating predictable replacement demand.
For Market Incumbents: Harden specification loyalty through backward integration into polymer resin supply and accelerated NSF/ANSI 61 certification investments for reformulated chemistries. Geosynthetic clay substitution in landfill applications threatens volume share; digital weld documentation capabilities provide the most durable defensive lever against mid-tier competitors bundling installation services. For New Entrants and Emerging Players: Aquaculture retrofit demand in coastal zones represents the most penetrable entry point for non-traditional liner applications. Recirculating finfish containment systems specify food-grade materials with limited incumbent penetration. Target engineer-procure-construct contracting consolidation in Southwestern states through partnerships with municipal consulting firms seeking certified material traceability. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating specialists holding diversified waterproofing portfolios. Five-to-ten year viability hinges on regulatory compliance agility rather than manufacturing scale alone. Watch EPA per- and polyfluoroalkyl substance restriction timelines as inflection indicator for PVC formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Gulf Coast ethylene access insulates margin against feedstock volatility for extruded sheet manufacturers. |
| Digital Weld Documentation System Deployment | Automated seam traceability aligns with Texas and Florida municipal asset management platform requirements. |
| NSF/ANSI 61 Certification Acceleration | Drinking water contact approvals unlock premium procurement channels ahead of fluorinated additive restrictions. |
| Geosynthetic Clay Composite Capacity Addition | Ultra-low permeability landfill specifications capture volume migrating from conventional polymer barriers. |
| Engineer-Procure-Construct Partnership Structuring | Bundled civil works contracting in California and Arizona displaces traditional general contractor material discretion. |
Methodological Framework
Initial hypotheses were tested against primary input from municipal wastewater engineers, certified liner installation contractors, geosynthetic procurement managers, and EPA regulatory affairs specialists and refined through secondary validation. Municipal bond financing databases, EPA underground storage tank compliance records, NSF/ANSI 61 certification registries, and SEC filings from diversified coating portfolio companies anchored the secondary foundation. Bottom-up project pipeline assessment triangulated with top-down infrastructure spending allocation analysis.
Demand-supply balance modeling across the analysis window incorporated material type segmentation by polyethylene, PVC, EPDM, and geosynthetic clay chemistries; end-use differentiation across waterproofing, waste management, agriculture, and mining applications; and technology distinctions between extrusion, coating, injection molding, and laminating processes. CAGRs were derived from regression against municipal capital expenditure cycles and regulatory compliance deadline clustering. Forecast inputs included petrochemical feedstock price trajectory assumptions and certified welding technician geographic distribution patterns.
Practitioners should monitor EPA per- and polyfluoroalkyl substance testing order outcomes and ECHA parallel evaluation timelines for early signals of formulation obsolescence. Forecasts embed assumptions regarding federal infrastructure spending authorization continuity and municipal bond market access conditions. Quarterly review of municipal procurement platform specification changes and certified installer geographic expansion patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market