
 Door Hardware Market | 2026-2036
Door Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Door Hardware Market Analysis
The split between premium architectural-grade hardware and commodity builder-grade products is shifting as specification-grade projects demand certified fire ratings and smart connectivity while mass residential construction optimizes for cost. ASSA ABLOY dominates electromechanical access solutions through its Yale and HID brands, leveraging decades of institutional channel control. Baldwin Hardware anchors the luxury residential segment with forged brass construction and lifetime finish warranties that sustain margin pools above commodity tiers.
Door hardware encompasses mechanical and electromechanical devices—including locks, hinges, handles, and latches—fabricated from steel, brass, aluminum, or stainless steel through casting, forging, CNC machining, and PVD coating processes to control access, ensure life-safety compliance, and enable building automation integration. Stainless steel handles and hinges lead specification-driven commercial projects where salt corrosion resistance and 316-grade composition command price premiums over plated steel alternatives. Smart installation types represent the fastest-expanding category as Bluetooth and NFC-enabled mortise locks displace traditional keyed systems in multifamily and hospitality verticals where property managers prioritize remote credential management.
NFPA 80 and the International Building Code govern fire-rated door assemblies in the United States, mandating labeled hardware that third-party laboratories test to UL 10C standards, while the EU Construction Products Regulation requires CE-marked hardware with declared performance under EN 12209 for locks and EN 1935 for hinges. Stakeholders must monitor whether evolving cybersecurity frameworks for connected locks from NIST and ETSI reshape product development roadmaps and certification costs for smart hardware portfolios.
Market Dynamics
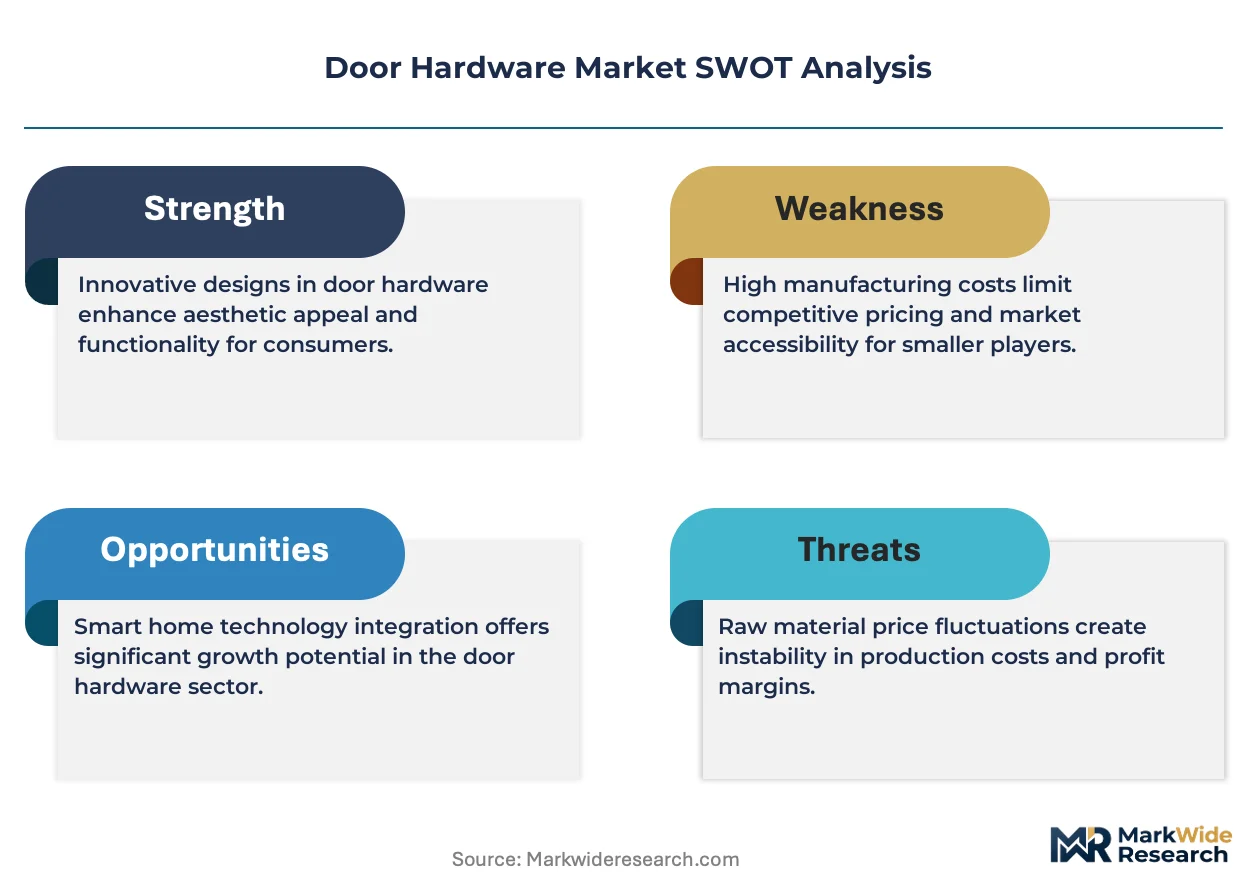
Smart access technology is fragmenting control architectures across commercial buildings as property managers demand cloud-native credential management that bypasses traditional hardwired systems. This shift compresses installation timelines while elevating cybersecurity exposure as attack surfaces multiply across Bluetooth and NFC endpoints.
Growth Catalysts
- NFPA 80 fire door mandates:US commercial real estate developers face accelerated replacement cycles as jurisdictions adopt stricter labeled hardware requirements for high-rise assemblies.
- China's green building mandates:The Ministry of Housing and Urban-Rural Development drives institutional procurement of certified hardware in urban renewal zones.
- Bluetooth Low Energy modules:Silicon cost curves enable OEMs to embed wireless connectivity into mid-tier mortise locks without premium pricing.
Market Restraints
- Brass and zinc input volatility:Forged hardware margins compress when London Metal Exchange prices spike, forcing spot-buying or inventory risk.
- 316-grade stainless concentration:Specification-grade hinge supply clusters in Zhejiang and Guangdong provinces, exposing buyers to port congestion shocks.
- Legacy keyed system persistence:Small multifamily operators resist retrofit costs despite smart lock availability, slowing category penetration.
Strategic Opportunities
- India's affordable housing vertical:PMAY-Urban scheme volume creates tiered hardware demand where certified fire-rated products remain undersupplied.
- ETSI cybersecurity standards:European connected lock certification opens margin pools for vendors investing in penetration-tested firmware architectures.
- Direct-to-developer platforms:Bypassing traditional distributor markup, hardware OEMs build procurement portals for national multifamily REITs.
Industry Challenges
- UL 10C testing backlog:Third-party laboratory capacity constraints delay fire-rated hardware launches by six to nine months.
- Cybersecurity talent scarcity:Embedded firmware security expertise commands premium compensation, stretching R&D budgets for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door Hardware Market |
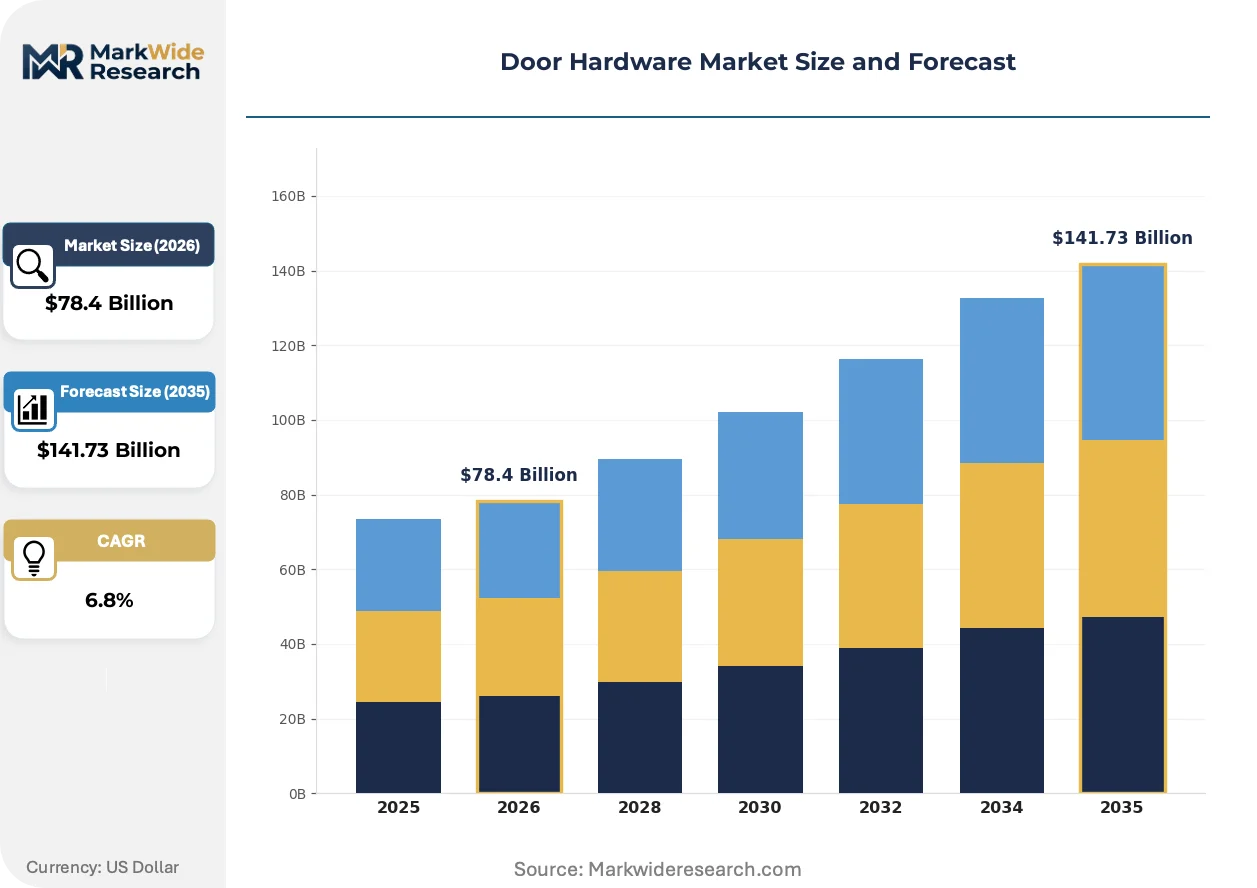
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handles, Locks, Hinges, Latches Material: Steel, Brass, Aluminum, Stainless Steel Installation Type: Universal, Mortise, Rim, Smart End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Dorma (dormakaba), Baldwin Hardware, ASSA ABLOY, Emtek, Hager Companies, Allegion, Kwikset, Yale, Häfele, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door Hardware Market Emerging Trajectories
Wireless credential architectures are collapsing the distinction between mechanical and electromechanical hardware as property technology stacks consolidate around unified access platforms. This convergence demands new supplier capabilities spanning metal fabrication, RF engineering, and cloud infrastructure.
Bluetooth-enabled mortise locks with over-the-air firmware update capability are decentralizing access control decisions from centralized security desks to individual unit managers. Hospitality operators in North American extended-stay segments deploy these systems to reduce front-desk staffing ratios. The technology is decentralizing hardware procurement authority from corporate facilities teams to regional property managers who prioritize installation speed over brand standardization.
China's GB standards for smart building hardware now mandate interoperability testing with domestic IoT platforms, forcing foreign OEMs to localize firmware stacks. This regulatory friction elevates compliance costs but creates captive demand for domestic semiconductor modules. European vendors targeting Chinese commercial projects must now certify against both EN 12209 and GB/T 31024, extending product development cycles.
Specification-grade buyers now unbundle hardware procurement from installation contracts, directly sourcing certified products while bidding out labor separately. This disintermediation compresses distributor margins and forces wholesalers to add value through inventory positioning or technical support. The pattern is most visible in US healthcare construction where facilities managers hold direct relationships with ASSA ABLOY and Allegion specification teams.
Door Hardware Market Segmentation
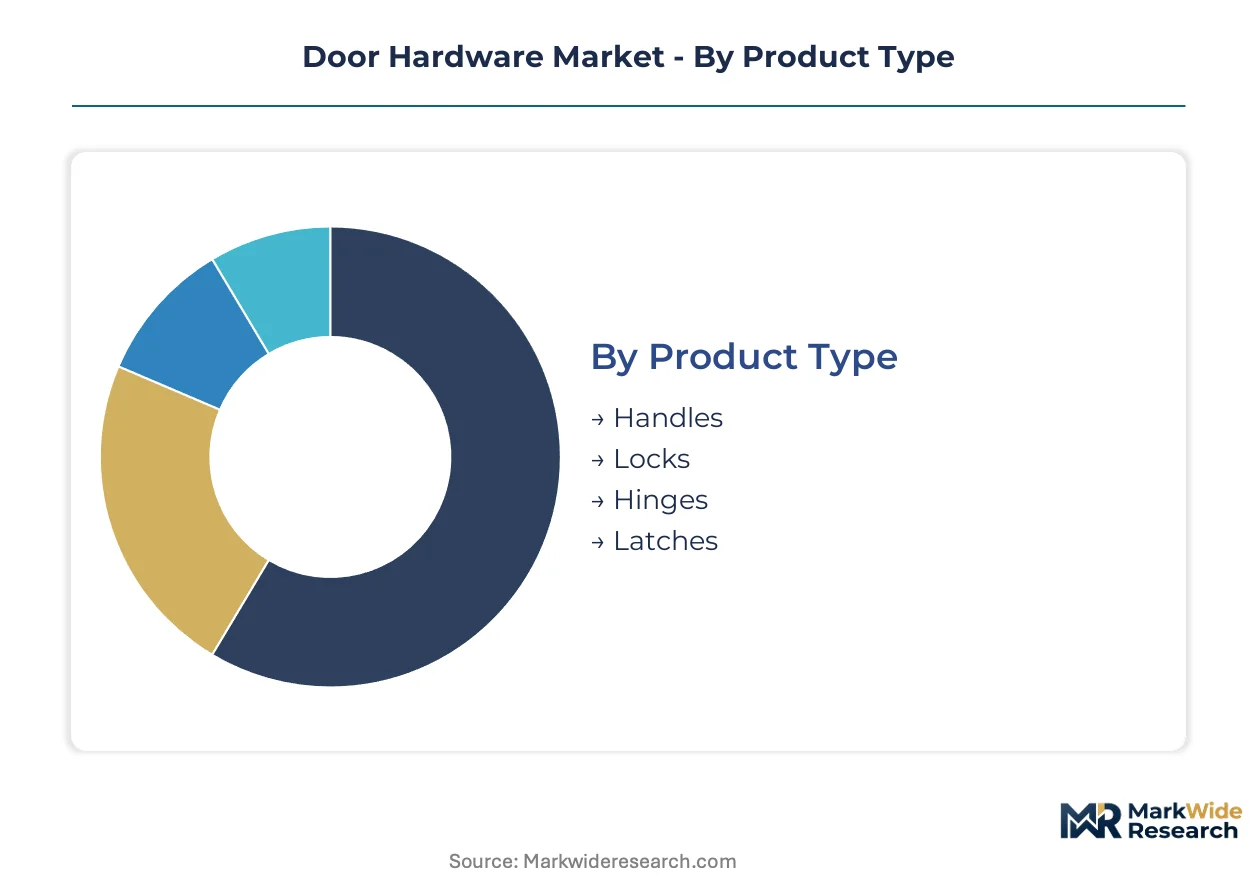
Door hardware segmentation reflects divergent buyer priorities across specification-grade projects, mass residential construction, and connected building retrofits. Procurement authority splits between architects demanding certified fire ratings, developers optimizing installation speed, and facility managers prioritizing remote credential management.
Product Type:
Buyers in this category differentiate by functional criticality and replacement frequency rather than upfront cost alone.
- Handles:Stainless steel and forged brass constructions dominate specification-driven commercial projects where salt corrosion resistance and tactile finish quality command price premiums. Demand concentrates in US healthcare and hospitality verticals where ADA compliance and antimicrobial copper alloys drive specification decisions.
- Locks:Electromechanical mortise and cylindrical formats are displacing traditional keyed systems in multifamily and hospitality properties where property managers prioritize remote credential management and audit trail capabilities. Bluetooth Low Energy modules now embed into mid-tier products without premium pricing.
- Hinges:Ball-bearing and continuous piano hinge formats serve fire-rated door assemblies requiring third-party UL 10C certification.
- Latches:Tubular and deadlatch mechanisms optimize for cost-sensitive residential new construction with minimal security requirements.
Volume sits with Locks; growth tilts toward Smart-enabled formats across all product types.
Material:
Raw material selection tracks exposure environment, life-cycle cost calculations, and regional supply availability.
- Steel:Cold-rolled and plated steel dominates mass residential construction where cost optimization outweighs corrosion resistance. China's Zhejiang and Guangdong provinces concentrate specification-grade hinge production, exposing buyers to port congestion risks.
- Brass:Forged brass construction anchors luxury residential segments with lifetime finish warranties and margin pools above commodity tiers. London Metal Exchange price volatility compresses margins during zinc and copper spikes, forcing spot-buying or inventory risk.
- Aluminum:Extruded and cast aluminum serves commercial projects requiring weight reduction and anodized finish durability.
- Stainless Steel:316-grade composition leads marine and coastal commercial applications where salt corrosion resistance justifies price premiums over 304-grade alternatives.
Steel captures the highest shipment volumes; stainless steel climbs fastest on specification-grade commercial demand.
Installation Type:
Installation complexity determines whether procurement flows through distributor networks or direct-to-developer channels.
- Universal:Adjustable backset designs accommodate retrofit applications across mixed-age building stocks without door preparation modifications.
- Mortise:Heavy-duty chassis formats serve high-traffic commercial entrances where ANSI Grade 1 durability ratings are mandatory. Bluetooth-enabled variants with over-the-air firmware updates are decentralizing access control decisions from centralized security desks to individual unit managers.
- Rim:Surface-mounted configurations enable rapid installation on metal door frames where mortise pocket cutting is impractical.
- Smart:Cloud-native credential management bypasses traditional hardwired systems, compressing installation timelines while elevating cybersecurity exposure across Bluetooth and NFC endpoints. Hospitality operators deploy these systems to reduce front-desk staffing ratios.
Mortise formats dominate commercial specifications; smart installations expand most quickly across multifamily and hospitality retrofits.
End User:
End-user segmentation maps to regulatory exposure, procurement sophistication, and replacement cycle predictability.
- Residential:Mass construction optimizes for cost while luxury segments demand architectural-grade finishes and smart connectivity. Small multifamily operators resist retrofit costs despite smart lock availability, slowing category penetration in the mid-market.
- Commercial:US real estate developers face accelerated replacement cycles as jurisdictions adopt stricter NFPA 80 labeled hardware requirements for high-rise assemblies. Specification-grade buyers now unbundle hardware procurement from installation contracts.
- Industrial:Heavy-duty hardware serves manufacturing facilities where OSHA compliance and equipment protection drive specification decisions.
- Institutional:China's Ministry of Housing and Urban-Rural Development drives certified hardware procurement in urban renewal zones through green building mandates. Facilities managers in US healthcare construction hold direct relationships with specification teams.
Commercial end users generate the largest revenue base; institutional demand accelerates fastest on regulatory mandates in China and India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors global specification-grade hinge manufacturing, with Wenzhou and Ningbo clusters supplying marine-grade 316 stainless steel hardware to coastal construction projects worldwide. Regional demand patterns diverge sharply between mature retrofit markets and urbanizing economies where green building mandates accelerate replacement cycles.
United States
Commercial real estate developers in New York, Chicago, and Los Angeles accelerate smart access procurement as jurisdictions adopt stricter NFPA 80 fire door standards for high-rise assemblies. The International Building Code mandates labeled hardware tested to UL 10C, compressing product launch timelines. Specification-grade buyers in Dallas and Atlanta now unbundle hardware procurement from installation contracts, bypassing traditional distributor markups.
China
Urban renewal zones in Shanghai, Shenzhen, and Beijing drive institutional demand for certified hardware under Ministry of Housing and Urban-Rural Development green building mandates. GB standards for smart building hardware now require interoperability testing with domestic IoT platforms, forcing firmware localization. Pearl River Delta factories in Guangdong province concentrate Bluetooth-enabled mortise lock assembly for both domestic consumption and export markets.
Germany
Healthcare and hospitality construction in Munich, Hamburg, and Frankfurt specification teams demand CE-marked hardware under EN 12209 and EN 1935 performance declarations. The EU Construction Products Regulation governs fire-rated door assemblies, while ETSI cybersecurity standards for connected locks reshape R&D investment patterns. Stuttgart-based engineering clusters specialize in precision-forged brass architectural hardware for luxury residential segments.
India
PMAY-Urban affordable housing schemes in Maharashtra, Gujarat, and Karnataka generate tiered hardware demand where certified fire-rated products remain undersupplied. Bureau of Indian Standards certification requirements lag behind institutional project specifications, creating compliance gaps. Mumbai and Delhi-NCR developers increasingly specify smart mortise formats for premium multifamily towers despite mid-market resistance to retrofit costs.
Japan
Tokyo and Osaka commercial reconstruction projects prioritize earthquake-resistant door assemblies with JIS-certified heavy-duty hinges and mortise chassis. METI building efficiency standards accelerate replacement of legacy keyed systems in hospitality and corporate facilities. Nagoya industrial corridors supply precision-machined stainless steel components for both domestic specification-grade projects and export markets across Southeast Asia.
Door Hardware Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and smart connectivity integration, with specification-grade portfolios commanding sustained pricing power over builder-grade alternatives. The vendor base stratifies between electromechanical access specialists, forged brass luxury fabricators, and scale-driven steel hardware producers. Three archetypes dominate: institutional channel controllers with decades of specification relationships, luxury residential specialists with lifetime finish warranties, and emerging smart-lock pure-plays leveraging cloud-native credential platforms. Competitive moves concentrate on M&A to fill connectivity capability gaps and direct-to-developer portal launches that disintermediate traditional distribution.
Within the institutional access control tier, ASSA ABLOY and dormakaba exemplify channel dominance through specification team relationships and certified fire-rated portfolios. Among forged brass specialists, Baldwin Hardware occupies a position defined by architectural-grade finishes and luxury residential positioning. On the mass-market cylindrical lock vector, Kwikset and Yale represent scale-driven manufacturing with smart connectivity migration strategies. These named entities anchor competitive archetypes rather than exhaust market coverage.
| Leading Market Players |
|---|
| Dorma (dormakaba) |
| Baldwin Hardware |
| ASSA ABLOY |
| Emtek |
| Hager Companies |
| Allegion |
| Kwikset |
| Yale |
| Häfele |
| Others |
Supply Flow & Price Mechanics
Captive hinge manufacturing in Zhejiang and Guangdong provinces anchors both the supply position and pricing power for specification-grade stainless steel hardware, allowing integrated producers to buffer London Metal Exchange volatility while commodity-tier competitors absorb spot-market shocks. This geographic concentration forces buyers into long-term offtake arrangements or inventory risk positions that reshape total cost calculations across project bids.
Pricing Analysis
Value-based pricing anchored to fire-safety certification outcomes dominates specification-grade procurement, where UL 10C and EN 12209 compliance tiers separate premium architectural hardware from commodity builder-grade alternatives. Price differentiation rests on certification depth and smart connectivity integration, with Bluetooth-enabled mortise locks commanding sustained premiums over keyed equivalents. Pricing pressure stems from brass and zinc input volatility compressing forged hardware margins during commodity spikes. Mass residential developers exhibit acute price sensitivity, while healthcare and hospitality facilities managers prioritize life-cycle cost over upfront unit economics.
Supply Chain Analysis
Freight cost volatility from Pearl River Delta ports to North American distribution centers amplifies total landed cost swings for specification-grade hinge shipments, particularly during peak construction seasons. Supply concentrates in China, Germany, and Japan for precision-forged brass and electromechanical lock assembly, drawing from copper cathode, 316-grade stainless steel billet, and Bluetooth Low Energy semiconductor inputs. Single-source vulnerability in Zhejiang hinge manufacturing exposes buyers to port congestion shocks. Distribution runs through institutional distributor networks for specification-grade projects, while mass residential flows direct-to-developer procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over 316-grade stainless steel forging capacity and embedded firmware development determines margin sustainability. Players are pursuing backward integration into precision metalworking to defend specification-grade positioning.
For Market Incumbents: Hedge against commodity volatility through captive Zhejiang forging capacity or long-term copper cathode offtake agreements. Reinforce specification team relationships with certified fire-rated portfolio expansion under evolving NFPA 80 jurisdictions. Counter smart-lock pure-plays by embedding over-the-air firmware capability across mid-tier cylindrical formats. For New Entrants and Emerging Players: Direct-to-developer platforms for national multifamily REITs offer the lowest friction entry path, bypassing entrenched distributor relationships. Target India's PMAY-Urban affordable housing vertical where certified fire-rated hardware remains undersupplied relative to Bureau of Indian Standards compliance gaps. Lead with installation-speed value propositions rather than brand heritage. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to electromechanical access conglomerates seeking smart connectivity fill-ins. Long-term viability favors vendors with dual certification depth against both EN 12209 and GB/T 31024 standards. Watch ETSI cybersecurity standard adoption rates as inflection indicator for European connected lock margin pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive 316-grade stainless capacity insulates margins from London Metal Exchange volatility. |
| Direct-to-Developer Portal Launch | Bypasses traditional distributor markup for national multifamily REIT procurement consolidation. |
| Dual Certification Investment | EN 12209 and GB/T 31024 compliance opens specification access across European and Chinese projects. |
| Firmware Security Architecture | Penetration-tested embedded systems satisfy emerging ETSI cybersecurity mandates for connected locks. |
| Regional Inventory Positioning | US healthcare construction unbundling demands localized stock for accelerated project timelines. |
Methodological Framework
Document review covered customs trade databases, UL certification registries, and Ministry of Housing and Urban-Rural Development policy circulars, complemented by interviews with specification sales directors, facilities managers at healthcare REITs, and procurement leads at national multifamily developers. Secondary validation drew from SEC filings of listed hardware conglomerates, London Metal Exchange price histories, and building permit data from major metropolitan statistical areas. Bottom-up shipment analysis triangulated against top-down construction spending models across the projection horizon.
Cross-referencing historical replacement cycle patterns with panel input from architectural specification teams anchored the analytical framework across product type, material grade, installation complexity, and end-user regulatory exposure segmentation. CAGRs derived from installed base turnover rates and smart access penetration curves. Forecast inputs incorporated Bluetooth module cost curves, NFPA 80 adoption timelines by jurisdiction, and China's GB standard interoperability mandates.
The model holds under steady regulatory enforcement and construction permit issuance; deviation in fire code adoption speed or cybersecurity certification requirements would shift replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Door and Window Hardware Market