
 Cladding Systems Market | 2026-2036
Cladding Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cladding Systems Market Intelligence
The performance gap between advanced, multi-functional cladding systems and basic, single-purpose panels is broadening. Kingspan Group leverages its expertise in insulated panels to capture demand for energy-efficient building envelopes. Arconic Corporation specializes in high-performance aluminum composite materials for architectural applications. Compagnie de Saint-Gobain S.A. competes across multiple material categories, utilizing its vast distribution network to serve diverse construction projects globally.
Cladding systems comprise the non-load-bearing exterior skin of a building, designed to protect the internal structure from environmental elements. These systems provide critical functions including weather resistance, thermal insulation, and aesthetic finishing, often specified with fire-retardant cores. Ventilated facades and rainscreen systems represent a high-value installation method, driven by energy efficiency goals in commercial buildings. Within material types, fiber cement boards are gaining share against traditional options due to their durability and design flexibility.
Product compliance is shaped by stringent fire safety regulations, such as Europe's CE marking requirements and the EN 13501-1 classification. In parallel, standards from organizations like ASTM in the United States and national GB standards in China dictate performance criteria for weatherability and structural integrity. Navigating this complex web of regional building codes while developing materials that meet evolving sustainability and fire-resistance targets is the central challenge for manufacturers.
Market Dynamics
The market's central tension exists between the demand for cost-effective materials for mass construction, primarily in China, and the enforcement of stringent fire safety and energy efficiency regulations, such as those under the EU Green Deal.
Growth Catalysts
- Energy Retrofitting Mandates:The EU Green Deal creates demand for high-performance insulated cladding by requiring energy upgrades to existing commercial building stock.
- New Construction in China:Large urban development projects continue to drive volume demand for aluminum composite panels and fiber cement boards.
- Material Substitution:Architects are increasingly specifying fiber cement for its durability and aesthetic versatility, displacing traditional brick and stucco facades.
Market Restraints
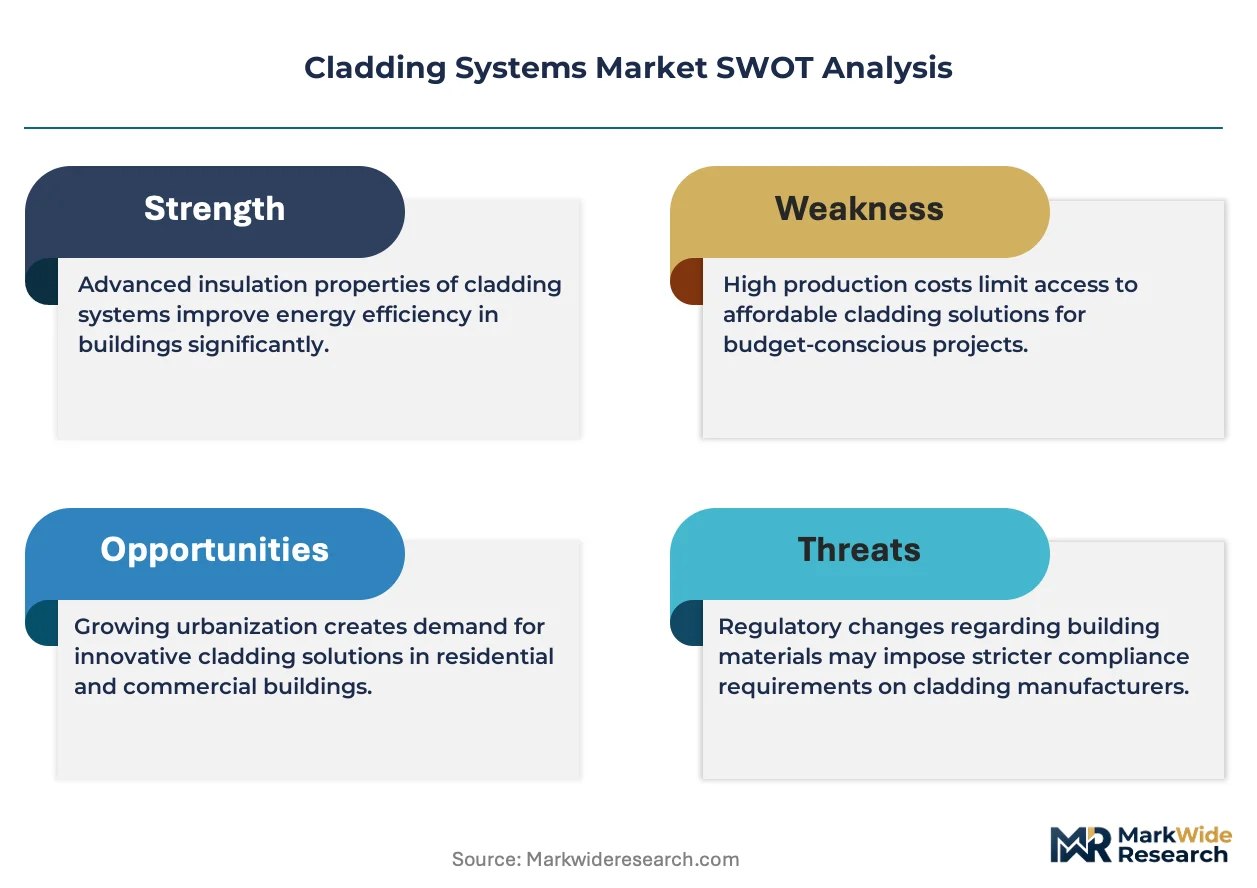
- Input Cost Volatility:Price swings in aluminum and petrochemical resins create margin pressure for panel manufacturers and uncertainty for project bids.
- Fragmented Regulations:Conflicting fire safety standards, like Europe's EN 13501-1 versus U.S. ASTM codes, increase compliance costs and limit market access.
- Threat of Substitutes:In cost-sensitive residential markets, basic finishes such as vinyl siding directly compete against higher-performance cladding systems on price.
Strategic Opportunities
- Building-Integrated Photovoltaics:Integrating solar cells into facade panels taps into demand for energy-generating building envelopes, aligning with net-zero construction goals.
- Prefabricated Systems:Developing panelized solutions for the modular construction sector addresses the need for systems that support rapid, off-site assembly.
- Mass Customization:Linking BIM models to CNC fabrication serves high-end architectural projects demanding unique, digitally manufactured facade components.
Industry Challenges
- Installer Skill Gap:A shortage of labor trained to install complex ventilated rainscreen systems delays projects, hindering adoption of these high-value systems.
- Fire-Safety Certification:The long, costly process to achieve compliance with standards like EN 13501-1 slows new material innovation.
- Retrofit Integration:Attaching modern cladding to older building substrates presents engineering challenges related to structural integrity and weatherproofing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cladding Systems Market |
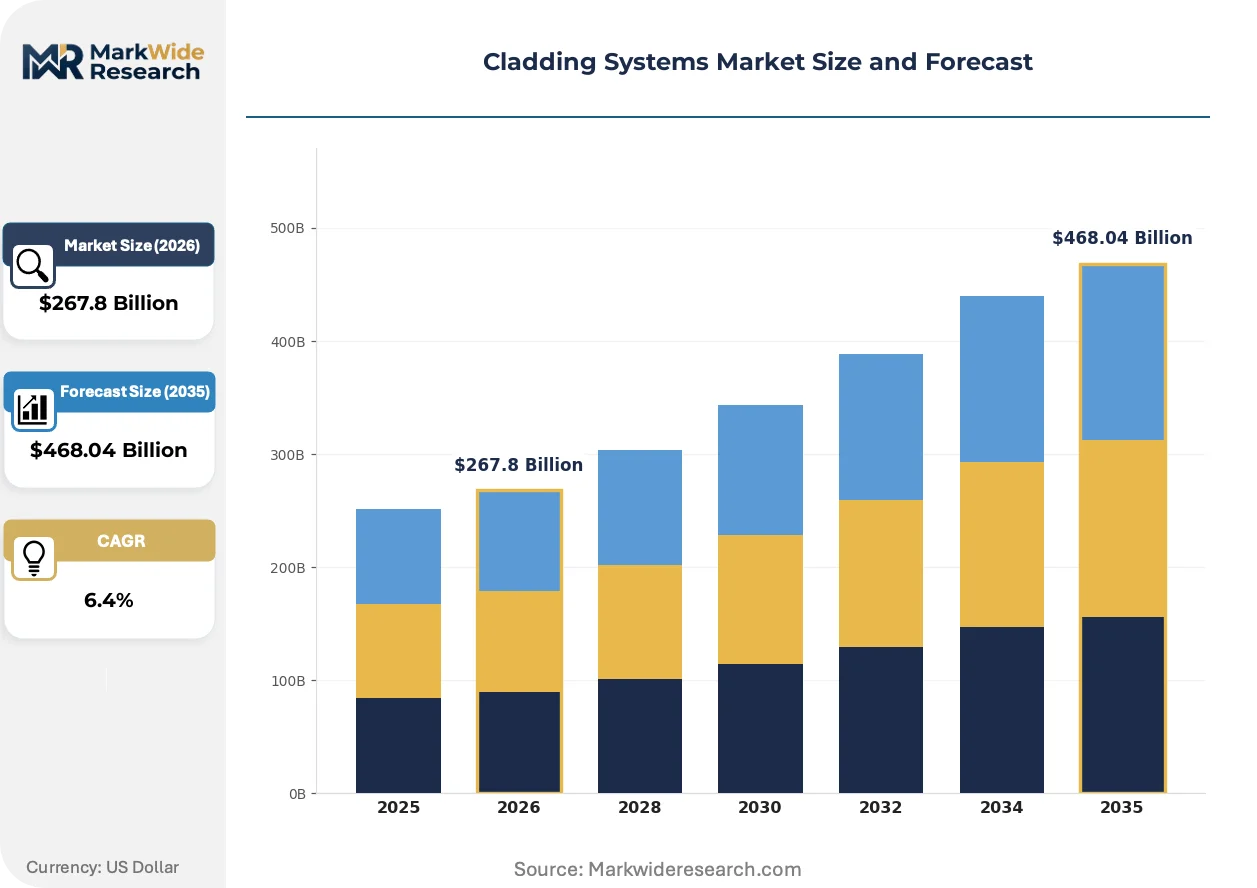
| Market Size in 2026 | $267.8 Billion |
| Market Size in 2035 | $468.04 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
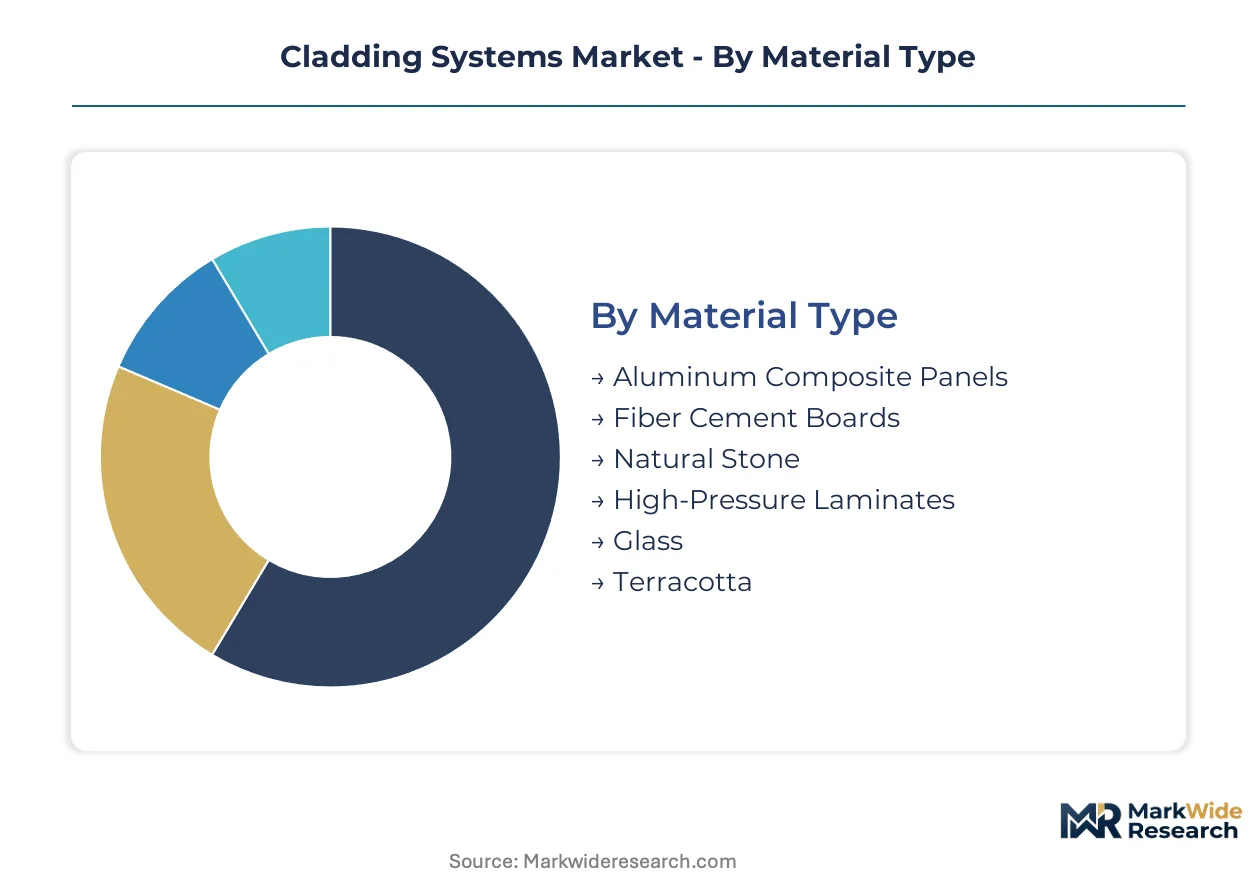
| Segmentation | Material Type: Aluminum Composite Panels, Fiber Cement Boards, Natural Stone, High-Pressure Laminates, Glass, Terracotta Application: Commercial Buildings, Institutional Facilities, Industrial Plants, Recreational Complexes, Educational Campuses, Government Structures Installation Method: Ventilated Facades, Rainscreen Systems, Stick Systems, Panelized Systems, Unitized Systems End User: Architectural Firms, General Contractors, Property Developers, Facility Management, Engineering Consultancies |
| Companies Covered | Kingspan Group, Compagnie de Saint-Gobain S.A., Etex Group, Tata Steel Limited, Arconic Corporation, Louisiana Pacific Corporation, James Hardie Industries PLC, Westlake Chemicals, Nichiha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cladding Systems Market Strategic Shifts & Innovations
Product evolution is reshaping cladding from a passive barrier into an active, multi-functional building envelope component. This shift is driven by digital design tools and tightening sustainability mandates that demand higher performance from every part of the building skin.
Digital twinning through Building Information Modeling (BIM) provides a virtual prototype for analyzing a facade's performance. Architectural and engineering firms are increasingly adopting this for complex commercial projects before construction begins. Integrating BIM data with factory equipment is automating the bespoke fabrication of high-tolerance panels, reducing waste.
China's national "dual carbon" objectives are directly influencing its GB standards for building materials, pushing for greater energy efficiency. This compels manufacturers to increase panel thermal resistance and document embodied carbon. The policy's impact is pronounced in the high-rise commercial sector, where new specifications prioritize lifecycle performance.
A notable shift from component-based sales to specifying complete, warranted envelope systems is underway. This model challenges distributors as it favors manufacturers who guarantee system-wide performance. This trend is most visible in Europe's commercial retrofitting market, where performance contracts depend on the entire wall assembly.
Cladding Systems Market Segmentation
Understanding the varied requirements across different building types and regulatory landscapes is crucial for navigating the Cladding Systems Market. This segmentation highlights how material properties, installation complexities, and end-user demands shape product development and market penetration strategies.
Material Type:
Compliance with fire safety regulations like EN 13501-1 and ASTM standards heavily influences material selection within this category.
- Aluminum Composite Panels:These panels feature two aluminum sheets bonded to a non-aluminum core, offering a lightweight yet rigid solution for exterior facades. Demand from large urban development projects in China drives significant volume for these versatile panels.
- Fiber Cement Boards:Composed of cement, cellulose fibers, and sand, these boards provide durability, fire resistance, and design flexibility, often displacing traditional stucco. Architects increasingly specify fiber cement for its aesthetic versatility and long lifespan in commercial and residential applications.
- Natural Stone:Sourced directly from quarries, natural stone offers premium aesthetics and exceptional longevity for high-end architectural projects.
- High-Pressure Laminates:These panels consist of cellulose fibers impregnated with resins and pressed under high pressure, valued for their durability and decorative finishes.
- Glass:Utilized for curtain walls and structural glazing, glass provides transparency and modern aesthetics, often integrated with advanced thermal performance features.
- Terracotta:Baked clay panels offer a natural, earthy aesthetic and excellent thermal mass, frequently chosen for their sustainable attributes and classic appearance.
Leading the category by volume: Aluminum Composite Panels. Growing fastest: Fiber Cement Boards.
Application:
The economic viability and long-term performance requirements differentiate cladding solutions across various application tiers.
- Commercial Buildings:This segment includes office towers, retail complexes, and hotels, demanding high-performance, aesthetically appealing, and energy-efficient cladding systems. Retrofitting mandates under the EU Green Deal are driving significant demand for insulated solutions in this sector.
- Institutional Facilities:Encompassing hospitals, universities, and cultural centers, this application prioritizes durability, specific safety standards, and long-term maintenance characteristics. These facilities often require specialized fire-retardant cores and robust weather resistance.
- Industrial Plants:Cladding for industrial facilities focuses on protection from harsh environments, corrosion resistance, and cost-effectiveness.
- Recreational Complexes:These venues, such as sports arenas and entertainment centers, require visually striking and durable cladding that can withstand heavy public use.
- Educational Campuses:Schools and universities specify cladding for its longevity, thermal insulation, and ability to create safe, comfortable learning environments.
- Government Structures:Public buildings require cladding that meets stringent security, fire safety, and aesthetic standards, often with a focus on long-term public investment.
Commercial Buildings command the largest share. Educational Campuses show expanding demand.
Installation Method:
The technical complexity and specialized labor requirements vary significantly across different installation methodologies.
- Ventilated Facades:These systems create an air gap between the cladding and the building's insulation, enhancing thermal performance and moisture management. The energy efficiency goals in commercial buildings drive high-value installations of these advanced systems.
- Rainscreen Systems:Designed to protect the building structure from water penetration by managing rainwater drainage and air pressure equalization within a cavity. These systems are critical for weather resistance and increasingly specified in high-performance building envelopes.
- Stick Systems:Components like mullions and transoms are assembled piece by piece on-site, offering flexibility for complex designs but requiring extensive field labor.
- Panelized Systems:Large sections of cladding are prefabricated off-site and then transported for rapid assembly on the building structure. This method supports faster construction timelines and modular building approaches.
- Unitized Systems:Entire facade units, complete with glazing and frames, are assembled in a factory and then lifted into place on the building. This method offers superior quality control and accelerated installation.
Ventilated Facades capture premium projects. Panelized Systems exhibit rapid growth.
End User:
Each end-user group exerts distinct influence on material specification and project execution.
- Architectural Firms:These firms are responsible for conceptual design, material specification, and aesthetic integration of cladding systems into overall building plans. Their choices are driven by design intent and performance criteria.
- General Contractors:Tasked with project execution and construction management, general contractors oversee the procurement and installation of cladding systems. Their focus is on cost-effectiveness, schedule adherence, and quality control.
- Property Developers:These entities initiate and finance construction projects, influencing cladding decisions based on market appeal, investment return, and long-term asset value.
- Facility Management:Responsible for the ongoing operation and maintenance of buildings, facility managers consider durability, ease of repair, and energy performance when evaluating cladding systems.
- Engineering Consultancies:These specialists provide technical expertise on structural integrity, thermal performance, and regulatory compliance for complex cladding designs.
General Contractors represent the largest purchasing volume. Property Developers drive specification innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's rapid urban expansion drives significant demand for advanced cladding systems. The city's extensive commercial and residential high-rise development projects require durable and aesthetically pleasing building envelopes. This concentration of construction activity positions China as a critical hub for cladding material consumption.
China
Large urban development projects and the high-rise commercial sector generate substantial demand for cladding materials. China's "dual carbon" objectives influence GB standards for building materials, pushing for greater energy efficiency. The Yangtze River Delta region focuses on increasing panel thermal resistance and documenting embodied carbon in new construction.
Germany
Commercial retrofitting mandates under the EU Green Deal create demand for high-performance insulated cladding solutions. CE marking requirements and EN 13501-1 classification shape material selection for fire safety. Frankfurt's financial district actively implements advanced ventilated facades to meet stringent energy performance targets.
United States
New commercial building construction and architectural applications drive consistent demand for diverse cladding systems. ASTM standards dictate performance criteria for weatherability and structural integrity across various material types. New York City's commercial real estate market specifies high-performance aluminum composite materials for iconic structures.
India
Rapid infrastructure development and a growing commercial sector fuel demand for cost-effective and durable cladding. National building codes emphasize fire safety and structural stability for multi-story residential and commercial projects. Mumbai's metropolitan area witnesses increased use of fiber cement boards for their durability and design flexibility in urban developments.
Cladding Systems Market Key Industry Players
Premium-margin players sit above commodity-margin players across product sophistication and technical support. The market exhibits a tiered structure, from highly specialized providers of advanced systems to large-volume manufacturers of basic panels. Strategic archetypes include innovation-driven specialists, diversified material suppliers, and regional cost leaders. Companies pursue portfolio diversification and strategic partnerships to strengthen their market positions.
Within the innovation-driven specialist tier, Kingspan Group exemplifies expertise in insulated panels, catering to demand for energy-efficient building envelopes. Arconic Corporation, a US-based entity, represents manufacturers focused on high-performance aluminum composite materials for architectural applications. Compagnie de Saint-Gobain S.A., a French public limited company, sits within the diversified material supplier archetype, leveraging its extensive distribution network for various construction projects.
| Leading Market Players |
|---|
| Kingspan Group |
| Compagnie de Saint-Gobain S.A. |
| Etex Group |
| Tata Steel Limited |
| Arconic Corporation |
| Louisiana Pacific Corporation |
| James Hardie Industries PLC |
| Westlake Chemicals |
| Nichiha Corporation |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's stringent energy performance mandates gate qualified supply and drive premium-tier pricing access for advanced cladding systems. This regulatory push elevates the cost structure for compliant materials and installation methods across European markets.
Pricing Analysis
Outcome-based pricing anchors high-performance cladding systems, where value is tied to long-term energy savings and structural integrity. Price differentiation stems from CE marking certification levels, customization for complex architectural designs, and bundled after-sales performance contracts. Pricing softness affects basic, single-purpose panels due to intense competition and input cost volatility. Residential markets exhibit the highest price sensitivity, often opting for basic finishes over advanced cladding systems.
Supply Chain Analysis
Aluminum and petrochemical resin supply largely rests on global commodity markets, introducing significant input cost volatility for panel manufacturers. Geographic supply concentration for high-volume materials like aluminum composite panels centers heavily in China. A structural risk involves logistics chokepoints and trade policy shifts affecting raw material imports. Distribution of advanced cladding systems increasingly runs through manufacturers who offer complete, warranted envelope solutions rather than component-based sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cladding Systems Market is evolving into a vertical-integration race, with players pursuing upstream control over material production and downstream ownership of installation capabilities.
For Market Incumbents: To counter fragmented regulations and the installer skill gap, incumbents must invest in comprehensive fire-safety certification for new material formulations. Expanding prefabrication capabilities and acquiring specialized installation firms will streamline project delivery and ensure quality control. Prioritizing R&D for multi-functional, energy-generating building envelopes will secure premium market positioning.
For New Entrants and Emerging Players: Capture demand for specialized, high-performance cladding solutions in niche applications like building-integrated photovoltaics. Target the modular construction sector by developing panelized systems that support rapid, off-site assembly. A go-to-market angle focused on digital design integration and rapid installation methodologies will differentiate offerings from established players.
For Investors and Strategic Acquirers: Increased adoption of fully warranted envelope systems is the leading indicator that market consolidation around performance-driven solutions is accelerating. Long-term viability hinges on companies capable of navigating complex regulatory landscapes and delivering integrated, sustainable solutions. Target acquisition archetypes include specialists in advanced material science, prefabrication technologies, or high-value rainscreen installation. A small set of named triggers warrants ongoing watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reducing embodied carbon in fiber cement boards aligns with China's dual carbon objectives. |
| Capacity Expansion for Prefabrication | Scaling panelized system production supports rapid assembly for commercial buildings. |
| Long-term Raw Material Supply Agreements | Mitigating input cost volatility for aluminum and petrochemical resins stabilizes margins. |
| Joint Ventures with Installation Specialists | Addressing the installer skill gap accelerates adoption of complex ventilated facades. |
| Product Launch for Building-Integrated Photovoltaics | Tapping into demand for energy-generating facades aligns with net-zero construction goals. |
Research Approach
Independent corroboration across industry interviews, building codes, and company reports underwrites the qualitative findings and quantitative market sizing. Primary research involved discussions with architectural firms, general contractors, property developers, and facility management professionals. Secondary sources included EU Green Deal policy documents, ASTM standards, China's GB standards, and relevant trade publications, ensuring a robust bottom-up and top-down triangulation.
Rate-of-change decomposition informed the market's trajectory over the projection horizon. The analytical framework segmented the market by material type, application, installation method, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data analysis and projected future trends, incorporating factors like new construction activity in China and energy retrofitting mandates in Germany.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to global economic shifts and material innovation cycles. Forecasts reflect assumptions documented regarding regulatory enforcement and technological advancements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Precast Concrete Manufacturing Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
North America Oriented Strand Board Market