
 Articulated Concrete Block Mattresses Market | 2026-2036
Articulated Concrete Block Mattresses Market Size, Share, and Industry Trends Forecast 2026-2036
Articulated Concrete Block Mattresses Market Insights
Geosynthetic-composite integration is tilting fabrication methods toward hybrid concrete-polymer systems that improve flexural durability under tidal loading. Officine Maccaferri S.p.A. leverages its geotechnical heritage to anchor European supply for marine deployment projects. WASKEY dominates North American infrastructure bids through in-house production of precast segments. ACE Geosynthetics competes across Asia-Pacific with specialized modular mattresses engineered for tropical cyclone zones.
Articulated concrete block mattresses consist of interlocking precast concrete units joined by flexible cables or geosynthetic tendons, typically cast from high-strength Portland cement concrete with compressive ratings exceeding 35 MPa to withstand hydraulic shear stress. These systems function as flexible armor layers that conform to subgrade settlement while dissipating wave energy and preventing scour. Erosion control applications lead volume demand due to recurring federal and state channel maintenance budgets, while coastal stabilization represents the fastest-expanding segment as sea-level adaptation funding accelerates. Modular mattresses command premium positioning where rapid marine installation reduces labor exposure in intertidal zones.
FEMA floodplain construction standards and USACE coastal engineering manuals shape product certification requirements for federal procurement eligibility. Australia's national construction code and state-level coastal management acts mandate performance testing for public shoreline works. Stakeholders must monitor evolving resiliency bond frameworks and green infrastructure incentives that increasingly specify nature-integrated hard armor solutions.
Market Dynamics
FEMA floodplain construction standards and USACE coastal engineering manuals are tightening certification requirements for federal procurement eligibility, compressing supplier qualification timelines while elevating technical performance thresholds for wave energy dissipation systems.
Growth Catalysts
- Stormwater Management Mandates:EPA regulations governing erosion control installations are elevating material specifications for hydraulic infrastructure, directing procurement toward certified articulated block systems.
- Cyclone Resilience Programs:Queensland's state-level coastal management acts are accelerating deployment of reinforced block mattresses across Australia's eastern seaboard.
- Sea-Level Adaptation Funding:Federal channel maintenance budgets are expanding allocations for flexible armor layers in intertidal stabilization projects.
Market Restraints
- Portland Cement Cost Volatility:Input price fluctuations for high-strength concrete formulations exceeding 35 MPa compressive ratings compress fabrication margins.
- Geographic Supply Concentration:North American production gravity centers on in-house precast segment manufacturers, limiting third-party sourcing flexibility.
- Geosynthetic-Polymer Integration Complexity:Hybrid fabrication methods require specialized tendon-casting equipment that constrains rapid capacity expansion.
Strategic Opportunities
- Green Infrastructure Incentives:Emerging resiliency bond frameworks are specifying nature-integrated hard armor solutions for shoreline defense contracts.
- Modular Installation Channels:Rapid marine deployment methods reducing labor exposure in tidal zones are opening premium positioning for pre-assembled mattress systems.
- Geosynthetic-Composite Convergence:Integration of flexible cables with high-strength concrete units is creating differentiated product lines for tropical cyclone zones.
Industry Challenges
- Subgrade Settlement Engineering:Conformance design for flexible armor layers demands specialized geotechnical assessment capabilities that strain technical staffing.
- Federal Certification Timelines:USACE coastal engineering manual compliance documentation extends qualification periods for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Articulated Concrete Block Mattresses Market |
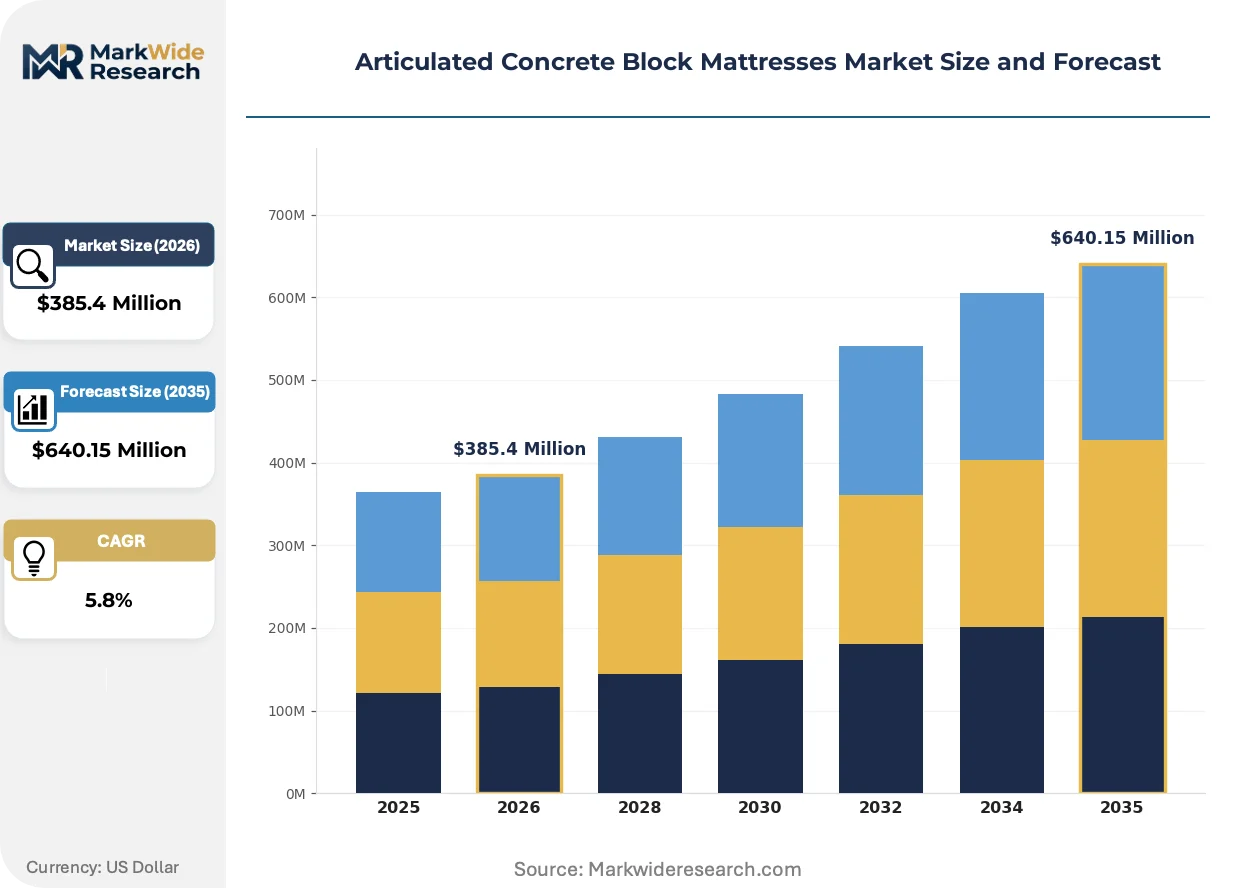
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Units, Reinforced Blocks, Modular Mattresses, Precast Segments Application: Erosion Control, Riverbank Protection, Coastal Stabilization, Slope Stabilization Installation Method: Marine Deployment, Roadside Placement, Dam Reinforcement, Canal Lining End User: Hydropower Facilities, Construction Contractors, Infrastructure Builders, Coastal Agencies |
| Companies Covered | Terraquavie, Permatile Concrete Products Co., Officine Maccaferri S.p.A., THE SHAW GROUP, Australian Concrete Posts Pty Ltd., Subsea Protection Systems, WASKEY, ACE Geosynthetics, Pipeshield, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Articulated Concrete Block Mattresses Market Trends and Innovations
Fabrication methods for coastal defense systems are pivoting toward hybrid material architectures that merge structural concrete with polymer flexibility, reshaping how suppliers engineer wave energy dissipation.
Geosynthetic-composite articulated block technology is migrating from pure concrete casting toward integrated tendon systems. Coastal agencies in the United States are expanding deployment of these hybrid mattresses for shoreline defense at accelerated procurement cycles. This migration from monolithic to flexible-conforming systems is compressing traditional rigid armor market share while elevating technical performance requirements for subgrade adaptation.
The EPA's stormwater management mandates are tightening material specifications for erosion control installations, elevating certification thresholds for federal procurement eligibility. Manufacturers must now document compressive ratings and hydraulic shear resistance through standardized performance testing. Erosion control applications face the most acute compliance pressure, with suppliers accelerating laboratory validation protocols to maintain bidding status.
Coastal stabilization buyers are consolidating procurement authority around rapid-installation capabilities that reduce intertidal labor exposure. State-level coastal management acts in cyclone-prone regions are displacing fragmented municipal purchasing with centralized resilience program administration. Queensland's coastline exhibits this concentration most visibly, where cyclone resilience programs now drive bulk procurement of reinforced block systems through single-source contracting vehicles.
Articulated Concrete Block Mattresses Market Segmentation
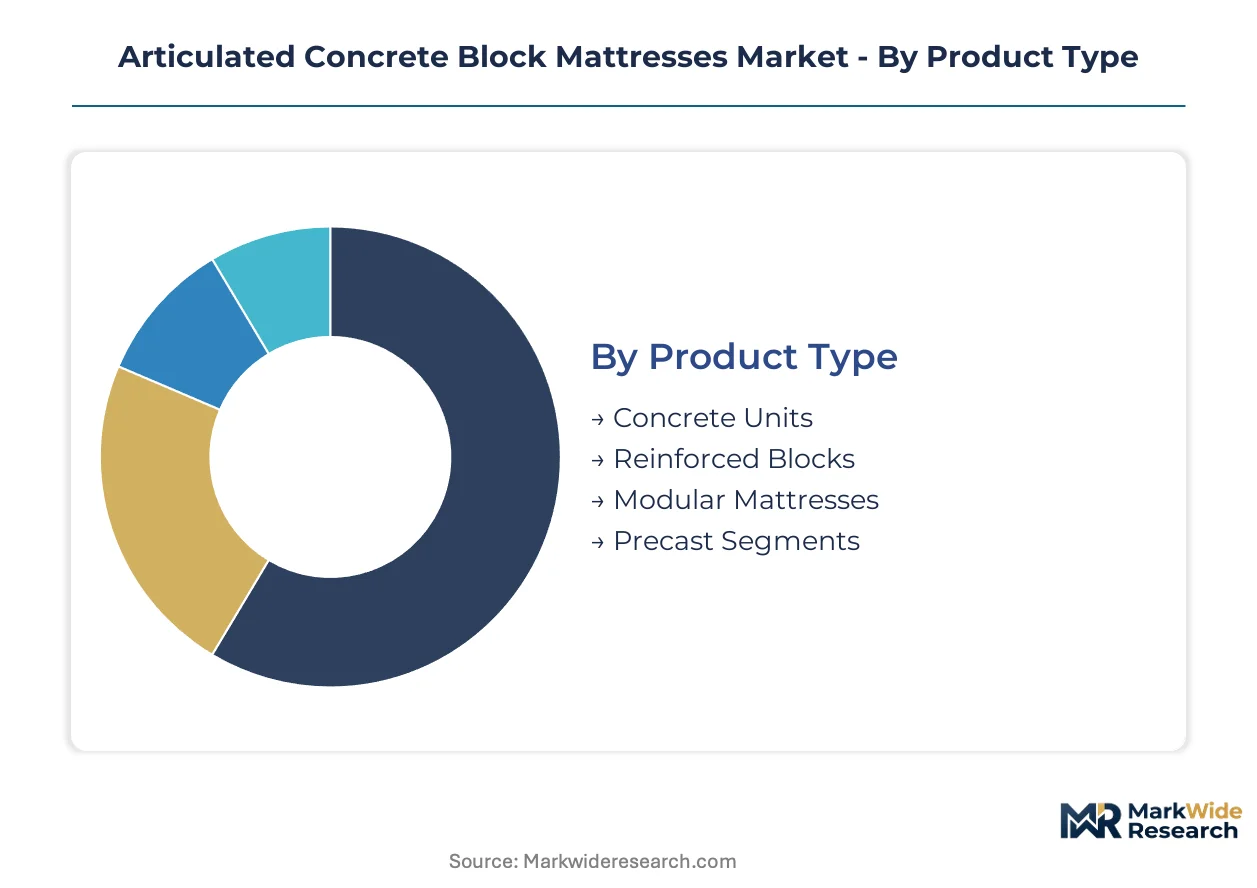
Segmentation in the articulated concrete block mattresses market reveals how technical specifications, deployment environments, and procurement authority shape supplier positioning. Product architecture and installation constraints determine which fabricators capture volume versus premium margins.
Product Type:
Mature casting technologies dominate volume production, while emerging hybrid systems are capturing specification upgrades in high-stress marine environments.
- Concrete Units:Standard Portland cement formulations with compressive ratings above 35 MPa serve baseline erosion control contracts. Federal channel maintenance programs in the United States concentrate procurement here, though EPA stormwater compliance documentation now extends qualification timelines.
- Modular Mattresses:Pre-assembled cable-linked systems reduce intertidal labor exposure during marine deployment. Queensland's cyclone resilience programs are accelerating specification of these units across Australia's eastern seaboard, where rapid shoreline defense installation carries premium positioning.
- Reinforced Blocks:Geosynthetic-tendon integration improves flexural durability under tidal loading cycles.
- Precast Segments:Factory-cast units with standardized dimensions streamline USACE-compliant project delivery.
Concrete Units handles the majority of throughput; Modular Mattresses is the fastest mover on share.
Application:
Cost tier stratification separates recurring maintenance budgets from capital-intensive coastal adaptation projects.
- Erosion Control:Channel lining and scour protection applications lead volume demand through recurring federal and state maintenance allocations. FEMA floodplain construction standards shape certification requirements, compressing supplier qualification timelines while elevating technical performance thresholds.
- Coastal Stabilization:Sea-level adaptation funding is accelerating deployment of flexible armor layers that conform to subgrade settlement. State-level coastal management acts in cyclone-prone regions are consolidating procurement authority around rapid-installation capabilities.
- Riverbank Protection:Inland waterway stabilization contracts emphasize hydraulic shear resistance specifications.
- Slope Stabilization:Transportation corridor and dam embankment applications require conformance design for settlement accommodation.
Erosion Control commands the largest installed base; Coastal Stabilization is expanding most quickly as resiliency bond frameworks specify nature-integrated hard armor solutions.
Installation Method:
Customer type differentiation separates specialized marine contractors from general civil engineering firms on technical capability requirements.
- Marine Deployment:Intertidal zone installation demands specialized tendon-casting equipment and rapid-assembly protocols. Coastal agencies in the United States are expanding procurement of pre-assembled systems that reduce labor exposure in tidal environments.
- Dam Reinforcement:Hydropower facility upgrades require performance testing documentation under Australia's national construction code and state-level public works mandates.
- Roadside Placement:Transportation infrastructure erosion control follows standardized federal procurement channels.
- Canal Lining:Irrigation and drainage channel maintenance contracts emphasize compressive rating certification.
Marine Deployment absorbs the highest contract values; Dam Reinforcement is climbing the fastest as hydropower resilience investments accelerate.
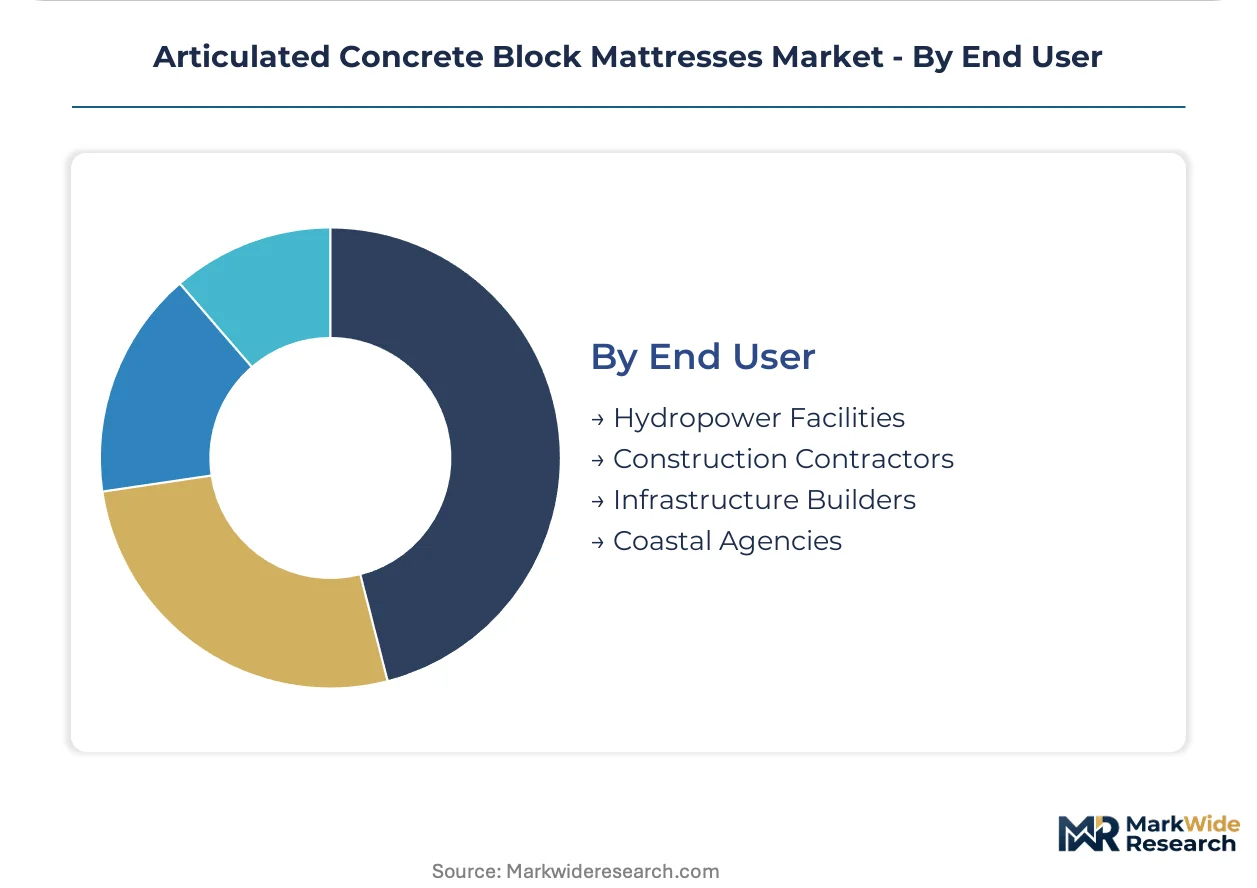
End User:
Volume concentration patterns reflect how procurement authority centralizes around federal agencies versus fragments across municipal contracts.
- Coastal Agencies:State-level resilience programs in Queensland and U.S. federal shoreline defense initiatives are consolidating bulk procurement through single-source contracting vehicles. These entities specify hybrid concrete-polymer systems for tropical cyclone zone performance.
- Construction Contractors:Private-sector infrastructure builders bid on USACE coastal engineering manual-compliant projects, facing compressed margins from Portland cement cost volatility.
- Hydropower Facilities:Utility-owned dam operators prioritize long-term scour protection with documented hydraulic shear resistance.
- Infrastructure Builders:General civil engineering firms compete on standardized erosion control installations with shorter qualification cycles.
Coastal Agencies direct the largest procurement volumes; Hydropower Facilities is gaining share fastest as climate adaptation funding flows to water infrastructure resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal agencies and hydropower utilities concentrate procurement authority in cyclone-prone shorelines and federal channel maintenance corridors. State-level resilience programs and stormwater mandates reshape where manufacturers anchor production capacity.
United States
FEMA floodplain construction standards and USACE coastal engineering manuals drive federal procurement eligibility for shoreline defense contracts. EPA stormwater management mandates tighten material specifications for erosion control installations in coastal counties. Gulf Coast state agencies expand deployment of modular mattresses for rapid marine installation in intertidal zones.
Australia
Queensland's cyclone resilience programs accelerate bulk procurement of reinforced block systems across the eastern seaboard. Australia's national construction code and state-level coastal management acts mandate performance testing for public shoreline works. Gold Coast municipal authorities consolidate fragmented purchasing into centralized resilience program administration.
Italy
Offshore marine infrastructure and Mediterranean port expansion sustain demand for geosynthetic-composite systems with flexural durability. EU Green Deal coastal adaptation funding channels investment toward nature-integrated hard armor solutions. Venice lagoon restoration projects exemplify specification of hybrid concrete-polymer mattresses for tidal loading environments.
United Kingdom
Environment Agency flood defense allocations prioritize flexible armor layers for riverbank and estuarine stabilization. UK coastal erosion management frameworks specify rapid-installation capabilities to reduce intertidal labor exposure. Scottish coastal protection schemes concentrate procurement of pre-assembled cable-linked systems in North Sea storm corridors.
China
Yangtze River Delta port authorities and South China Sea island infrastructure drive specification of high-strength concrete units exceeding 35 MPa compressive ratings. MEE water conservancy standards and dual carbon goals elevate technical thresholds for hydraulic infrastructure materials. Guangdong provincial water resources bureaus expand channel lining contracts with standardized precast segment requirements.
Articulated Concrete Block Mattresses Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Federal certification requirements compress supplier qualification timelines while elevating technical performance thresholds for wave energy dissipation. Three archetypes dominate: vertically integrated precast manufacturers with in-house tendon-casting capacity, geotechnical heritage firms leveraging polymer-concrete hybrid expertise, and regional specialists capturing state-level resilience program contracts. Dominant competitive moves include backward integration into captive supply of high-strength Portland cement formulations and strategic partnerships with marine installation contractors.
Among European geotechnical fabricators, Officine Maccaferri S.p.A. anchors supply for marine deployment projects through its heritage in flexible cable-tendon systems. WASKEY exemplifies the North American vertically integrated archetype with in-house production of precast segments for USACE-compliant infrastructure bids. ACE Geosynthetics occupies a position within the Asia-Pacific specialist tier, representing modular mattress engineering adapted for tropical cyclone zone performance requirements.
| Leading Market Players |
|---|
| Terraquavie |
| Permatile Concrete Products Co. |
| Officine Maccaferri S.p.A. |
| THE SHAW GROUP |
| Australian Concrete Posts Pty Ltd. |
| Subsea Protection Systems |
| WASKEY |
| ACE Geosynthetics |
| Pipeshield |
| Others |
Pricing and Supply Chain Analysis
Portland cement supply concentration in China, Vietnam, and Indonesia anchors input cost volatility for high-strength concrete formulations exceeding 35 MPa, compressing fabrication margins for modular mattress producers while concentrating pricing power with vertically integrated precast manufacturers holding captive supply agreements.
Pricing Analysis
Cost-plus contracts indexed to Portland cement futures and geosynthetic tendon spot markets dominate federal procurement channels. Three-tier pricing structure across USACE-certified premium, state-compliant standard, and municipal economy levels separates specification grades. Price differentiation hinges on compressive rating certification and rapid-installation bundling. Cost compression in economy-tier channel lining contracts is intensifying because of EPA stormwater compliance documentation extensions. Municipal erosion control buyers exhibit highest price sensitivity; cyclone resilience program administrators in Queensland demonstrate lowest sensitivity due to centralized single-source contracting.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from geosynthetic tendon suppliers are stabilizing working capital for precast segment fabricators. Production gravity centers on the United States, Australia, and China, with the latter drawing from captive high-alumina cement reserves. Raw material dependencies rest on Portland cement clinker, polypropylene geosynthetic fibers, and galvanized steel cables. Single-source vulnerability in specialized tendon-casting equipment constrains rapid capacity expansion. Distribution runs through marine installation contractors for intertidal deployment and civil engineering firms for inland channel maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The articulated concrete block mattresses market is approaching a platform-economics inflection as hybrid concrete-polymer systems create interoperability standards between geosynthetic suppliers and precast fabricators, consolidating procurement around integrated specification ecosystems rather than discrete component sourcing.
For Market Incumbents: Insulate federal certification status by accelerating USACE coastal engineering manual compliance documentation and deepening backward integration into captive Portland cement formulation capacity. WASKEY's in-house precast segment production and Officine Maccaferri's geotechnical heritage demonstrate how vertical integration defends against emerging hybrid-system specialists. Threat substitution from nature-based shoreline solutions demands R&D investment in bio-integrated hard armor interfaces. For New Entrants and Emerging Players: Mid-market state resilience programs in cyclone-prone U.S. Gulf Coast counties represent the most penetrable entry point, where fragmented municipal purchasing lacks centralized specification authority. Queensland's single-source contracting vehicles are displacing smaller fabricators, creating white-space for specialized marine installation partnerships. Go-to-market execution should anchor on rapid-deployment capability demonstrations that reduce intertidal labor exposure. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated precast manufacturers with in-house tendon-casting capacity and established USACE certification pipelines. Long-term viability across the 5-10 year window hinges on positioning for sea-level adaptation funding acceleration and green infrastructure incentive eligibility. The signal to watch is consolidation of state-level coastal management act procurement authority around rapid-installation specification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Portland Cement Supply | Captive high-strength formulation capacity insulates margin compression from Chinese clinker price volatility. |
| Geosynthetic-Composite Product Line Expansion | Hybrid tendon-casting capabilities capture Queensland cyclone resilience program premium positioning. |
| USACE Certification Fast-Track Investment | Accelerated federal procurement eligibility compresses competitor qualification timelines for channel maintenance contracts. |
| Marine Installation Contractor Partnerships | Pre-assembled mattress bundling reduces intertidal labor exposure and opens premium rapid-deployment pricing. |
| Nature-Integrated Hard Armor R&D Program | Green infrastructure incentive alignment positions for emerging resiliency bond framework specifications. |
Research Methodology
Desk research of USACE coastal engineering manuals, EPA stormwater management technical guidance, and Australian national construction code amendments preceded structured interviews with precast manufacturing plant managers, marine installation contractors, state coastal agency procurement officers, and geosynthetic supplier technical directors. Secondary validation drew from FEMA floodplain construction standards documentation, Queensland state coastal management act filings, and customs trade data for Portland cement and geosynthetic fiber imports. Bottom-up project pipeline assessments and top-down federal channel maintenance budget allocations were triangulated to establish market sizing.
Assumptions held fixed include prevailing FEMA and USACE certification requirements, EPA stormwater mandate enforcement intensity, and cyclone resilience program funding continuity across state budgets; variables included Portland cement cost trajectories, geosynthetic-polymer integration adoption rates, and consolidation pace of municipal procurement authority. The analytical framework modeled product type, application, installation method, and end user segmentation dimensions across the projection horizon. CAGRs were derived from weighted average of historical federal maintenance allocation trends and forward-projected sea-level adaptation funding flows, with hydraulic infrastructure resilience investment cycles as a key industry-specific input.
Macroeconomic conditions sit as an overlay; deviation in construction material input costs, federal infrastructure appropriation levels, or coastal storm frequency would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Plastic Roofing Tiles Market