
 Global Nordic Building Automation and Control Market | 2026-2036
Global Nordic Building Automation and Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nordic Building Automation and Control Market Outlook
Sweden is tilting toward advanced building automation manufacturing as Nordic energy retrofit mandates intensify. Siemens AG leverages its industrial automation heritage to anchor large-scale commercial deployments across Scandinavian capitals. Caverion Corporation competes through integrated service contracts that bundle installation with long-term maintenance. Honeywell differentiates via cloud-based energy management platforms tailored to Nordic climate conditions.
Nordic building automation and control encompasses integrated systems that regulate HVAC, lighting, security, and energy consumption through wired, wireless, IoT, and cloud-based technologies operating across BACnet, Modbus, and proprietary protocols. These systems reduce operational energy expenditure in commercial and institutional structures subject to subarctic heating loads and extended seasonal darkness. HVAC Control dominates product type revenue due to thermal regulation intensity in Nordic climates, while IoT and Cloud-Based technology segments capture expanding margin pools as remote diagnostics replace on-site service calls. Energy Management applications are accelerating fastest among public sector clients facing mandatory carbon disclosure requirements.
EU Green Deal frameworks, national implementations of the Energy Performance of Buildings Directive, and country-specific building codes enforced by national energy agencies collectively shape product certification pathways and procurement specifications across Denmark, Sweden, Norway, and Finland. CE marking under EU harmonized standards remains mandatory for system components, while national regulators layer additional efficiency thresholds for publicly funded construction. Stakeholders must monitor divergence between EU-wide standardization momentum and emerging national preferences for domestic supplier qualification in public tenders.
Market Dynamics
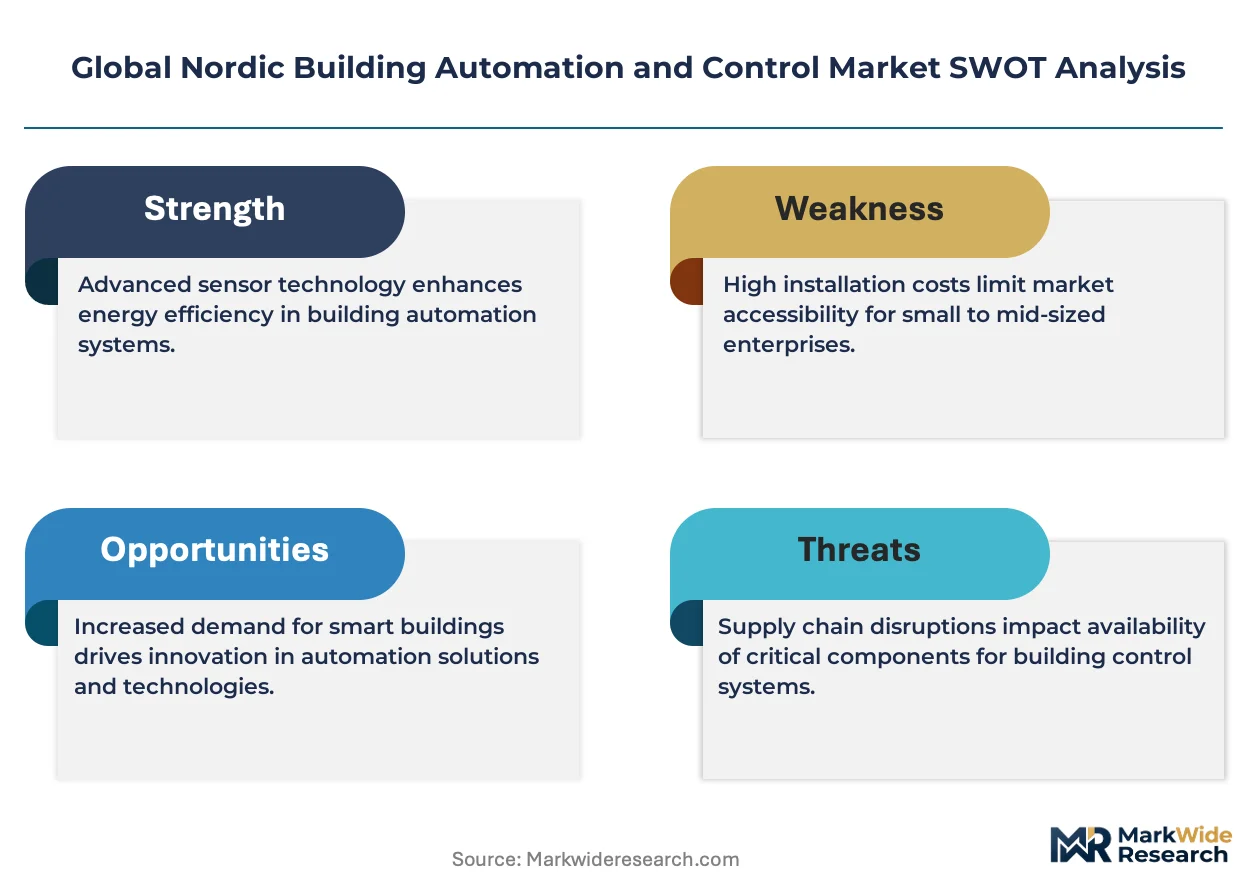
The Nordic building automation sector is compressing around EU Green Deal compliance deadlines that mandate building performance disclosure and retrofit acceleration across Denmark, Sweden, Norway, and Finland.
Growth Catalysts
- Energy Performance of Buildings Directive:National implementations across Denmark and Sweden mandate automated energy monitoring in commercial structures above specific floor thresholds, forcing control system procurement.
- Subarctic heating intensity:Extended heating seasons in Stockholm-Uppsala and Greater Copenhagen corridors concentrate HVAC control demand in high-density commercial portfolios.
- IoT sensor proliferation:Wireless temperature, occupancy, and air quality sensors enable granular zone control without structural retrofit, accelerating deployment in aging Nordic building stock.
Market Restraints
- Specialized technician scarcity:BACnet and Modbus protocol expertise concentrates in Stockholm and Copenhagen labor pools, constraining installation velocity in peripheral Finnish and Norwegian markets.
- Component import dependency:Cloud infrastructure and edge computing hardware rely on non-Nordic semiconductor supply chains, exposing lead time volatility.
- Legacy system lock-in:Proprietary protocols from 1990s installations resist standard interoperability, fragmenting upgrade pathways in institutional buildings.
Strategic Opportunities
- Finnish public sector retrofits:Municipal building portfolios in Helsinki-Tampere corridor face mandatory carbon disclosure by 2027, creating white space for integrated energy management platforms.
- Predictive maintenance convergence:Machine learning diagnostics layered atop cloud-based building management systems compress service call frequency and extend contract durations.
- Swedish green procurement incentives:Public tender scoring favors domestic supplier qualification and lifecycle carbon metrics, rewarding localized service bundling.
Industry Challenges
- Cybersecurity certification complexity:IEC 62443 compliance timelines for industrial control systems lag product development cycles, delaying commercial release of connected building platforms.
- Interoperability testing overhead:Multi-protocol integration across BACnet, Modbus, and proprietary legacy systems demands extended commissioning periods that strain project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nordic Building Automation and Control Market |
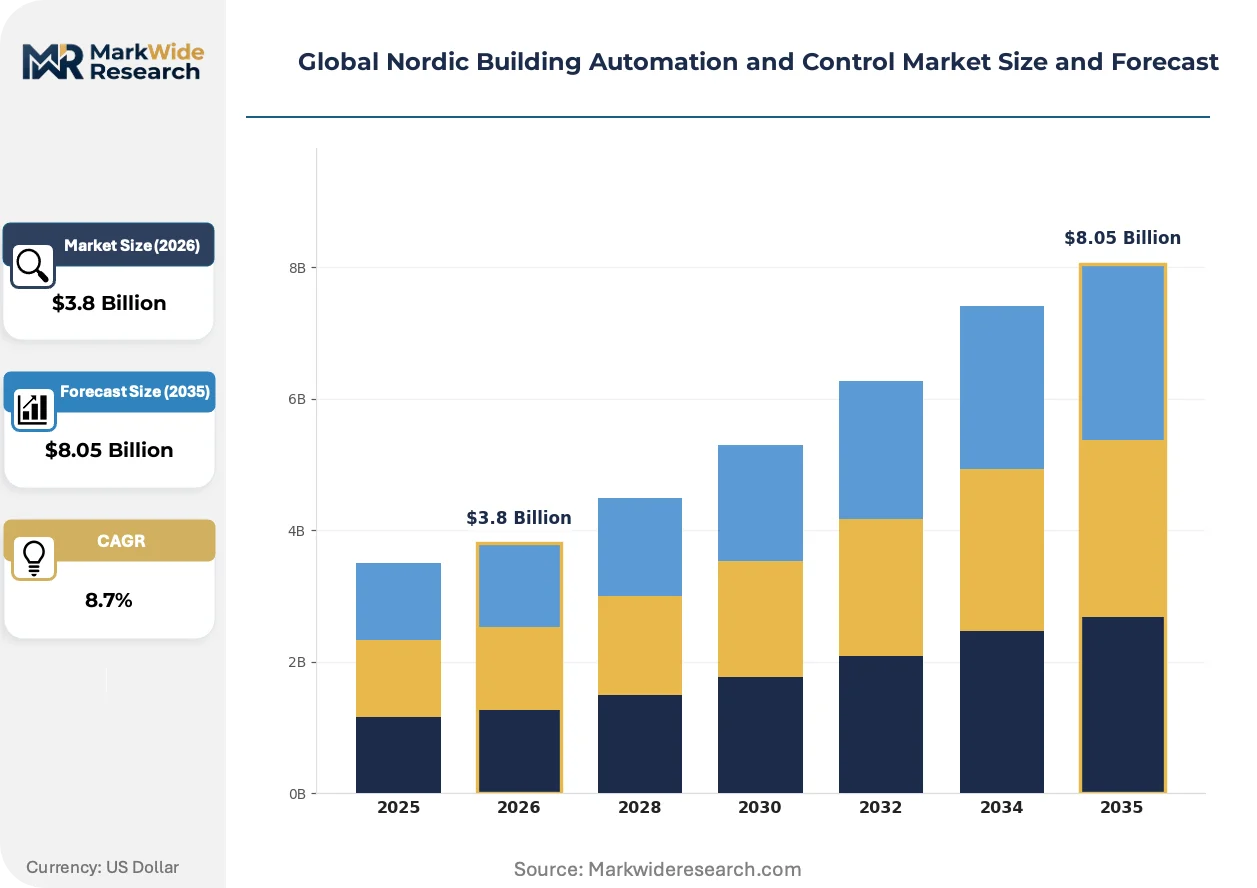
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, HVAC Control, Security Systems, Energy Management Technology: Wired, Wireless, IoT, Cloud-Based End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Educational Institutions Installation: Retrofitting, New Installation, Upgrades, Maintenance |
| Companies Covered | Caverion Corporation, Beijer Electronics, Bastec AB, Fidelix, Nordomatic AB, Guard Automation, Regin Group, Honeywell, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nordic Building Automation and Control Market Strategic Shifts
Digital twin architectures and edge-native control platforms are compressing the traditional building management stack, displacing centralized server rooms with distributed intelligence across Nordic commercial portfolios.
Digital twin software is virtualizing physical building performance through real-time sensor fusion and thermal simulation. Large commercial landlords in Stockholm and Copenhagen are deploying these platforms to optimize HVAC sequencing before physical retrofit commitment. The technology is virtualizing capital planning cycles, allowing energy savings verification without hardware installation.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition in heat pump-dependent Nordic buildings. This regulatory pressure forces control system upgrades to accommodate lower-GWP refrigerant thermodynamic properties. Denmark's national energy agency enforces stricter leakage monitoring thresholds than EU baselines, driving sensor density requirements in Copenhagen-area commercial properties.
Facility managers are consolidating vendor relationships around integrated service contracts that bundle hardware, software, and predictive maintenance. Traditional equipment-only procurement is contracting in favor of outcome-guaranteed performance agreements. Swedish hospital and university portfolios exhibit the fastest contract structure migration, with five-year bundled terms replacing annual maintenance renewals.
Global Nordic Building Automation and Control Market Segmentation
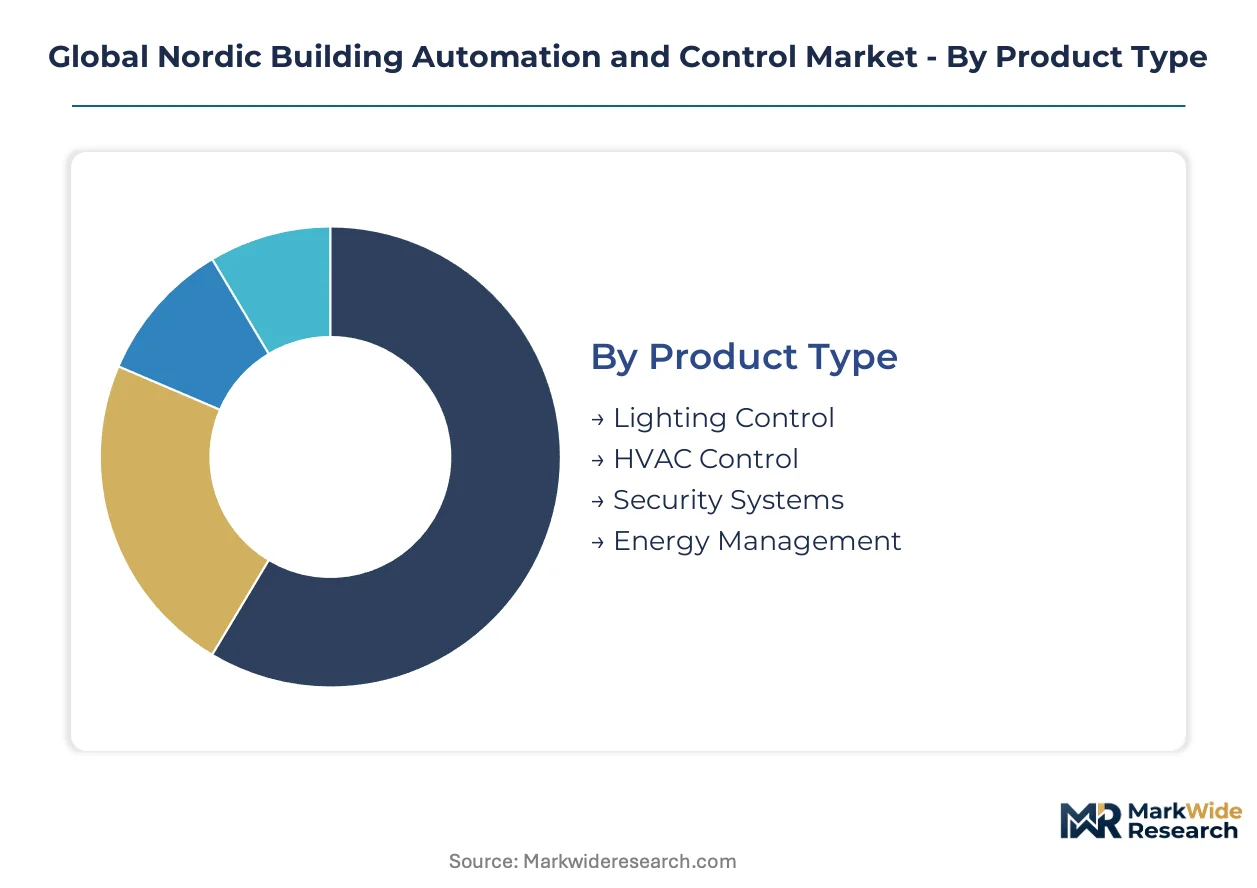
Nordic building automation segmentation reflects the tension between legacy infrastructure constraints and EU Green Deal compliance deadlines. Product and technology categories map directly to distinct procurement workflows across Denmark, Sweden, Norway, and Finland.
Product Type:
Mature HVAC control systems dominate installed base revenue, while emerging energy management platforms capture retrofit-driven growth.
- HVAC Control:Thermal regulation systems engineered for subarctic heating loads and extended seasonal darkness. Demand concentrates in Stockholm-Uppsala corridor commercial portfolios where heating intensity drives control system density per square meter.
- Energy Management:Integrated monitoring platforms that aggregate consumption data across building systems for carbon disclosure compliance. Finnish municipal buildings in Helsinki-Tampere corridor are accelerating procurement ahead of mandatory reporting deadlines.
- Lighting Control:Daylight harvesting and occupancy-responsive systems addressing Nordic extended darkness conditions.
- Security Systems:Access control and surveillance integration bundled with broader building management platforms.
HVAC Control handles the majority of throughput; Energy Management is expanding most quickly on share.
Technology:
Cost tier stratification separates premium cloud-native deployments from economy-tier wired retrofits in aging Nordic building stock.
- Cloud-Based:Centralized platforms enabling remote diagnostics and predictive maintenance across distributed commercial portfolios. Swedish hospital and university systems are consolidating vendor relationships around five-year bundled service contracts.
- IoT:Wireless sensor networks delivering granular zone control without structural modification. Greater Copenhagen commercial landlords deploy these for rapid compliance with Denmark's stricter-than-EU leakage monitoring thresholds.
- Wireless:BACnet and Modbus-compatible radio frequency networks reducing installation labor in peripheral Norwegian and Finnish markets.
- Wired:Legacy copper infrastructure remaining dominant in institutional buildings with 1990s proprietary protocol lock-in.
Cloud-Based commands premium pricing; IoT is climbing the fastest on deployment velocity.
End User:
Application concentration varies sharply between public sector disclosure mandates and private portfolio efficiency targets.
- Commercial Buildings:Office and retail portfolios across Scandinavian capitals requiring automated energy monitoring above statutory floor thresholds. Stockholm and Copenhagen clusters exhibit highest control system density per building.
- Educational Institutions:Universities and technical colleges pursuing integrated platforms for research facility climate control. Swedish green procurement incentives favor domestic supplier qualification in this segment.
- Industrial Facilities:Manufacturing plants with process-critical environmental regulation needs.
- Residential Buildings:Multi-unit housing with slower adoption due to fragmented ownership structures.
Commercial Buildings absorb the largest project volume; Educational Institutions are gaining share fastest on public retrofit acceleration.
Installation:
Customer type bifurcation separates owner-operated new construction from third-party retrofit specialists serving compliance-driven upgrades.
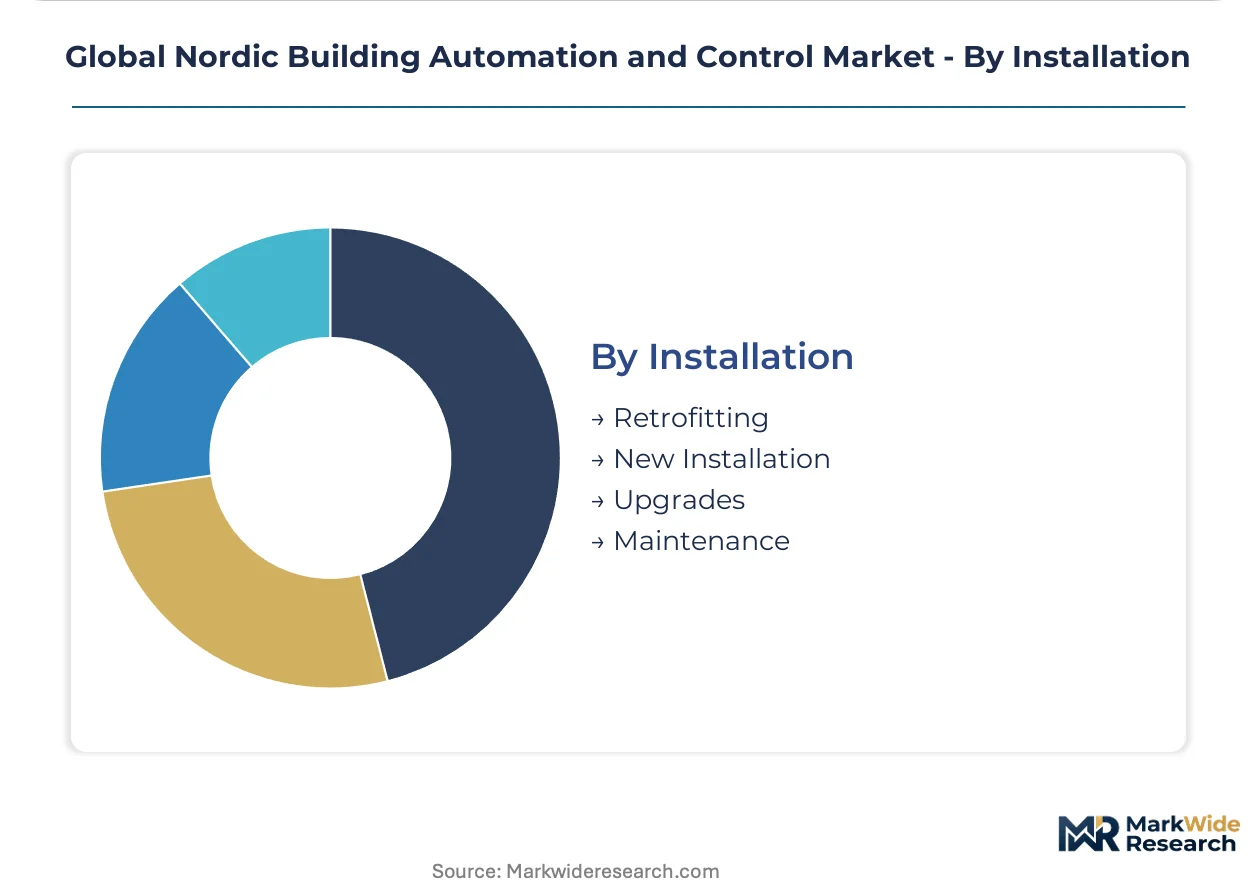
- Retrofitting:Control system overlay onto existing HVAC and lighting infrastructure without full replacement. Aging Nordic building stock drives demand as EU Energy Performance of Buildings Directive deadlines approach.
- Upgrades:Protocol conversion and sensor density expansion in buildings with partial automation already installed.
- New Installation:Integrated system specification in publicly funded construction subject to national efficiency thresholds.
- Maintenance:Predictive service contracts replacing annual renewals with outcome-guaranteed performance agreements.
Retrofitting carries the heaviest project load; Maintenance is the fastest-expanding revenue line on contract structure migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Control system fabrication concentrates in Sweden and Denmark, where industrial automation heritage and green procurement frameworks create integrated supplier ecosystems. Component sourcing spans German semiconductor supply chains and Baltic assembly operations. Installation velocity varies sharply between capital-region labor pools and peripheral Nordic markets.
Sweden
Stockholm-Uppsala corridor dominates HVAC control deployment density, driven by subarctic heating loads in commercial portfolios. The Swedish Energy Agency enforces stricter-than-EU building performance disclosure thresholds for public tenders. Gothenburg's industrial automation cluster anchors manufacturing of BACnet-compatible control modules for export across the Nordic region.
Denmark
Greater Copenhagen commercial landlords accelerate IoT sensor deployment for F-Gas Regulation compliance and leakage monitoring. The Danish Energy Agency mandates automated energy monitoring in structures above specific floor thresholds ahead of EU deadlines. Odense's robotics engineering base supplies wireless control hardware to building automation integrators.
Norway
Oslo-Bergen corridor exhibits concentrated demand for offshore-adjacent industrial facility climate control. The Norwegian Water Resources and Energy Directorate layers national efficiency standards atop EU Green Deal baselines. Stavanger's oil services engineering pool supplies technicians for complex BMS commissioning in North Sea platform support facilities.
Finland
Helsinki-Tampere municipal building portfolios face mandatory carbon disclosure by 2027, forcing energy management platform procurement. Motiva, the national energy efficiency agency, administers public retrofit subsidy programs tied to automated monitoring requirements. Espoo's cleantech cluster develops cloud-native building analytics for Nordic climate optimization.
Germany
German industrial automation suppliers serve as upstream component sources for Nordic system integrators, particularly in edge computing hardware and semiconductor controls. The Federal Ministry for Economic Affairs and Climate Action coordinates EU Green Deal implementation with national building energy efficiency standards. Munich and Stuttgart engineering centers supply BACnet protocol expertise to Stockholm and Copenhagen installation teams.
Global Nordic Building Automation and Control Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in protocol modules and sensor hardware. The Nordic building automation sector exhibits moderate consolidation around full-service providers bundling installation with long-term maintenance contracts. Two strategic archetypes dominate: industrial automation conglomerates leveraging manufacturing heritage for large-scale commercial deployments, and regional specialists competing through integrated service bundling and domestic procurement qualification. Competitive moves center on predictive maintenance capability acquisition and cloud platform partnerships to displace traditional annual service renewals.
Among Nordic-headquartered service integrators, Caverion Corporation and Nordomatic AB occupy positions emphasizing long-term maintenance bundling over equipment-only sales. Siemens AG anchors the industrial automation tier, drawing on cross-sector control system expertise. Honeywell represents the multinational platform archetype, competing through cloud-based energy management architectures. These three exemplify the tension between regional service depth and global technology scale.
| Leading Market Players |
|---|
| Caverion Corporation |
| Beijer Electronics |
| Bastec AB |
| Fidelix |
| Nordomatic AB |
| Guard Automation |
| Regin Group |
| Honeywell |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Stockholm freight corridor shapes Nordic building automation economics, as logistics costs from German semiconductor sources concentrate pricing power with Stockholm-based system integrators while Danish commercial landlords absorb premium IoT sensor pricing for F-Gas compliance.
Pricing Analysis
The EU Energy Performance of Buildings Directive dictates the pricing tier structure across Nordic markets, separating premium cloud-native platforms with predictive maintenance bundling from standard wired retrofits and economy-tier component-only procurement. Price differentiation rests on CE certification grade and after-sales service intensity, with Swedish public tenders rewarding domestic supplier qualification. Cost compression in the wired retrofit tier is intensifying because Finnish municipal budgets face mandatory carbon disclosure deadlines. Commercial building portfolios in Greater Copenhagen exhibit lowest price sensitivity due to regulatory penalty avoidance, while peripheral Norwegian markets show highest sensitivity to installation labor costs.
Supply Chain Analysis
Tariff exposure between Germany and Denmark dominates supply chain risk planning for edge computing hardware and BACnet protocol modules. Component sourcing concentrates in Germany, Taiwan, and South Korea for semiconductors, sensors, and wireless communication chipsets. Raw material dependencies span copper for wired infrastructure, lithium for battery-backed sensors, and rare earth elements for magnetic components in HVAC actuators. Single-source vulnerability persists in cloud infrastructure provision from non-Nordic hyperscalers. Distribution runs through Stockholm and Copenhagen-based system integrators who bundle hardware with long-term maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated commercial landlords in Stockholm-Uppsala and Greater Copenhagen corridors, as portfolio-scale procurement replaces fragmented building-level purchasing and forces vendors toward outcome-guaranteed performance contracts.
For Market Incumbents: Entrench predictive maintenance capabilities through machine learning diagnostics acquisitions, defending against emerging cloud-native platform entrants. Prioritize backward integration into wireless sensor manufacturing to secure supply continuity amid Baltic assembly volatility. Lock in five-year bundled service contracts with Swedish hospital and university portfolios before Finnish municipal retrofits accelerate competitive bidding. For New Entrants and Emerging Players: Establish a beachhead in Finnish municipal energy management platforms ahead of mandatory carbon disclosure deadlines, where incumbent service networks remain underdeveloped. Target the Helsinki-Tampere corridor with rapid-deployment IoT sensor packages that bypass structural retrofit requirements. Lead with subscription-based pricing that converts capital expenditure to operational expenditure for budget-constrained public sector buyers. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates seeking to divest non-core building automation divisions amid portfolio rationalization. Long-term viability favors platform-integrated service providers with captive maintenance revenue streams over equipment-only vendors. Monitor Swedish green procurement incentive expansion as the inflection signal for domestic qualification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Acquisition | Machine learning diagnostics compress service call frequency and extend contract durations for Swedish hospital portfolios. |
| Wireless Sensor Manufacturing Integration | Backward integration into IoT hardware reduces lead time volatility from Baltic assembly operations. |
| Five-Year Bundled Service Contract Migration | Outcome-guaranteed performance agreements replace annual renewals in Stockholm-Uppsala commercial buildings. |
| Finnish Municipal Retrofit Specialization | Helsinki-Tampere corridor procurement acceleration creates white space for integrated energy management platforms. |
| CE Plus National Certification Stacking | Swedish Energy Agency disclosure thresholds reward vendors with dual-layer compliance documentation. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with building automation system integrators, facility management executives, and municipal procurement officers across Denmark, Sweden, Norway, and Finland; and secondary validation against EU Energy Performance of Buildings Directive implementation timelines, national energy agency efficiency standards, and trade data on HVAC control module imports. Bottom-up project pipeline assessment triangulated with top-down market sizing across product type, technology, and end user segmentation dimensions.
Forecast inputs encompassed retrofit velocity tied to EU Green Deal compliance deadlines, IoT sensor deployment rates in aging Nordic building stock, and cloud platform adoption curves in Swedish institutional portfolios. Segmentation modeling spanned HVAC control, energy management, lighting control, and security systems by wired, wireless, IoT, and cloud-based technology tiers across commercial, educational, industrial, and residential end users. CAGRs were derived from installation volume trajectories and contract value migration toward bundled service structures.
Stress conditions across semiconductor lead times, technician labor availability, and EU F-Gas Regulation enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and public sector budget continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
Signage Market
Building Automation Systems
Building Technologies Market