
 Spray Foam Market | 2026-2036
Spray Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Foam Market Analysis
North American chemical producers is hardening supply positions ahead of anticipated feedstock volatility. BASF SE leverages its integrated polyols network across Ludwigshafen and Geismar to secure precursor availability. Dow Chemical Company sustains technology leadership in next-generation low-GWP formulations through its Materials Science division. Huntsman Corporation anchors North American capacity with dedicated spray foam systems production in Geismar, Louisiana.
Spray foam comprises a two-component polyurethane system combining isocyanate and polyol resin that expands on application to create a rigid or semi-rigid cellular structure with thermal resistance values ranging from R-3.5 to R-7 per inch depending on cell configuration. The material functions primarily as an air barrier and thermal insulator in building envelopes, reducing HVAC loads by eliminating convective heat transfer through gaps and seams. Closed cell foam dominates commercial and industrial applications where higher compressive strength and moisture resistance justify premium positioning, while open cell foam occupies residential wall cavities where cost-per-R-value and sound attenuation drive specification. The insulation application segment leads volume consumption across all end-user categories, though roofing systems represent a concentrated margin pool due to specialized labor certification requirements and longer performance warranties.
The EPA's SNAP program and OSHA's isocyanate exposure standards shape product formulation and contractor certification requirements throughout the United States. State-level energy codes adopted by California, New York, and Washington mandate minimum insulation performance thresholds that elevate spray foam specification rates above national averages. Stakeholders must monitor evolving blowing agent phase-out schedules and building electrification mandates that will redefine competitive advantage around low-carbon chemistry and installation workforce development.
Market Dynamics
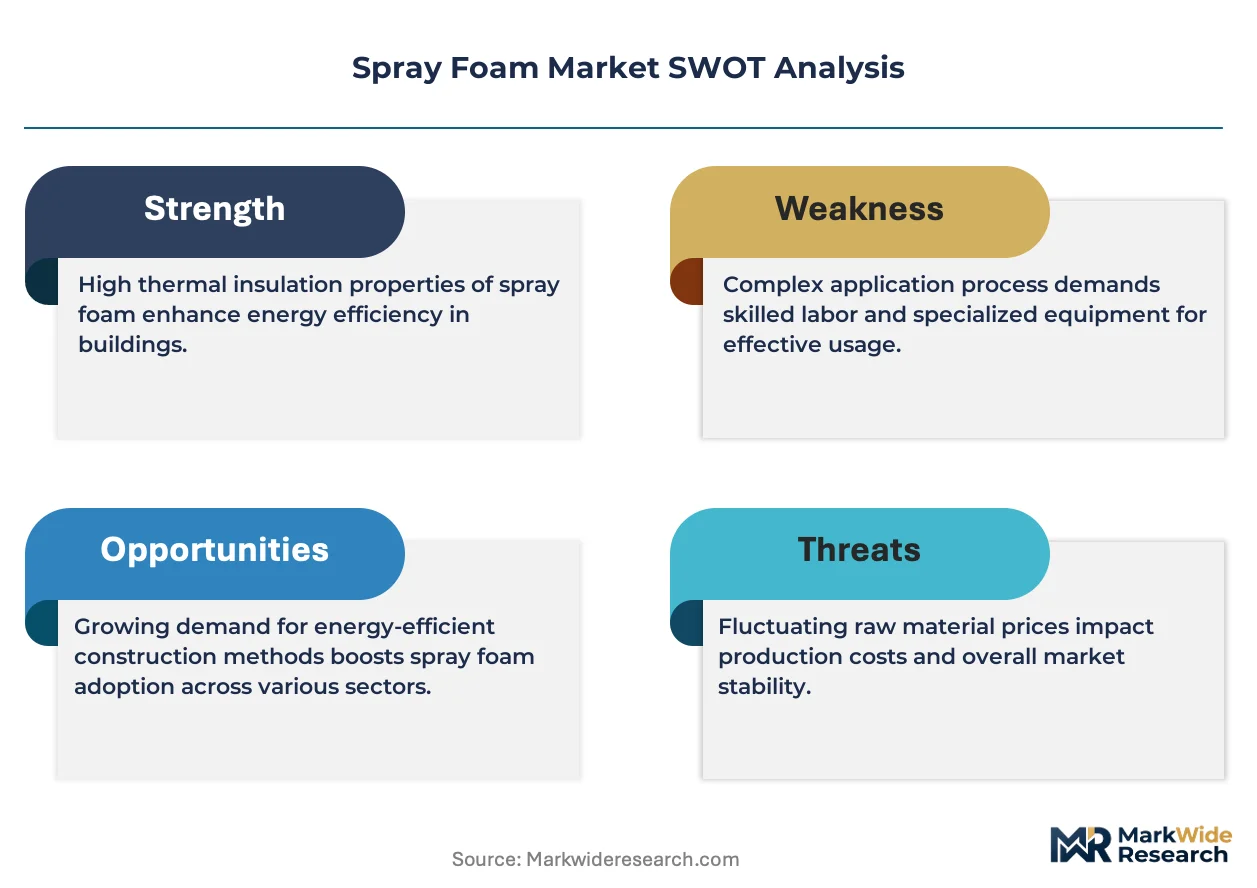
The spray foam sector confronts a structural squeeze between feedstock volatility and regulatory-driven chemistry transitions, with the EPA's SNAP program forcing wholesale blowing-agent reformulation while polyol and isocyanate supply chains tighten.
Growth Catalysts
- Sun Belt Housing Construction:Texas, Florida, and Arizona residential permitting volumes elevate specification of high-R-value envelope systems in single-family and multifamily developments.
- Building Electrification Mandates:California's Title 24 energy code and Washington State's Clean Buildings Performance Standard tighten thermal efficiency thresholds, mandating spray foam in retrofit and new construction.
- Low-GWP Chemistry Transition:Hydrofluoroolefin blowing agents are replacing hydrofluorocarbons in closed-cell formulations, opening specification pathways in jurisdictions with phasedown schedules.
Market Restraints
- Petrochemical Feedstock Volatility:Crude oil and natural gas liquid price swings transmit directly to polyol and isocyanate input costs, compressing blended margins for systems houses.
- Concentrated MDI Supply:North American methylene diphenyl diisocyanate production clusters on the Gulf Coast, exposing the value chain to hurricane disruption and force majeure risk.
- Cellulose and Mineral Wool Substitution:Lower-cost fibrous insulations capture residential wall-cavity specifications where air-sealing performance is deprioritized by cost-conscious builders.
Strategic Opportunities
- Passive House Certification Growth:The PHIUS and Passivhaus Institut standards penetrate the US custom-home and mid-rise multifamily segments, specifying spray foam for thermal-bridge-free assemblies.
- Cold-Chain Infrastructure Expansion:Refrigerated warehouse and food-processing facility construction in the Midwest and Southeast drives demand for closed-cell roofing and wall systems with integrated vapor control.
- Direct-to-Contractor Digital Platforms:E-commerce channels for two-component kits and portable rigs are fragmenting traditional distribution, enabling smaller applicators to bypass regional distributors.
Industry Challenges
- Certified Applicator Shortage:OSHA's isocyanate exposure standard and manufacturer warranty requirements constrain the pool of qualified installers, extending project timelines in high-demand markets.
- Reformulation R&D Burden:The transition to next-generation blowing agents demands capital allocation to pilot-scale testing and fire-performance recertification without guaranteed code acceptance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Foam Market |
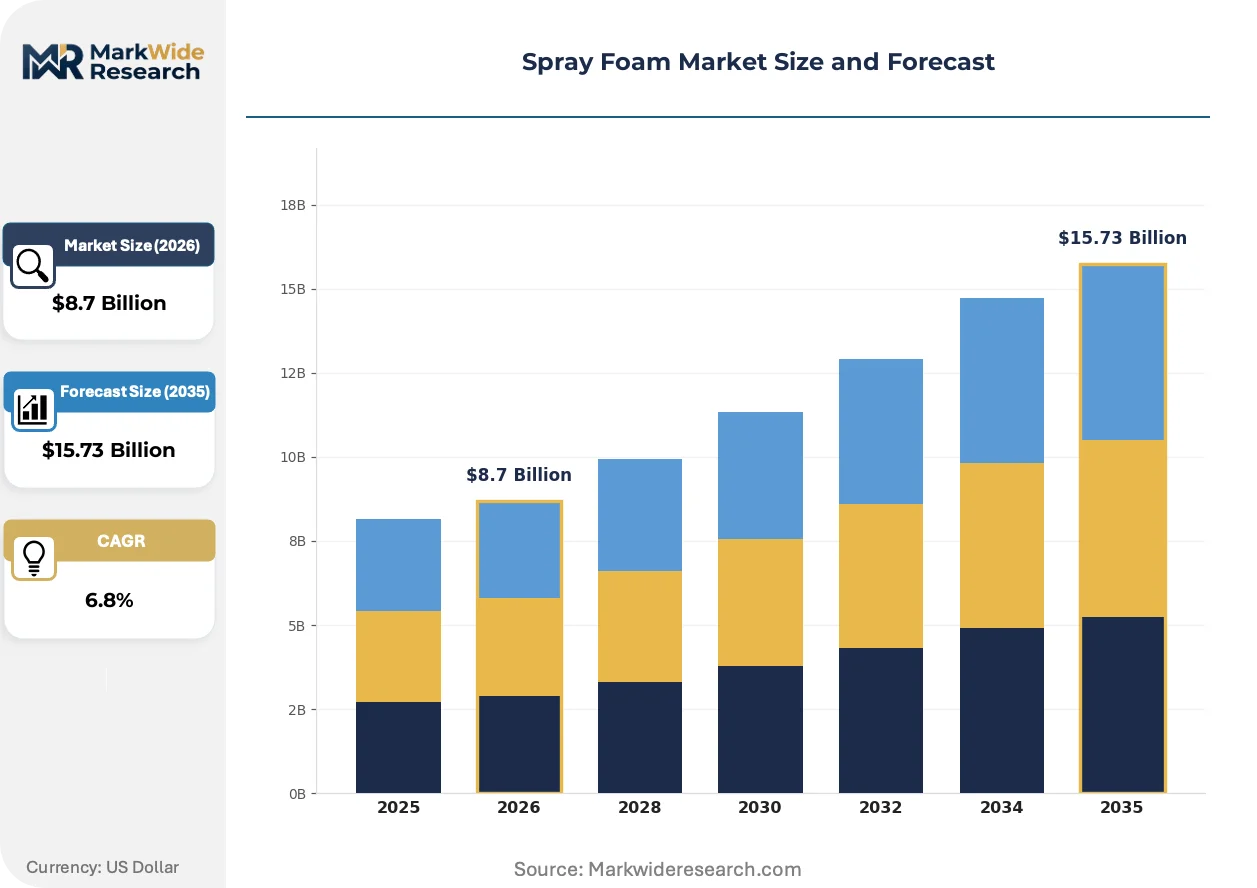
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cell Foam, Closed Cell Foam, Hybrid Foam, Others Application: Insulation, Roofing, Sealing, Filling End User: Residential, Commercial, Industrial, Agricultural Technology: Spray Application, Hand Mixing, Machine Mixing, Pouring |
| Companies Covered | Covestro AG, Johns Manville, BASF SE, NCFI Polyurethanes, CertainTeed, Dow Chemical Company, Carlisle Companies Inc., Accella Performance Materials, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Foam Market Emerging Trajectories
Reformulation pressures and installation-model disruption are compressing legacy product lifecycles while opening whitespace for chemistry innovators and channel insurgents.
Plant-based polyol feedstocks are absorbing incremental R&D investment from systems houses seeking carbon-intensity reductions for ESG disclosure and green-building certification compliance. Custom-home builders and net-zero developers specify these formulations at 15-30% price premiums. The shift is compressing petroleum-derived polyol volumes in residential segments where environmental claims drive purchasing.
The EPA's Significant New Alternatives Policy program is forcing phase-out schedules for high-GWP hydrofluorocarbon blowing agents across all closed-cell formulations. Manufacturers must recertify fire-performance and thermal-resistance ratings under accelerated timelines. Commercial roofing contractors in California and New York face the steepest compliance curves as state energy codes tighten in parallel.
Application contractors are consolidating purchasing power through cooperative buying groups and regional associations, displacing traditional distributor relationships. These aggregators negotiate direct volume commitments with systems houses, capturing margin that previously accrued to wholesale intermediaries. The pattern is most pronounced in Texas and Florida where independent applicator density supports collective bargaining structures.
Spray Foam Market Segmentation
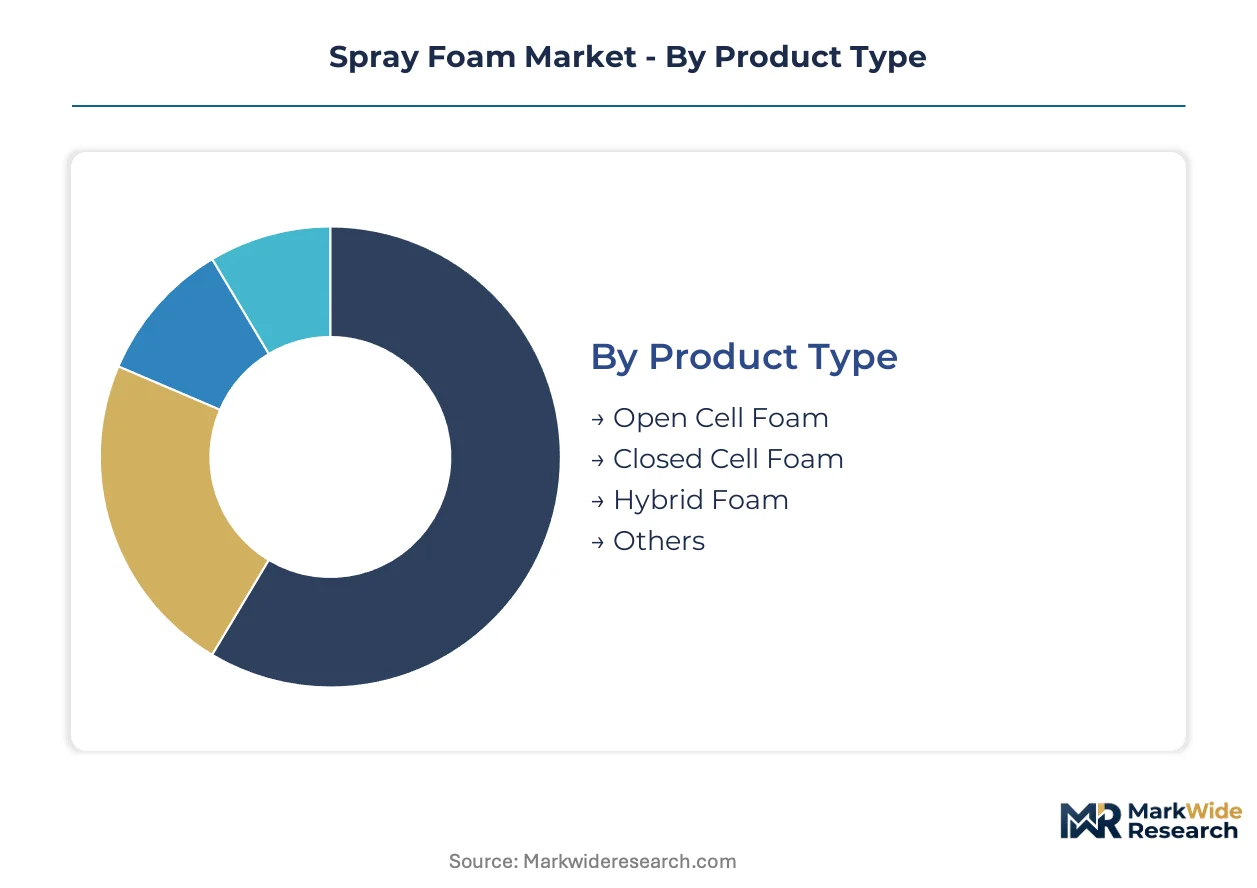
Spray foam segmentation reflects the tension between thermal performance specifications and installation economics. Product cell structure, application method, and end-use regulatory exposure each create distinct margin profiles and growth trajectories across the value chain.
Product Type:
Cell configuration determines compressive strength, moisture resistance, and thermal resistance per inch, anchoring specification decisions across climate zones and building codes.
- Open Cell Foam:Semi-rigid cellular structure with permeable walls allows moisture vapor transmission while delivering R-3.5 to R-4 per inch. Residential wall cavities in Sun Belt states specify this chemistry where cost-per-R-value and sound attenuation outweigh moisture-blocking requirements.
- Closed Cell Foam:Dense rigid structure with trapped blowing agent gas achieves R-6 to R-7 per inch and functions as both insulation and vapor barrier. Commercial roofing and cold-chain warehousing in hurricane-exposed Gulf Coast markets demand this chemistry for structural reinforcement and flood resistance.
- Hybrid Foam:Combines open-cell and closed-cell layers in single application to balance cost and performance. Emerging specification in mid-rise multifamily envelope assemblies.
- Others:Includes slow-rise formulations for retrofit cavity fill and high-density pour-in-place systems for structural insulated panels.
Closed cell foam leads on scale; hybrid foam leads on momentum.
Application:
Functional use case determines labor certification intensity, warranty duration, and exposure to energy code mandates.
- Insulation:Envelope thermal barrier installation in walls, attics, and floors accounts for the majority of volume consumption across all end-user categories. California Title 24 and Washington Clean Buildings Performance Standard mandate minimum R-values that elevate spray foam specification rates above national averages in retrofit and new construction.
- Roofing:Monolithic membrane systems combine thermal resistance with structural adhesion and wind uplift resistance. Specialized labor certification requirements and longer performance warranties create a concentrated margin pool for contractors serving commercial and industrial facilities.
- Sealing:Air barrier applications at penetrations, joints, and rim joists address blower-door test compliance in Passive House and net-zero certifications.
- Filling:Cavity-fill and void-filling applications in existing construction leverage slow-rise formulations to avoid structural displacement.
Insulation leads on scale; roofing leads on momentum.
End User:
Customer category shapes batch size, specification authority, and sensitivity to first-cost versus lifecycle energy savings.
- Residential:Single-family and multifamily builders drive volume through production home construction and custom net-zero developments. Sun Belt permitting volumes in Texas, Florida, and Arizona elevate specification of high-R-value envelope systems.
- Commercial:Office, retail, and hospitality developers prioritize thermal performance to meet LEED and utility incentive thresholds. Building electrification mandates tighten envelope requirements in jurisdictions with phased carbon reduction schedules.
- Industrial:Manufacturing facilities and refrigerated warehouses demand closed-cell roofing with integrated vapor control for process temperature stability.
- Agricultural:Poultry houses, dairy barns, and controlled-environment agriculture specify spray foam for condensation control and livestock thermal comfort.
Residential leads on scale; commercial leads on momentum.
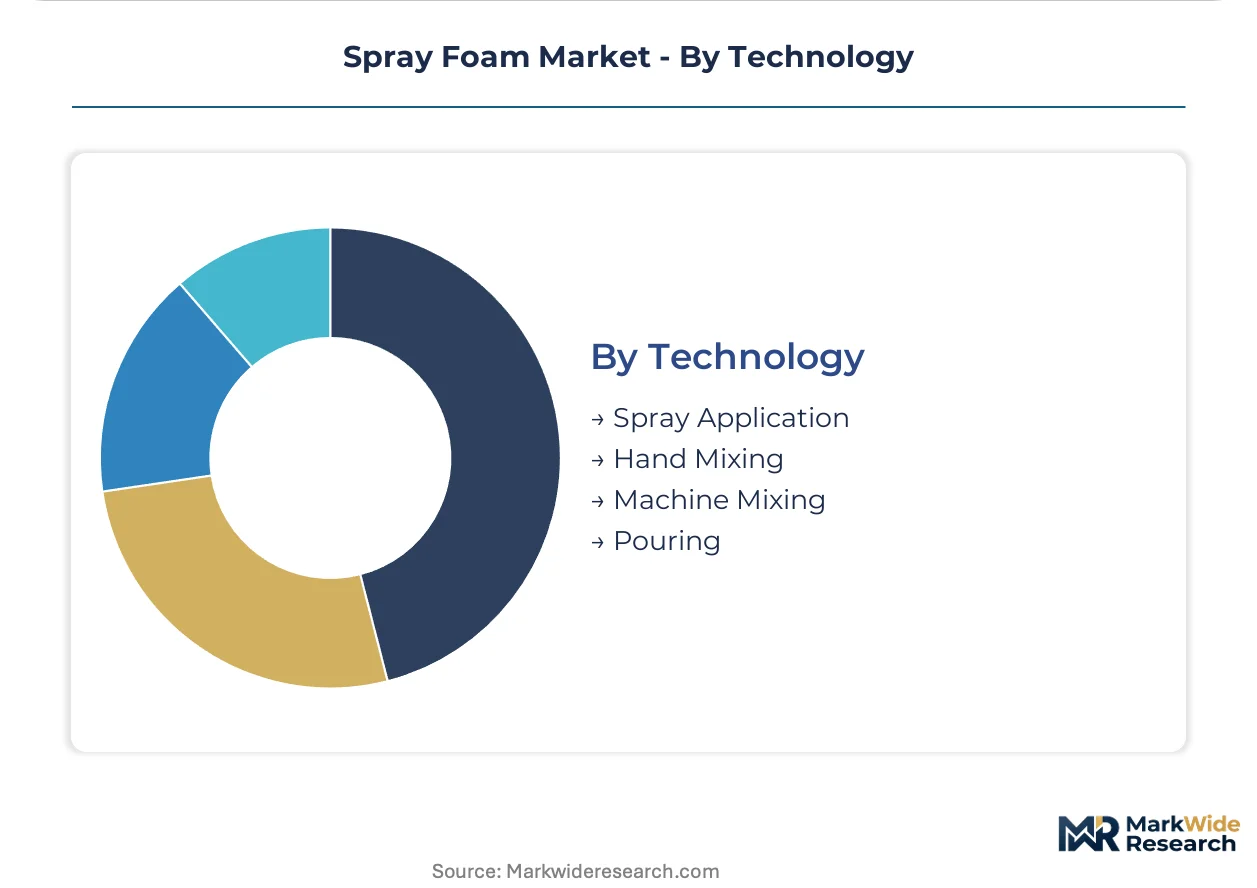
Technology:
Application method determines capital equipment requirements, material yield rates, and contractor entry barriers.
- Spray Application:Two-component proportioning systems deliver heated and pressurized isocyanate and polyol through plural-component spray guns. This method dominates professional installation for insulation and roofing across all end-user segments.
- Hand Mixing:Pre-measured two-component kits enable small-scale repairs and specialty applications without capital equipment investment. Direct-to-contractor digital platforms are fragmenting traditional distribution for this format.
- Machine Mixing:Portable and trailer-mounted rigs with onboard generators support remote construction sites and high-volume commercial projects.
- Pouring:Slow-rise formulations for structural insulated panel manufacturing and insulated concrete form cavity fill.
Spray application leads on scale; hand mixing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical producers supply polyol precursors to North American formulators, while China's construction chemical sector scales domestic spray foam production for its building electrification push. Regional demand patterns diverge sharply between mature retrofit markets and high-growth new construction corridors.
United States
Sun Belt housing construction in Texas, Florida, and Arizona drives specification of high-R-value envelope systems in single-family developments. The EPA's SNAP program mandates hydrofluorocarbon blowing agent phase-outs, forcing reformulation timelines. The Gulf Coast petrochemical corridor around Houston anchors North American methylene diphenyl diisocyanate production, concentrating supply risk.
Germany
Passivhaus Institut standards penetrate the custom-home and mid-rise multifamily segments, specifying spray foam for thermal-bridge-free assemblies. The EU F-Gas Regulation accelerates low-GWP chemistry transitions across closed-cell formulations. The Ludwigshafen chemical cluster integrates polyol production with systems house supply chains.
China
Building electrification mandates in tier-one cities tighten thermal efficiency thresholds for retrofit and new construction. The Ministry of Ecology and Environment enforces dual carbon goals that elevate low-carbon insulation specifications. The Yangtze River Delta construction chemical sector scales domestic spray foam production for cold-chain infrastructure.
Japan
Net-zero building codes in Tokyo and Osaka mandate high-performance envelope systems for commercial developments. METI energy efficiency standards accelerate specification of rigid foam insulation in seismic-resistant structures. The Kanto region's chemical producers supply specialized polyol formulations for humidity-resistant applications.
Canada
Cold-climate construction in Alberta and British Columbia demands closed-cell roofing with integrated vapor control for condensation management. Health Canada's PMRA regulates blowing agent environmental profiles under federal environmental protection statutes. The Ontario construction sector specifies spray foam for energy code compliance in mid-rise multifamily envelope assemblies.
Spray Foam Market Vendor Landscape
German chemical conglomerates anchor one tier through integrated polyol networks; North American systems houses hold application-specific formulation expertise. Market structure consolidates around petrochemical-backed scale players and regional specialists with certified applicator networks. Two strategic archetypes dominate: integrated chemical producers controlling precursor supply, and independent systems houses with distribution depth. Competitive moves concentrate on backward integration into polyol production and direct-to-contractor digital platform development.
Among integrated chemical producers, BASF SE and Dow Chemical Company occupy positions exemplifying upstream control over precursor availability. Huntsman Corporation represents the systems house archetype with dedicated North American production capacity. Covestro AG anchors European supply positions through specialized polyurethane materials expertise.
| Leading Market Players |
|---|
| Covestro AG |
| Johns Manville |
| BASF SE |
| NCFI Polyurethanes |
| CertainTeed |
| Dow Chemical Company |
| Carlisle Companies Inc. |
| Accella Performance Materials |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
EPA SNAP program mandates on hydrofluorocarbon blowing agents gate qualified supply and premium-tier pricing access, restricting formulation-certified producers to high-margin commercial roofing contracts while uncertified competitors compete on cost in residential open-cell segments.
Pricing Analysis
Capacity additions in the US Gulf Coast are reshaping price floors for methylene diphenyl diisocyanate precursors. Three-tier pricing structure across premium low-GWP formulations, standard HFC-based closed-cell, and economy open-cell residential grades stratifies the market. Price differentiation centers on blowing agent certification tier and applicator warranty backing. Cost compression in standard-tier formulations is intensifying because cellulose and mineral wool substitution threatens residential wall-cavity share. Production home builders exhibit highest price sensitivity; Passive House-certified custom developers show lowest.
Supply Chain Analysis
Dual-sourcing requirements from commercial roofing contractors now mandate qualified backup suppliers for both polyol and isocyanate streams. Supply concentrates in the United States, Germany, and China for precursor production. Raw material dependencies center on crude oil derivatives for polyol feedstocks, natural gas liquids for isocyanate precursors, and fluorinated gas intermediates for blowing agents. Single-source vulnerability runs through Gulf Coast MDI production exposed to hurricane disruption. Distribution runs through regional systems houses with certified applicator networks, though direct-to-contractor digital platforms are fragmenting traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spray foam market represents a late-cycle quality story as building electrification mandates in California and Washington shift specification authority toward high-R-value envelope systems that reward certified installation networks and low-GWP chemistry investments.
For Market Incumbents: Lock in precursor supply through captive polyol production or long-term offtake agreements with Ludwigshafen and Geismar chemical clusters. Secure certified applicator capacity ahead of OSHA isocyanate exposure standard enforcement to constrain competitor access to warranty-eligible labor pools. Defend against cellulose substitution in residential segments by bundling air-sealing performance guarantees with envelope system specifications. For New Entrants and Emerging Players: Washington State's Clean Buildings Performance Standard opens a window for low-GWP formulation specialists to capture retrofit commercial envelope contracts ahead of incumbent reformulation timelines. Target mid-rise multifamily hybrid foam applications where specification authority sits with regional architecture firms rather than national production builders. Pursue direct digital platform routes to independent applicator cooperatives in Texas and Florida to bypass established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional systems houses with certified applicator networks because warranty eligibility creates sticky contractor relationships that resist price competition. The five-to-ten year viability window favors targets with established low-GWP formulation pipelines and direct-to-contractor digital infrastructure. Monitor EPA SNAP program phase-out acceleration as the inflection signal that would compress legacy product margins and reward early reformulation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | BASF SE and Dow Chemical secure precursor availability against Gulf Coast feedstock volatility. |
| Low-GWP Blowing Agent Reformulation | Hydrofluoroolefin transition opens specification pathways in California and New York commercial roofing. |
| Certified Applicator Network Expansion | OSHA compliance and manufacturer warranty requirements constrain qualified installer supply in high-demand Sun Belt markets. |
| Direct-to-Contractor Digital Platform | E-commerce fragmentation enables smaller applicators to bypass regional distributors and capture margin. |
| Plant-Based Polyol Feedstock Development | Carbon-intensity reductions command 15-30% price premiums from net-zero developers and ESG-mandated institutional builders. |
Methodological Framework
Multiple input streams — primary interviews with spray foam systems house technical directors, commercial roofing contractor purchasing managers, and residential production builder specification leads; secondary validation through EPA SNAP program filings, ACC chemical trade data, and state energy code adoption records; plus customs and feedstock pricing databases — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical shipment volumes were cross-referenced against expert panel inputs on reformulation timelines and certified applicator capacity constraints. Segmentation dimensions modeled include cell structure type, application function, end-user category, and technology method across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating housing permit forecasts, energy code stringency indices, and blowing agent phase-out schedules. Industry-specific inputs encompassed OSHA isocyanate exposure compliance costs and PHIUS certification penetration rates in custom-home construction.
Revisions become necessary when EPA accelerates hydrofluorocarbon phase-out schedules, Gulf Coast petrochemical operations experience sustained disruption, or cellulose insulation achieves comparable air-sealing performance at lower installed cost. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Gutter and Downspout Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market