
 Global Cool Roofs Market | 2026-2036
Global Cool Roofs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cool Roofs Market Foresight
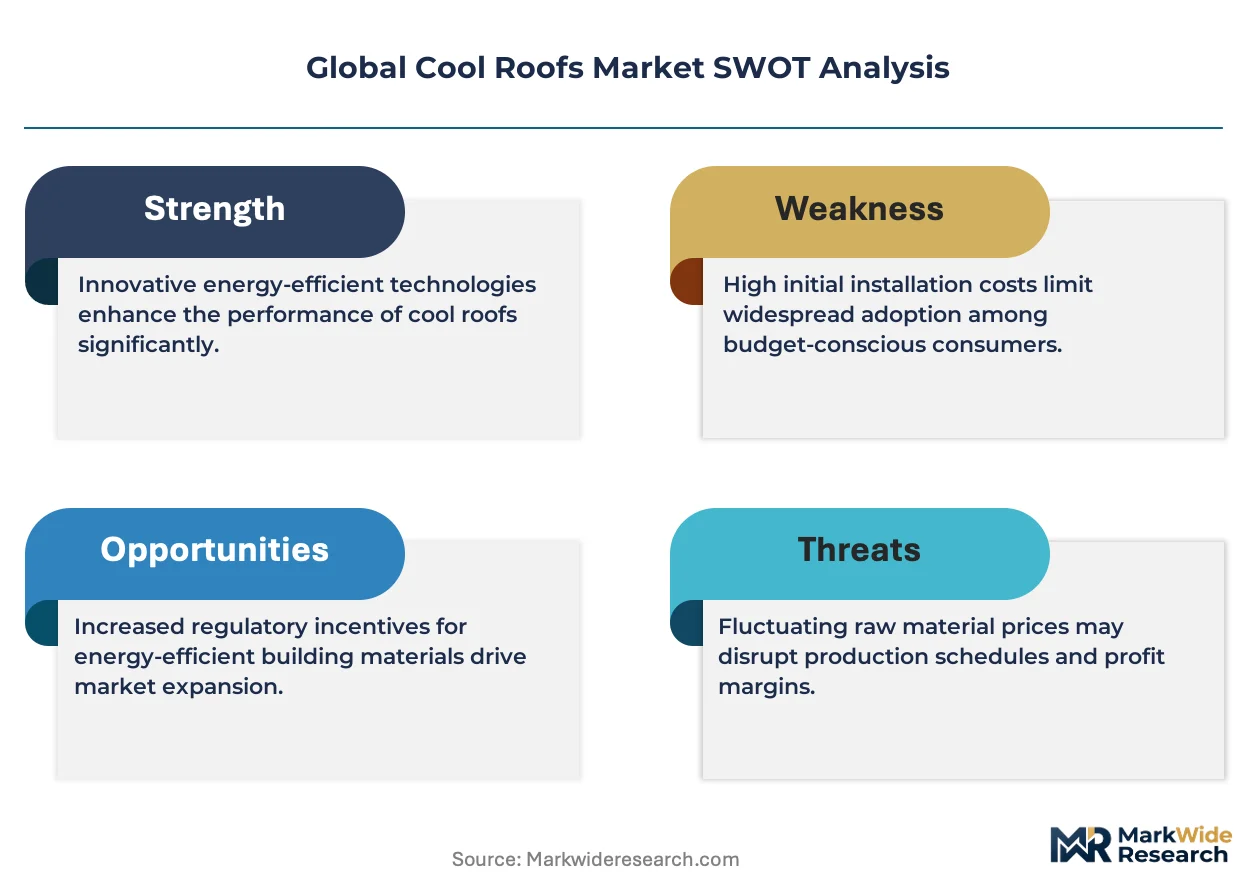
Green bond financing and energy service company leasing models are reshaping competitive dynamics in cool roof deployment. Owens Corning leverages its integrated insulation-to-membrane platform to capture bundled building envelope contracts. GAF Materials Corporation sustains manufacturing scale across multiple polymer chemistries for reflective membranes. Sika AG anchors its position through liquid-applied polyurethane systems that reduce installation labor on complex roof geometries.
Cool roofs are roofing assemblies engineered with high solar reflectance index values, typically achieved through white or light-colored coatings, single-ply membranes, or reflective granules that reduce surface temperatures by 50 to 60 degrees Fahrenheit versus conventional dark roofs. Their primary commercial purpose is to lower cooling energy consumption and extend membrane service life by reducing thermal cycling stress. The coatings segment leads volume due to lower material cost and applicability across existing substrates, while membranes command premium positioning in commercial and industrial facilities where seam integrity and warranty terms drive specification. Retrofit projects represent the fastest-growing installation category as building owners face accelerated replacement cycles for aged roofing systems and seek compliance with evolving energy codes without full structural replacement.
The US EPA Energy Star Roof Products program and California Title 24 Building Energy Efficiency Standards set minimum solar reflectance thresholds that directly shape product certification requirements and market access for manufacturers. The EU Green Deal and F-Gas Regulation are tightening embodied carbon and blowing agent standards for insulated roof assemblies, pushing reformulation of polyurethane and polystyrene components. India's Bureau of Energy Efficiency mandates cool roof compliance for government buildings in several climate zones under its Energy Conservation Building Code. Stakeholders must monitor how fragmented municipal adoption of performance-based codes versus prescriptive material lists will determine which product formats achieve specification dominance in priority markets.
Market Dynamics
Building energy codes across major economies are hardening solar reflectance mandates, forcing membrane and coating manufacturers to reformulate product lines for compliance or face market exclusion. This regulatory compression is accelerating consolidation among suppliers capable of certifying multi-jurisdictional performance standards.
Growth Catalysts
- California Title 24 Standards:Minimum solar reflectance thresholds for commercial and residential retrofits are pulling specification-grade coatings into mainstream building material distribution.
- Urban heat island mitigation:Municipal planning departments in Phoenix, Delhi, and Tokyo are embedding cool roof requirements into zoning overlays for dense commercial districts.
- Thermal cycling reduction:Reflective granule technology is extending membrane service life by 40-60% in high-temperature climates, lowering lifecycle cost calculations for portfolio owners.
Market Restraints
- Titanium dioxide volatility:White pigment feedstock prices swing with chloride process capacity constraints in Chinese manufacturing zones, compressing coating margin structures.
- Polyurethane blowing agent transition:EU F-Gas Regulation phase-down schedules are forcing reformulation of spray foam insulation bonded to reflective membranes, lengthening R&D cycles.
- Aesthetic limitation in heritage districts:Historic preservation boards in European city centers block white membrane installations, constraining retrofit addressable market.
Strategic Opportunities
- India ECBC expansion:Bureau of Energy Efficiency mandates for government buildings in hot-dry and warm-humid climate zones are creating specification pipelines for membrane suppliers with local testing partnerships.
- Green bond-linked installation:Sustainability-linked financing structures are bundling cool roof retrofits into commercial real estate refinancing, opening capital-light deployment channels.
- Cool roof-agrivoltaic convergence:Reflective substrate technology is migrating into agricultural building-integrated photovoltaic systems, expanding addressable square footage beyond traditional commercial envelopes.
Industry Challenges
- Installer certification fragmentation:Liquid-applied polyurethane systems require trained applicator networks, but manufacturer-specific credentialing programs lack cross-recognition, slowing crew scaling.
- Substrate compatibility testing:Aging built-up roofs with moisture infiltration create unpredictable adhesion surfaces, raising warranty claim exposure for coating applicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cool Roofs Market |
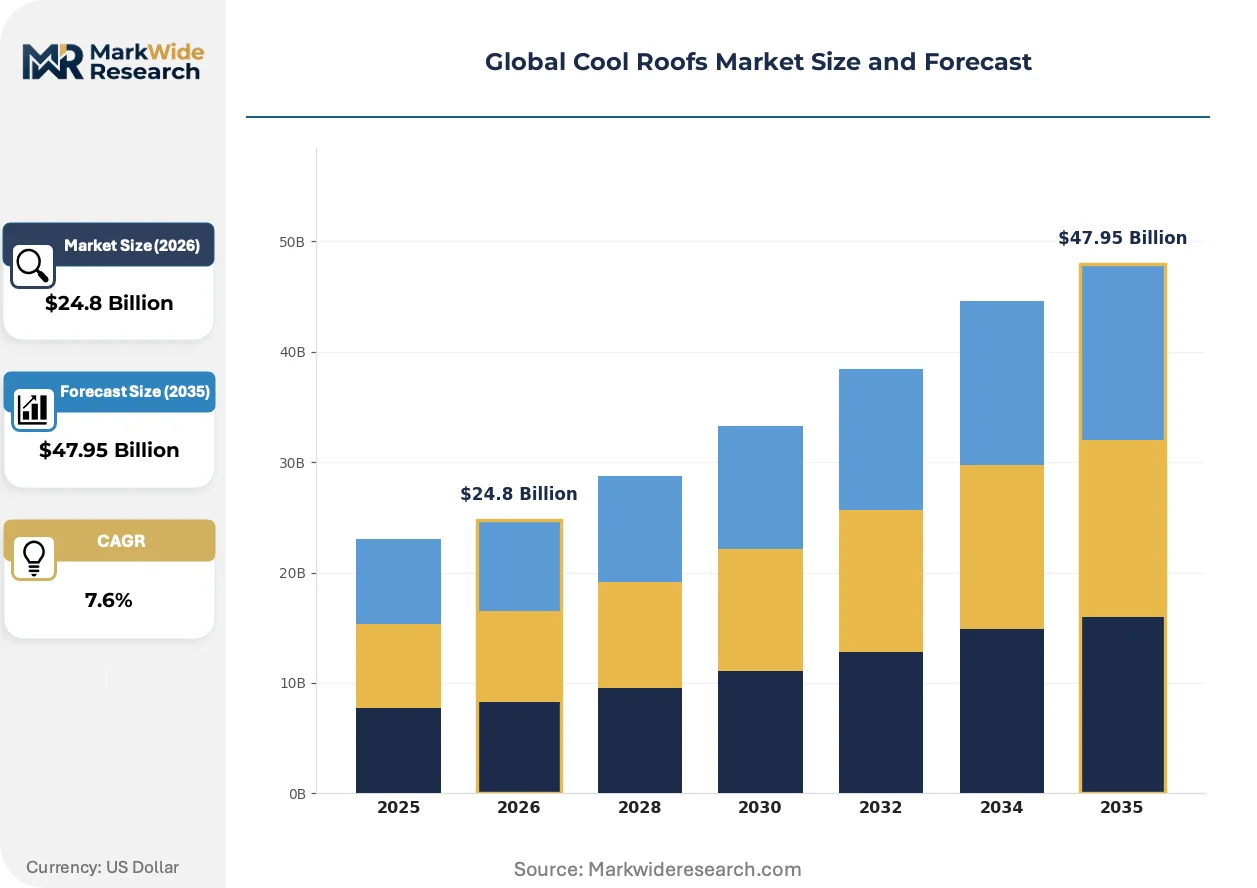
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Membranes, Tiles, Shingles, Paints Application: Commercial Buildings, Residential Structures, Industrial Facilities, Educational Institutions Installation Type: New Construction, Retrofit Projects, Replacement, Maintenance End User: Construction Companies, Facility Managers, Property Developers, Government Agencies |
| Companies Covered | Owens Corning, GAF Materials Corporation, Sika AG, BASF SE, 3M, PPG Industries, CertainTeed Corporation, Dow, Sherwin-Williams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cool Roofs Market Shifts & Advancements
Product chemistry and installation methodology are diverging as manufacturers compete on speed-to-install versus durability metrics. This bifurcation is reshaping specification criteria across commercial, industrial, and institutional buyer segments.
Cool roof technology is migrating from single-ply thermoplastic membranes toward liquid-applied polyurethane systems that conform to irregular substrates without mechanical fastening. Commercial facilities with complex roof geometries—skylights, HVAC curbs, penetrations—are specifying these systems to eliminate seam failure points. The shift is compressing demand for traditional rolled membrane formats in retrofit applications where substrate condition variability is highest.
EU F-Gas Regulation tightening on hydrofluorocarbon blowing agents is forcing polyurethane insulation suppliers toward hydro-olefin formulations with lower global warming potential. This transition is lengthening product recertification timelines and raising unit costs for insulated roof assemblies. German and French commercial construction markets are absorbing these premiums most acutely, as their national building codes reference EU Green Deal embodied carbon thresholds directly.
Building owners with distributed portfolios are consolidating roofing procurement under national account structures that bundle material, labor, and warranty into single-source contracts. This concentration is disintermediating regional roofing distributors who previously controlled local specification relationships. The pattern is most visible in United States retail and logistics facility networks, where standardized building prototypes enable volume commitments that extract preferential pricing and dedicated manufacturing slots.
Global Cool Roofs Market Segmentation
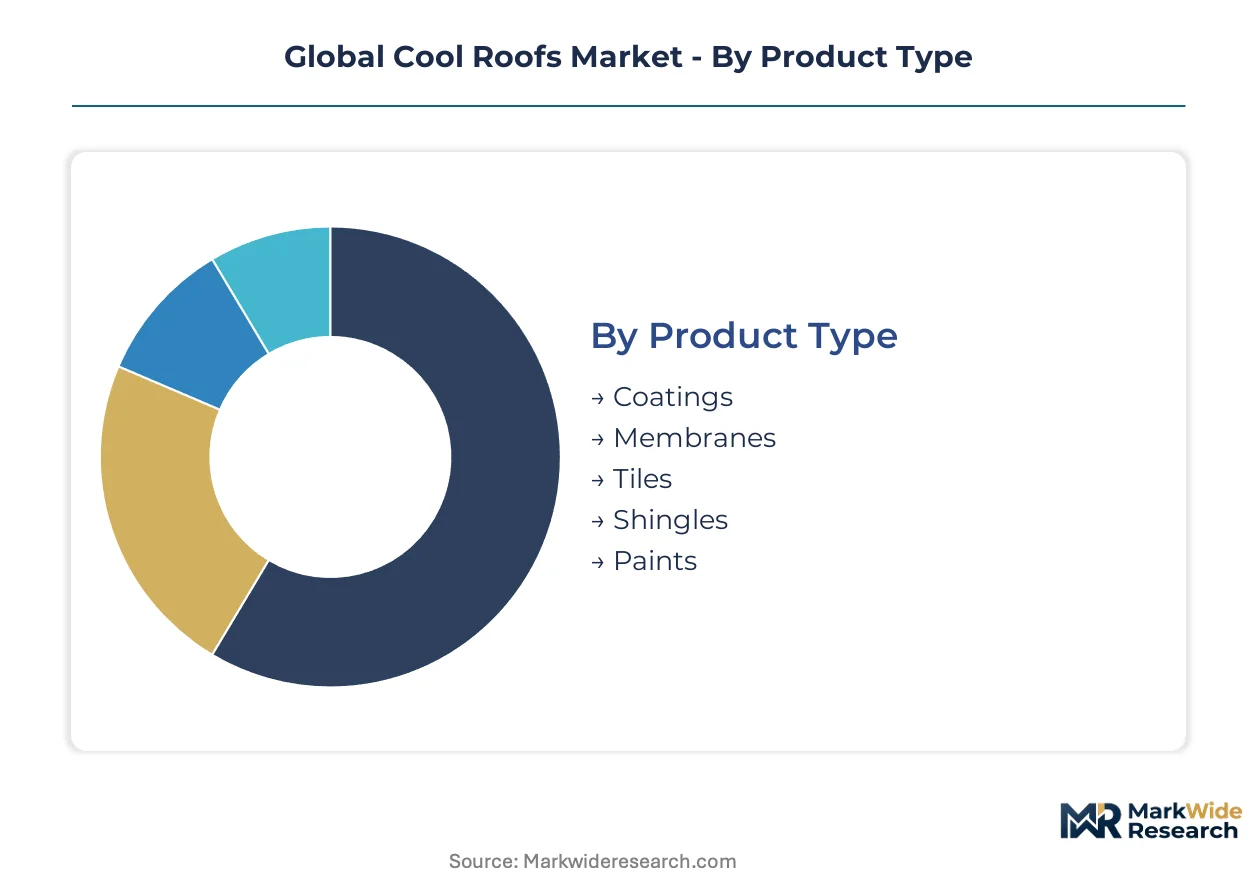
Cool roof procurement patterns diverge sharply across building types, installation contexts, and buyer sophistication levels. Understanding these segment boundaries clarifies where formulation investments concentrate and which specification pathways dominate contract flows.
Product Type:
Reflective technologies span liquid-applied systems through rigid roofing assemblies, each occupying distinct cost-performance positions across climate zones and substrate conditions.
- Coatings:Acrylic, silicone, and urethane formulations deliver solar reflectance through spray or roller application over existing substrates. Demand concentrates in United States commercial retrofits where California Title 24 compliance deadlines accelerate procurement of low-cost compliance solutions.
- Membranes:Thermoplastic polyolefin and polyvinyl chloride sheets provide factory-controlled thickness and seam-welded integrity. Industrial facilities in Germany and Japan specify these systems for warranty-backed performance where thermal cycling stress is most severe.
- Tiles:Clay and concrete units with surface glazes or reflective slurries achieve cool roof ratings without full membrane replacement. Mediterranean climate zones favor this format for aesthetic compatibility with regional architecture.
- Shingles:Asphalt-based products with reflective granule surfacing target residential replacement cycles. North American distribution networks stock these for contractor convenience in suburban markets.
- Paints:Lower-cost acrylic emulsions provide partial reflectance improvement on aged metal or modified bitumen roofs. Developing markets with limited capital budgets deploy these as interim efficiency measures.
Established volume favors coatings; emerging adoption favors membranes.
Application:
Building use cases determine thermal load profiles, code stringency exposure, and procurement centralization patterns.
- Commercial Buildings:Office, retail, and hospitality structures with flat or low-slope roofs dominate membrane specification. Portfolio owners in United States Sun Belt cities deploy national account structures to standardize reflective systems across multiple properties.
- Residential Structures:Steep-slope formats with shingle or tile surfacing respond to homeowner aesthetic preferences and local HOA restrictions. Cool roof penetration remains constrained by first-cost sensitivity in mass-market housing.
- Industrial Facilities:Warehouses, manufacturing plants, and cold storage buildings prioritize thermal performance over appearance. Large uninterrupted roof planes enable economies in single-ply membrane installation with minimal penetration complexity.
- Educational Institutions:K-12 schools and university buildings combine public funding availability with extended ownership horizons. State procurement offices in India and United States specify cool roofs for lifecycle cost advantages in taxpayer-funded construction.
Commercial and industrial applications absorb the majority of specification-grade membrane volume; educational procurement is climbing fastest as public sector sustainability mandates harden.
Installation Type:
Project origin—new build versus existing structure—shapes product format selection, labor skill requirements, and warranty risk allocation.
- New Construction:Integrated design processes enable cool roof specification during structural planning. Architects in Japan and Germany embed solar reflectance targets into envelope performance models before contractor selection.
- Retrofit Projects:Application of coatings or membrane overlays onto aged substrates without structural replacement. Building owners in Phoenix, Delhi, and Los Angeles deploy these solutions to meet municipal heat island ordinances with minimal disruption.
- Replacement:Full tear-off and re-roofing cycles triggered by membrane end-of-life or storm damage. Insurance claim processes in United States coastal markets increasingly specify reflective replacements for hail-resistant properties.
- Maintenance:Recoating, seam repair, and granule replenishment to preserve reflectance performance. Facility management contracts in commercial portfolios bundle these services under multi-year service agreements.
Retrofit activity is expanding most quickly as building stock ages and energy code compliance deadlines approach.
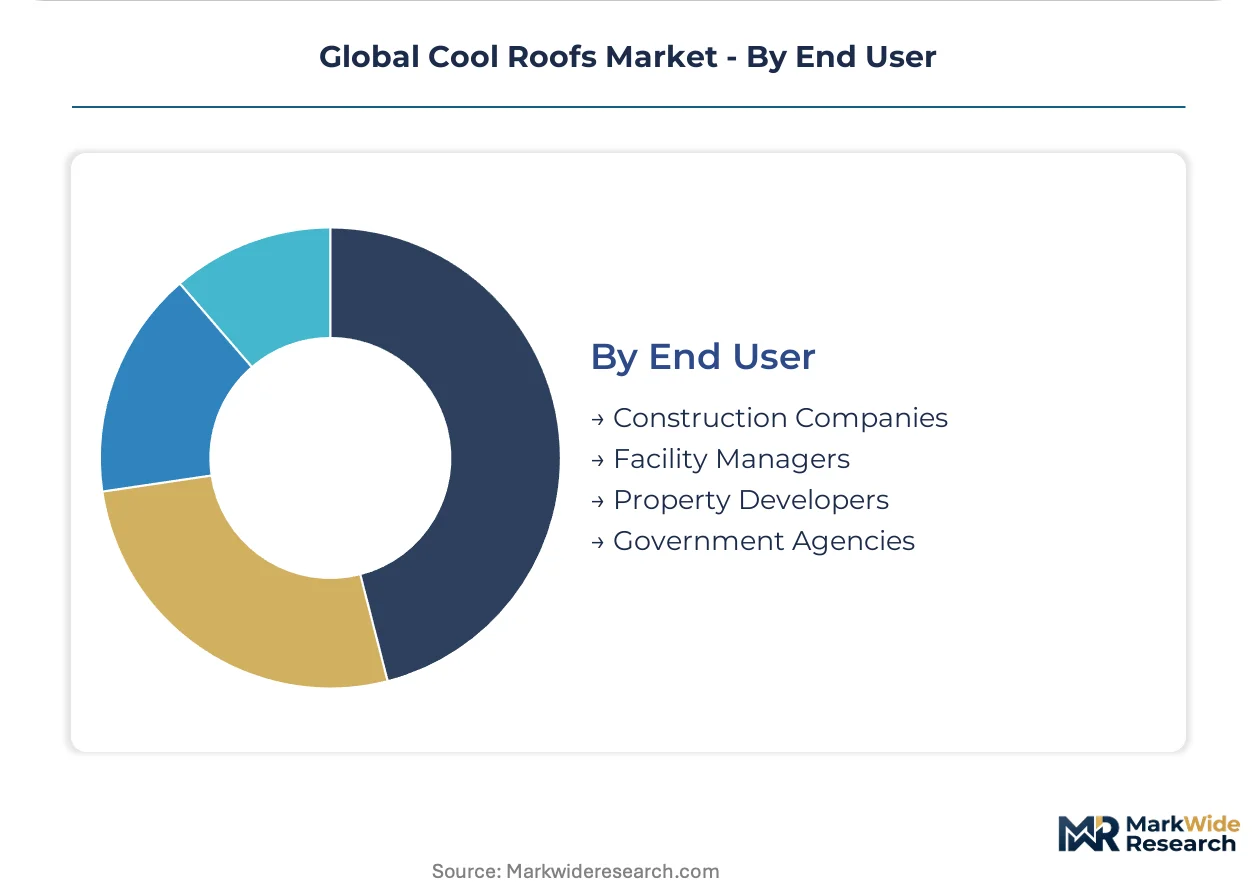
End User:
Buyer organizational structure determines whether procurement emphasizes lowest first cost, lifecycle optimization, or regulatory risk mitigation.
- Construction Companies:General and roofing contractors select products based on crew familiarity, distributor availability, and bid competitiveness. Regional preferences persist where training programs and supplier relationships are entrenched.
- Facility Managers:Corporate and institutional building operators prioritize warranty terms and predictive maintenance compatibility. Large United States retail and logistics networks centralize these decisions under national procurement functions.
- Property Developers:Speculative builders and real estate investment trusts evaluate cool roofs through net operating income impact and green building certification point accumulation. Green bond financing structures increasingly influence these calculations.
- Government Agencies:Federal, state, and municipal entities with mandated sustainability targets. India's Bureau of Energy Efficiency directives for government buildings create specification pipelines with testing and compliance documentation requirements.
Facility managers and government agencies are driving specification toward certified, warranty-backed systems; construction companies remain price-sensitive in competitive bidding environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portfolio owners and facility managers in the United States, China, and India drive the bulk of specification-grade procurement as municipal heat island ordinances harden compliance deadlines across dense commercial districts.
United States
Retail and logistics networks with standardized building prototypes deploy national account structures to extract volume pricing across Sun Belt properties. California's Title 24 Building Standards mandate minimum solar reflectance thresholds for commercial retrofits, pulling specification-grade coatings into mainstream distribution. Phoenix and Los Angeles municipal planning departments embed cool roof requirements into zoning overlays for dense commercial corridors.
China
Urban heat island mitigation has become a planning priority in megacity clusters along the eastern seaboard. The Ministry of Ecology and Environment enforces dual carbon goals that tighten embodied carbon standards for construction materials in public building procurement. Yangtze River Delta municipalities specify reflective roofing for government facilities and state-owned enterprise portfolios undergoing energy efficiency retrofits.
India
Bureau of Energy Efficiency mandates under the Energy Conservation Building Code create specification pipelines for membrane suppliers with local testing partnerships. Government buildings in hot-dry and warm-humid climate zones face accelerated compliance timelines. Delhi and Hyderabad municipal corporations require cool roof installation for commercial structures above specified floor-area thresholds.
Germany
Industrial facilities prioritize thermal performance as EU F-Gas Regulation phase-down schedules force polyurethane insulation reformulation. The EU Green Deal anchors national building codes to embodied carbon thresholds that raise unit costs for insulated roof assemblies. Bavarian and North Rhine-Westphalian commercial construction markets absorb these premiums through lifecycle cost optimization frameworks.
Japan
Architects embed solar reflectance targets into envelope performance models during integrated design processes for new commercial construction. METI efficiency standards shape product certification requirements for membrane and coating manufacturers seeking market access. Tokyo municipal authorities require reflective roofing for large-floor-area commercial buildings in designated urban heat island mitigation zones.
Global Cool Roofs Market Competitive Landscape
Channel-controlling players compete with product-specialist players for specification influence across fragmented procurement pathways. The vendor base separates into three tiers: integrated building envelope suppliers with captive insulation-to-membrane platforms, standalone coating and membrane manufacturers with formulation depth, and regional applicator networks with installation certification. Consolidation pressures mount as multi-jurisdictional compliance documentation becomes a prerequisite for national account eligibility. Strategic moves center on backward integration into white pigment supply and upstream control over polymer resin production.
Within the integrated building materials tier, Owens Corning and GAF Materials Corporation exemplify archetypes competing on bundled envelope contracts versus manufacturing scale across multiple polymer chemistries. Sika AG anchors the liquid-applied systems specialist position through applicator network development for complex roof geometries. These three entities represent distinct strategic postures: platform breadth, production scale, and installation-method specialization.
| Leading Market Players |
|---|
| Owens Corning |
| GAF Materials Corporation |
| Sika AG |
| BASF SE |
| 3M |
| PPG Industries |
| CertainTeed Corporation |
| Dow |
| Sherwin-Williams |
| Others |
Supply & Pricing Matrix
Tangshan and Binhai New Area pigment manufacturing clusters in China determine white TiO2 feedstock availability for reflective coating formulators worldwide, with chloride process capacity constraints translating directly into margin compression for downstream membrane and coating producers.
Pricing Analysis
Cost-plus contracts with titanium dioxide indexation dominate procurement between coating manufacturers and pigment suppliers, with three-tier pricing structure across premium, standard, and economy levels separating specification-grade membranes from commodity recoating solutions. Price differentiation hinges on solar reflectance certification tier and volume scale commitments from national account portfolios. Cost compression in economy-grade acrylic emulsions is intensifying because chloride process TiO2 supply tightens in Chinese manufacturing zones. Facility managers with centralized procurement functions demonstrate lowest price sensitivity; regional roofing contractors in competitive bidding environments absorb highest margin pressure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from resin distributors enable regional applicators to stock polymer feedstock without tying working capital, though this financing layer adds cost. Manufacturing concentrates in China, Germany, and the United States, with membrane calendering lines clustered near industrial chemical complexes. Formulation draws from titanium dioxide, polyurethane resins, and reflective ceramic granules as primary inputs. Single-source vulnerability in chloride-process TiO2 from select Chinese provinces presents structural risk. Distribution runs through building materials distributors with contractor-facing yards in metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cool roof penetration remains below saturation across commercial building stock, with regulatory tailwinds from California Title 24 and India's ECBC expansion creating sustained specification pipelines for compliant products.
For Market Incumbents: Insulate membrane margin structures through backward integration into white pigment supply and captive polymer resin production, while accelerating certification documentation for multi-jurisdictional compliance to defend against emerging liquid-applied specialists with faster installation methodologies. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with government facility retrofits in India's warm-humid climate zones offering secondary access; partner with local testing laboratories for BIS compliance documentation to bypass incumbent specification relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-locked infrastructure play because building energy codes harden solar reflectance mandates across major economies; target applicator networks with certified installation credentials in high-growth corridors, watching municipal heat island ordinance adoption velocity as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into White Pigment Supply | Owens Corning and GAF secure TiO2 cost stability against Chinese chloride process volatility. |
| Applicator Network Certification Expansion | Sika AG scales liquid-applied polyurethane deployment through trained crew pipelines in complex roof geometries. |
| Multi-Jurisdictional Compliance Documentation | Membrane suppliers achieve national account eligibility across California Title 24, EU F-Gas, and India ECBC regimes. |
| Green Bond-Linked Installation Partnerships | Property developers bundle cool roof retrofits into sustainability-linked refinancing structures for capital-light deployment. |
| Cool Roof-Agrivoltaic System Convergence | Reflective substrate technology expands addressable square footage into agricultural building-integrated photovoltaic applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with membrane manufacturing executives, coating formulators, commercial roofing contractors, facility management directors, and Bureau of Energy Efficiency officials; and secondary validation through customs trade data, EPA Energy Star certification databases, SEC 10-K filings from listed building materials suppliers, and EU F-Gas Regulation implementation reports. Bottom-up project pipeline tracking across priority metropolitan markets triangulated with top-down building stock modeling.
Forecast inputs include product type segmentation across coatings, membranes, tiles, and shingles; application splits between commercial, industrial, residential, and educational end-uses; and installation type categorization of new construction, retrofit, replacement, and maintenance cycles. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory compliance deadline phasing and urban heat island mitigation policy adoption curves across the analysis window.
Practitioners should monitor municipal ordinance adoption velocity, titanium dioxide supply disruptions, and F-Gas Regulation phase-down schedules for early signals of forecast deviation. Macroeconomic construction cycle downturns, regulatory enforcement softening, or breakthrough cool roof material substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Residential and Commercial Smart Glass Market