
 Construction Camera [Time Lapse Camera] Market | 2026-2036
Construction Camera [Time Lapse Camera] Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Camera [Time Lapse Camera] Market Analysis
Cloud-native image processing and AI-powered analytics is tilting the technology stack away from on-premise DVR systems toward edge-computing camera platforms. EarthCam leverages its proprietary streaming infrastructure to serve stadium and infrastructure megaprojects across North America. OxBlue Corporation anchors its competitive position through vertically integrated hardware-software bundles purpose-built for general contractors. Brinno Inc. specializes in battery-efficient standalone units that dominate residential and small-commercial deployments where power access remains limited.
Construction cameras are ruggedized imaging systems engineered to capture sequential photographic frames at programmable intervals, typically ranging from seconds to hours, with weatherproof enclosures rated for extended outdoor exposure and integrated cellular or Wi-Fi transmission modules. These devices serve primary industrial purposes including progress documentation, dispute resolution, safety compliance verification, and stakeholder remote visibility across multi-year build cycles. Fixed camera installations currently occupy the largest product category due to their permanence on tower cranes and building parapets for duration-of-project coverage. Solar-powered technology segments are expanding fastest as ESG mandates push developers toward off-grid power solutions that eliminate generator dependency and cabling costs. Wireless connectivity architectures command premium positioning by enabling real-time cloud uploads without trenching for fiber or coaxial runs.
The Federal Communications Commission governs spectrum allocation for cellular-enabled construction cameras operating on LTE and emerging 5G bands, while the Occupational Safety and Health Administration mandates fall-protection and electrical-safety standards for aerial-mounted installations above six feet. State-level building codes in California and Florida increasingly require visual documentation of structural milestone completion, directly stimulating procurement of time-lapse systems with timestamp verification. Stakeholders must monitor evolving municipal drone ordinances and FAA small-unmanned-aircraft regulations, as hybrid aerial-ground camera fleets create overlapping jurisdictional complexity that will reshape vendor certification requirements and installation protocols.
Market Dynamics
Cloud-native image processing is compressing deployment timelines and collapsing the traditional hardware-software boundary that once protected on-premise DVR vendors. Edge-computing camera platforms now stream directly to stakeholder dashboards without intermediary infrastructure.
Growth Catalysts
- OSHA Fall-Protection Mandates:Aerial-mounted documentation requirements above six feet in the United States are institutionalizing camera installations as standard safety equipment rather than discretionary tools.
- Cellular Infrastructure Expansion:The Federal Communications Commission's broadband infrastructure push is extending LTE and 5G coverage to remote construction zones previously unreachable by real-time streaming systems.
- ESG-Driven Solar Adoption:Off-grid power mandates from institutional investors are accelerating procurement of solar-powered camera units that eliminate diesel generator dependency and trenching costs.
Market Restraints
- Semiconductor Supply Concentration:Image sensor and cellular modem fabrication concentrates in East Asian foundries, exposing camera manufacturers to geopolitical disruption and allocation delays.
- Cellular Data Cost Volatility:Monthly bandwidth consumption for 4K time-lapse uploads creates recurring operational expenditures that compress margins for budget-conscious general contractors.
- Drone Substitution Threat:FAA Part 107-certified unmanned aerial systems are capturing periodic progress imagery at lower capital cost for projects without continuous monitoring requirements.
Strategic Opportunities
- AI-Powered Safety Analytics:Computer vision algorithms detecting hard-hat violations and perimeter breaches are creating upsell revenue streams beyond raw image capture.
- Texas Megaproject Density:The state's energy and logistics corridor expansions are concentrating demand for multi-camera fleet deployments with unified cloud management.
- California Structural Documentation Mandates:State building codes requiring timestamped milestone verification are converting discretionary purchases into compliance-driven procurement.
Industry Challenges
- Embedded Systems Engineering Talent:The shortage of firmware developers capable of optimizing power consumption for solar-battery camera units is extending product development cycles.
- Legacy VMS Integration Friction:Hybrid deployments combining new cloud-native cameras with existing on-premise video management systems require custom API development that delays installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Camera [Time Lapse Camera] Market |
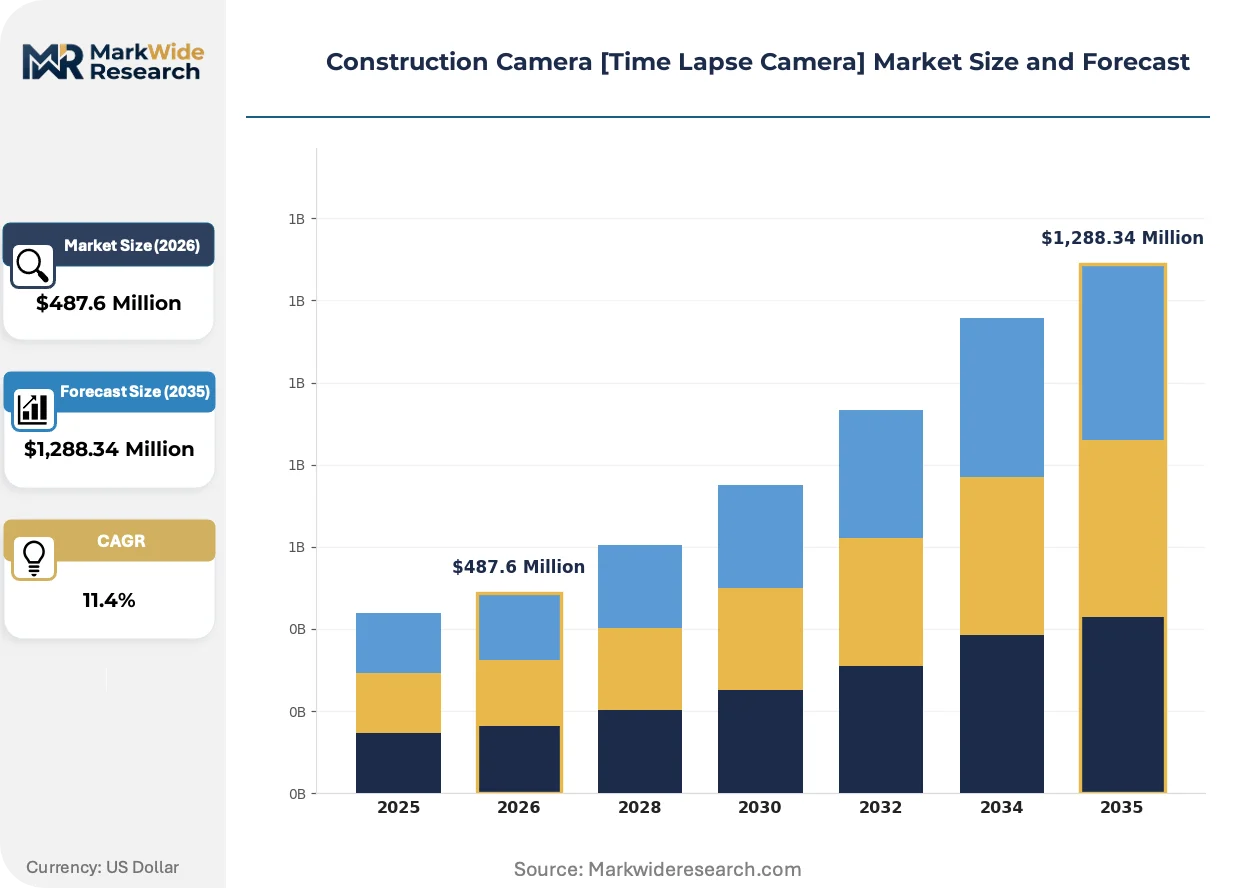
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cameras, Mobile Cameras, Wireless Cameras, Hybrid Cameras Technology: Digital Imaging, High-Definition Video, Remote Monitoring, Solar-Powered End User: Construction Companies, Project Managers, Architects, Surveillance Firms Installation: Ground Mounted, Aerial Mounted, Scaffold Mounted, Vehicle Mounted |
| Companies Covered | EarthCam, OxBlue Corporation, TrueLook Construction Cameras, Brinno Inc., ECAMSECURE, Enlaps, SENSERA Systems, iBEAM Systems, CamDo Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Camera [Time Lapse Camera] Market Emerging Trajectories
Computational photography and machine learning at the edge are redefining what construction cameras capture, process, and transmit without human intervention or centralized infrastructure.
Edge-based AI inference engines are rendering obsolete the practice of uploading raw image streams to cloud servers for batch processing. General contractors in Texas and Florida are deploying cameras with on-device person-detection and equipment-recognition capabilities that trigger alerts without bandwidth consumption. This compression of the analytics pipeline is eliminating latency and reducing cellular data costs by orders of magnitude.
The Federal Communications Commission's spectrum reallocation for 5G mid-band is forcing hardware refresh cycles as LTE-only units face obsolescence in dense urban markets. Stadium and infrastructure megaprojects in California are specifying 5G-native cameras to ensure connectivity resilience through multi-year build cycles. Vendors are responding with modular radio architectures that permit field upgrades rather than full device replacement.
Stakeholder visibility expectations are collapsing the traditional monthly-progress-report format into real-time dashboard access. Institutional investors and public agencies are demanding live URL feeds embedded in capital management platforms rather than periodic email attachments. This behavioral shift is most visible in Florida commercial high-rise developments where lender oversight requirements now specify continuous remote access as a loan condition.
Construction Camera [Time Lapse Camera] Market Segmentation
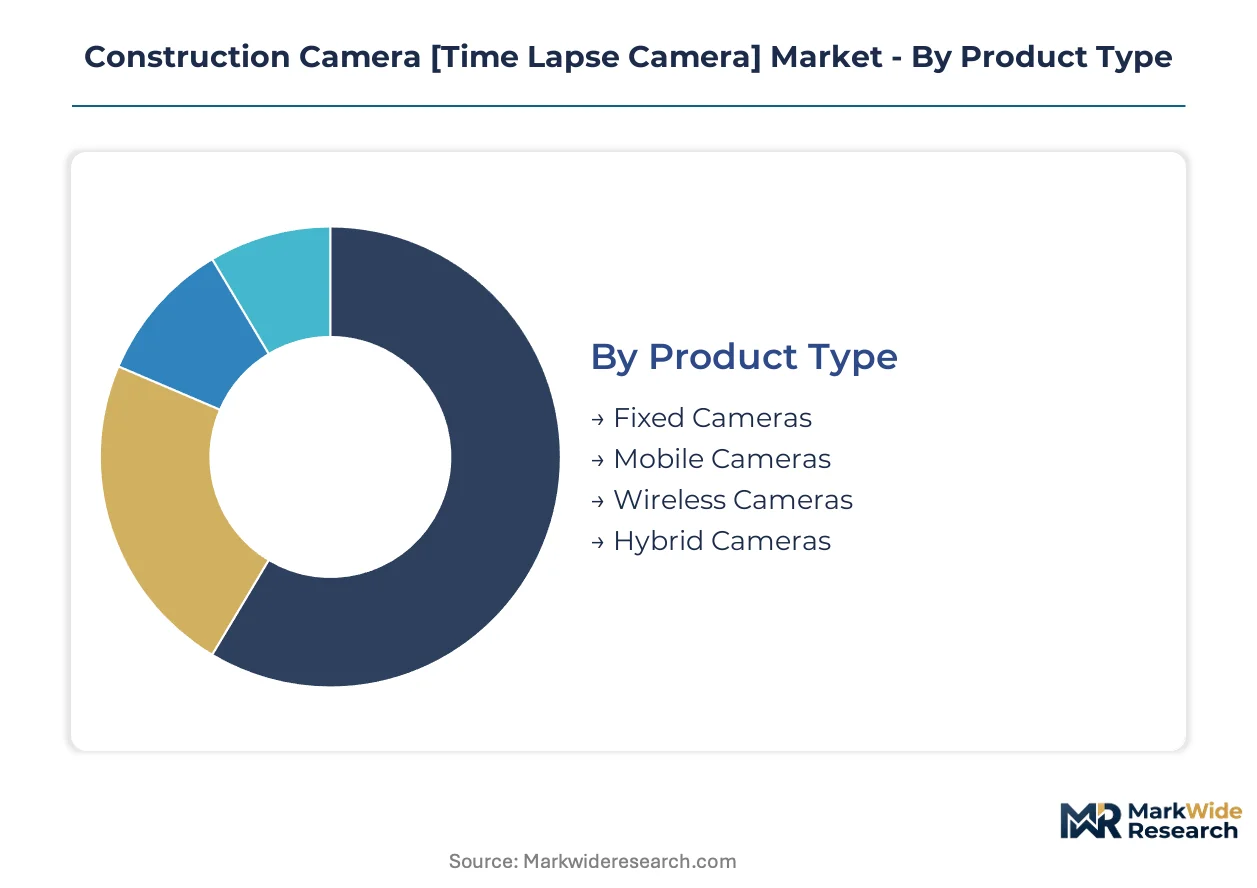
Construction camera procurement decisions cascade through multiple technical and operational dimensions. Product architecture, power systems, user workflows, and mounting constraints each filter the addressable market into distinct competitive battlegrounds with specialized vendor positioning.
Product Type:
Use-case spectrum spans permanent infrastructure documentation to temporary mobility requirements across project phases.
- Fixed Cameras:Weatherproof enclosures with programmable interval capture anchor tower crane and building parapet installations for multi-year build cycles. Demand concentrates in Texas and California megaprojects where duration-of-project coverage justifies capital investment over rental alternatives. OSHA fall-protection mandates above six feet institutionalize these as standard safety equipment rather than discretionary documentation tools.
- Mobile Cameras:Rapid-deployment units with magnetic or clamp-based mounting enable phase-specific coverage without permanent infrastructure. Florida commercial high-rise developments deploy these for foundation-through-structure sequences where crane relocation drives camera repositioning requirements.
- Wireless Cameras:Cellular-enabled streaming modules eliminate trenching for fiber runs, commanding premium positioning in remote construction zones where FCC broadband infrastructure expansion now extends LTE and 5G coverage.
- Hybrid Cameras:Dual-mode units switching between fixed and mobile configurations serve general contractors managing mixed project portfolios with varying documentation intensity.
The dominant share belongs to Fixed Cameras, while Wireless Cameras are closing the gap fastest.
Technology:
Cost tier separation runs from commodity imaging components to integrated power and connectivity systems.
- Digital Imaging:CMOS sensor arrays with programmable compression algorithms form the baseline capture layer across all product categories. Construction Companies in budget-sensitive segments prioritize these for progress documentation without analytics overhead.
- High-Definition Video:4K resolution streams with H.265 encoding satisfy lender and institutional investor visibility requirements where timestamp verification supports dispute resolution. California structural documentation mandates directly stimulate procurement of these specification-grade systems.
- Remote Monitoring:Cloud-native dashboards with multi-stakeholder access replace monthly email attachments with real-time URL feeds embedded in capital management platforms. Florida commercial developments now specify continuous remote access as a loan condition.
- Solar-Powered:Photovoltaic-battery hybrid systems with power-optimized firmware eliminate diesel generator dependency and trenching costs. ESG mandates from institutional investors accelerate procurement fastest in Texas energy corridor expansions where grid access remains limited.
Solar-Powered systems command the steepest expansion trajectory as off-grid mandates displace conventional power architectures.
End User:
Customer type determines procurement authority and technical specification complexity.
- Construction Companies:General contractors with multi-project portfolios drive fleet-standardization decisions favoring unified cloud management platforms across Texas megaproject densities.
- Project Managers:Site-level operators prioritize rapid deployment and stakeholder dashboard access over deep hardware customization.
- Architects:Design-phase documentation requirements emphasize aesthetic milestone capture with broadcast-quality output for portfolio marketing.
- Surveillance Firms:Third-party monitoring services integrate construction cameras into broader security operations with AI-powered safety analytics detecting hard-hat violations and perimeter breaches.
Construction Companies retain procurement volume leadership, though Surveillance Firms are gaining share fastest through bundled security-documentation offerings.
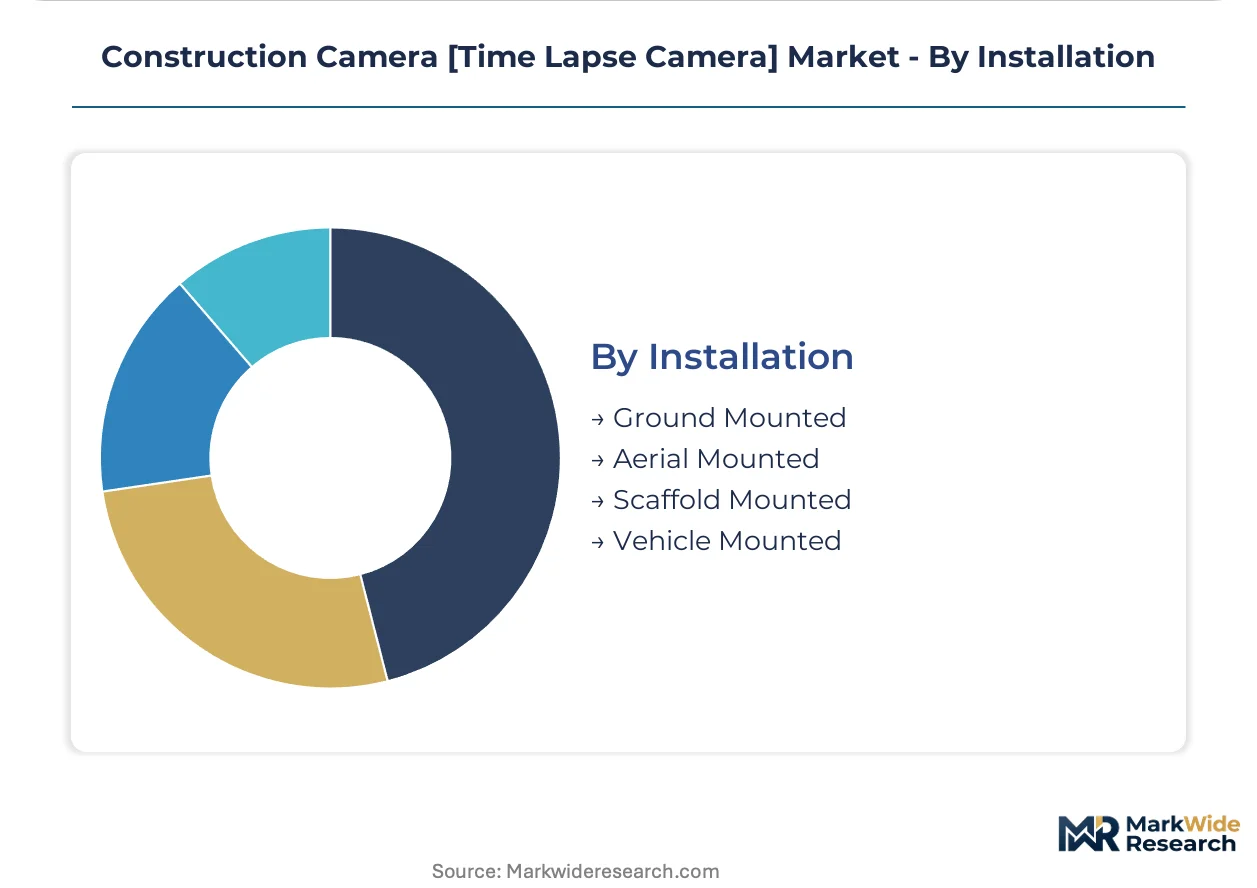
Installation:
Mounting geometry dictates hardware ruggedization requirements and regulatory compliance exposure.
- Ground Mounted:Tripod or pole-based installations below six feet avoid OSHA aerial-work regulations while serving perimeter and staging-area coverage.
- Aerial Mounted:Tower crane and building parapet positions above six feet trigger fall-protection mandates and electrical-safety standards, institutionalizing these as compliance-driven procurement rather than discretionary tools.
- Scaffold Mounted:Temporary work-platform installations serve mid-rise construction phases with rapid repositioning as building envelope advances.
- Vehicle Mounted:Mobile construction equipment integration enables progress documentation during earthwork and infrastructure phases where fixed infrastructure remains absent.
Aerial Mounted installations hold the dominant position, while Vehicle Mounted configurations are climbing the fastest as infrastructure-phase documentation requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German camera component suppliers ship imaging modules to North American system integrators serving Texas energy corridor megaprojects. This transatlantic trade flow reflects Europe's sensor fabrication strength and the United States' construction documentation demand concentration.
United States
Texas, Florida, and California megaprojects drive fleet-scale procurement of cellular-enabled documentation systems. OSHA fall-protection mandates above six feet institutionalize aerial-mounted cameras as standard safety equipment rather than discretionary tools. Dallas-Fort Worth energy logistics expansions concentrate multi-camera deployments with unified cloud management platforms.
Germany
Industrial automation heritage supports precision imaging component manufacturing for export markets. CE marking requirements and EU machinery directives shape ruggedization standards adopted across European construction zones. Bavarian sensor fabricators supply CMOS arrays to system integrators serving global infrastructure documentation demand.
China
Domestic infrastructure investment and Belt and Road construction documentation create parallel demand for cost-optimized time-lapse systems. MIIT radio equipment regulations govern cellular transmission module certification for construction camera deployments. Yangtze River Delta electronics manufacturing clusters produce power-optimized firmware for solar-battery camera units.
United Arab Emirates
NEOM and Red Sea tourism developments specify broadcast-quality documentation for stakeholder visibility and portfolio marketing. Dubai building codes increasingly require visual milestone verification for structural completion certification. Abu Dhabi sovereign wealth-backed developments mandate ESG-compliant solar-powered monitoring to eliminate diesel generator dependency.
Australia
Remote mining and resources infrastructure projects drive demand for off-grid cellular documentation systems beyond fiber reach. TGA-equivalent telecommunications equipment standards govern spectrum use for construction zone connectivity modules. Western Australia Pilbara region iron ore expansions deploy solar-powered cameras across vast sites lacking grid infrastructure.
Construction Camera [Time Lapse Camera] Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure shows moderate concentration at the premium documentation tier with broader fragmentation in commoditized hardware segments. Three strategic archetypes dominate: vertically integrated hardware-software bundlers, cloud-native streaming platform operators, and battery-efficient standalone unit specialists. Competitive moves center on modular radio architectures permitting field upgrades and AI-powered safety analytics upsells beyond raw image capture.
Within the vertically integrated tier, OxBlue Corporation and EarthCam exemplify contrasting approaches to construction documentation dominance. OxBlue anchors its position through purpose-built hardware-software bundles targeting general contractor workflows. EarthCam occupies a position centered on proprietary streaming infrastructure serving stadium and infrastructure megaprojects. Brinno Inc. represents the specialist archetype, with its battery-efficient standalone units dominating residential and small-commercial deployments where power access remains constrained.
| Leading Market Players |
|---|
| EarthCam |
| OxBlue Corporation |
| TrueLook Construction Cameras |
| Brinno Inc. |
| ECAMSECURE |
| Enlaps |
| SENSERA Systems |
| iBEAM Systems |
| CamDo Solutions |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta freight corridors channel CMOS sensor modules from Chinese fabricators to North American system integrators, with container cost volatility translating directly into tiered hardware pricing and procurement timing advantages for volume buyers. This logistics artery concentrates supply-side power among East Asian electronics manufacturers while forcing downstream vendors to absorb or pass through transportation cost swings across premium and standard product tiers.
Pricing Analysis
LTE-to-5G hardware refresh cycles stratify pricing across three technology generations, with legacy cellular units commanding commodity rates and 5G-native platforms capturing premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with FCC modular-approval tiers adding compliance cost layers. Price erosion runs through economy-tier fixed cameras as commoditized imaging components flood distribution channels. General contractors managing Texas megaproject fleets exhibit lowest price sensitivity, while residential developers prioritize economy-tier standalone units.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for cellular modem and image sensor procurement. Component sourcing draws from China, Taiwan, and South Korea for CMOS arrays, power management ICs, and RF transmission modules. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through authorized distributor networks serving system integrators and direct OEM relationships with large general contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across power-architecture, connectivity-protocol, and analytics-integration dimensions creates specialist acquisition opportunities as ESG mandates and AI safety requirements splinter homogeneous demand into niche specifications.
For Market Incumbents: Build switching-cost moats through cloud-platform data gravity and embedded AI analytics that lock general contractor workflows into recurring subscription structures. Deepen backward integration into solar-battery power systems to capture ESG-driven procurement premiums. Counter drone substitution threats by bundling continuous monitoring with predictive safety alerts that episodic aerial surveys cannot replicate. For New Entrants and Emerging Players: Build out white-space presence in vehicle-mounted infrastructure-phase documentation where fixed-camera installation remains impractical during earthwork sequences. Target Western Australia Pilbara region and Texas energy corridor off-grid deployments where solar-native firmware optimization creates differentiation against retrofitted competitors. Pursue direct EPC contractor channel partnerships bypassing established distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates with undermonetized imaging subsidiaries lacking construction-vertical software stacks. Five-to-ten year viability hinges on cloud-platform recurring revenue ratios exceeding hardware transactional dependence. Monitor FAA Part 107 regulatory expansion as signal of drone substitution velocity affecting capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies multi-camera fleet management under single cloud dashboard for Texas megaproject operators. |
| Backward Integration | Captures solar-battery power system margins and accelerates ESG-compliant product certification cycles. |
| Geographic Expansion | Establishes local installation and service presence in California compliance-driven procurement markets. |
| Product Launch | Introduces 5G-native modular radio architectures permitting field upgrade without full device replacement. |
| Strategic Partnership | Links camera data streams to lender capital management platforms as loan condition compliance tools. |
Methodological Framework
Desk research of FCC equipment authorization databases, OSHA regulatory filings, and construction industry trade publications preceded structured interviews with general contractor procurement directors, site safety managers, and cloud platform product leads. Primary fieldwork with Texas and California megaproject operators validated secondary estimates of fleet deployment scale and cellular data consumption patterns. Bottom-up unit economics triangulated against top-down market size reconstructions from customs import data and distributor shipment records.
Assumptions held FCC broadband infrastructure expansion timelines and OSHA enforcement intensity constant across the modeling period, with cellular coverage penetration and fall-protection mandate compliance as primary demand drivers. Segmentation dimensions modeled include product architecture, power system type, connectivity protocol, installation geometry, and end-user procurement authority. CAGRs derived from logistic adoption curves fitted to early-adopter penetration rates in stadium and infrastructure megaprojects. Solar-battery unit cost decline curves and 5G module price erosion trajectories informed technology-transition timing.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud-native platform operators or cellular carrier direct-entry would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Scaffold Technology Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Bulldozer Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Road Roller Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Grader Blades Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Heavy Construction Equipment Rental Market