
 Concrete Cooling Market | 2026-2036
Concrete Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Cooling Market Intelligence
The shift towards modular, containerized cooling systems is broadening access for contractors on remote or temporary project sites. This configuration allows for rapid deployment and scalability compared to traditional fixed plants. KTI-Plersch Kältetechnik GmbH leverages its expertise in custom-engineered solutions for large-scale projects. Meanwhile, Fujian Snowman Co., Ltd. specializes in ice-making equipment, a critical component within bundled cooling packages.
Concrete cooling involves methods to reduce the temperature of concrete mixes before and after placement, controlling the heat of hydration. This process is critical for preventing thermal cracking in mass pours, ensuring structural integrity by maintaining a core temperature below 70°C. Within the technology segment, chilled water systems are common for general use, while flake or block ice offers more intensive cooling for demanding applications like dam construction. On-site delivery models dominate for large-scale projects, where logistical efficiency is paramount.
Construction standards, such as those from the American Concrete Institute (ACI), dictate the need for temperature control in specific applications. Environmental regulations like the EU's F-Gas Regulation and the US EPA's rules on refrigerants directly impact equipment design and operating costs. These frameworks compel manufacturers to adopt lower-GWP (Global Warming Potential) refrigerants. The key decision for project managers becomes balancing initial equipment cost against long-term compliance and operational efficiency.
Market Dynamics
The concrete cooling market's core dynamic is the tension between the massive scale of modern infrastructure projects and the tightening grip of environmental regulations. Demand for mass concrete in dams and nuclear facilities necessitates powerful cooling, while rules like the EU F-Gas Regulation dictate which technologies are viable.
Growth Catalysts
- Infrastructure Megaprojects:Investment in large-scale infrastructure, particularly giga-projects in Saudi Arabia and the broader Middle East, creates sustained demand for high-capacity concrete cooling systems to manage mass pours in extreme climates.
- Stringent Construction Standards:Engineering codes, such as those from the American Concrete Institute (ACI), mandate strict temperature control to prevent thermal cracking in mass concrete, making cooling a non-negotiable process for ensuring structural integrity.
- Nuclear Power Plant Construction:The construction and expansion of nuclear power plants, which require thick, high-quality concrete containment structures, serve as a significant catalyst for advanced, reliable cooling solutions.
Market Restraints
- High Initial Capital Outlay:The substantial upfront investment required for on-site ice plants, chilled water systems, and aggregate cooling equipment presents a significant barrier to entry for small and mid-sized construction contractors.
- Refrigerant Regulations:The global phase-down of high-GWP refrigerants under frameworks like the US EPA's SNAP program and the EU F-Gas Regulation increases equipment costs and complexity for manufacturers and end-users.
- Logistical and Site Constraints:The deployment of cooling systems, especially in remote or space-constrained project sites, poses significant logistical challenges related to water supply, power, and equipment footprint.
Strategic Opportunities
- Modular System Deployment:Containerized, plug-and-play cooling systems offer a key opportunity to serve temporary or remote projects, providing contractors with scalable and rapidly deployable solutions without the need for permanent plant construction.
- Low-GWP Refrigerant Retrofits:A significant service-based opportunity exists in retrofitting and upgrading existing concrete cooling plants to comply with new environmental regulations, replacing older HFC-based systems with compliant alternatives.
- Expansion in Southeast Asia:Rapid urbanization and infrastructure development in countries like Indonesia and Vietnam present underpenetrated markets for concrete cooling technologies, driven by dam, port, and high-rise construction.
Industry Challenges
- Specialized Operator Shortage:A scarcity of technicians and engineers trained to operate and maintain sophisticated concrete cooling systems, particularly in emerging markets, can lead to operational inefficiencies and equipment downtime.
- Project-Specific Engineering Demands:The need to custom-engineer cooling solutions for each project's unique climate, concrete mix design, and pour schedule adds complexity and cost, limiting the use of standardized equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Cooling Market |
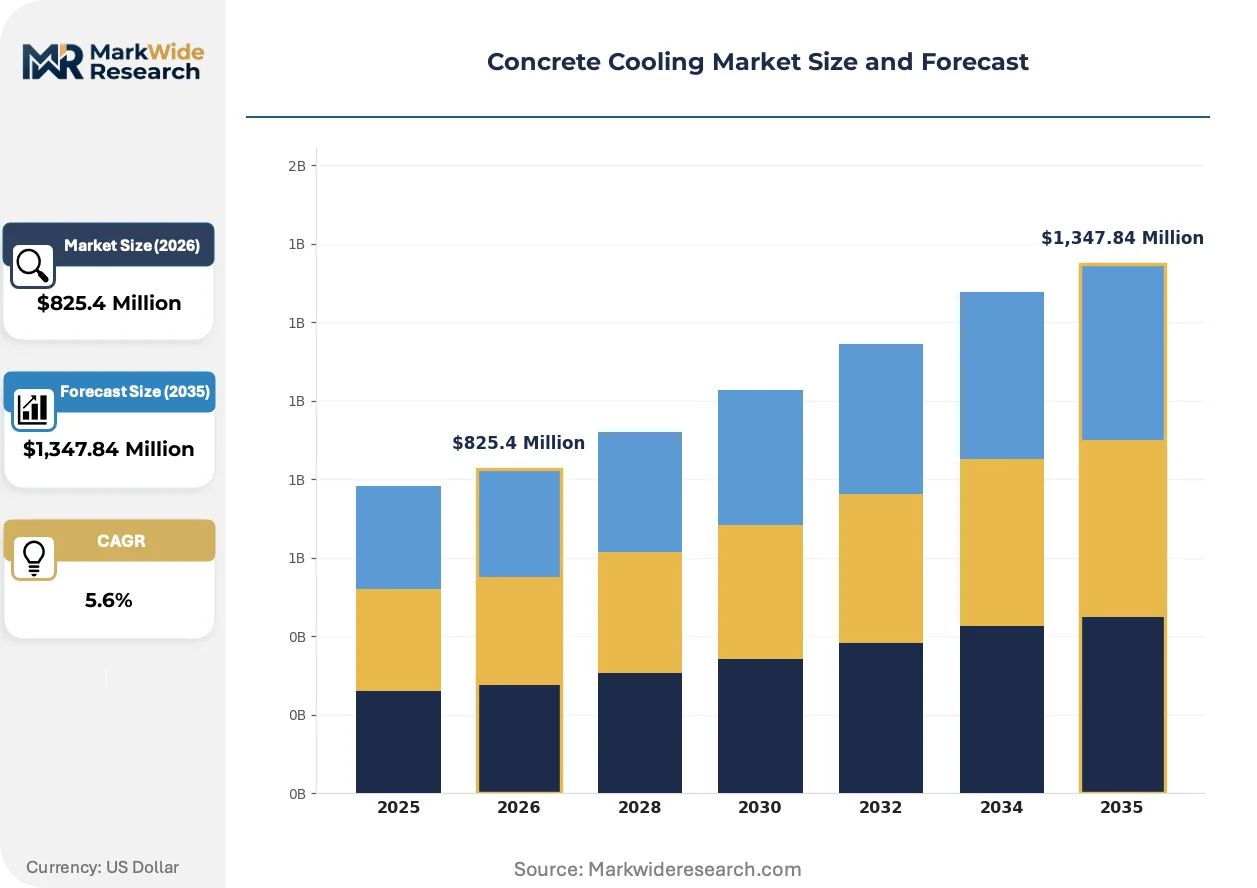
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,347.84 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chilled Water, Ice, Refrigerated Brine, Evaporative Cooling Application: Large-Scale Projects, Road Construction, Bridge Construction, Residential Projects End User: Contractors, Construction Companies, Engineers, Project Managers Delivery Mode: On-Site Delivery, Off-Site Delivery, Direct Supply, Rental Services |
| Companies Covered | KTI-Plersch Kältetechnik GmbH, Fujian Snowman Co., Ltd., Coldcrete Inc., ConCool LLC, Kirloskar Pneumatic Company Limited, Lintec Germany GmbH, Icelings, North Star Ice Equipment Corporation, Focusun Refrigeration Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Cooling Market Strategic Shifts & Innovations
Technological evolution in the concrete cooling market centers on integrating digital controls with more sustainable refrigeration hardware. This shift is a direct response to the dual pressures of achieving precise temperature control in complex pours and complying with stringent environmental mandates on refrigerants.
Advanced digital control systems integrated with IoT sensors provide real-time monitoring of concrete temperature and ambient conditions. Large-scale infrastructure contractors are adopting these platforms to automate cooling adjustments and maintain compliance with strict temperature differential limits. The integration of these smart controls with mechanical cooling equipment is absorbing the operational risk associated with manual monitoring, improving quality assurance on critical projects.
The EU F-Gas Regulation mandates a sharp reduction in the use of high-GWP hydrofluorocarbons. This regulatory pressure is forcing equipment manufacturers to re-engineer chillers and ice plants to use natural refrigerants like ammonia or CO2. The industrial refrigeration sector, a key supplier to this market, is most affected, accelerating innovation in compressor and heat exchanger designs compatible with these environmentally superior alternatives.
Contractors are exhibiting a clear behavioral shift toward rental and leasing models for cooling equipment, moving away from direct capital purchases. This trend disrupts traditional equipment sales channels, creating a larger role for specialized rental fleet operators who can provide turnkey cooling services. This procurement model is most visible in the Middle East, where project-based demand requires flexible and scalable cooling capacity without long-term asset ownership.
Concrete Cooling Market Segmentation
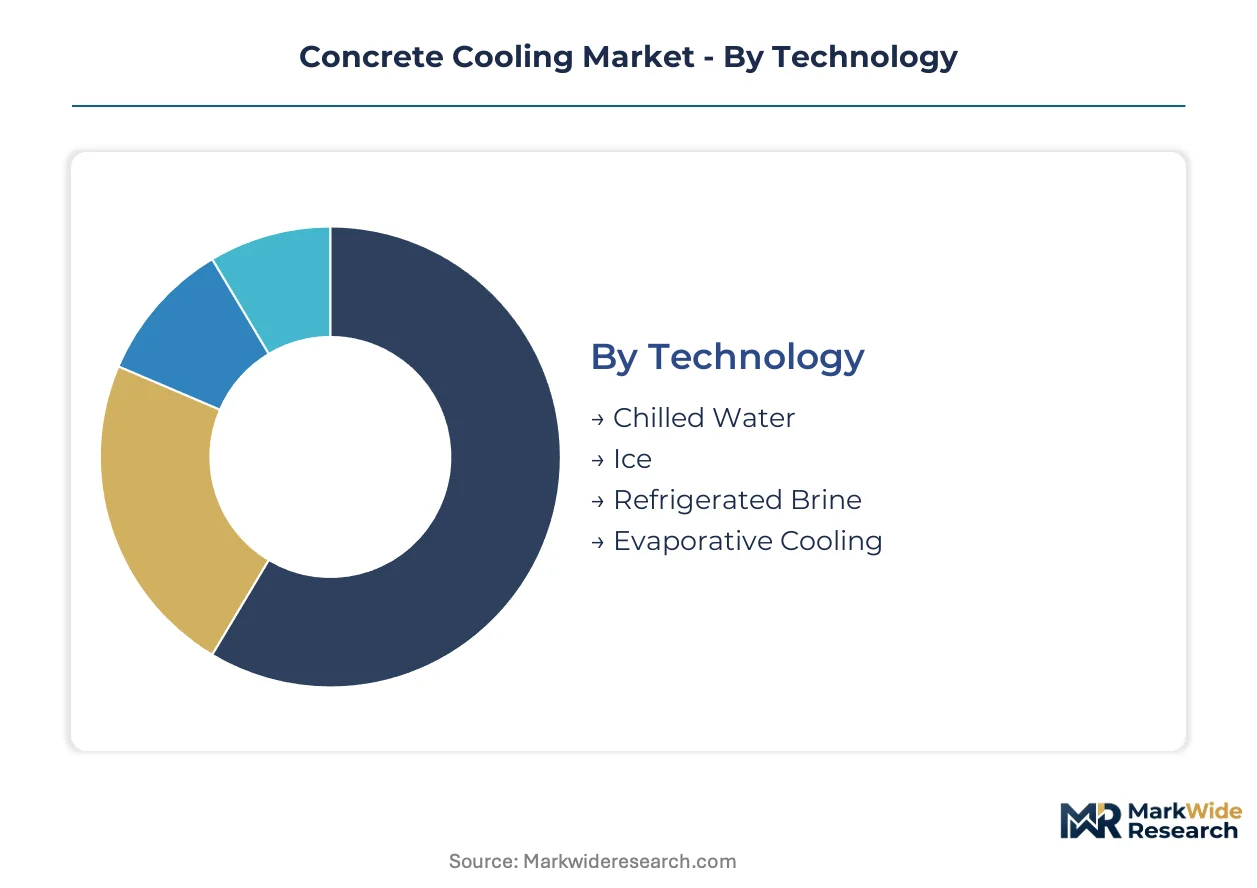
The concrete cooling market's segmentation reflects the diverse technical requirements and operational models across construction projects. Analyzing these distinct categories provides a clearer understanding of demand drivers and technological preferences. This granular view helps stakeholders tailor solutions for specific project scales and environmental conditions.
Technology:
The choice of concrete cooling technology often depends on the required integration depth into the construction process and the intensity of cooling needed.
- Chilled Water:This method involves circulating cold water through aggregates or mixing it directly into the concrete batch. Chilled water systems are widely adopted for general construction projects, particularly where moderate temperature reduction is sufficient for structural integrity.
- Ice:Flake or block ice is directly added to the concrete mix, offering a highly effective and rapid cooling solution due to its latent heat of fusion. Demand for ice-based cooling concentrates in demanding applications like dam construction and large infrastructure projects in hot climates, such as Saudi Arabia.
- Refrigerated Brine:Refrigerated brine systems cool aggregates or water using a secondary coolant loop, suitable for precise temperature control in specialized applications.
- Evaporative Cooling:This technique cools aggregates or water through the evaporation of water, often employed in conjunction with other methods for pre-cooling.
Volume placements concentrate in Chilled Water systems; the faster expansion belongs to Ice-based solutions.
Application:
Concrete cooling applications are primarily differentiated by the scale of projects and their specific thermal requirements for structural durability.
- Large-Scale Projects:These encompass massive infrastructure developments like dams, nuclear power plants, and giga-projects requiring extensive mass concrete pours. Such projects necessitate advanced cooling systems to manage significant heat of hydration and prevent thermal cracking, ensuring long-term structural integrity.
- Road Construction:Cooling methods in road construction focus on controlling concrete temperature during paving to optimize setting times and prevent premature cracking. This application often uses simpler, more mobile cooling solutions.
- Bridge Construction:Bridge projects, especially those involving large concrete sections or complex geometries, demand precise temperature control to meet stringent engineering standards. This ensures the structural performance of critical load-bearing elements.
- Residential Projects:Concrete cooling in residential construction is less common but can be employed for specialized foundations or structures in extreme heat conditions.
The highest demand originates from Large-Scale Projects, while Bridge Construction shows significant growth in specialized cooling needs.
End User:
End users of concrete cooling solutions are categorized by their decision-making authority and operational responsibility within construction workflows.
- Contractors:General contractors and specialized concrete contractors directly implement cooling strategies and operate the equipment on-site. Their procurement decisions balance equipment cost with operational efficiency and project timelines.
- Construction Companies:These entities oversee multiple projects and often establish company-wide standards for concrete temperature control. They influence the adoption of specific cooling technologies and preferred suppliers.
- Engineers:Structural engineers and civil engineers specify the temperature control requirements for concrete mixes, influencing the choice of cooling methods to meet design specifications.
- Project Managers:Project managers coordinate all aspects of a construction project, including the integration and scheduling of concrete cooling operations.
Contractors represent the largest purchasing segment, with Construction Companies increasingly centralizing procurement decisions.
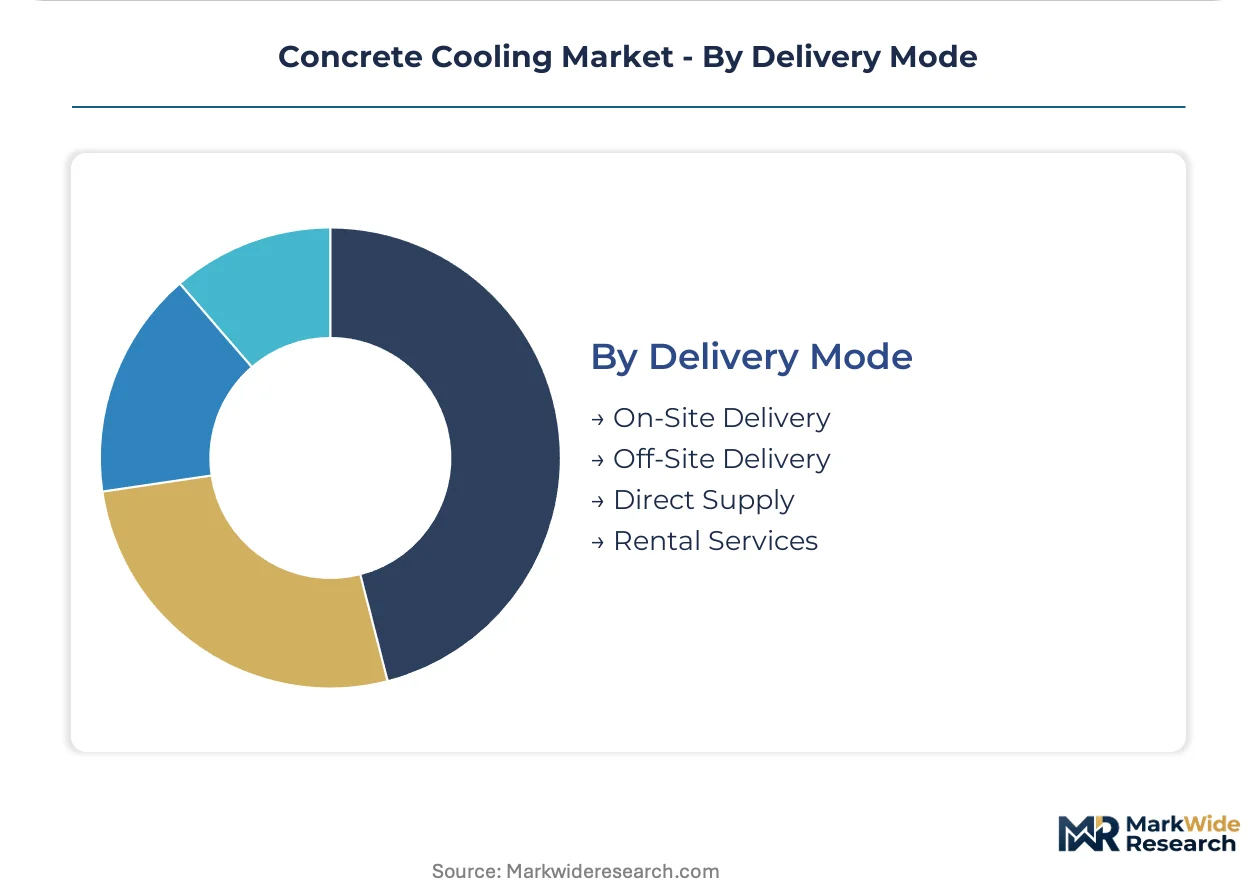
Delivery Mode:
Delivery modes for concrete cooling equipment are shaped by logistical efficiency and asset ownership preferences of project stakeholders.
- On-Site Delivery:This model involves setting up cooling plants directly at the construction site, common for large, long-duration projects. Logistical efficiency is paramount for continuous mass concrete pours, particularly in remote locations.
- Rental Services:Contractors lease cooling equipment for specific project durations, avoiding large capital investments. This model is gaining traction in the Middle East for its flexibility and scalability, reducing upfront capital outlay.
- Off-Site Delivery:Equipment or pre-cooled materials are prepared at a central facility and transported to the construction site, suitable for smaller projects.
- Direct Supply:Manufacturers or distributors sell cooling equipment directly to construction companies for permanent installation or long-term ownership.
On-Site Delivery remains critical for large infrastructure, while Rental Services are rapidly expanding due to project-based demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global concrete cooling market exhibits a divide between regions driving massive infrastructure consumption and those focusing on advanced cooling technology production. Demand concentrates in hot climates with extensive construction projects. Regulatory frameworks in developed economies influence equipment innovation and deployment strategies.
Saudi Arabia
Saudi Arabia drives significant demand for concrete cooling, fueled by ambitious giga-projects and extreme desert climate. National infrastructure development plans mandate precise temperature control for mass concrete pours. Construction activities in Riyadh and the Eastern Province require high-capacity cooling systems.
United States
The United States market requires concrete cooling for extensive infrastructure projects and nuclear power plant construction. American Concrete Institute (ACI) standards strictly govern temperature control, preventing thermal cracking. Major construction hubs in California and Texas implement advanced cooling systems for critical civil engineering works.
Germany
Germany's demand for concrete cooling stems from high-quality civil engineering and stringent construction specifications. The EU F-Gas Regulation directly influences equipment design, compelling lower-GWP refrigerant adoption. Industrial centers in Bavaria and North Rhine-Westphalia deploy sophisticated cooling solutions.
India
Rapid urbanization and extensive infrastructure development across India generate substantial demand for concrete cooling technologies. The Bureau of Indian Standards (BIS) guides concrete mix design and placement, including temperature control. Mega projects in Maharashtra and Gujarat increasingly utilize ice-based cooling for dams.
Indonesia
Indonesia's infrastructure boom, particularly in port and high-rise construction, drives significant concrete cooling requirements. National building codes from the Ministry of Public Works and Housing enforce quality standards for large concrete structures. Projects in Jakarta and Surabaya leverage cooling systems to manage heat in tropical conditions.
Concrete Cooling Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the concrete cooling market, creating a tiered competitive structure. This market includes large industrial refrigeration providers alongside niche manufacturers specializing in concrete-specific cooling technologies. Key strategic archetypes include integrated solution providers, specialized equipment manufacturers, and flexible rental service operators. Companies primarily engage in portfolio diversification and geographic expansion to capture market share across different project scales.
Specialists in custom-engineered solutions, such as Germany-based KTI-Plersch Kältetechnik GmbH, exemplify providers for large-scale, complex infrastructure projects globally. Fujian Snowman Co., Ltd., a China-based entity, represents manufacturers focused on critical ice-making equipment, a core component within comprehensive cooling packages. North Star Ice Equipment Corporation, an American manufacturer, occupies a position among suppliers of high-capacity ice generation systems, essential for demanding concrete applications requiring intensive temperature reduction.
| Leading Market Players |
|---|
| KTI-Plersch Kältetechnik GmbH |
| Fujian Snowman Co., Ltd. |
| Coldcrete Inc. |
| ConCool LLC |
| Kirloskar Pneumatic Company Limited |
| Lintec Germany GmbH |
| Icelings |
| North Star Ice Equipment Corporation |
| Focusun Refrigeration Corporation |
| Others |
Cost & Logistics Intelligence
Global copper price fluctuations directly impact the manufacturing costs of concrete cooling equipment, cascading through the supply chain to influence final equipment pricing. Energy benchmarks also shape operational costs, affecting rental rates and project-based service charges.
Pricing Analysis
Cost-down pressure on standard concrete cooling equipment accelerates due to increased competition and commoditization of basic chilled water systems. Project-based contract pricing dominates for large infrastructure, while rental services utilize a lease model. Customization level, after-sales service, and compliance with EU F-Gas regulations drive price differentiation. Contractors on mega-projects prioritize reliability and are less price-sensitive for advanced systems, whereas smaller contractors exhibit high sensitivity to initial capital outlay.
Supply Chain Analysis
Stringent quality certifications and compliance with environmental standards, such as the EU F-Gas Regulation, gate the supply of advanced concrete cooling components. Manufacturing concentrates in Germany for engineered solutions, China for ice-making equipment, and the United States for high-capacity systems. The supply chain draws from specialized compressors, heat exchangers, and low-GWP refrigerants. Regulatory restrictions on high-GWP refrigerants pose a significant structural risk, while distribution runs through direct sales for large infrastructure projects and specialized rental operators for flexible capacity needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concrete cooling market is fundamentally a cost-of-compliance narrative, where regulations like the EU F-Gas Regulation create a significant barrier-to-entry moat for manufacturers and service providers offering compliant, low-GWP solutions. This regulatory framework drives innovation and market segmentation.
For Market Incumbents: Deploy continuous R&D investment into natural refrigerant technologies like ammonia and CO2 to maintain a competitive edge against evolving GWP limits. Consolidate market position by acquiring specialized rental fleet operators, thereby controlling critical distribution channels and offering flexible solutions to contractors. This strategy mitigates threats from new modular system providers and enhances service integration.
For New Entrants and Emerging Players: Enter via specialized modular, containerized cooling systems targeting remote or temporary project sites in underserved markets like Southeast Asia. Focus on offering turnkey rental packages that integrate advanced digital controls and utilize low-GWP refrigerants, appealing to contractors seeking rapid deployment and regulatory compliance. This approach bypasses the high capital outlay of traditional fixed plants.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking long-term viability in infrastructure-driven markets over the next decade. Target vertically integrated providers of low-GWP cooling equipment, especially those with established rental fleets and strong engineering capabilities for custom solutions. A key signal to watch is the accelerated adoption rate of natural refrigerant systems in new giga-projects across the Middle East and Asia.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Low-GWP Refrigerant R&D | Drives compliance with environmental regulations and secures future market access. |
| Expand Modular Rental Fleet | Offers flexible, scalable solutions to contractors on temporary or remote sites. |
| Acquire Specialized Engineering Firms | Enhances capability for custom-engineered solutions required by complex projects. |
| Target Emerging Infrastructure Markets | Captures demand from rapid urbanization in regions like Southeast Asia. |
| Integrate Digital Monitoring Systems | Improves operational efficiency and ensures precise temperature control for critical pours. |
Research Approach
Independent corroboration across project managers, concrete contractors, and equipment manufacturers underwrites the qualitative findings of this analysis. Primary interviews with these industry stakeholders were combined with rigorous secondary validation. Data sources included American Concrete Institute (ACI) standards, EU F-Gas Regulation documents, and national infrastructure development reports. A bottom-up and top-down triangulation approach ensured data accuracy and market sizing integrity.
The forecast window was anchored to historical reference periods, establishing a baseline for future projections across the analysis window. This analytical framework modeled market dynamics by technology, application, end user, delivery mode, and refrigerant type. Compound Annual Growth Rates (CAGRs) were derived through trend analysis and expert consensus, incorporating key inputs like global infrastructure spending forecasts and regulatory compliance timelines.
Revisions become necessary when significant geopolitical instability impacts infrastructure spending or rapid shifts in refrigerant technology disrupt existing market paradigms. Forecasts reflect assumptions about stable regulatory environments and consistent project pipelines. A model refresh is warranted upon material change in global infrastructure investment trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Concrete Aggregate Market