
 Artificial Marble Market | 2026-2036
Artificial Marble Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Marble Market Analysis
A capital-intensity divergence between automated continuous-casting lines and conventional batch presses is redrawing competitive tiers in artificial marble. Cosentino Group leverages vertically integrated quartz sourcing across Spain to sustain margin control from raw material to finished slab. Cambria anchors its position through captive Minnesota quartz reserves and domestic fabrication capacity. Hyundai L&C competes on scale in the Asia-Pacific basin with dedicated engineered stone complexes in South Korea.
Artificial marble denotes a composite surfacing material comprising mineral fillers such as calcium carbonate or aluminum trihydrate bound with unsaturated polyester resin or acrylic polymers, pressed and cured into dimensionally stable slabs or custom shapes. Engineered stone commands the dominant volume position due to quartz-binder durability in high-traffic commercial environments. Solid surface formulations retain growth momentum in healthcare and laboratory applications where seamless repair and thermoformability matter. The countertops form factor captures the largest margin pool, though slab formats gain traction among fabricators serving bespoke hospitality installations.
EPA standards on volatile organic compound emissions from resin systems constrain formulation choices for US manufacturers, while REACH restrictions on styrene content in Europe push substitution toward low-VOC acrylic binders. China's GB standards on building material radon emission classify artificial marble for interior use based on filler mineralogy. Stakeholders must track regulatory divergence on resin chemistry, as compliance investments in one jurisdiction rarely transfer to another, fragmenting supplier qualification requirements across major demand centers.
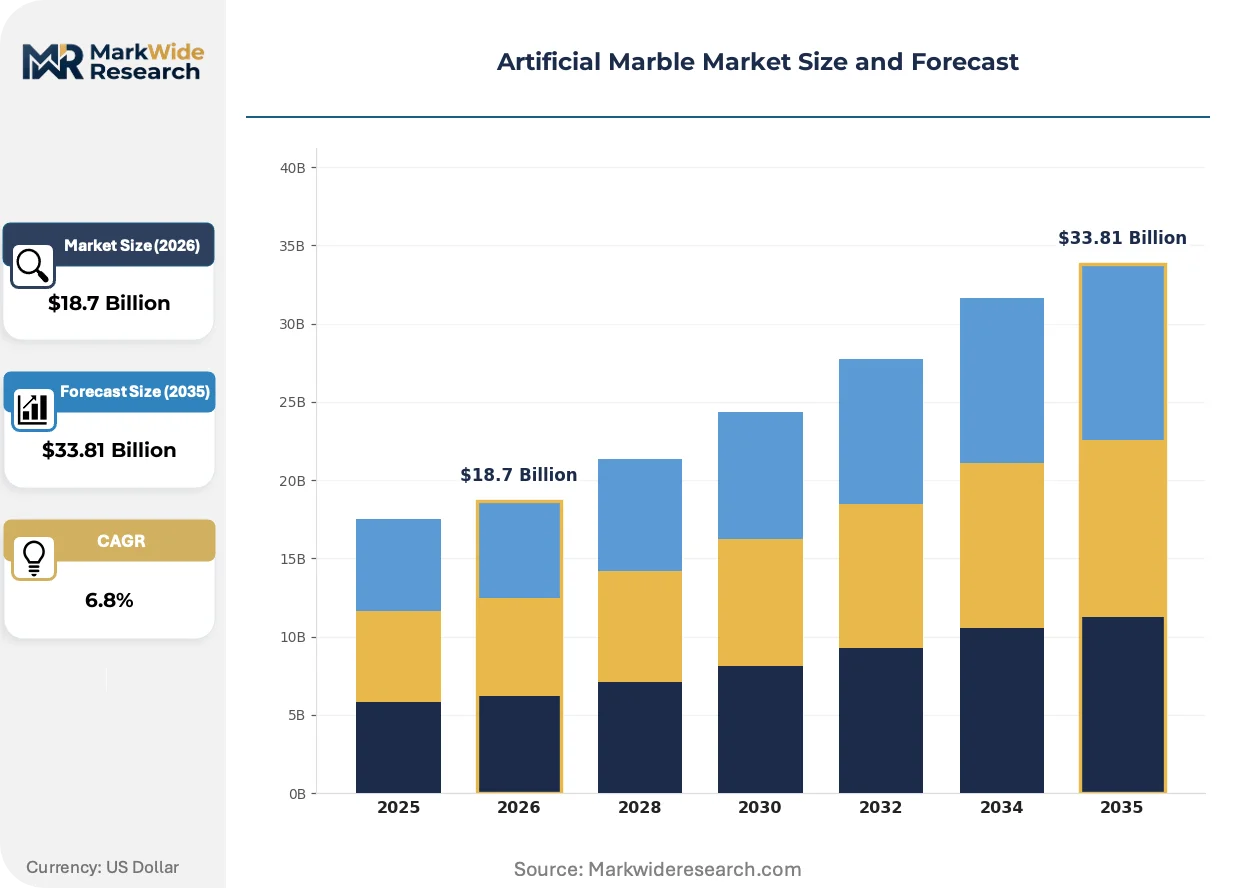
Market Dynamics
Resin chemistry standard divergence between EPA VOC limits, REACH styrene restrictions, and China's GB radon classifications is fragmenting supplier qualification requirements across major demand centers. Manufacturers now face parallel compliance investments that rarely transfer between jurisdictions.
Growth Catalysts
- Hospitality renovation wave:Asia-Pacific hotel refurbishment cycles are accelerating specification of engineered stone surfaces for lobby and bathroom installations, particularly in China's tier-one urban commercial corridors.
- REACH low-VOC transition:European styrene content restrictions are accelerating substitution toward acrylic binders, creating first-mover advantages for resin formulators with compliant product lines.
- Continuous-casting automation:Automated slab production lines are compressing unit costs and enabling dimensional consistency that batch presses cannot match, reshaping competitive tiers.
Market Restraints
- Petrochemical resin volatility:Unsaturated polyester and acrylic polymer feedstock costs fluctuate with crude oil derivatives, compressing margins for producers without captive chemical supply.
- Quartz sourcing concentration:High-purity silica deposits cluster in specific geographies, creating supply security risks for engineered stone manufacturers dependent on imported mineral filler.
- Radon emission classification:China's GB standards restrict interior applications based on filler mineralogy, eliminating certain calcium carbonate formulations from commercial building projects.
Strategic Opportunities
- Healthcare solid surface penetration:Seamless repair and thermoformability characteristics position acrylic-based formulations for expansion in hospital and laboratory surface applications.
- India commercial construction:Urban infrastructure investment under BIS building material standards creates demand for certified engineered stone in retail and office developments.
- EU Green Deal embodied carbon tracking:CSRD reporting requirements favor suppliers with verified low-carbon resin systems and regional mineral sourcing documentation.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel EPA, REACH, and GB compliance testing extends product qualification cycles, delaying market entry for reformulated resin systems.
- Continuous-casting capex barriers:Automated production lines require capital commitments that conventional batch press operators cannot finance, consolidating capacity among scale players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Marble Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Surface, Engineered Stone, Reinforced Marble, Cultured Marble End User: Residential, Commercial, Industrial, Hospitality Form: Slabs, Tiles, Countertops, Sinks Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | LX Hausys, Vicostone, Cosentino Group, Compac, Cambria, Caesarstone, Hyundai L&C, Lotte Advanced Materials, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Marble Market Emerging Trajectories
Digital slab design tools and low-carbon resin chemistry are converging to reshape specification workflows and embodied carbon accounting across commercial construction procurement.
Photorealistic digital printing on engineered stone surfaces is supplanting traditional veining techniques in hospitality and residential specification. Interior designers specify digitally rendered marble and granite patterns for bespoke installations. This technology is compressing lead times for custom aesthetics while reducing reliance on rare natural stone varieties.
REACH restrictions on styrene monomer content are forcing reformulation toward methyl methacrylate and vinyl ester alternatives across European production. Resin suppliers invest in pilot plants for low-VOC acrylic systems. Engineered stone manufacturers serving EU commercial projects face raw material cost step-ups during the transition window.
Specification decisions now embed embodied carbon verification as a secondary selection criterion alongside performance and aesthetics. Procurement teams in Nordic commercial construction markets request Environmental Product Declarations and regional sourcing documentation. This behavioral shift advantages suppliers with vertically integrated mineral extraction and captive resin production.
Artificial Marble Market Segmentation
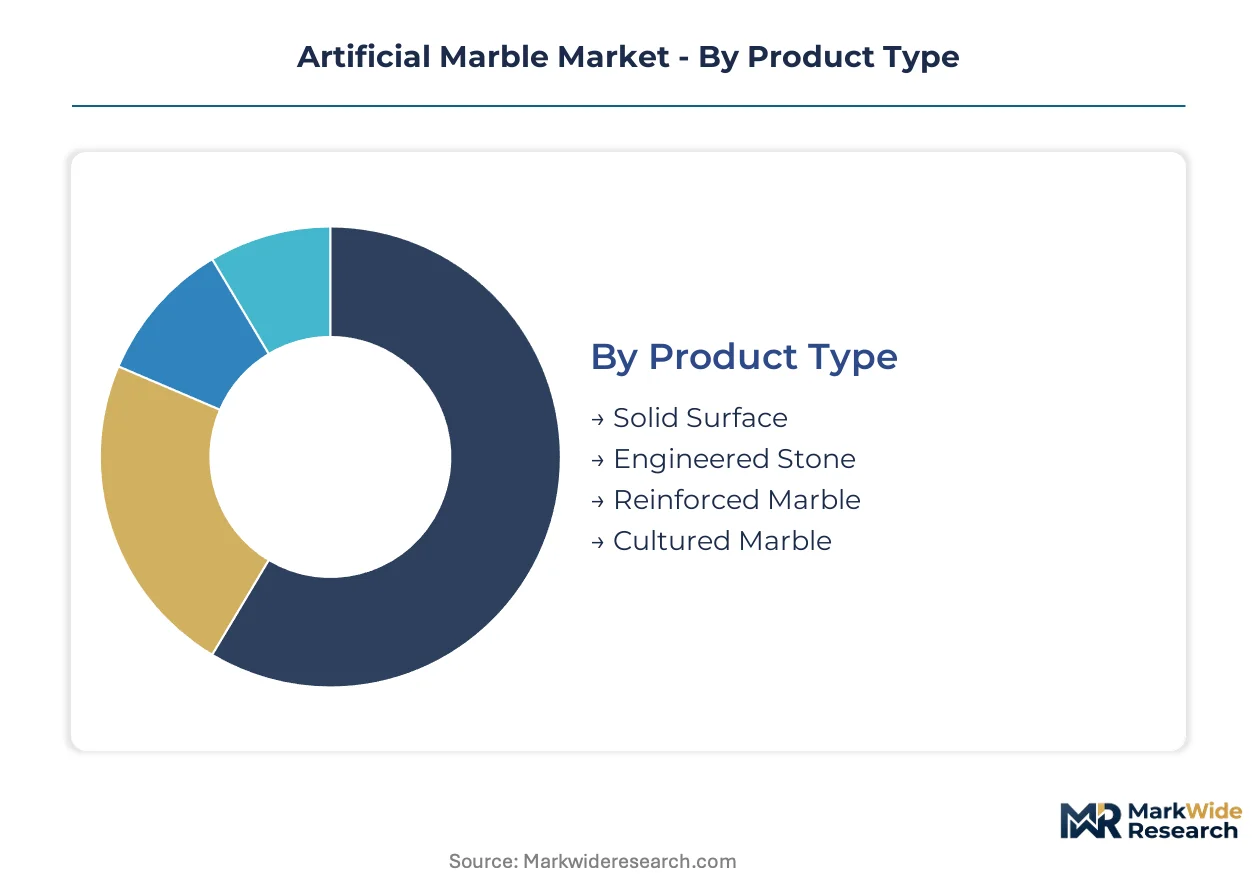
Artificial marble segmentation reveals how resin chemistry, mineral filler composition, and curing technology create distinct performance tiers. Specification decisions hinge on traffic intensity, repair requirements, and regulatory compliance thresholds rather than aesthetics alone.
Product Type:
REACH styrene restrictions and EPA VOC limits fragment qualification requirements across resin systems, forcing manufacturers to maintain parallel formulation portfolios.
- Engineered Stone:Quartz-binder composites dominate high-traffic commercial installations. China's tier-one urban corridors specify this grade for hospitality lobbies and retail atriums where abrasion resistance outweighs first-cost premiums. GB radon emission classifications favor quartz mineralogy over calcium carbonate alternatives.
- Solid Surface:Acrylic polymer matrices enable seamless repair and thermoformability. Hospital and laboratory specification in the US and Europe prioritizes this grade for infection control surfaces that require periodic resurfacing. Low-VOC acrylic binders satisfy REACH transition timelines.
- Reinforced Marble:Polyester-resin systems with enhanced fiber backing for structural applications.
- Cultured Marble:Cast marble-resin composites for bathroom fixtures and residential vanity tops.
Established volume favors engineered stone; emerging adoption favors solid surface.
End User:
Cost-to-performance ratios diverge sharply between residential renovation budgets and commercial lifecycle accounting.
- Commercial:Office developments and retail chains specify engineered stone for 15-20 year depreciation schedules. India's BIS-certified projects under urban infrastructure programs create qualified demand corridors. Procurement teams embed embodied carbon verification alongside performance metrics.
- Hospitality:Hotel refurbishment cycles across Asia-Pacific accelerate engineered stone specification for lobby and bathroom installations. Digital printing technology compresses lead times for bespoke marble-patterned surfaces in luxury properties.
- Residential:Kitchen and bath renovation demand concentrates in owner-occupied housing segments.
- Industrial:Chemical-resistant formulations serve manufacturing environments with spill exposure.
Commercial captures the dominant margin pool; hospitality climbs the fastest.
Form:
Dimensional standardization versus custom fabrication shapes supply chain configuration and lead time economics.
- Countertops:Pre-fabricated dimensions dominate residential specification through big-box retail channels. US and European fabricators maintain regional template libraries that compress installation timelines. Continuous-casting automation enables thickness consistency that batch presses cannot match.
- Slabs:Full-format material serves bespoke hospitality and high-end residential projects requiring field-fabricated dimensions. Fabricators serving China's urban commercial corridors prefer slab formats for complex cutouts and waterfall edges.
- Tiles:Standardized dimensions for flooring and wall cladding in volume construction.
- Sinks:Integrated basin-vanity combinations for residential bathroom specification.
Fabrication economics favor countertops; design flexibility favors slabs.
Distribution Channel:
Customer technical sophistication and project scale determine channel selection and service intensity requirements.
- Direct Sales:Large-scale commercial and hospitality projects route through manufacturer-direct specification teams. Cosentino Group and Cambria maintain captive sales organizations for architect and designer relationships. Contract volume justifies dedicated project management and templating services.
- Specialty Stores:Independent fabricators and kitchen-bath showrooms serve residential renovation with design consultation and installation coordination. This channel captures premium pricing through bundled service offerings.
- Wholesale:Distributor networks supply regional fabricators with inventory buffer and credit terms.
- Online Retail:Sample ordering and small-format direct sales for DIY renovation segments.
Project scale favors direct sales; service bundling favors specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese urban commercial corridors while European fabricators absorb REACH compliance cost step-ups. German and Spanish producers command premium positioning through low-VOC acrylic binder portfolios. Indian specification lags on BIS certification penetration.
China
Tier-one urban commercial construction in Shanghai, Beijing, and Shenzhen drives engineered stone specification for hospitality lobbies and retail atriums. GB standards on building material radon emission classify artificial marble for interior use based on filler mineralogy. The Yangtze River Delta hosts dedicated engineered stone complexes serving domestic and export fabrication demand.
United States
Residential kitchen renovation through big-box retail channels sustains countertop volume, while commercial projects embed 15-20 year lifecycle depreciation schedules. EPA VOC emission standards from resin systems constrain formulation choices for domestic manufacturers. Minnesota quartz deposits anchor captive supply chains for scale fabricators serving architect-specified commercial installations.
Germany
Commercial construction procurement teams in Berlin and Munich request Environmental Product Declarations and regional sourcing documentation under CSRD reporting requirements. REACH styrene content restrictions accelerate substitution toward methyl methacrylate and vinyl ester alternatives. The North Rhine-Westphalia industrial corridor concentrates resin formulator pilot plants for low-VOC acrylic system development.
India
Urban infrastructure investment under BIS building material standards creates qualified demand corridors for certified engineered stone in retail and office developments. Maharashtra and Gujarat commercial construction clusters specify imported slab formats for complex architectural cutouts. Delhi-NCR hospitality refurbishment cycles accelerate adoption of digitally printed marble-patterned surfaces.
Spain
Cosentino Group's vertically integrated quartz sourcing across Almería and Murcia sustains margin control from raw material to finished slab. EU Green Deal embodied carbon tracking favors suppliers with verified low-carbon resin systems and regional mineral sourcing documentation. The Mediterranean coastal fabrication belt serves export markets across Southern Europe and North Africa.
Artificial Marble Market Vendor Landscape
Concentration sits with scale players operating automated continuous-casting lines that batch press operators cannot finance. The vendor base separates into three tiers: integrated mineral-resin producers, regional fabricators with captive templating networks, and commodity slab distributors. Consolidation pressure favors M&A activity among mid-cap specialists and capacity expansion among Asia-Pacific basin producers with dedicated engineered stone complexes.
Within the integrated producer tier, Cosentino Group and Cambria exemplify archetypes of backward integration into captive quartz reserves and domestic fabrication capacity. Hyundai L&C occupies a position among scale-driven Asia-Pacific manufacturers. These three anchors demonstrate how vertical control over mineral sourcing and resin formulation creates defensive positioning against petrochemical feedstock volatility and multi-jurisdiction certification fragmentation.
| Leading Market Players |
|---|
| LX Hausys |
| Vicostone |
| Cosentino Group |
| Compac |
| Cambria |
| Caesarstone |
| Hyundai L&C |
| Lotte Advanced Materials |
| DuPont |
| Others |
Supply Flow & Price Mechanics
REACH styrene restrictions and EPA VOC limits gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to maintain parallel formulation portfolios that fragment pricing power across regulatory jurisdictions. Buyers in premium hospitality segments absorb compliance-driven cost step-ups, while standard-grade procurement faces margin compression from petrochemical feedstock volatility.
Pricing Analysis
Configured-to-order slab pricing commands substantial premiums over standard countertop dimensions through digital printing customization and field-fabrication complexity. Pricing stratifies across premium, standard, and economy tiers based on quartz purity grades and certification tier under GB radon classifications. Cost compression in standard-grade engineered stone is intensifying because batch press operators cannot match continuous-casting unit economics. Residential renovation through big-box retail channels exhibits highest price sensitivity; architect-specified commercial installations show lowest.
Supply Chain Analysis
China and South Korea anchor engineered stone slab production through dedicated manufacturing complexes serving Asia-Pacific basin demand. High-purity quartz deposits in Spain and Minnesota feed captive mineral sourcing for integrated producers, while unsaturated polyester and acrylic polymer feedstocks draw from petrochemical derivatives. Single-source vulnerability concentrates in high-grade silica deposits clustered in specific geographies. Distribution runs through manufacturer-direct specification teams for large commercial projects and specialty fabricator networks for residential renovation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial marble specification workflows are shifting toward platform-economics dynamics as digital design tools and embodied carbon verification systems create interoperability requirements between resin formulators, fabricators, and procurement platforms.
For Market Incumbents: Consolidate backward integration into captive quartz reserves and regional resin production to defend margin position against petrochemical volatility. Scale continuous-casting automation in China's Yangtze River Delta and South Korea's dedicated engineered stone complexes to compress unit costs below batch press competitors. Prioritize multi-jurisdiction certification investments under REACH, EPA, and GB standards to maintain specification access across fragmented regulatory environments. For New Entrants and Emerging Players: Healthcare solid surface penetration represents a service-layer gap where incumbents under-serve hospital and laboratory infection control requirements with seamless repair capabilities. India's BIS-certified commercial construction corridor offers the most penetrable geography for certified engineered stone specification. Target acrylic-based low-VOC formulations for European REACH transition timelines as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated continuous-casting lines, consolidating capacity among scale players and squeezing mid-cap batch press operators. Long-term viability favors vertically integrated mineral-resin producers with regional sourcing documentation under EU Green Deal requirements. Watch for inflection signals in CSRD reporting adoption rates among Nordic commercial construction procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Quartz Reserves | Cosentino Group's Almería sourcing secures margin control from mineral extraction through finished slab. |
| Continuous-Casting Capacity Expansion | Hyundai L&C's South Korean complexes achieve dimensional consistency that batch presses cannot match. |
| Low-VOC Acrylic Resin Transition | North Rhine-Westphalia pilot plants accelerate REACH-compliant methyl methacrylate substitution timelines. |
| Digital Slab Design Platform Integration | Photorealistic printing technology compresses lead times for bespoke hospitality marble-patterned surfaces. |
| Embodied Carbon Verification Program | Nordic procurement teams under CSRD requirements demand Environmental Product Declarations and regional sourcing documentation. |
Methodological Framework
Operator-level perspectives from plant managers at engineered stone complexes, resin formulator R&D directors, commercial construction procurement leads, and hospitality specification architects anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, SEC 10-K filings of listed surfacing manufacturers, and building material certification databases. Bottom-up demand modeling across countertop, slab, and tile form factors triangulated against top-down construction spending forecasts.
Sensitivity analysis framed volume and value outputs across the projection horizon, modeling resin chemistry type, mineral filler composition, end-use vertical, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from trend extrapolation of continuous-casting automation penetration and REACH low-VOC transition timelines. Forecast inputs incorporated petrochemical feedstock price indices and urban commercial construction pipeline data from tier-one Chinese cities.
Forecasts assume regulatory continuity in REACH styrene restrictions, EPA VOC emission standards, and China's GB radon classifications; material policy shifts would require re-modeling. Supply disruption risks from quartz deposit concentration and resin feedstock volatility could compress margins beyond base-case assumptions. Recalibration cycles align with material shifts in CSRD reporting adoption and continuous-casting capacity buildout announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Glass Tiles Market