
 Construction Sealants Market | 2026-2036
Construction Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Sealants Market Analysis
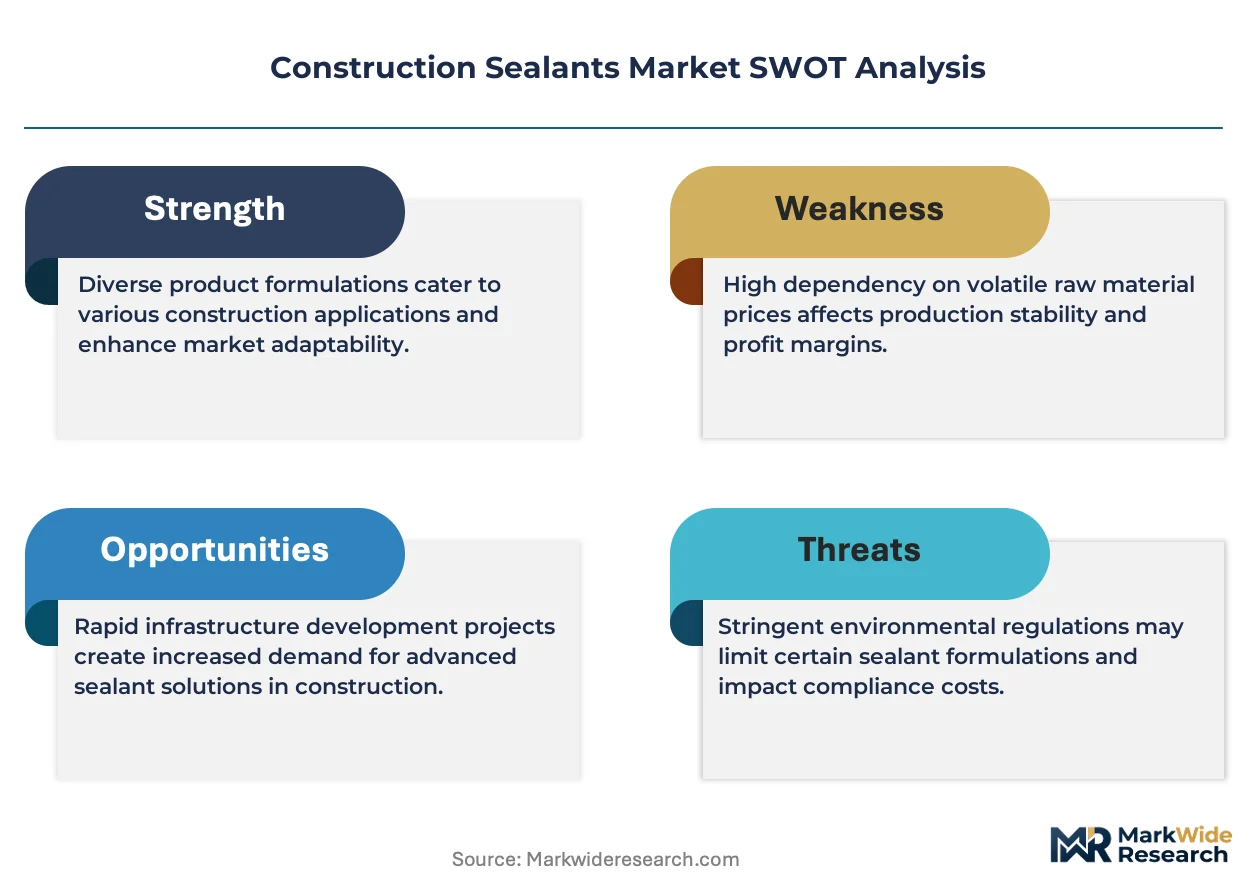
Hybrid polymer formulations is rebalancing cost-performance tradeoffs across mid-tier construction projects. Sika AG leverages its European manufacturing footprint to sustain supply chain responsiveness for infrastructure-grade sealants. H.B. Fuller anchors its position through specialized adhesives-sealants integration for commercial glazing systems. Dow Inc. competes on silicone chemistry leadership, particularly in high-performance building envelope applications where thermal cycling resistance commands premium positioning.
Construction sealants are elastomeric compounds formulated to fill joints, gaps, and seams while accommodating substrate movement through elastic recovery; typical specifications include elongation-at-break exceeding 200% and Shore A hardness ranging from 15 to 50 depending on application load. Their primary purpose is to prevent air and moisture infiltration in building envelopes, transportation structures, and industrial assemblies. Silicone products dominate weathersealing for curtain wall systems where UV stability and temperature resistance justify material cost. Polyurethane formulations lead structural bonding and expansion joint applications given their superior adhesion to porous substrates and tensile strength. Waterborne technology segments show expanding share in interior and occupied-space applications where low-odor, low-VOC profiles align with tightening indoor air quality protocols.
EPA regulations under the National Volatile Organic Compound Emission Standards for Architectural Coatings constrain solvent-based sealant formulations, redirecting R&D investment toward waterborne and hybrid chemistries. REACH compliance in Europe mandates disclosure of Substances of Very High Concern, elevating testing burdens for imported formulations while creating competitive advantage for manufacturers with established European regulatory affairs capabilities. Stakeholders must monitor evolving state-level amendments to California's SCAQMD Rule 1168 and emerging EU restrictions on siloxanes, as these frameworks will determine which chemistries retain market access across major demand centers.
Market Dynamics
EPA VOC emission standards under the National Volatile Organic Compound Emission Standards for Architectural Coatings are redirecting formulation chemistry across the construction sealants sector, compressing solvent-based product lifecycles while elevating waterborne and hybrid polymer alternatives.
Growth Catalysts
- Green building codes:LEED v4.1 and BREEAM certification requirements in Germany, India, and China mandate low-emitting sealant systems for envelope assemblies, pulling silicone and polyurethane formulations into specification sheets.
- Infrastructure renewal cycles:Bridge deck and highway expansion joint rehabilitation programs across the United States, China, and Germany generate recurring demand for high-movement-capable polyurethane sealants with 500%+ elongation ratings.
- REACH SVHC disclosure mandates:European manufacturers with established regulatory affairs capabilities capture import substitution opportunities as non-EU suppliers face elevated testing burdens for Substances of Very High Concern.
Market Restraints
- Petrochemical input volatility:Polyol and isocyanate feedstock costs fluctuate with crude oil indices, compressing margin stability for polyurethane sealant producers without long-term supply agreements.
- Siloxane regulatory uncertainty:Emerging EU restrictions on cyclic siloxanes (D4, D5, D6) threaten market access for conventional silicone sealants in weathersealing applications, forcing costly reformulation investments.
- Hybrid polymer patent thickets:Proprietary MS polymer and STPE chemistries remain controlled by a concentrated licensor base, limiting formulation freedom for mid-tier compounders.
Strategic Opportunities
- Prefabricated construction integration:Offsite manufacturing of modular building envelopes in China and Germany creates demand for factory-applied sealant systems with accelerated cure profiles and bond-on-damp-substrate capability.
- California SCAQMD Rule 1168 amendments:Anticipated tightening of VOC limits for architectural coatings in South Coast Air Quality Management District jurisdictions will advantage waterborne sealant suppliers with compliant product lines.
- Retrofit energy efficiency programs:Deep renovation of existing commercial building stocks across the United States and Germany drives air-sealing specification upgrades, displacing aging solvent-based caulks with high-performance elastomeric systems.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in hybrid polymer rheology and substrate-specific adhesion science commands premium compensation, constraining R&D throughput for mid-scale manufacturers.
- Multi-jurisdictional certification timelines:Simultaneous pursuit of ETA approvals in Europe, ICC-ES reports in the United States, and GB standard compliance in China extends product launch cycles by 18-24 months.
- Legacy substrate compatibility:Existing building envelopes with aged bituminous or solvent-based residue layers require extensive surface preparation protocols, complicating warranty coverage and installer training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Sealants Market |
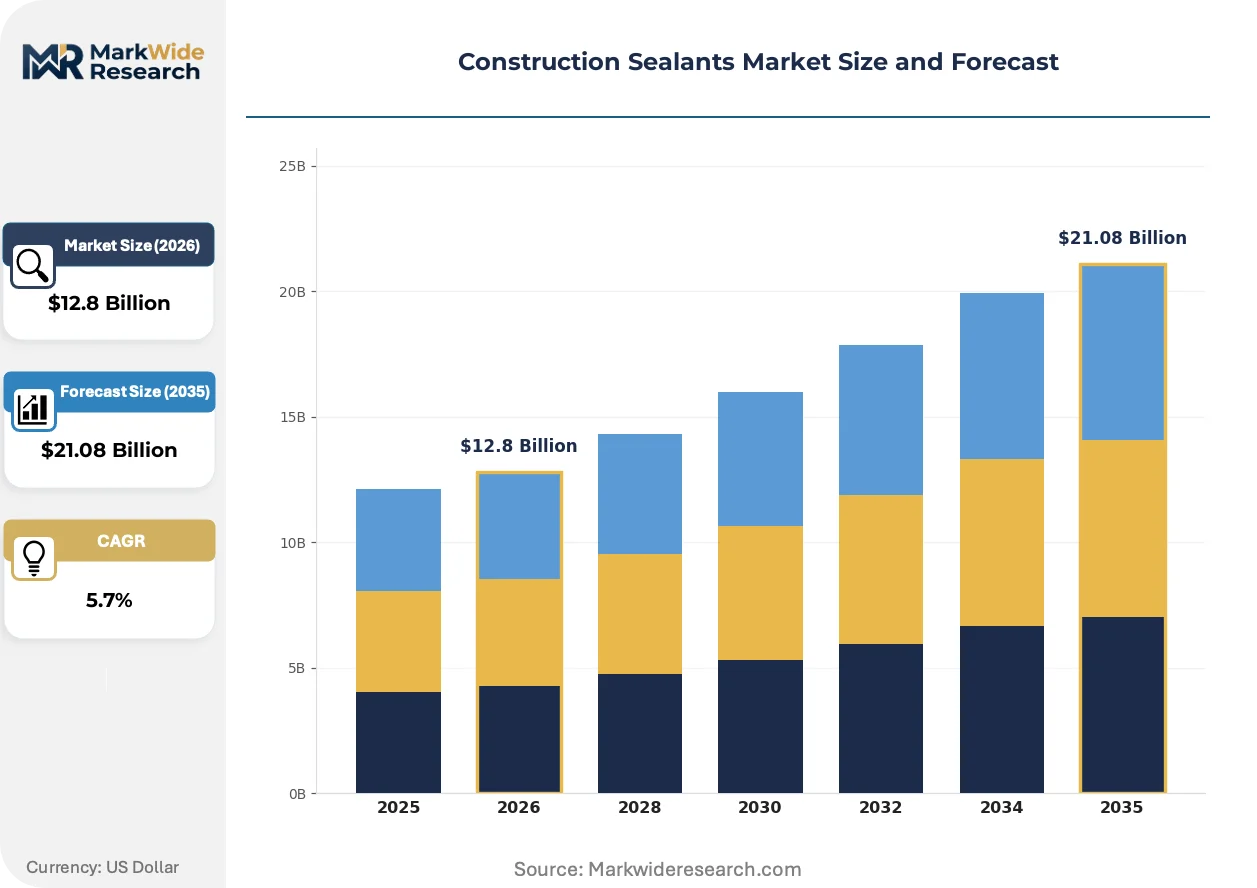
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Bituminous Application: Building & Construction, Automotive, Aerospace, Marine End User: Contractors, Architects, DIY Users, Manufacturers Technology: Thermoplastic, Thermosetting, Hybrid, Waterborne |
| Companies Covered | 3M Company, H.B. Fuller, Sika AG, Bostik, Mapei S.p.A., Henkel AG & Co. KGaA, BASF SE, Wacker Chemie AG, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Sealants Market Emerging Trajectories
Formulation chemistry convergence and regulatory pressure are compressing traditional product category boundaries, with hybrid systems capturing specification share previously divided between silicone and polyurethane alternatives.
Hybrid polymer sealant technology is consolidating performance attributes previously split across chemistries, combining silicone UV stability with polyurethane substrate adhesion and paintability. Commercial glazing contractors and infrastructure maintenance divisions are specifying these systems for mid-tier projects where premium silicone costs are unjustified. The technology is consolidating supplier portfolios as compounders reduce SKU complexity by replacing discrete silicone and polyurethane lines with unified hybrid platforms.
REACH authorization requirements for Substances of Very High Concern are forcing disclosure and substitution planning across European supply chains. Industrial consequence includes elevated testing expenditures and reformulation timelines for imported sealant formulations containing candidate list substances. High-performance building envelope applications in Germany and France are most affected, with specification officers now requiring full material transparency documentation prior to product approval.
Specification authority is migrating from general contractors to envelope commissioning agents and building envelope consultants who control performance-based material selection. This channel disruption compresses traditional distributor influence while elevating manufacturer-direct technical service relationships. The United States commercial high-rise sector exhibits the most pronounced shift, where envelope commissioning protocols now mandate pre-installation adhesion testing and cure-profile validation for all elastomeric joint materials.
Construction Sealants Market Segmentation
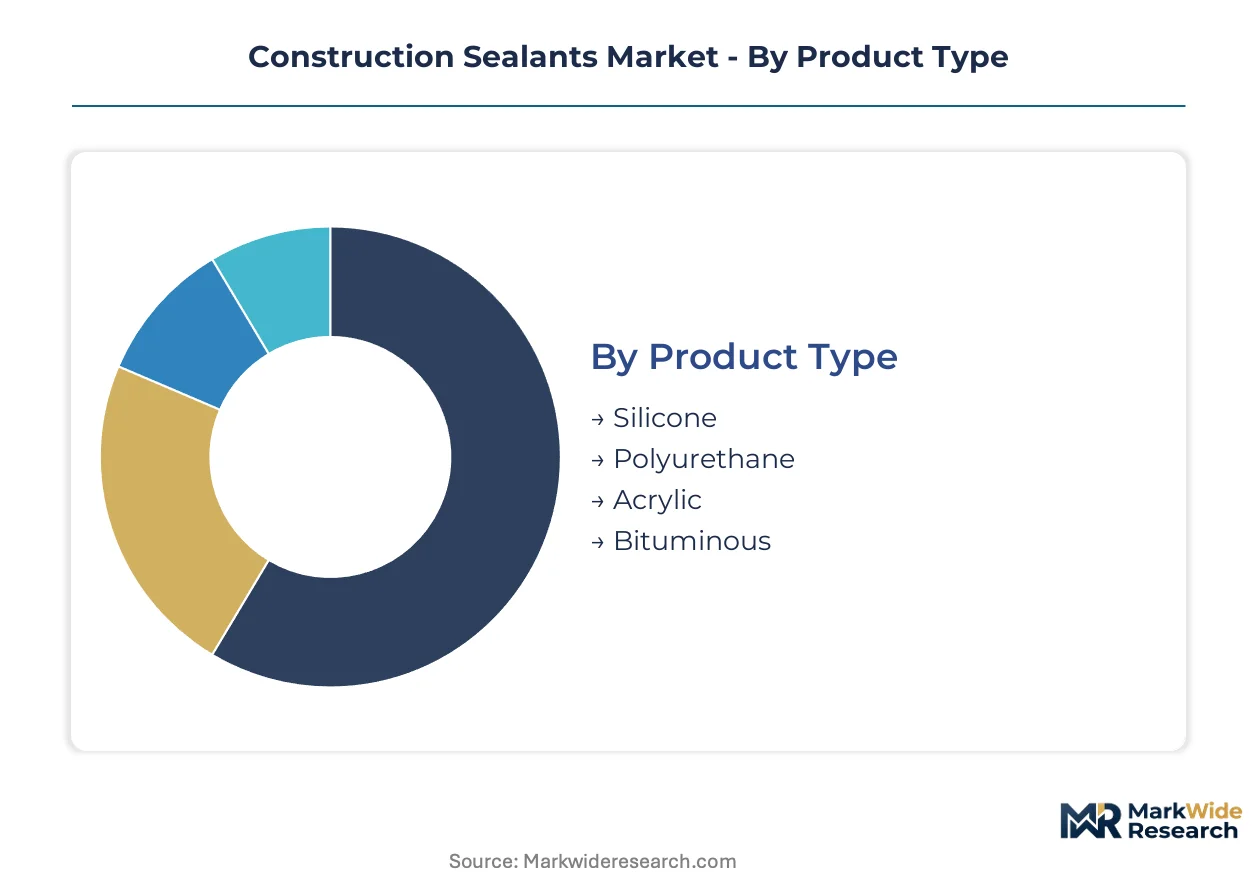
Construction sealants fragment across formulation chemistry, cure mechanism, and specification authority. Each segmentation axis reveals distinct margin structures and competitive entry barriers that reshape procurement patterns across commercial and infrastructure end-uses.
Product Type:
Formulation chemistry determines thermal stability, substrate adhesion, and regulatory compliance profiles across building envelope specifications.
- Silicone:UV-stable polysiloxane backbones deliver temperature resistance from -60°C to 200°C. Curtain wall weathersealing in Germany and China pulls high-consistency formulations where 25-year service life justifies material cost premiums.
- Polyurethane:Isocyanate-terminated prepolymers bond aggressively to porous concrete and masonry. Bridge deck expansion joints across the United States specify 500%+ elongation grades for high-movement infrastructure rehabilitation cycles.
- Acrylic:Water-dispersed acrylic emulsions serve interior caulking and paintable finishing applications with low-odor profiles suitable for occupied-space renovations.
- Bituminous:Solvent-cut or emulsified asphaltic compounds seal below-grade waterproofing and roofing membranes where moisture resistance trumps elastic recovery requirements.
Polyurethane leads on scale through infrastructure volume; silicone leads on momentum through green building code alignment.
Application:
End-use environments dictate movement accommodation, chemical exposure, and certification requirements that segment supplier capabilities.
- Building & Construction:Envelope sealing, expansion joints, and structural glazing dominate volume. LEED v4.1 compliance in India and China mandates low-VOC systems for commercial high-rise commissioning protocols.
- Automotive:Windshield bonding and seam sealing require rapid-cure polyurethane systems with crash-durability ratings. OEM assembly lines specify moisture-cure profiles compatible with just-in-sequence production.
- Aerospace:Fuel-resistant fluorosilicone and polysulfide formulations seal fuel tanks and pressure bulkheads under FAA certification requirements for temperature extremes and jet fuel exposure.
- Marine:Deck sealing and hull bonding applications demand saltwater-resistant elastomers with Shore A hardness tuned for dynamic flex fatigue in vessel structures.
Building & Construction anchors absolute volume; aerospace commands the steepest expansion trajectory through lightweighting mandates.
End User:
Specification authority and technical sophistication determine channel structure, warranty terms, and service intensity across customer segments.
- Contractors:Installation crews procure through distribution for field-applied joint sealing. Bulk purchasing power and seasonal demand patterns compress margin capture for formulated product suppliers.
- Architects:Design-phase specification control elevates performance documentation and pre-installation adhesion testing requirements. Envelope consultants in the United States commercial sector now mandate cure-profile validation prior to approval.
- DIY Users:Retail-packaged caulks and sealants serve residential maintenance and renovation. Waterborne acrylics with tool-cleanup convenience dominate shelf placement at home improvement centers.
- Manufacturers:Factory-applied systems for modular construction and OEM assembly demand accelerated cure chemistry and bond-on-damp-substrate capability for production line integration.
Contractors represent the largest addressable base; manufacturers are climbing the fastest as prefabrication scales.
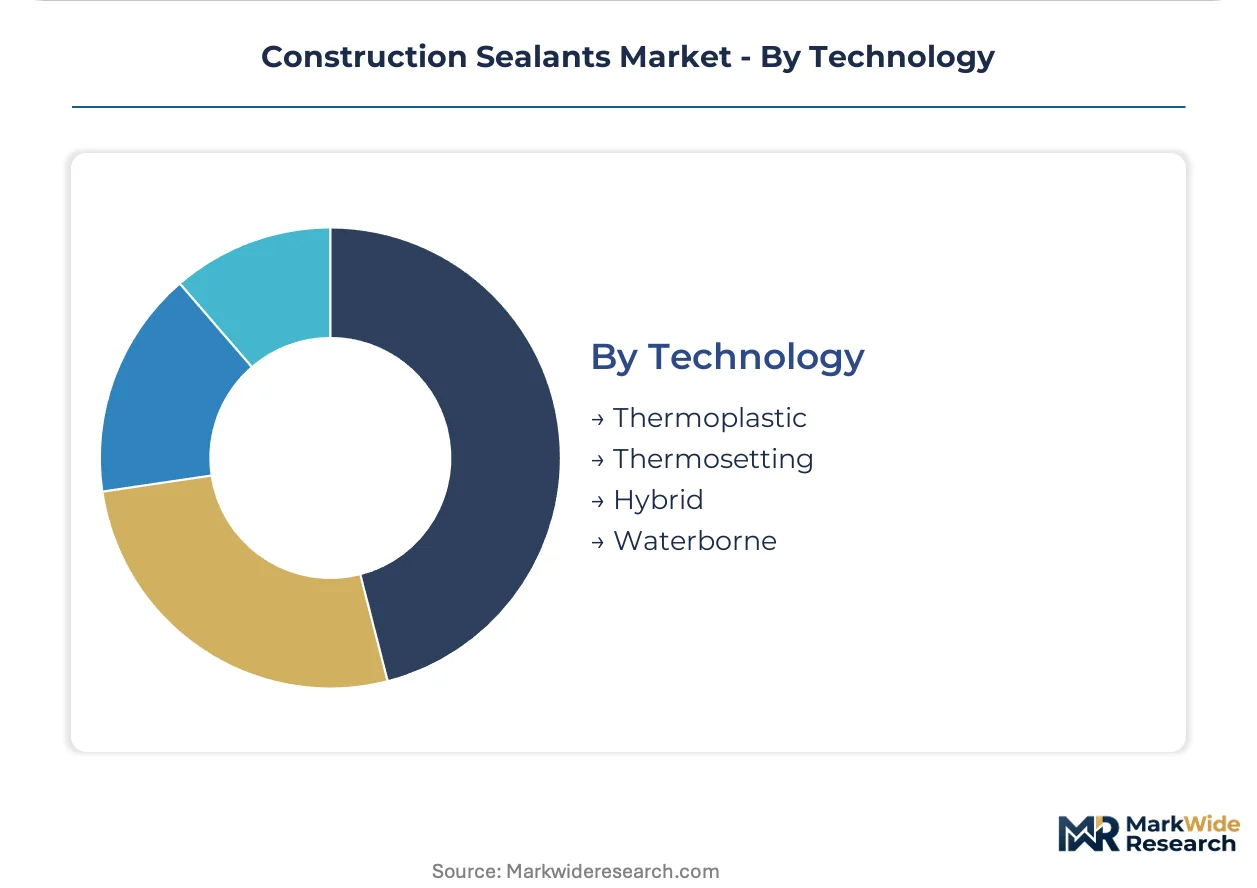
Technology:
Cure mechanism and polymer architecture determine application latitude, environmental compliance, and capital equipment requirements.
- Thermoplastic:Hot-melt application of EVA and polyamide formulations suits high-speed manufacturing lines. Limited heat resistance restricts use to interior or protected exterior applications.
- Thermosetting:Two-component epoxy and polyurethane systems deliver structural strength for load-bearing joints. Mix ratio sensitivity and pot-life constraints demand skilled application labor.
- Hybrid:MS polymer and STPE chemistries merge silicone UV stability with polyurethane adhesion and paintability. Mid-tier commercial projects in Germany specify these for cost-performance optimization.
- Waterborne:Acrylic and polyurethane dispersions eliminate solvent content for EPA VOC compliance and indoor air quality protocols. Cure speed and early water resistance lag solvent-borne alternatives.
Thermosetting retains the deepest specification lock in structural bonding; hybrid technology is expanding most quickly through chemistry convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan corridor concentrates European sealant demand through infrastructure renewal and commercial envelope specifications. Urbanization across Asia-Pacific and tightening environmental codes in North America reshape regional procurement priorities. Regulatory divergence between EPA VOC mandates and REACH SVHC protocols fragments formulation strategies across major demand centers.
United States
Bridge deck rehabilitation and commercial high-rise envelope commissioning drive polyurethane and silicone consumption. EPA National Volatile Organic Compound Emission Standards for Architectural Coatings constrain solvent-based formulations, redirecting procurement toward waterborne alternatives. The South Coast Air Quality Management District in California enforces Rule 1168 amendments that advantage low-VOC suppliers in Los Angeles and San Diego construction corridors.
Germany
Curtain wall weathersealing for energy-efficient commercial buildings specifies high-consistency silicone systems with 25-year service life requirements. REACH Substances of Very High Concern disclosure mandates elevate testing burdens for imported formulations, creating competitive advantage for domestic manufacturers with established regulatory affairs capabilities. The Frankfurt-Rhine-Main and Munich metropolitan regions anchor specification authority through envelope consultant networks.
China
Urbanization in tier-one cities and green building code implementation under dual carbon goals accelerate silicone and polyurethane adoption for commercial envelopes. GB standard compliance requirements and MIIT industrial policy shape formulation chemistry for domestic and export markets. The Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing capacity and specification demand for high-performance elastomeric joint systems.
India
LEED v4.1 certification requirements for commercial high-rise projects in Mumbai and Delhi-NCR mandate low-emitting sealant systems for envelope assemblies. BIS standard harmonization with international protocols elevates quality thresholds for imported and domestic formulations. The Maharashtra and Karnataka state construction corridors generate concentrated demand for expansion joint and structural glazing applications.
Construction Sealants Market Vendor Landscape
Global majors compete with regional champions across formulation chemistry and specification authority channels. Market structure consolidates around three tiers: integrated chemical conglomerates with captive silicone supply, specialized sealant compounders with distribution depth, and regional formulators serving price-sensitive infrastructure segments. Strategic archetypes include chemistry-led innovators, application-focused technical service providers, and scale-driven commodity suppliers. Dominant competitive moves encompass hybrid polymer portfolio expansion and direct specification relationships with envelope consultants.
Within the chemistry-led tier, Dow Inc. and Wacker Chemie AG exemplify integrated silicone specialists leveraging vertical control over polysiloxane feedstocks. Sika AG and H.B. Fuller occupy positions bridging formulation expertise with construction channel access. Among diversified industrial conglomerates, 3M Company and BASF SE represent cross-sector technology platforms with sealant portfolios embedded within broader adhesive and material science offerings. These named entities anchor competitive dynamics without exhausting the participant base.
| Leading Market Players |
|---|
| 3M Company |
| H.B. Fuller |
| Sika AG |
| Bostik |
| Mapei S.p.A. |
| Henkel AG & Co. KGaA |
| BASF SE |
| Wacker Chemie AG |
| Dow Inc. |
| Others |
Supply Flow & Price Mechanics
LEED v4.1 certification mandates for commercial high-rise envelopes in China, India, and Germany are compressing specification timelines and forcing compounders to absorb compliance-testing costs upstream, which then propagates through tiered product positioning. Procurement officers now bundle low-VOC validation with volume commitments, shifting margin capture toward suppliers with captive regulatory affairs capabilities.
Pricing Analysis
Polyol and isocyanate feedstock volatility propagates directly into polyurethane sealant quotations, with compounders indexing long-term supply agreements to crude derivatives. Three-tier pricing structure across premium, standard, and economy levels separates structural-grade silicone systems certified for 25-year service life from mid-tier hybrid polymers and commodity waterborne acrylics. Cost compression in the standard tier is intensifying because REACH SVHC testing burdens for imported formulations disadvantage non-European suppliers without established regulatory infrastructure. Contractors represent the most price-sensitive segment due to bulk purchasing power and seasonal demand patterns, while envelope commissioning agents show lowest sensitivity where performance documentation justifies material premiums.
Supply Chain Analysis
ETA approvals in Europe, ICC-ES reports in the United States, and GB standard compliance in China function as qualification gates that extend product launch cycles and concentrate supply among established compounders with multi-jurisdictional certification capabilities. Manufacturing capacity clusters in Germany, China, and the United States anchor regional supply, with the Rhine-Ruhr and Yangtze River Delta corridors serving as formulation hubs for infrastructure-grade systems. Siloxane feedstocks for silicone sealants and isocyanate-terminated prepolymers for polyurethane formulations represent critical input dependencies. Single-source vulnerability for specialized hybrid polymer licenses constrains formulation freedom. Distribution runs through construction chemicals distributors and manufacturer-direct technical service channels for specification-intensive commercial glazing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction sealants market compounds steadily through infrastructure renewal cycles and green building code proliferation, with regulatory compliance investments functioning as a durable moat for established compounders.
For Market Incumbents: Hedge against siloxane regulatory uncertainty in Europe by accelerating hybrid polymer portfolio expansion and securing backward integration into MS polymer feedstocks. Deepen specification relationships with envelope commissioning agents in the United States commercial high-rise sector to defend against distributor disintermediation. Prioritize factory-applied sealant system development for prefabricated construction integration in China and Germany. For New Entrants and Emerging Players: Begin with waterborne acrylic formulations for interior caulking in India's LEED-certified commercial projects, where BIS standard harmonization creates entry pathways without incumbent certification lock-in. Target the DIY retail channel through tool-cleanup convenience and low-odor positioning. Pursue private-label manufacturing partnerships with regional distributors to bypass direct specification authority barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized sealant compounders possessing established European regulatory affairs capabilities and hybrid polymer licensing relationships. Five-to-ten year viability hinges on substitution resilience as silicone faces REACH restrictions and polyurethane confronts petrochemical volatility. Watch for EPA amendments to SCAQMD Rule 1168 as an inflection indicator for waterborne technology share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Polymer Portfolio Expansion | Captures specification share previously divided between silicone and polyurethane chemistries in mid-tier commercial projects. |
| Backward Integration into Siloxane Feedstocks | Secures supply continuity for high-consistency silicone formulations as EU restrictions on cyclic siloxanes emerge. |
| Multi-Jurisdictional Certification Investment | Compresses product launch timelines across ETA, ICC-ES, and GB standard requirements for global specification access. |
| Prefabricated Construction Partnership | Positions factory-applied systems with accelerated cure profiles for modular building envelope manufacturing in China and Germany. |
| Direct Technical Service Channel Development | Bypasses distributor influence as envelope commissioning agents assume specification authority in commercial high-rise sectors. |
Methodological Framework
Multiple input streams — primary interviews with sealant formulation chemists, construction procurement managers, and envelope commissioning consultants; secondary validation through EPA VOC emission filings, REACH SVHC candidate list updates, and SEC 10-K disclosures from listed chemical conglomerates; plus customs and trade data for polyol and isocyanate feedstock flows — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across the modeling period applied a segmentation framework spanning formulation chemistry, cure mechanism, specification authority channel, and regional regulatory cluster to derive volume and value outputs. CAGRs were computed from fitted growth curves incorporating infrastructure renewal cycle timing, green building code adoption trajectories, and petrochemical input cost indices as industry-specific forecast inputs.
Caveats apply where EPA amendments to architectural coating standards, EU restrictions on cyclic siloxanes, or feedstock price spikes could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement continuity and infrastructure spending commitment levels. A model refresh is warranted upon material change in hybrid polymer patent licensing availability or prefabricated construction adoption rates in major demand centers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Thinset Mortar Market