
 Non-Residential Polished Concrete Market | 2026-2036
Non-Residential Polished Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Residential Polished Concrete Market Analysis
Market Context
Specifier-dealer networks for commercial flooring systems is rewriting how polished concrete reaches non-residential job sites. Cemex leverages its integrated cement-to-finish supply chain to control material specification at the design stage. Sika AG competes through chemical admixture and densifier portfolios that anchor its position in high-traffic installations. BASF SE differentiates via polyurethane and epoxy hybrid sealers that extend performance warranties in warehouse environments.
Technical Definition and Segment Structure
Non-residential polished concrete is a mechanically refined concrete surface achieving specified gloss and clarity through progressive diamond abrasive grinding, chemical densification with lithium silicate or sodium silicate hardeners, and optional guard or sealer application, producing a durable, low-maintenance finish for commercial and institutional foot and wheeled traffic. The grind-and-seal installation method dominates warehouse and logistics applications where speed-to-occupancy and cost containment outweigh maximum aesthetic refinement, while mechanical polish commands margin pools in flagship retail and corporate headquarters where clarity and reflectivity specifications are stringent. High-gloss finish types lead specification in premium office spaces and showrooms, though satin and matte finishes are gaining share in educational institutions where glare reduction and slip resistance ratings govern selection.
Regulatory Framework and Outlook
LEED v4.1 from the U.S. Green Building Council, California Air Resources Board VOC limits, and OSHA silica exposure standards collectively shape product formulation, jobsite dust control, and indoor air quality certification requirements for polished concrete contractors and material suppliers. The U.S. EPA Safer Choice program and state-level extended producer responsibility frameworks in California and New York are beginning to influence sealer and densifier chemistry selection. Stakeholders must monitor evolving state-level low-carbon procurement mandates that will soon embed embodied carbon thresholds into public and institutional construction specifications.
Market Dynamics
Mechanical densification technologies are displacing topical sealers as warehouse developers prioritize speed-to-occupancy and LEED v4.1 indoor air quality compliance over traditional multi-coat finishing systems.
Growth Catalysts
- Sun Belt Speculative Construction:Industrial developers across Texas, Arizona, and Florida are specifying polished concrete at slab pour to accelerate tenant fit-out timelines and reduce flooring change orders.
- LEED v4.1 Low-Emitting Materials Credit:The U.S. Green Building Council's updated indoor air quality criteria rewards mechanically polished surfaces over resinous coatings that off-gas during cure.
- Lithium Silicate Densifier Chemistry:Advanced lithium-based hardeners penetrate deeper into slab substrates, reducing maintenance cycles in high-wheeled-traffic logistics corridors.
Market Restraints
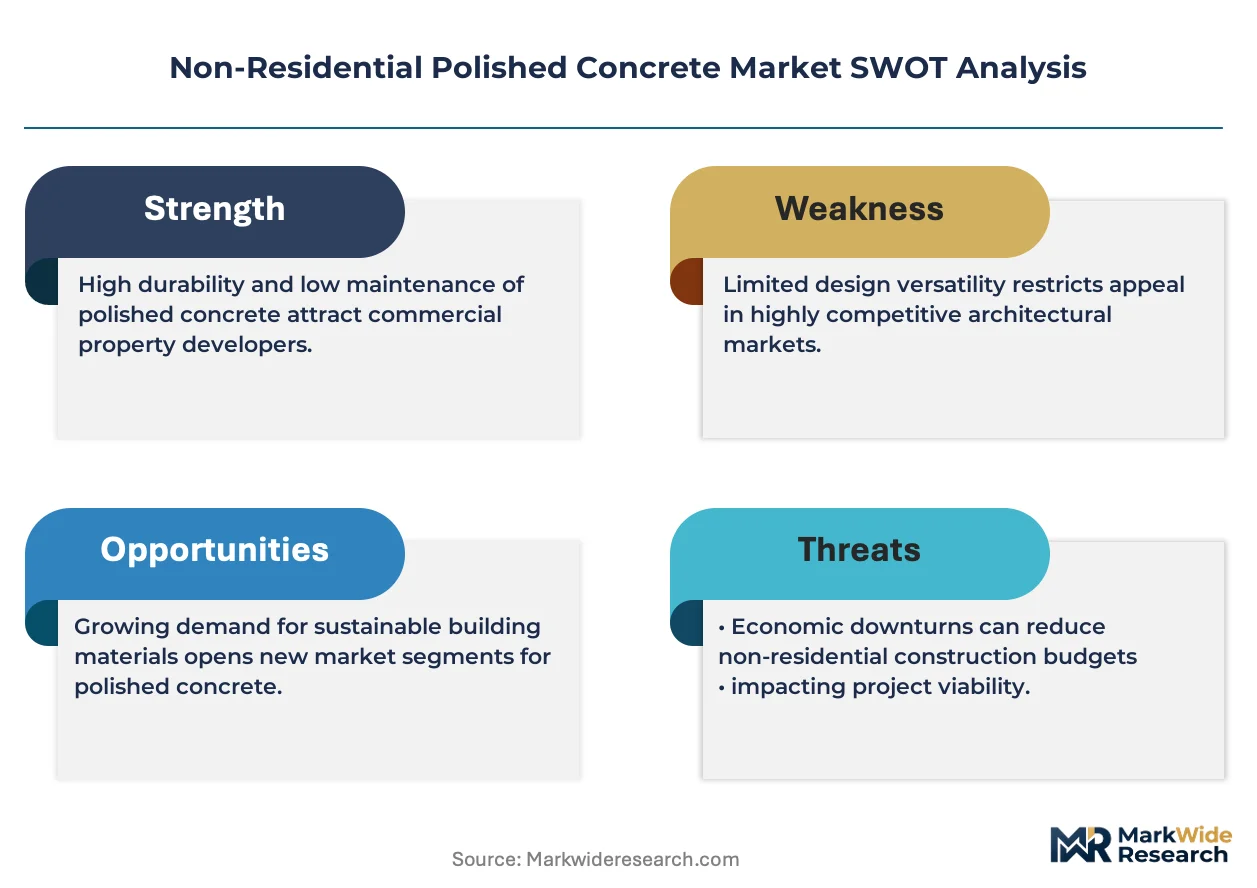
- Portland Cement Price Volatility:Energy-intensive clinker production concentrates in a handful of integrated suppliers, exposing contractors to input cost swings that compress bid margins.
- Silica Exposure Compliance Burden:OSHA's respirable crystalline silica standard mandates expensive dust collection infrastructure on every grind-and-polish job site, elevating contractor capital requirements.
- Resinous Coating Substitution:Epoxy and polyurethane systems retain specification share in chemical spill environments and freezer warehouses where thermal shock resistance trumps polished concrete durability.
Strategic Opportunities
- Data Center Construction Surge:Hyperscale cloud providers in Northern Virginia and Dallas-Fort Worth are adopting polished concrete for raised-floor plenums to minimize particulate generation and static buildup.
- Carbon-Embodied Procurement Mandates:California's Buy Clean program and similar state-level low-carbon concrete standards will advantage contractors with Environmental Product Declarations and slab mix optimization capabilities.
- Retrofit Overlays:Self-leveling cementitious toppings with integrated polish capability are opening renovation opportunities in 1980s-era distribution facilities where original slabs lack structural tolerance for deep grinding.
Industry Challenges
- Certified Craftsman Shortage:The Concrete Polishing Association of America's craftsman certification program has not kept pace with installation volume, creating quality variance risks on large-format retail rollouts.
- Slab-Quality Dependency:Final polished appearance remains hostage to concrete contractor finishing practices at pour, creating coordination failures and rework costs when flatness specifications are missed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Residential Polished Concrete Market |
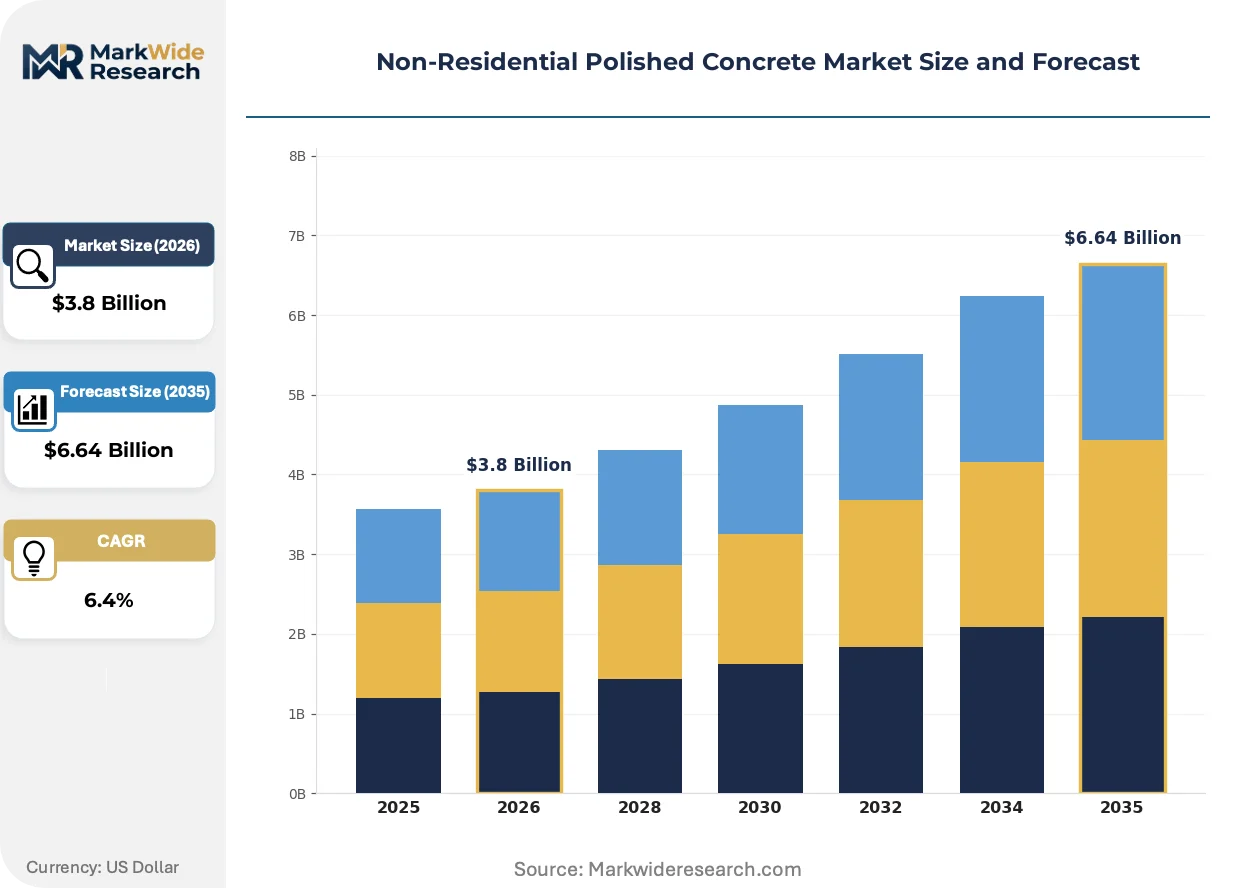
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail Stores, Warehouses, Office Spaces, Educational Institutions Finish Type: High-Gloss, Matte, Satin, Semi-Gloss Installation Method: Grind and Seal, Polish and Grind, Mechanical Polish, Chemical Polish End User: Construction Companies, Property Developers, Architects, Facility Managers |
| Companies Covered | Cemex, Boral, LafargeHolcim Ltd, Sika AG, Husqvarna Group, HeidelbergCement AG, UltraTech Cement Ltd, BASF SE, CRH plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Residential Polished Concrete Market Emerging Trajectories
Digital surface profiling and real-time gloss measurement are compressing quality assurance cycles and enabling outcome-based contractor selection. Three developments are restructuring how polished concrete reaches specification.
Robotic grinding platforms equipped with LiDAR surface mapping are digitizing quality control in large-format warehouse installations. National logistics developers are piloting autonomous equipment on million-square-foot distribution slabs to achieve consistent aggregate exposure across vast footprints. This digitizing of surface preparation is compressing punch-list timelines and reducing reliance on manual operator skill variation.
California Air Resources Board VOC limits are forcing sealer chemistry reformulation across the Western United States. Manufacturers are migrating from solvent-borne to water-borne guard products, extending cure times but eliminating regulatory compliance risks. Warehouse developers in the Central Valley and Inland Empire are accepting longer occupancy delays to secure air quality permits without coating substitution.
Direct specification between end-users and material suppliers is disintermediating traditional distributor networks. Large retail chains are negotiating national purchasing agreements with densifier manufacturers, bypassing regional flooring contractors on chemistry selection. This consolidation of procurement authority is most visible among big-box retailers with standardized prototype designs across fifty-plus annual store openings.
Non-Residential Polished Concrete Market Segmentation
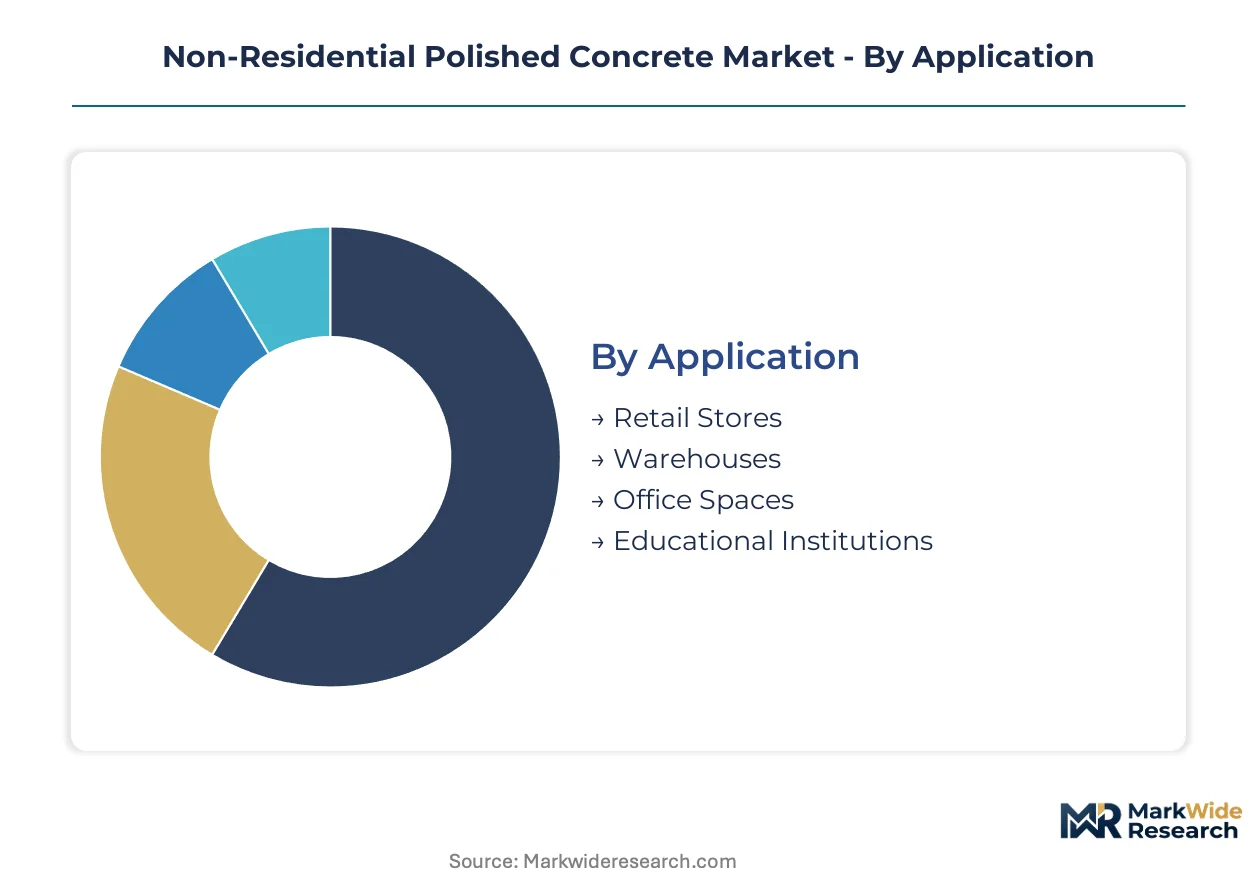
Segmentation in non-residential polished concrete reveals how specification authority, finish chemistry, and installation speed trade off across commercial building types. Each dimension captures distinct procurement behaviors and margin structures that contractors must navigate.
Application:
Mature warehouse specification dominates volume, while emerging data center and life science applications are rewriting performance criteria.
- Retail Stores:Flagship locations demand mechanical polish with high-gloss clarity for brand presentation. Big-box rollout programs in Texas and Florida specify grind-and-seal to compress tenant improvement timelines and reduce flooring change orders.
- Warehouses:Logistics developers specify polished concrete at slab pour to eliminate resinous coating cycles and meet LEED v4.1 low-emitting materials criteria. Flatness tolerances for high-bay racking drive coordination between concrete finishers and polishing contractors.
- Office Spaces:Corporate headquarters favor high-gloss finishes in lobby and circulation zones, with matte specification in open work areas to control glare.
- Educational Institutions:K-12 and university projects prioritize slip resistance ratings and maintenance simplicity over aesthetic refinement, with satin finishes gaining specification share.
Warehouses retain volume leadership; retail stores hold the steepest expansion curve.
Finish Type:
Cost tier separation runs from premium clarity systems to economy maintenance-focused surfaces.
- High-Gloss:Achieves 800+ gloss units through progressive resin-bond diamond grinding and lithium silicate densification. Corporate headquarters and automotive showrooms specify this tier where reflectivity reinforces brand identity.
- Matte:Stops at 400-grit mechanical refinement without guard application, producing a low-shear surface preferred in educational corridors and healthcare circulation where slip resistance governs.
- Satin:Occupies the middle ground at 400-800 gloss units, balancing maintenance visibility with glare control in mixed-use commercial environments.
- Semi-Gloss:Applied primarily through grind-and-seal methods with topical guards, offering faster installation and lower initial cost for speculative industrial leasing.
High-gloss commands premium pricing; matte finishes are climbing fastest on institutional specification.
Installation Method:
Volume concentration favors speed-optimized approaches, while margin pools concentrate in precision mechanical systems.
- Grind and Seal:Single-pass coarse grinding followed by topical sealer application delivers lowest first-cost and fastest return-to-service. Warehouse developers across the Sun Belt specify this method to accelerate occupancy permits.
- Polish and Grind:Combines mechanical refinement with selective densifier application, serving mid-tier retail and light industrial where durability requirements exceed grind-and-seal capability.
- Mechanical Polish:Full progressive refinement through 3000-grit resin diamonds produces maximum clarity and stain resistance. Premium office and flagship retail specifications demand this approach despite extended installation schedules.
- Chemical Polish:Relies on reactive densifiers without mechanical refinement, occupying niche applications in existing slab renovation where structural tolerance limits grinding depth.
Grind and Seal retains volume leadership; mechanical polish holds the steepest margin expansion trajectory.
End User:
Customer type determines whether specification flows through design-phase influence or post-construction procurement.
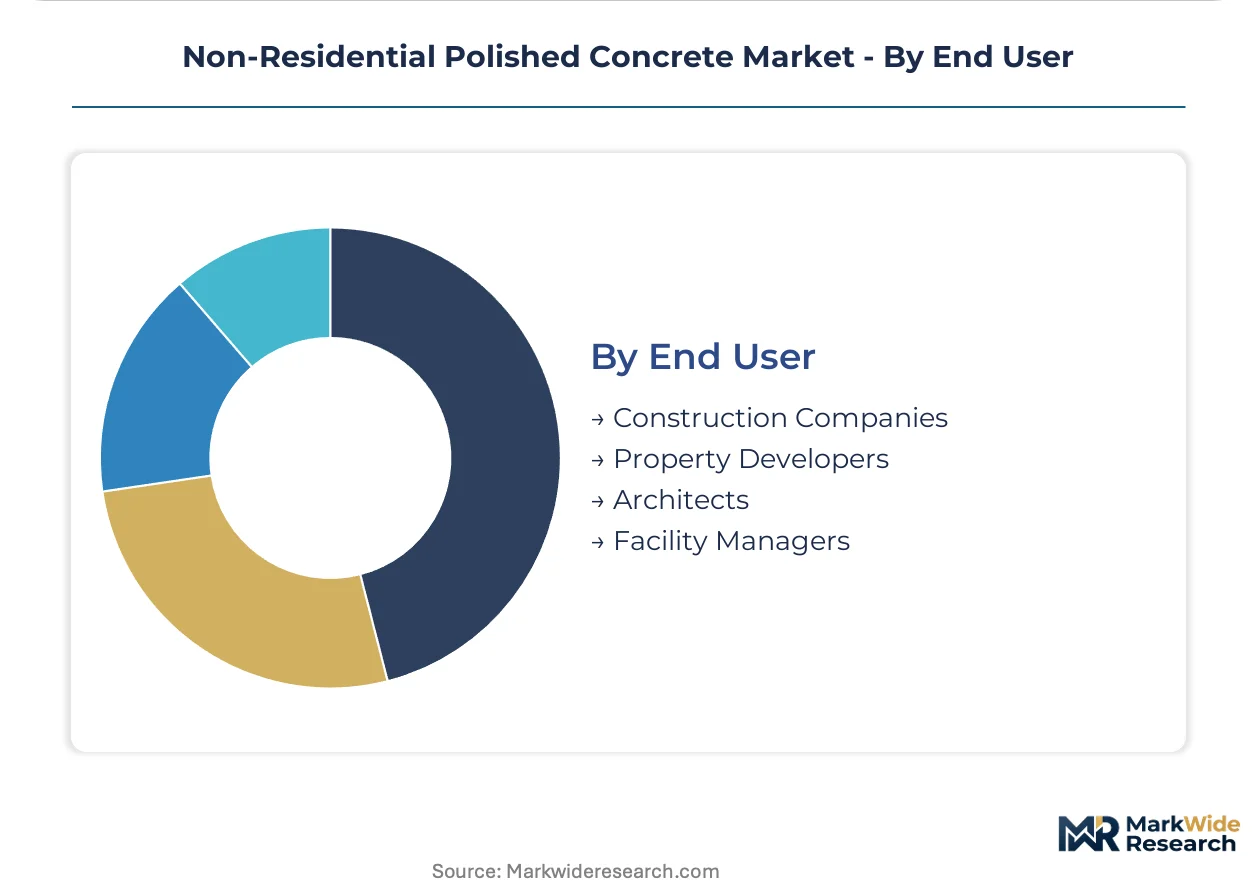
- Construction Companies:General contractors select installation methods based on schedule compression and subcontractor availability, with grind-and-seal dominating fast-track industrial projects.
- Property Developers:Speculative industrial developers in Dallas-Fort Worth and Phoenix specify polished concrete at slab pour to differentiate leasing collateral and reduce tenant improvement allowances.
- Architects:Design-phase specification of densifier chemistry and gloss level influences material procurement before contractor bidding, particularly in corporate headquarters and institutional projects.
- Facility Managers:Post-occupancy maintenance contracts and renovation specifications drive demand for compatible guard products and repair protocols in existing commercial portfolios.
Property developers retain volume leadership; facility managers represent the steepest expansion curve as retrofit activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate highway system and Class I rail networks connecting Dallas-Fort Worth to the Port of Los Angeles anchor North American polished concrete demand. Distribution corridors in the United States Sun Belt concentrate speculative industrial construction where slab-at-pour specification accelerates tenant occupancy.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives specification for raised-floor plenum applications. OSHA's respirable crystalline silica standard mandates dust collection infrastructure on every grind-and-polish job site. The Central Valley and Inland Empire warehouse clusters accept extended cure times to secure California Air Resources Board air quality permits.
Germany
Industrial logistics developers in the Rhine-Ruhr corridor specify mechanically polished surfaces to meet EU Green Deal embodied carbon thresholds. REACH regulation governs lithium silicate densifier chemistry formulation across Western European supply chains. The Stuttgart automotive manufacturing cluster demands high-gloss clarity specifications for flagship corporate showrooms and brand experience centers.
China
E-commerce fulfillment center construction in the Yangtze River Delta and Pearl River Delta concentrates demand for speed-optimized grind-and-seal installations. GB standards for indoor air quality in commercial buildings influence sealer chemistry selection in Beijing-Tianjin-Hebei developments. Chongqing's inland port expansion drives speculative warehouse slab specification to capture western logistics flows.
United Arab Emirates
Expo 2020 legacy developments and Dubai South logistics zone construction prioritize LEED-equivalent certification for international tenant attraction. MOHAP indoor air quality guidelines shape densifier and guard product specification in healthcare and educational institutional projects. Abu Dhabi's Masdar City sustainable development cluster embeds low-carbon concrete thresholds into public procurement mandates.
India
Third-party logistics facility construction in Maharashtra and Gujarat drives warehouse polished concrete volume as foreign direct investment in manufacturing accelerates. BIS standards for commercial building materials influence contractor qualification requirements in Delhi-NCR corporate headquarters projects. The Bangalore technology corridor specifies high-gloss finishes in campus lobby and circulation zones to signal global workplace standards.
Non-Residential Polished Concrete Market Vendor Landscape
On the supply side, the industry is consolidating around integrated cement-to-finish supply chains and specialized chemical admixture portfolios. Three strategic archetypes dominate: integrated building materials conglomerates controlling raw material specification, specialty chemical manufacturers anchoring densifier and sealer formulation, and surface preparation equipment suppliers enabling installation automation. Competitive moves concentrate on backward integration into lithium silicate chemistry and strategic partnerships with national retail chains for direct procurement disintermediation.
Within the integrated materials tier, Cemex leverages its captive cement production to influence design-phase specification through slab-mix optimization capabilities. Sika AG and BASF SE anchor the specialty chemical vector, with the former exemplifying densifier chemistry leadership and the latter representing hybrid sealer formulation expertise. These three entities collectively illustrate how supply-side concentration in non-residential polished concrete flows through distinct control points: raw material, chemical performance, and installation chemistry.
| Leading Market Players |
|---|
| Cemex |
| Boral |
| LafargeHolcim Ltd |
| Sika AG |
| Husqvarna Group |
| HeidelbergCement AG |
| UltraTech Cement Ltd |
| BASF SE |
| CRH plc |
| Others |
Supply Flow & Price Mechanics
Portland cement price volatility determines both tiered pricing spreads across installation methods and supply chain configuration in non-residential polished concrete. Energy-intensive clinker production concentrates among integrated suppliers, forcing contractors to absorb input cost swings or pass them through on bid-based projects.
Pricing Analysis
Volume-discount tiering separates mechanical polish from grind-and-seal and chemical polish methods. Premium-mid-economy pricing differentiation rests on gloss unit achievement, densifier chemistry grade, and warranty duration. Cost compression in grind-and-seal is intensifying because speculative developers prioritize speed-to-occupancy over clarity specifications. Warehouse developers in the Sun Belt corridor demonstrate highest price sensitivity; corporate headquarters and flagship retail buyers accept premium positioning for brand-aligned aesthetics.
Supply Chain Analysis
Contract manufacturing concentration for lithium silicate densifiers sits with specialty chemical producers in Germany, Switzerland, and the United States. Raw material feeds from Saudi Arabian cement producers, Chinese grinding equipment fabricators, and domestic aggregate quarries. Single-source vulnerability runs through lithium compound supply for densifier chemistry. Distribution runs through specifier-dealer networks and direct national purchasing agreements with large retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-residential polished concrete operates as a defensive-moat market where switching costs lock facility managers into compatible maintenance chemistry and repair protocols.
For Market Incumbents: Pre-empt resinous coating substitution in freezer warehouse and chemical spill environments by advancing thermal shock-resistant hybrid sealer formulations. Backward integration into lithium compound sourcing secures densifier margin pools against commodity volatility. Cement-to-finish supply chain control anchors specification influence at the design stage.
For New Entrants and Emerging Players: Build out retrofit overlay capabilities for 1980s-era distribution facilities where original slabs lack structural tolerance for deep grinding. Self-leveling cementitious toppings with integrated polish capability represent the most penetrable white-space. Target facility managers through maintenance contract bundling rather than competing on initial installation bids.
For Investors and Strategic Acquirers: California's Buy Clean program reshapes the acquisition landscape by advantaging contractors with Environmental Product Declarations and slab mix optimization capabilities. Long-term viability centers on carbon-accounting readiness as public procurement mandates embed embodied carbon thresholds. Signal to monitor: state-level low-carbon concrete standard adoption velocity beyond California and New York.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Silicate Chemistry | Cemex and Sika AG anchor densifier supply chains through captive lithium compound sourcing. |
| Robotic Grinding Platform Deployment | Husqvarna Group pilots LiDAR-equipped autonomous equipment on million-square-foot warehouse slabs. |
| Direct Procurement Disintermediation | National retail chains negotiate densifier purchasing agreements bypassing regional contractor networks. |
| Environmental Product Declaration Investment | Contractors with slab mix optimization capabilities secure California public project eligibility. |
| Retrofit Overlay Capability Development | Self-leveling toppings open renovation opportunities in aging distribution facilities nationwide. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings from building materials conglomerates, OSHA enforcement databases, and LEED project directories. Interviews with polished concrete contractors, concrete densifier procurement managers at national retail chains, facility maintenance directors, and specification architects informed demand-side validation. Secondary sources included U.S. Green Building Council certification records, California Air Resources Board compliance filings, and trade data from the National Association of Manufacturers. Bottom-up installation volume estimates triangulated against top-down cement consumption proxies.
Forecast inputs span finish type tier, application building category, installation method speed, and regional construction permit velocity across the analysis window. Segmentation modeling incorporated gloss level specification, densifier chemistry penetration, and end-user procurement authority. CAGRs derived from slope analysis of historical installation volumes against projected non-residential construction expenditure. Hyperscale data center construction pipelines and Sun Belt industrial permit backlogs served as industry-specific demand anchors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated cement producers or rapid robotic platform adoption by national contractors would shift outcomes. Quarterly review of state-level low-carbon procurement mandate progression and OSHA silica enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
China Oriented Strand Board Market