
 Brick Market | 2026-2036
Brick Market Size, Share, and Industry Trends Forecast 2026-2036
Brick Market Analysis
Project finance for kiln modernization and emissions retrofitting is reconfiguring capital requirements across the brick industry, favoring producers with balance-sheet capacity to absorb multi-year environmental compliance cycles. CEMEX S.A.B. de C.V. leverages its integrated cement-brick distribution network to secure feedstock cost advantages in key construction corridors. General Shale Inc. anchors its position through deep regional quarry access and controlled clay reserves across the southeastern United States. CRH Plc competes via standardized product platforms that reduce specification friction for large-scale infrastructure tenders.
Brick denotes a fired or chemically cured masonry unit, typically composed of clay, shale, or concrete aggregate, formed through extrusion or molding and hardened at temperatures exceeding 900°C to achieve compressive strength above 7 MPa for structural applications. Clay Brick retains the largest revenue pool in residential construction, though Fly Ash Brick is gaining specification share in commercial and industrial projects where thermal efficiency ratings and waste-utilization credits improve project economics. Concrete Block dominates infrastructure and load-bearing commercial segments due to standardized dimensional tolerances and compatibility with mechanized installation systems.
EPA emissions standards for brick kiln operations in the United States, India's BIS structural grading protocols, and the EU Green Deal embodied-carbon tracking requirements are collectively raising compliance costs for traditional clamp-kiln producers while accelerating investment in tunnel-kiln automation and alternative binder formulations. Stakeholders must monitor regulatory divergence between jurisdictions, as carbon-border adjustment mechanisms and localized building-code updates will increasingly determine which product categories and manufacturing geographies retain cost-competitive access to premium construction markets.
Market Dynamics
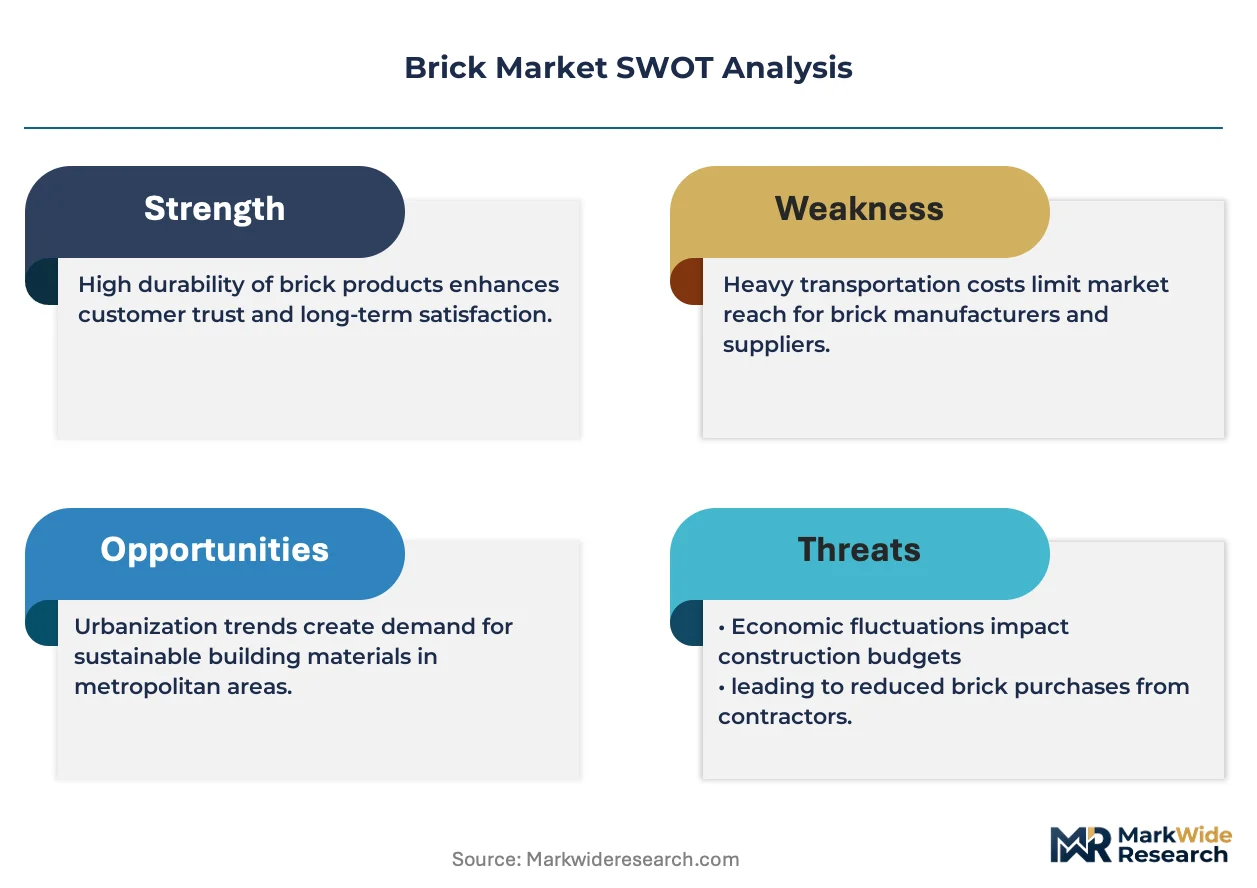
Kiln automation mandates and embodied-carbon tracking requirements are compressing margins for traditional clamp-kiln operators while tunnel-kiln investments absorb disproportionate capital flows.
Growth Catalysts
- India's BIS structural grading protocols:Quality thresholds for fired clay bricks are consolidating informal supply channels into certified producer networks. Maharashtra and Gujarat urban infrastructure budgets are absorbing record masonry volumes.
- Tunnel-kiln automation:Mechanized firing systems reduce particulate emissions below EPA thresholds while improving dimensional consistency for mechanized construction.
- Fly ash utilization mandates:Waste-to-resource policies in power-generating regions are redirecting thermal power plant byproduct into chemically cured brick formulations.
Market Restraints
- Natural gas price volatility:Fired clay production depends on thermal energy inputs whose cost swings compress operating margins for continuous-kiln operators.
- Quarry access concentration:Controlled clay reserves in the southeastern United States limit new entrant access to premium shale deposits.
- Concrete block substitution:Standardized dimensional tolerances and compatibility with mechanized installation systems displace clay brick in load-bearing commercial segments.
Strategic Opportunities
- EU Green Deal embodied-carbon tracking:Alternative binder formulations utilizing industrial byproduct streams qualify for preferential specification in public infrastructure tenders.
- Western India urban corridors:Unconsolidated regional supply in Gujarat secondary cities offers acquisition targets for certified producers seeking distribution density.
- Digital specification platforms:Building information modeling integration reduces friction for architects selecting masonry units by compressibility and thermal performance.
Industry Challenges
- Kiln retrofit capex cycles:Multi-year emissions compliance timelines strain balance-sheet capacity for mid-scale producers lacking project finance relationships.
- Cross-jurisdiction carbon accounting:Divergent methodologies between EU border adjustment mechanisms and India's BIS protocols complicate export qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brick Market |
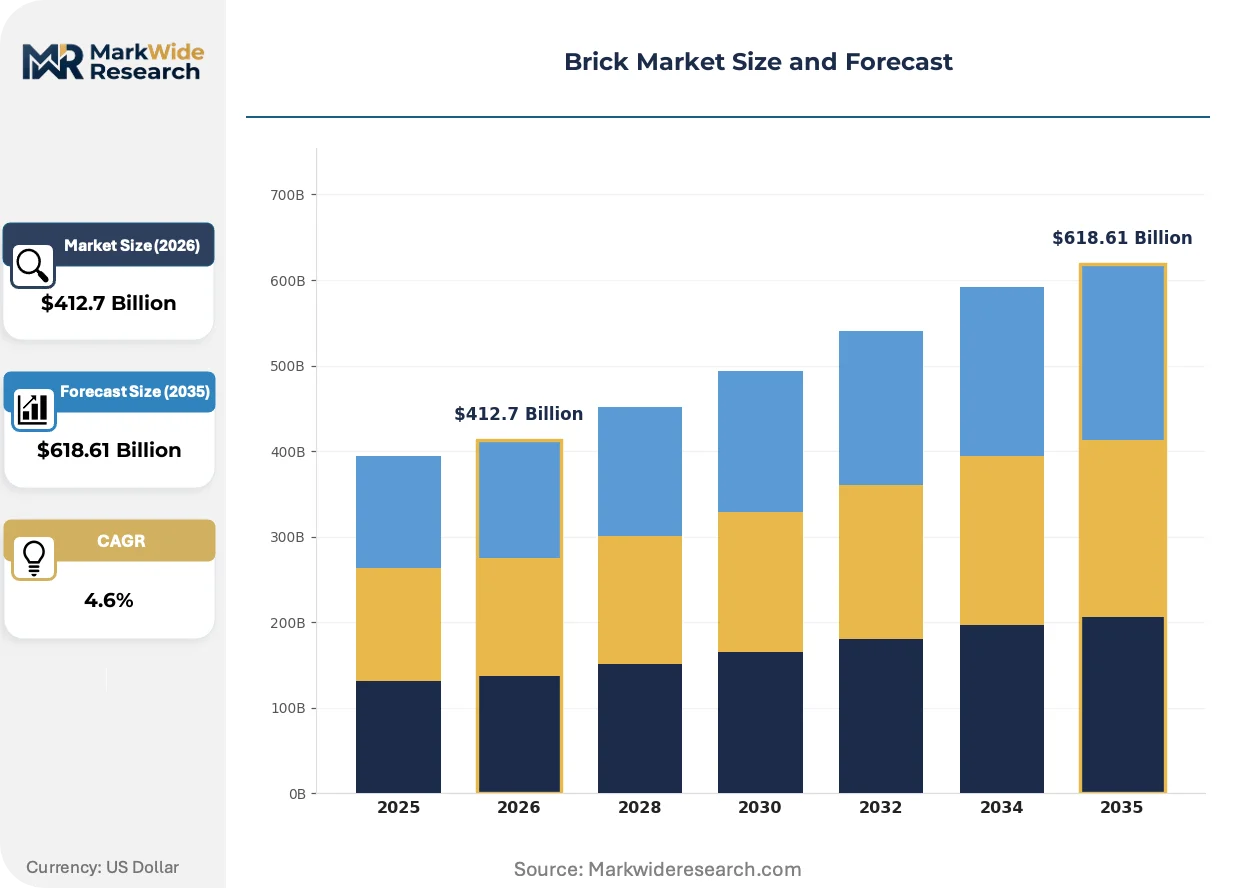
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $618.61 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay Brick, Concrete Block, Fly Ash Brick, AAC Block Size: Standard Size, Modular Size, Large Format, Custom Size End User: Residential Buildings, Commercial Buildings, Industrial Projects, Landscaping Installation: DIY, Professional, Masonry Contractors, Prefabricated |
| Companies Covered | CEMEX S.A.B. de C.V., Xella Group, Boral Limited, Glen-Gery, Acme Brick Company, General Shale Inc., Yankee Hill Brick, US Brick, CRH Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brick Market Emerging Trajectories
Automation in firing systems and digital traceability in supply chains are compressing the cost gap between traditional and alternative binder formulations.
Sensor-integrated tunnel kilns are digitizing temperature profiling and fuel optimization across continuous firing operations. Large-scale residential developers in India's western states are specifying digitally monitored production for quality assurance. Real-time emissions monitoring is digitizing compliance documentation for carbon-border adjustment qualification.
EPA emissions standards for brick kiln operations are tightening particulate matter thresholds and accelerating scrubber retrofits. Continuous monitoring requirements are raising capital intensity for clamp-kiln operators. Producers in coal-dependent regions are responding with alternative fuel trials and waste-heat recovery installations.
Specification decisions are migrating from general contractors to architect-led building information modeling workflows. Masonry selection now flows through digital libraries that filter by compressive strength, thermal conductivity, and embodied carbon. This pattern is most visible in commercial and institutional projects across European markets with Green Deal procurement mandates.
Brick Market Segmentation
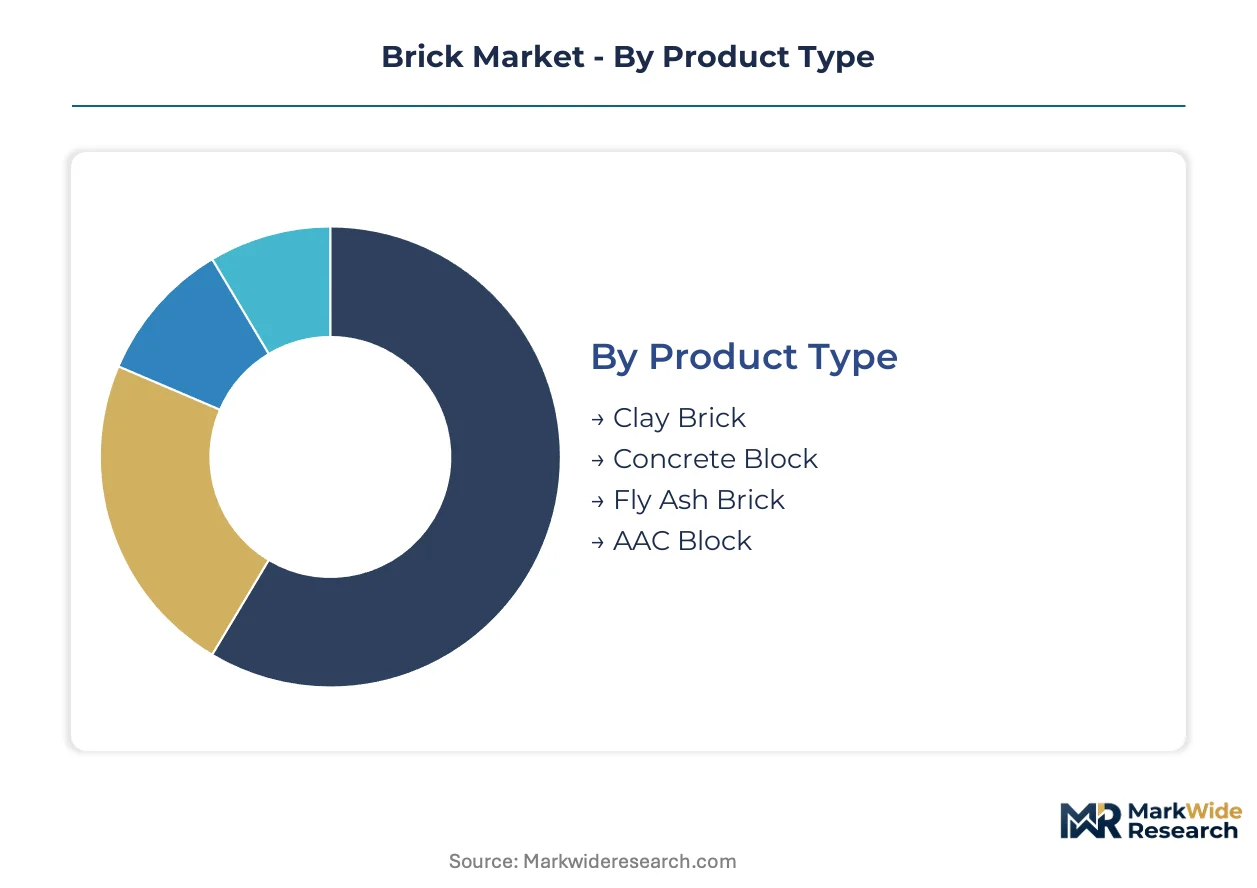
Brick market segmentation tracks how material composition, dimensional standards, and installation methods determine specification pathways across construction verticals. Each dimension carries distinct margin profiles and regulatory exposure that shape producer positioning strategies.
Product Type:
Mature fired-clay technologies dominate volume, while emerging chemically cured alternatives capture specification share through embodied-carbon advantages.
- Clay Brick:Fired clay masonry units hardened above 900°C deliver compressive strength exceeding 7 MPa for structural walls. Residential construction across India's western states—Maharashtra and Gujarat—absorbs record volumes as BIS certification mandates consolidate informal supply into certified networks.
- Concrete Block:Cement-aggregate units with standardized dimensional tolerances enable mechanized installation systems. Infrastructure and load-bearing commercial segments specify concrete block for compatibility with automated laying equipment and predictable structural performance.
- Fly Ash Brick:Chemically cured units utilizing thermal power plant byproduct qualify for waste-utilization credits under India's fly ash utilization mandates. Commercial and industrial projects specify these for thermal efficiency ratings.
- AAC Block:Autoclaved aerated concrete delivers lightweight thermal performance through aluminum powder expansion. Premium residential and institutional projects in EU Green Deal jurisdictions specify AAC for embodied-carbon tracking compliance.
Clay brick handles the majority of throughput; AAC block is expanding most quickly on specification share.
Size:
Dimensional standardization runs along a cost-to-customization spectrum, with modular formats optimizing mechanized construction economics.
- Standard Size:Traditional fired-clay dimensions—190mm x 90mm x 90mm in India—match legacy masonry labor skills and existing mortar specifications. Informal construction across South Asian markets maintains demand for these proportions.
- Modular Size:Coordinated dimensional systems align with 100mm planning grids and reduce cutting waste on site. Large-scale residential developers in India's urban corridors specify modular formats for speed-to-completion targets.
- Large Format:Oversized units—exceeding 400mm in any dimension—reduce mortar joints and labor hours per wall area. Prefabricated wall system manufacturers source large format for factory-controlled quality.
- Custom Size:Project-specific dimensions serve restoration, acoustic, or aesthetic specifications. Heritage conservation architects in European markets commission custom sizes for material compatibility with historic fabric.
Standard size commands the installed base; modular size is climbing fastest as mechanized construction spreads.
End User:
Application segments separate by load-bearing requirements, finish specifications, and procurement channel concentration.
- Residential Buildings:Single-family and multi-family construction specifies clay brick for aesthetic finish and thermal mass. India's western states—Maharashtra and Gujarat—absorb record masonry volumes through expanding urban infrastructure budgets.
- Commercial Buildings:Office, retail, and hospitality projects prioritize dimensional consistency and speed of enclosure. Building information modeling workflows in European markets filter masonry selection by compressive strength and thermal conductivity data.
- Industrial Projects:Warehousing and manufacturing facilities specify concrete block for fire resistance and load-bearing capacity. Tunnel-kiln automation investments target industrial segment quality thresholds.
- Landscaping:Paving, retaining walls, and decorative applications emphasize color consistency and surface durability. Controlled clay reserves in the southeastern United States anchor supply for premium landscaping specifications.
Residential buildings carry the volume base; commercial buildings are gaining share fastest through architect-led specification platforms.
Installation:
Channel structure distinguishes between owner-managed procurement and professional masonry contractor networks.
- DIY:Homeowner-directed purchases through retail building supply concentrate in repair, extension, and garden wall applications. Big-box retailers in the United States stock standard clay brick for this channel.
- Professional:Architect-specified, general-contractor-procured masonry flows through distributor networks with technical support. CEMEX leverages integrated cement-brick distribution to secure feedstock cost advantages in key construction corridors.
- Masonry Contractors:Specialized subcontractors procure direct from manufacturers on volume contracts with lay-down yard logistics. General Shale anchors this channel through deep regional quarry access.
- Prefabricated:Offsite wall panel manufacturers source block and brick for factory assembly under quality-controlled conditions. Tunnel-kiln dimensional consistency enables prefabricated system integration.
Professional channel moves the dominant share; prefabricated is accelerating fastest as offsite construction scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale residential developers and infrastructure procurement offices concentrate demand across distinct national construction corridors. Government-mandated quality certifications and emissions protocols reshape supplier eligibility in each market. Urban infrastructure budgets in high-growth metros absorb the majority of certified masonry volumes.
United States
Commercial and institutional builders specify masonry through architect-led building information modeling workflows. EPA emissions standards for brick kiln operations tighten particulate matter thresholds and accelerate scrubber retrofits. The southeastern states cluster production around controlled clay reserves that anchor supply for premium landscaping and residential specifications.
India
Urban infrastructure expansion across Maharashtra and Gujarat absorbs record volumes of fired clay and concrete masonry units. BIS certification mandates for structural clay bricks consolidate informal supply channels into certified producer networks. Secondary cities in Gujarat present acquisition opportunities for certified producers seeking distribution density in unconsolidated regional supply.
Germany
Prefabricated wall system manufacturers source block and brick for factory assembly under quality-controlled conditions. EU Green Deal embodied-carbon tracking requirements accelerate investment in alternative binder formulations utilizing industrial byproduct streams. Industrial clusters in North Rhine-Westphalia concentrate tunnel-kiln automation investments targeting reduced emissions profiles.
China
Power-generating regions redirect thermal power plant byproduct into chemically cured brick formulations under waste-to-resource policies. National dual carbon goals compress margins for traditional clamp-kiln operators while tunnel-kiln investments absorb disproportionate capital flows. Yangtze River Delta construction corridors specify digitally monitored production for quality assurance in large-scale residential developments.
Brazil
Infrastructure and load-bearing commercial segments specify concrete block for compatibility with automated laying equipment. General functional descriptors for national environmental regulators shape emissions compliance timelines for mid-scale producers. São Paulo state construction markets filter masonry selection by compressive strength and thermal performance data in professional procurement channels.
Brick Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented national markets. The vendor base spans integrated building materials conglomerates, regional quarry-anchored producers, and chemically cured formulation specialists. Three archetypes dominate: cement-brick integrators with distribution network control, clay reserve holders with deep regional quarry access, and alternative binder innovators with waste-stream feedstock relationships. Competitive moves concentrate on tunnel-kiln automation capex cycles and strategic quarry acquisitions that secure long-term raw material positions.
Within the integrated conglomerate tier, CEMEX S.A.B. de C.V. and CRH Plc exemplify channel-controlling players that leverage cement-brick distribution networks to secure feedstock cost advantages in key construction corridors. General Shale Inc. represents the quarry-anchored specialist archetype, occupying a position sustained by controlled clay reserve access. These three entities collectively illustrate how balance-sheet capacity to absorb multi-year environmental compliance cycles separates viable competitors from margin-compressed traditional operators.
| Leading Market Players |
|---|
| CEMEX S.A.B. de C.V. |
| Xella Group |
| Boral Limited |
| Glen-Gery |
| Acme Brick Company |
| General Shale Inc. |
| Yankee Hill Brick |
| US Brick |
| CRH Plc |
| Others |
Supply Flow & Price Mechanics
Overcapacity in India's informal clamp-kiln sector compresses realized prices for ungraded clay brick while tunnel-kiln operators command premiums through BIS certification. This utilization gap shapes supplier consolidation incentives and buyer procurement strategies across developing construction corridors.
Pricing Analysis
Certification level under India's BIS structural grading protocols creates the primary spread between commodity and specification-grade product. Three-tier pricing structure separates premium tunnel-kiln output from standard mechanized production and economy clamp-kiln material. Cost compression in the ungraded tier intensifies because fly ash brick substitutes erode residential share. Large-scale developers in Maharashtra and Gujarat exhibit lowest price sensitivity; informal contractors in secondary cities show highest elasticity.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian construction markets dominates supply chain risk planning for AAC block exporters. Manufacturing concentrates in China, India, and Germany for distinct product categories. Clay brick production draws from controlled shale reserves, thermal coal or natural gas, and mechanized extrusion equipment. Single-source vulnerability in southeastern United States quarry access limits new entrant supply security. Distribution runs through integrated cement-brick networks, regional masonry distributors, and direct contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of tunnel-kiln automation expertise and certified clay reserve access concentrates viable expansion capacity among balance-sheet-strong incumbents. Producers lacking project finance relationships face multi-year compliance timelines that freeze competitive response.
For Market Incumbents: Build regulatory moat through BIS certification density in Gujarat secondary cities where informal supply still dominates. Accelerate tunnel-kiln retrofit cycles ahead of EPA particulate thresholds tightening. Anchor position via quarry acquisition in shale-rich southeastern United States territories where General Shale holds controlled reserves. Prioritize backward integration into waste-heat recovery systems that reduce natural gas exposure. For New Entrants and Emerging Players: Build out fly ash brick capacity in Indian power-generating regions where waste-to-resource mandates guarantee feedstock supply. Western India urban corridors present the most penetrable geography given unconsolidated regional supply and expanding infrastructure budgets. Target commercial building specifications through digital specification platform integration that filters by thermal performance data. For Investors and Strategic Acquirers: Capital is best deployed toward tunnel-kiln operators with existing BIS certification and unutilized balance-sheet capacity for emissions retrofitting. Long-term viability over the next decade hinges on embodied-carbon tracking compliance and alternative binder formulation capabilities. Watch for EU Green Deal procurement mandate expansion as the inflection signal for premium product demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Clay Reserves | Secures decades-long feedstock security for tunnel-kiln operators in shale-rich southeastern United States corridors. |
| Tunnel-Kiln Automation Investment | Reduces particulate emissions below EPA thresholds while enabling prefabricated wall system integration. |
| Alternative Binder Formulation Development | Qualifies producers for EU Green Deal preferential specification through industrial byproduct utilization. |
| Digital Specification Platform Integration | Compresses architect selection friction by embedding compressive strength and thermal conductivity data in BIM workflows. |
| Regional Distribution Network Acquisition | Consolidates unconsolidated supply in Gujarat secondary cities where certified producer networks remain sparse. |
Methodological Framework
A standing panel of kiln operations managers, masonry contractor procurement leads, BIS certification auditors, and urban infrastructure budget officers provided ongoing calibration. Primary interviews combined with secondary validation from EPA emissions filings, BIS grading protocol documentation, and EU Green Deal procurement databases. Customs data on clay and shale trade flows, SEC 10-K disclosures from integrated building materials conglomerates, and tunnel-kiln equipment manufacturer order backlogs anchored supply-side triangulation. Bottom-up unit economics and top-down construction spend projections were reconciled.
Scenario-bracketing framed demand trajectories across the projection horizon. Segmentation dimensions modeled include product type, dimensional standard, end-use vertical, and installation channel. CAGRs derived from construction spend elasticity to masonry unit consumption, regulatory compliance cost pass-through assumptions, and substitution dynamics between clay brick and concrete block. Forecast inputs incorporated natural gas price volatility bands and fly ash utilization mandate enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese AAC block exporters or rapid EU carbon-border adjustment expansion would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Aluminum Board Raised Access Floor Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Door Hinges Market