
 United Kingdom Prefab Wood Buildings Market | 2026-2036
United Kingdom Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Prefab Wood Buildings Market Analytics
Housing association procurement consolidation is recalibrating supplier relationships across the prefab timber sector. Legal & General Modular Homes leverages factory-based manufacturing to secure large-volume contracts with registered providers. Baufritz anchors its position through bespoke timber engineering and premium positioning in the self-build segment. ZEDfactory competes via integrated zero-carbon design capabilities that align with tightening energy regulations.
Prefab wood buildings comprise structurally engineered timber frames, cross-laminated timber panels, and glulam assemblies manufactured in controlled factory conditions before transport to site for rapid installation. These systems achieve thermal transmittance values below 0.15 W/m²K when paired with high-performance insulation, serving residential and commercial applications where speed of erection and carbon footprint reduction matter. Multi-story timber construction leads structural innovation as engineered wood products enable six-to-ten storey buildings previously restricted to steel or concrete. Off-site installation dominates value capture in the supply chain, with factory-controlled panelized and modular methods commanding premium positioning over on-site alternatives. The residential end-user segment occupies the largest demand pool, though educational procurement for permanent classroom replacement is expanding fastest among buyer categories.
Building Regulations Part L and the Future Homes Standard shape product specifications by mandating operational energy reductions and fabric-first efficiency approaches. The Timber Research and Development Association certification framework governs structural integrity and fire performance classifications for factory-produced systems. MHCLG planning policy on modular construction streamlines approvals for repeatable designs. Stakeholders must monitor evolving fire safety guidance from the Department for Levelling Up, Housing and Communities and assess how updated Approved Document B amendments affect material selection and compartmentation strategies in taller timber structures.
Market Dynamics
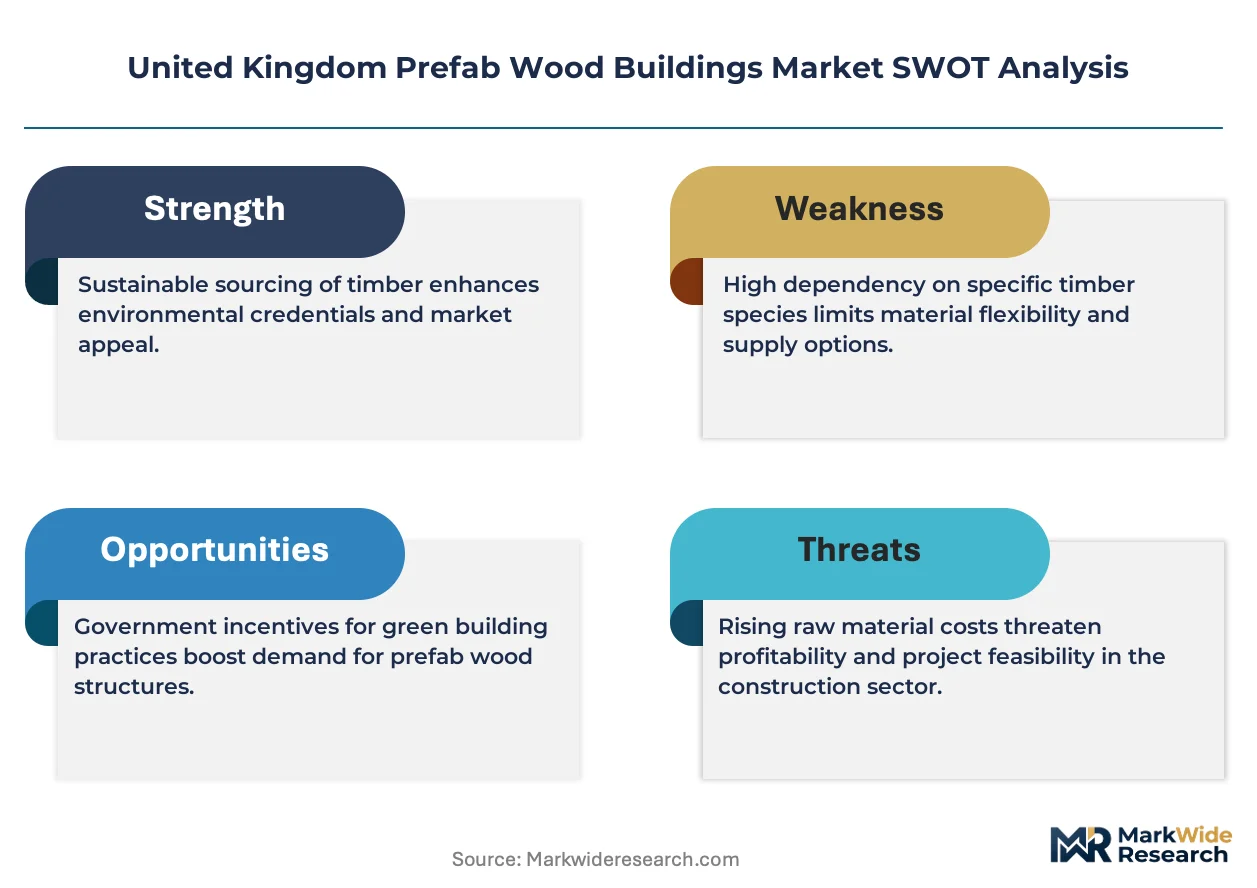
Housing associations and local authorities are consolidating procurement volumes around factory-built timber systems, compressing supplier margins while accelerating design standardization across England's social housing pipeline.
Growth Catalysts
- Future Homes Standard:Tightening thermal performance requirements for new dwellings mandate fabric-first efficiency approaches that factory-controlled timber panels deliver consistently.
- Cross-laminated timber panels:Engineered wood products now enable six-to-ten storey residential structures previously restricted to steel or concrete, unlocking urban density solutions.
- South East England:Land scarcity and planning pressures in this region favor off-site construction methods that reduce site disruption and accelerate completion timelines.
Market Restraints
- Structural timber supply concentration:Nordic and Baltic suppliers dominate engineered wood feedstock, exposing UK fabricators to currency volatility and shipping bottlenecks.
- Approved Document B friction:Evolving fire safety guidance from the Department for Levelling Up, Housing and Communities creates material selection uncertainty for taller timber structures.
- Skill gap in factory production:CNC machining and automated panel assembly require technicians that vocational training pipelines have not yet scaled to supply.
Strategic Opportunities
- Educational procurement expansion:Permanent classroom replacement represents the fastest-growing buyer category as local authorities seek rapid, low-disruption school capacity additions.
- MHCLG modular planning policy:Streamlined approvals for repeatable designs reduce pre-construction timelines, creating first-mover advantages for standardized housing typologies.
- Digital fabrication convergence:BIM-to-CNC workflows are compressing design-to-delivery cycles and enabling mass customization without sacrificing factory throughput.
Industry Challenges
- TRADA certification timelines:Factory-produced systems require structural integrity and fire performance classifications that testing protocols delay by months.
- Integration with legacy utilities:Timber frame assemblies must accommodate existing gas and electrical infrastructure standards that were not designed for panelized construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Prefab Wood Buildings Market |
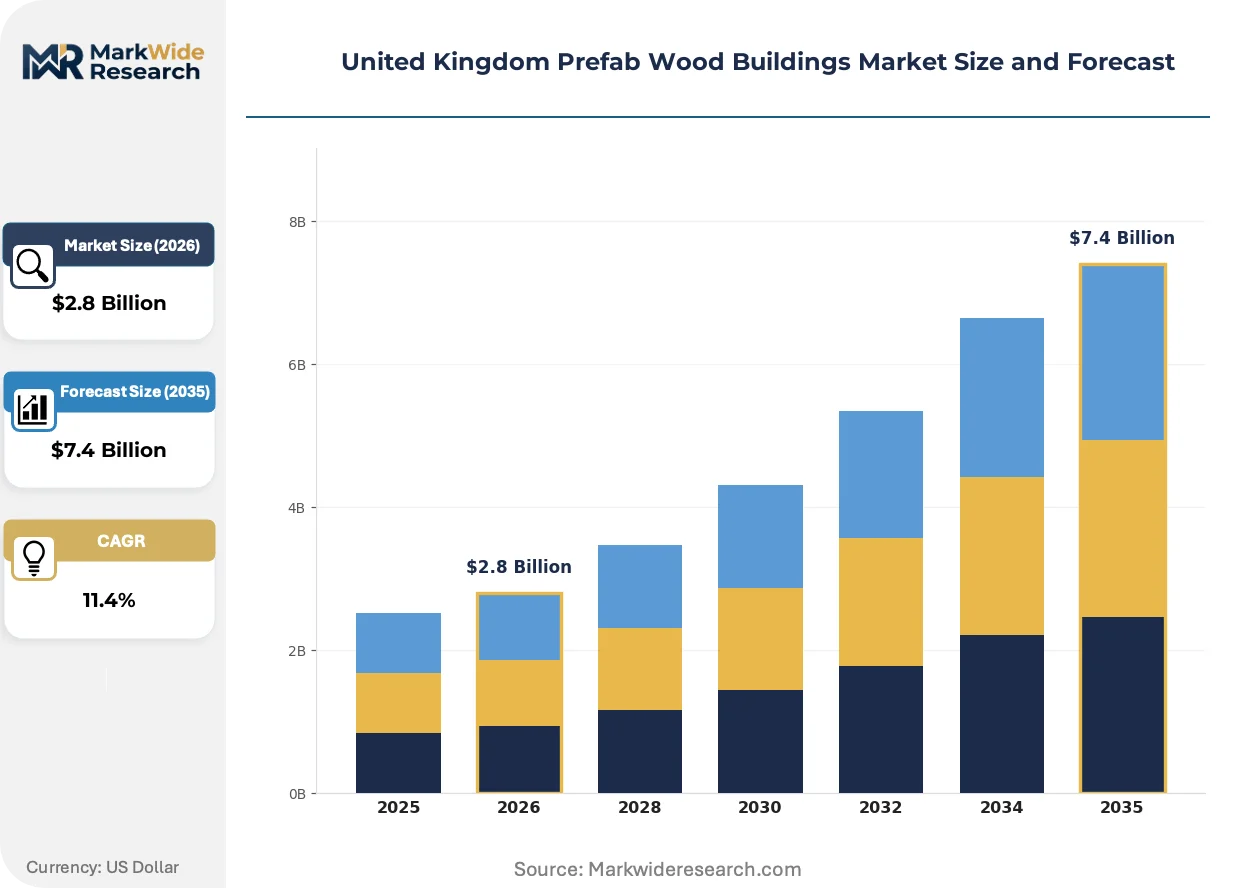
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Story, Multi-Story, Modular, Cabin Installation Type: On-Site, Off-Site, Integrated, Panelized End User: Residential, Commercial, Agricultural, Educational Design Style: Modern, Rustic, Industrial, Minimalist |
| Companies Covered | Legal & General Modular Homes, Baufritz, ZEDfactory, Algeco UK Limited, TG Escapes Limited, Passmores Portable Buildings Ltd, Phoenix Homes UK, The House Builders, Ecosphere, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Prefab Wood Buildings Market Evolving Landscape
Digital design-to-fabrication pipelines are compressing delivery timelines while regulatory pressure on embodied carbon accelerates material substitution away from steel and concrete.
Cross-laminated timber is unifying structural and finish functions into single factory-produced panels. Housing associations specify these systems for multi-storey social housing blocks where speed of erection outweighs upfront cost premiums. The technology is unifying previously separate trades—framing, insulation, and airtightness—into consolidated supply contracts that reduce site coordination complexity.
Building Regulations Part L amendments mandate operational energy reductions that fabric-first approaches satisfy more reliably than bolt-on renewable systems. The industrial consequence is specification lock-in toward high-performance timber envelopes that achieve thermal transmittance values below 0.15 W/m²K. Residential developers in the South East respond by pre-approving repeatable modular designs that secure faster planning permissions.
Buyer concentration among registered providers is consolidating contract volumes around fewer, larger suppliers capable of factory scale. Direct-to-housing-association frameworks are displacing traditional general contractor intermediaries in social housing procurement. This pattern is most visible in England where Homes England funding streams favor off-site construction methods in affordable housing allocations.
United Kingdom Prefab Wood Buildings Market Segmentation
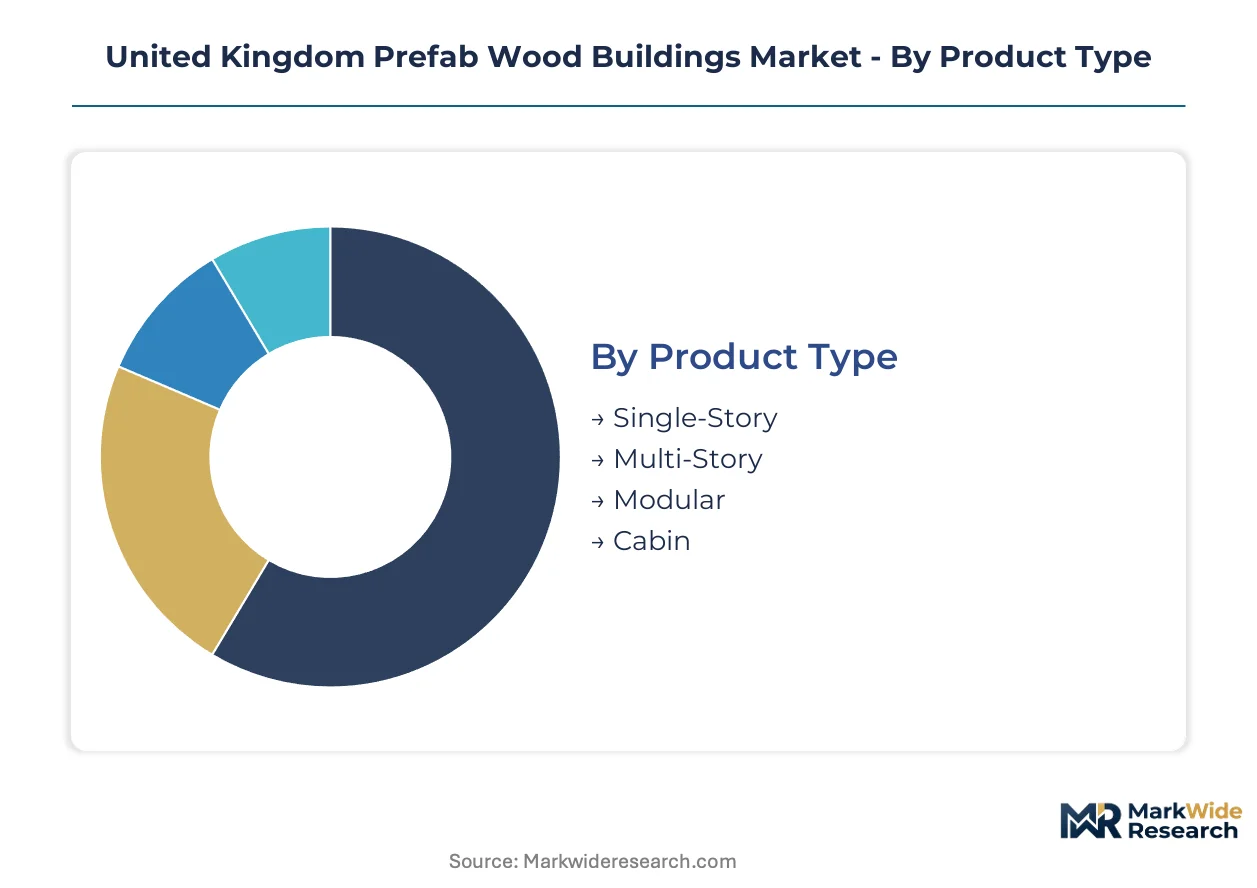
Segmentation in the United Kingdom prefab wood buildings market reveals how technical specifications, installation methods, and end-use requirements reshape procurement patterns. Housing associations and commercial developers prioritize different performance attributes, creating distinct demand pools that suppliers must navigate.
Product Type:
Structural height and assembly complexity define the technology axis across product categories.
- Multi-Story:Engineered timber systems enable six-to-ten storey structures through cross-laminated timber and glulam assemblies. South East England developers specify these for urban density solutions where land scarcity intensifies vertical construction economics.
- Modular:Factory-complete volumetric units arrive with MEP rough-ins and interior finishes installed. Housing association procurement consolidation favors this category for social housing pipelines requiring rapid site mobilization and repeatable quality.
- Single-Story:Panelized timber frames dominate suburban infill and rural residential applications. Garden annexes and ancillary dwellings drive volume in Home Counties where permitted development rights streamline approvals.
- Cabin:Compact footprint structures serve hospitality glamping sites and remote workspace pods. Scottish Highlands and Lake District operators specify these for seasonal accommodation with minimal foundation requirements.
Mature deployment sits with Single-Story products. Newer deployment is concentrated in Multi-Story systems.
Installation Type:
Supply chain positioning and value capture intensity vary sharply by assembly location.
- Off-Site:Factory-controlled manufacturing commands premium positioning through CNC machining precision and weather-independent production. Registered providers specify these methods for Future Homes Standard compliance where fabric-first efficiency demands tight thermal envelope control.
- Panelized:Flat-pack timber frame components ship to site for rapid crane-assisted erection. South East contractors favor this hybrid approach when site access constraints limit full modular delivery.
- On-Site:Traditional stick-frame construction persists in self-build segments and bespoke architectural projects. Cost-sensitive rural developments in Northern England retain this method where labor availability exceeds factory capacity.
- Integrated:Design-build contracts bundle architecture, engineering, and installation under single accountability. Commercial office developers in Greater Manchester specify these for accelerated programme delivery.
Margin concentration aligns with Off-Site methods. Volume expansion is climbing the fastest in Panelized approaches.
End User:
Procurement sophistication and specification authority differentiate buyer categories.
- Residential:Housing associations and private developers constitute the largest demand pool. Homes England funding streams prioritize off-site timber for affordable housing allocations, concentrating volume with factory-scale suppliers.
- Educational:Permanent classroom replacement represents the steepest expansion trajectory among buyer categories. Local authorities across England specify rapid-deployment timber structures for school capacity expansion with minimal disruption to existing operations.
- Commercial:Office and retail fit-out specialists specify timber for biophilic design credentials and embodied carbon reduction. Bristol and Manchester commercial developments lead adoption of exposed CLT aesthetics.
- Agricultural:Farm diversification projects and rural enterprise units utilize prefab timber for cost-controlled outbuilding construction. Welsh hill farms and Cotswolds estates deploy these for visitor accommodation and storage.
Specification standardization sits with Residential procurement. Design innovation is concentrating in Educational applications.
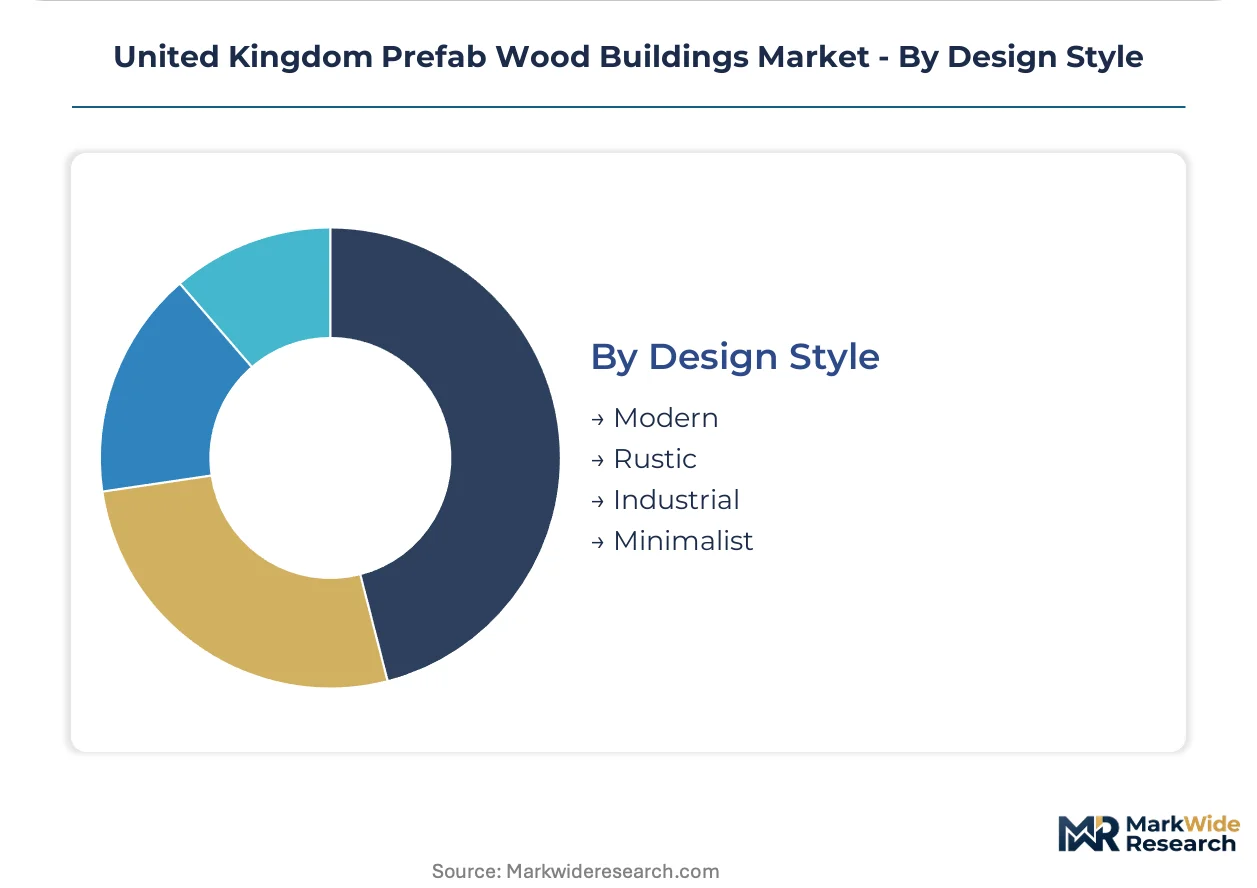
Design Style:
Aesthetic positioning and material expression create tiered market access.
- Modern:Clean lines and extensive glazing characterize self-build premium segments. Grand Designs-influenced purchasers in Home Counties specify these for planning permission advantages in conservation-sensitive locations.
- Rustic:Timber cladding and pitched roof profiles serve rural hospitality and holiday let markets. Lake District and Peak District operators favor this aesthetic for brand differentiation in saturated accommodation markets.
- Industrial:Exposed structural elements and black metal accents appeal to creative workspace conversions. East London and Manchester Northern Quarter developments specify these for tenant attraction in competitive commercial leasing.
- Minimalist:Reduced material palettes and precision jointing command architect-led commissions. High-net-worth individuals in Surrey and Berkshire specify these for bespoke residential projects.
Volume deployment sits with Modern styling. Premium positioning is concentrating in Minimalist commissions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baltic and Nordic timber feedstock corridors anchor prefab wood building supply chains across the United Kingdom, with finished product demand clustering around England's constrained urban land markets and Scotland's rural diversification zones.
London and South East England
Land scarcity and planning pressures concentrate demand for off-site timber construction in Greater London, Kent, and Surrey. The Future Homes Standard mandates fabric-first thermal performance that factory-controlled CLT panels deliver reliably. Housing associations in Croydon and Slough specify modular timber for rapid social housing deployment.
Midlands
Manufacturing heritage and central logistics positioning attract panelized timber fabricators to Birmingham and Nottingham corridors. MHCLG planning policy on modular construction streamlines approvals for repeatable designs in Leicester and Coventry. Factory-scale suppliers anchor production capacity near the M1 motorway corridor for national distribution reach.
North England
Cost-sensitive residential development and heritage conservation constraints shape timber frame specification in Manchester, Leeds, and Yorkshire. Local authorities in Sheffield procure prefab timber for permanent classroom replacement under educational expansion programs. Former industrial sites in Greater Manchester convert to modular construction facilities.
Scotland
Rural enterprise diversification and seasonal hospitality drive cabin and ancillary dwelling demand across the Highlands and Perthshire. Scottish Government building standards exceed English thermal requirements, favoring high-performance timber envelopes. Edinburgh and Glasgow housing associations trial modular timber for affordable housing pipelines.
Wales
Farm diversification projects and rural tourism accommodation concentrate prefab timber demand in Powys and Pembrokeshire. Welsh Government procurement frameworks prioritize off-site construction for public sector buildings. The A55 corridor hosts emerging panel assembly operations serving northwest England markets.
United Kingdom Prefab Wood Buildings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized niches and digital fabrication capabilities. The supplier base stratifies between factory-scale modular operators and bespoke timber engineering specialists. Three archetypes dominate: volume contractors securing housing association frameworks, premium self-build architects, and integrated zero-carbon designers. Competitive moves center on procurement consolidation capture and BIM-to-CNC workflow investment.
Among UK-based fabricators, Legal & General Modular Homes, Baufritz, and ZEDfactory occupy distinct positioning vectors. Legal & General Modular Homes exemplifies the scale-driven archetype securing large-volume contracts with registered providers. Baufritz anchors the premium self-build segment through bespoke timber engineering credentials. ZEDfactory represents the integrated design-build model aligning zero-carbon capabilities with tightening energy regulations.
| Leading Market Players |
|---|
| Legal & General Modular Homes |
| Baufritz |
| ZEDfactory |
| Algeco UK Limited |
| TG Escapes Limited |
| Passmores Portable Buildings Ltd |
| Phoenix Homes UK |
| The House Builders |
| Ecosphere |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up factory operators now control the mid-tier panelized segment, compressing supplier margins while enforcing volume-based pricing discipline that favors housing association frameworks over bespoke self-build commissions.
Pricing Analysis
Volume-scale modular contracts trade margin for pipeline security, while premium self-build segments retain pricing power through bespoke engineering credentials. Three-tier pricing structure across premium, standard, and economy levels separates certified Passivhaus performance from code-minimum social housing specifications. Cost compression in the standard tier intensifies because procurement consolidation forces competitive bidding among factory-scale suppliers. Housing associations exhibit highest price sensitivity due to fixed grant allocations, whereas high-net-worth self-build purchasers in Surrey and Berkshire demonstrate lowest elasticity for certified timber systems.
Supply Chain Analysis
Workforce availability constraints in the Midlands manufacturing corridor and Scottish panel assembly zones limit factory throughput expansion despite order backlogs. Engineered wood feedstock draws from Sweden, Finland, and Latvia, exposing UK fabricators to Baltic currency volatility and shipping bottlenecks through North Sea ports. Cross-laminated timber panels, glulam beams, and high-performance insulation batts constitute critical input dependencies. Single-source vulnerability concentrates in Nordic structural timber suppliers. Distribution runs through registered provider procurement frameworks that displace traditional merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK prefab wood buildings market is becoming a vertical-integration race as factory operators pursue captive supply of engineered timber feedstock to insulate margins from Baltic currency swings and shipping disruptions.
For Market Incumbents: Deepen backward integration into Nordic timber sourcing through long-term offtake agreements or equity stakes in Baltic sawmill operations. Expand CNC machining capacity in the M1 corridor to capture educational procurement growth. Housing association framework consolidation threatens margin erosion for non-integrated suppliers. For New Entrants and Emerging Players: Begin with digital fabrication capabilities targeting the educational segment in North England, where permanent classroom replacement demand outstocks incumbent factory capacity. Local authority procurement in Sheffield and Leeds favors rapid-deployment timber structures with minimal site disruption. Position through BIM-to-CNC workflow specialization rather than volume competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale panelized fabricators in the Midlands with underutilized factory footprints and established TRADA certification pathways. Long-term viability hinges on securing housing association framework relationships before procurement consolidation locks out smaller suppliers. Watch MHCLG planning policy amendments on modular construction approvals as the inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive Nordic feedstock sourcing insulates margins from currency volatility and shipping bottlenecks. |
| CNC Machining Capacity Expansion | Automated panel assembly in the M1 corridor captures educational procurement growth in Sheffield and Leeds. |
| TRADA Certification Investment | Accelerated fire performance testing timelines unlock housing association framework eligibility. |
| BIM-to-CNC Workflow Deployment | Digital fabrication convergence compresses design-to-delivery cycles for local authority school projects. |
| Registered Provider Framework Capture | Direct procurement relationships with Homes England-funded housing associations displace general contractor intermediaries. |
Research Methodology
Multi-period observation of housing association procurement volumes, factory capacity utilization rates, and planning approval timelines anchored the trend analysis, supplemented by interviews with modular manufacturing executives, TRADA certification officers, local authority housing directors, and educational estate managers. Secondary validation drew from MHCLG planning statistics, Homes England funding allocation data, Timber Research and Development Association technical bulletins, and Nordic timber trade flow customs records. Bottom-up project pipeline tracking triangulated against top-down construction output indices.
Input-output matrices modeled demand across product type, installation method, end-user segment, and regional planning authority clusters throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by housing association commitment pipelines and educational procurement schedules. Forecast inputs incorporated Future Homes Standard compliance cost curves, Baltic timber feedstock price indices, and MHCLG modular construction policy implementation rates.
Underlying measurement precision varies by segment; educational procurement and social housing pipelines carry tighter precision than self-build and commercial office fit-out categories. Forecasts reflect documented assumptions on regulatory implementation timelines, currency stability, and factory workforce scaling. Supply chain disruption, fire safety guidance amendments, and planning permission volatility warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Marble Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Tile Grout Market