
 US Plywood Market | 2026-2036
US Plywood Market Size, Share, and Industry Trends Forecast 2026-2036
US Plywood Market Intelligence
The proliferation of oriented strand board (OSB) as a lower-cost alternative for sheathing and subflooring is shifting product economics for US plywood manufacturers. Georgia-Pacific leverages its extensive distribution network to serve both residential and industrial customers. Weyerhaeuser differentiates through its vast timberland ownership and focus on sustainable sourcing. Boise Cascade competes by offering a broad portfolio of engineered wood products alongside its plywood lines.
Plywood is an engineered wood panel constructed from thin veneers of wood, bonded together with adhesives under heat and pressure. Each layer, or ply, is oriented with its grain at a right angle to adjacent layers, providing dimensional stability and high strength-to-weight ratios for load-bearing applications. The construction end-user segment accounts for the majority of market volume, primarily for structural applications. While structural product types are dominant, decorative and marine-grade plywoods provide opportunities for higher-margin sales.
The EPA enforces formaldehyde emission standards for composite wood products, impacting adhesive formulations and production costs. Concurrently, OSHA regulations govern workplace safety, including standards for wood dust exposure in manufacturing plants. These federal rules set a baseline for product compliance and operational conduct. Manufacturers must decide whether to focus on commodity-grade structural panels for volume or invest in specialized, higher-margin products for niche applications.
Market Dynamics
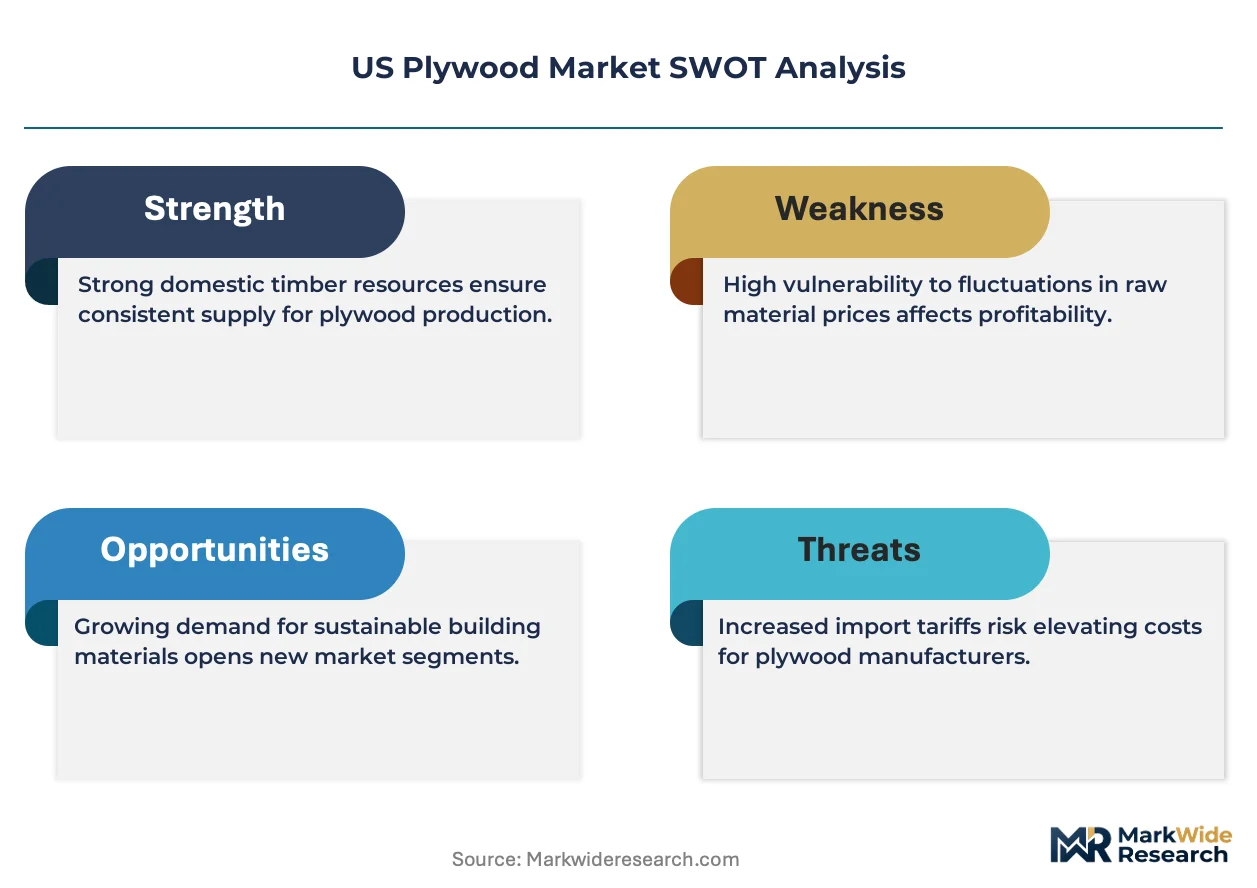
The US plywood market's fundamental dynamic is the tension between high-volume, price-sensitive structural panel demand and the competitive encroachment from oriented strand board (OSB). This forces manufacturers to either optimize for cost in commodity grades or differentiate through specialized products.
Growth Catalysts
- Residential Construction Demand:A persistent need for new single-family and multi-family housing, especially in the Southeast US, directly fuels consumption of structural plywood for framing, sheathing, and subflooring applications.
- Remodeling and Repair Activity:Homeowner investment in renovation projects provides a consistent secondary demand stream for various plywood grades, separate from the new construction cycle and often focused on smaller-volume purchases.
- Engineered Wood Systems:The adoption of mass timber and prefabricated building components creates demand for high-quality plywood as a constituent material in more complex, factory-built structural assemblies.
Market Restraints
- OSB Substitution:Oriented strand board presents a significant and persistent substitution threat, capturing market share in sheathing and subflooring applications due to its lower manufacturing cost and comparable structural performance.
- Timber Resource Volatility:Plywood manufacturers face fluctuating raw material costs and availability tied to regional timber harvests, which are influenced by factors like land use policy, weather events, and wildfire risk.
- Adhesive and Resin Costs:Compliance with EPA formaldehyde emission standards requires the use of more advanced, and often more expensive, adhesive systems, which directly increases the production cost of finished panels.
Strategic Opportunities
- Specialty and Decorative Panels:Developing higher-margin products like architectural-grade hardwood plywood or marine-grade panels allows manufacturers to target niche applications in cabinetry, furniture, and boatbuilding, away from commodity price pressures.
- Green Building Certifications:Offering products certified by the Forest Stewardship Council (FSC) or Sustainable Forestry Initiative (SFI) opens access to commercial and institutional projects requiring documented sustainable materials for LEED certification.
- Prefabricated Construction Supply:Manufacturers can supply custom-sized or specially treated plywood panels directly to the growing offsite and modular construction industry, which prioritizes material consistency and just-in-time delivery.
Industry Challenges
- Skilled Labor Shortages:Plywood mills, often located in rural areas, face persistent difficulties in recruiting and retaining skilled machine operators, maintenance technicians, and quality control personnel needed for modern plant operations.
- Capital-Intensive Upgrades:Modernizing presses, dryers, and veneer lathes to improve efficiency and meet regulatory requirements for emissions and safety demands significant capital investment with long payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Plywood Market |
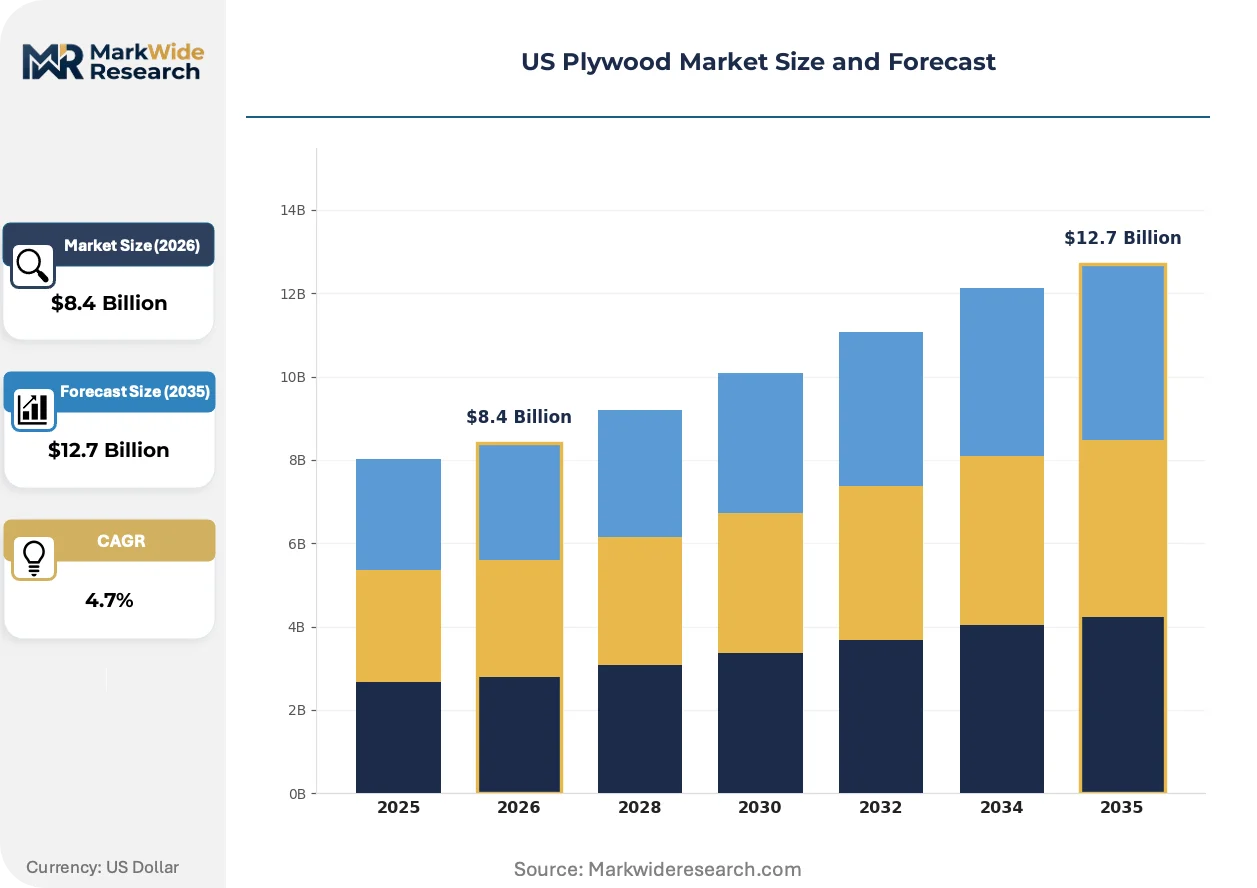
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative, Structural, Marine, Hardwood End User: Construction, Furniture, Industrial, DIY Grade: Interior, Exterior, Softwood, Birch Thickness: 1/4 Inch, 1/2 Inch, 3/4 Inch, Others |
| Companies Covered | Columbia Forest Products, PotlatchDeltic, Georgia-Pacific, Murphy Company, Swanson Group, Weyerhaeuser, Roseburg Forest Products, Louisiana-Pacific, Boise Cascade, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Plywood Market Strategic Shifts & Innovations
The US plywood industry is pivoting toward process automation and product specialization. This shift is a direct response to intense competition from lower-cost structural panel alternatives and stringent environmental regulations governing manufacturing and product emissions.
Advanced layup and pressing technology is a key focus for product development. Automated systems for veneer grading and composition allow for the precise placement of plies to optimize panel strength and stiffness. This technology is being adopted by large-scale producers for structural panel lines. The implementation of these systems is unifying the performance characteristics of panels made from varied wood fiber sources, creating a more consistent final product.
The EPA's Formaldehyde Standards for Composite Wood Products Act, under TSCA Title VI, continues to shape manufacturing processes. This regulation mandates strict limits on formaldehyde emissions, forcing producers to use compliant, low-emitting resin systems and undergo rigorous third-party certification. The structural panel segment, which competes heavily on price, is most affected as compliance adds direct material and administrative costs.
A notable behavioral shift is occurring in material specification for commercial and institutional construction. Architects and general contractors are increasingly selecting plywood based on life-cycle assessments and environmental product declarations, not solely on price or structural grade. This trend is most prominent in projects pursuing green building certifications in states like California, Oregon, and Washington.
US Plywood Market Segmentation
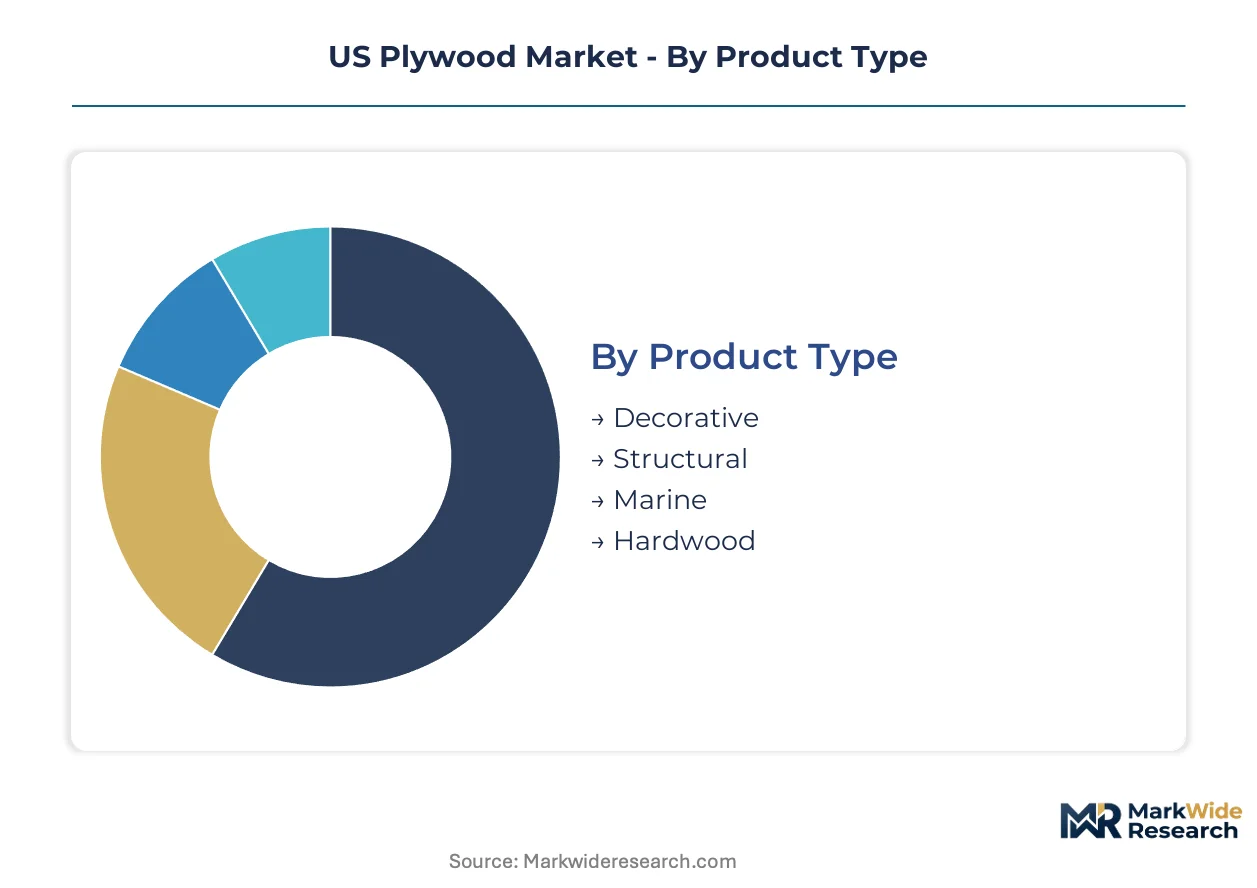
Understanding the US plywood market's segmentation is critical for manufacturers to align production capabilities with specific demand profiles. Product differentiation allows companies to target distinct end-use applications, optimizing for either volume efficiency in commodity segments or higher margins in specialized niches. This granular view reveals where investment in new technologies or capacity expansion provides the greatest strategic advantage.
Product Type:
The capital intensity of manufacturing varies significantly across plywood product types, with structural panels requiring robust, high-volume production lines and specialty panels demanding precise, often custom, fabrication processes.
- Structural:These panels are engineered for load-bearing applications, featuring high strength-to-weight ratios and consistent mechanical properties essential for building integrity. Demand concentrates in US residential construction, serving as sheathing, subflooring, and roof decking for new homes.
- Marine:Constructed with waterproof adhesives and void-free cores from durable wood species, marine plywood resists delamination and fungal attack in wet environments. This product type sees demand in boatbuilding and exterior applications where moisture exposure is constant, particularly along coastal regions.
- Decorative:Featuring aesthetic wood grain patterns or specialized finishes, decorative plywood is used where visual appeal is paramount. Interior design projects and furniture manufacturing drive demand for these visually distinctive panels.
- Hardwood:Produced from species like birch, maple, or oak, hardwood plywood offers superior strength and a fine grain suited for high-quality finished products. Cabinetry and architectural millwork represent key end-uses for these premium panels.
Most installed capacity flows through Structural plywood. Expansion is steepest in Marine applications.
End User:
Market participation across end-user segments dictates distinct sales channels and customer engagement strategies, ranging from large-scale B2B contracts to fragmented retail purchases.
- Construction:This segment encompasses both residential and commercial building projects, utilizing plywood for structural components, concrete forms, and interior finishes. New housing starts and commercial developments across the Southeast US drive substantial volume.
- Industrial:Plywood serves diverse industrial needs, including packaging, crating, truck trailer flooring, and material handling applications. Manufacturing facilities and logistics operations require consistent supply for these functional uses.
- Furniture:Manufacturers of cabinetry, case goods, and upholstered furniture integrate plywood for its stability, strength, and workability. The demand for durable and aesthetically pleasing components influences material selection in this sector.
- DIY:Do-It-Yourself consumers purchase plywood for home improvement projects, small repairs, and hobbyist applications. Retail home centers and hardware stores cater to this segment's varied project requirements.
The demand profile for End User segments is heavily influenced by the pace of new building activity.
Grade:
Plywood grades reflect manufacturing specifications and wood species, directly influencing both performance characteristics and market pricing across the supply chain.
- Softwood:Produced primarily from conifer species like pine or fir, softwood plywood offers excellent structural performance for construction applications. This commodity grade dominates the US market due to its availability and cost-effectiveness.
- Birch:Known for its fine grain, strength, and light color, birch plywood is favored for applications requiring a smooth finish and high-quality appearance. Cabinetry and furniture production in the US frequently specify this premium material.
- Interior:Designed for use in protected environments, interior-grade plywood uses adhesives that are not water-resistant, making it suitable for indoor structural and decorative applications. This grade is prevalent in subflooring and wall sheathing within enclosed structures.
- Exterior:Manufactured with waterproof glues, exterior-grade plywood withstands moisture exposure, making it ideal for outdoor structural components and sheathing. Roofing and exterior wall applications in US housing demand this weather-resistant product.
Strategic investment in Grade aims to capture higher value segments through specialized offerings like Birch plywood.
Thickness:
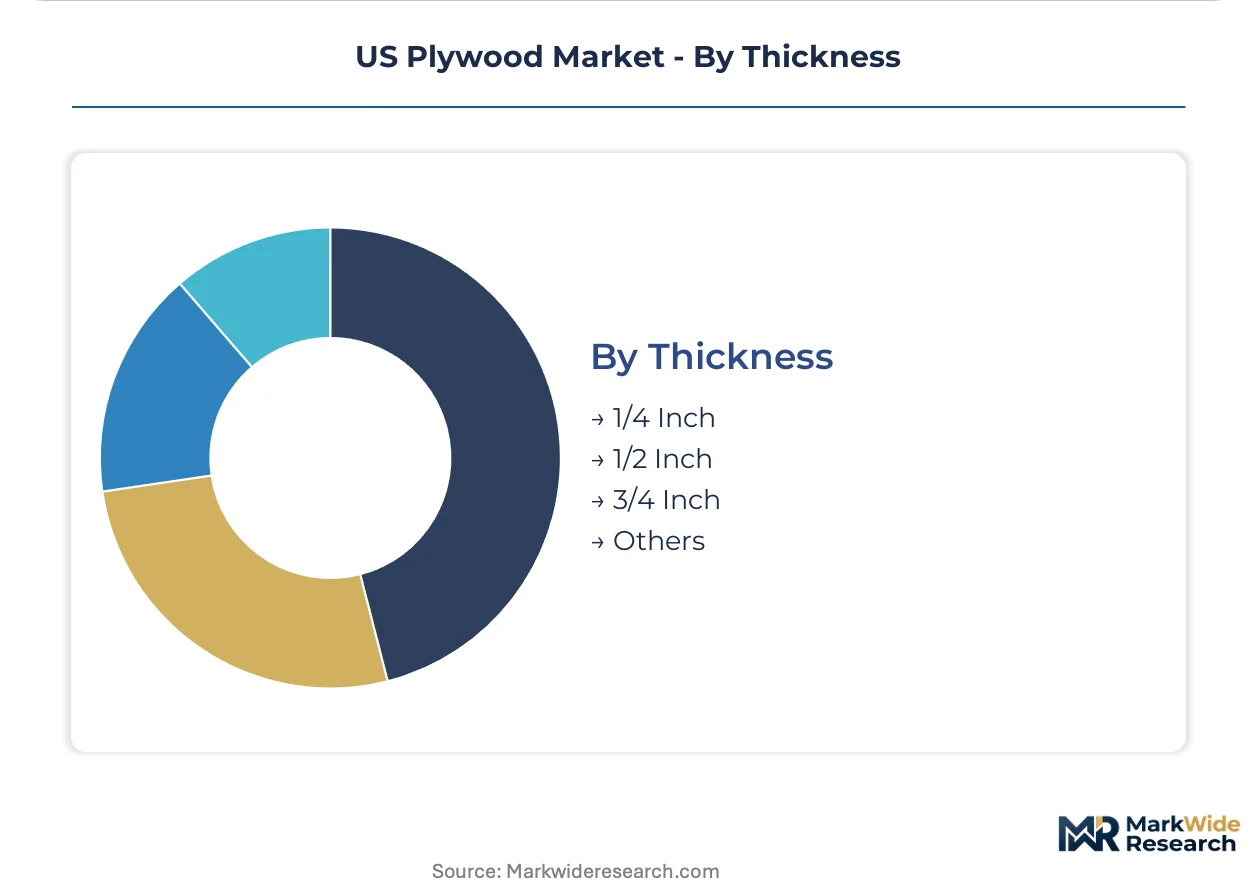
Plywood thickness directly correlates with its structural capacity and intended application, with manufacturers optimizing production lines for specific panel dimensions to meet performance requirements.
- 3/4 Inch:This thickness provides superior rigidity and load-bearing strength, making it a standard for subflooring, concrete forms, and heavy-duty shelving. New residential construction in the US consumes significant volumes of 3/4 inch panels.
- 1/2 Inch:Offering a balance of strength and manageability, 1/2 inch plywood is widely used for wall sheathing, roof decking, and general utility purposes. Its versatility makes it a staple in both new builds and renovation projects.
- 1/4 Inch:Thinner 1/4 inch plywood is often specified for underlayment, decorative paneling, and non-structural applications where flexibility and lighter weight are advantageous. Furniture backs and cabinet components frequently utilize this dimension.
- Others:This category encompasses a range of specialized thicknesses, including very thin veneers for craft projects or exceptionally thick panels for industrial applications. Custom orders for specific structural or aesthetic requirements drive this segment.
Panel thickness specifications directly align with structural performance requirements, with 3/4 Inch and 1/2 Inch representing the highest volume segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Southeast US, with its abundant timber resources and consistent residential construction activity, drives significant demand for plywood products across the nation. This region's building boom, particularly in single-family and multi-family housing, underpins the market's fundamental growth. Manufacturers often locate production facilities near these timber supplies and expanding urban centers.
Southeast US
Residential construction and new home builds consistently fuel plywood consumption in the Southeast US. The EPA's formaldehyde emission standards influence adhesive choices and production methods for regional mills. Major metropolitan areas like Atlanta, Georgia, see concentrated building activity, supporting local plywood demand for structural applications.
Pacific Northwest
The Pacific Northwest benefits from extensive timberland ownership and a focus on sustainable sourcing practices. Forest Stewardship Council (FSC) certifications and Sustainable Forestry Initiative (SFI) standards guide material procurement for producers. Oregon and Washington states are at the forefront of mass timber adoption, integrating high-quality plywood into engineered wood systems.
California
California's stringent green building certifications and robust remodeling activity create demand for specialized plywood panels. The state's CALGreen code promotes environmentally responsible construction, driving the selection of certified materials. Urban centers such as Los Angeles and the San Francisco Bay Area utilize architectural-grade plywood for high-value interior design projects.
Texas
Rapid population growth and continuous new housing starts in Texas generate substantial plywood consumption. Local building codes and energy efficiency standards shape material specifications for both residential and commercial projects. Houston and the Dallas-Fort Worth metropolitan areas require large volumes of plywood for widespread construction and industrial packaging applications.
Midwest
Agricultural building projects, home renovation, and furniture manufacturing sustain plywood demand across the Midwest. OSHA regulations concerning wood dust exposure mandate specific safety protocols within regional manufacturing plants. Cities like Chicago and Detroit serve as hubs for industrial applications and cabinet production, utilizing various plywood grades.
US Plywood Market Key Industry Players
Global majors compete with regional champions across manufacturing scale and product specialization within the US plywood market. This market exhibits a tiered structure, with large integrated producers often focusing on high-volume commodity panels. Specialized manufacturers target niche applications with higher-margin products. Dominant competitive moves include optimizing existing capacity and pursuing strategic product differentiation.
Within the large-scale integrated producers, Georgia-Pacific and Weyerhaeuser exemplify companies leveraging extensive timberland and distribution networks. Boise Cascade, a diversified wood products manufacturer, occupies a position offering a broad portfolio of engineered wood products alongside its plywood lines. These companies anchor the market with their ability to serve both residential and industrial customers across various product grades.
| Leading Market Players |
|---|
| Columbia Forest Products |
| PotlatchDeltic |
| Georgia-Pacific |
| Murphy Company |
| Swanson Group |
| Weyerhaeuser |
| Roseburg Forest Products |
| Louisiana-Pacific |
| Boise Cascade |
| Others |
Cost & Logistics Intelligence
A clear divergence between commodity structural panels and specialized plywood products drives distinct pricing and supply chain strategies. This bifurcation influences material sourcing and distribution models across the US plywood market.
Pricing Analysis
Fluctuating timber resource costs directly impact pricing for US plywood manufacturers, often passed through to end-users. The market operates with a hybrid pricing model, combining commodity spot pricing for structural softwood panels and contract-based pricing for specialized grades. Price differentiation stems from product type, such as marine-grade or architectural hardwood panels, and green building certifications like FSC or SFI. Pricing pressure intensifies for structural panels due to persistent OSB substitution, while decorative and marine segments exhibit less buyer price sensitivity.
Supply Chain Analysis
Logistics and freight costs significantly influence the supply chain, particularly for bulky plywood panels transported from timber-rich regions to construction hubs. The US plywood supply concentrates in the Southeast US and the Pacific Northwest, drawing heavily from regional timber harvests. Manufacturers depend on consistent timber availability and specialized adhesive systems, with raw material volatility and skilled labor shortages posing structural risks. Distribution runs through both large-scale B2B contracts for construction and retail home centers for DIY consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US plywood market is transitioning into a late-cycle quality story, driven by a demand shift towards premium specifications for green building certifications. This evolution necessitates strategic adjustments for market participants to capture value.
For Market Incumbents: Lock in existing distribution channels by offering a balanced portfolio of cost-optimized structural panels and higher-margin specialty plywood. Invest in advanced layup and pressing technology to improve efficiency and reduce production costs, countering the threat of OSB substitution. Secure long-term supply agreements for compliant, low-emitting resin systems to meet EPA formaldehyde emission standards. Pursue green building certifications like FSC or SFI to differentiate products for commercial projects.
For New Entrants and Emerging Players: Enter via specialized product niches, focusing on decorative or marine-grade plywood for applications where visual appeal and specific performance are paramount. Target the growing prefabricated construction industry by supplying custom-sized or specially treated panels, leveraging consistent material requirements. The cabinetry and architectural millwork segments represent a penetrable segment for high-quality birch or hardwood plywood. Develop direct relationships with modular builders to offer tailored solutions and just-in-time delivery.
For Investors and Strategic Acquirers: Consolidation pressure builds where commodity pricing compresses margins and regulatory compliance costs rise for smaller players. The US plywood market offers long-term viability, driven by persistent residential construction demand and remodeling activity. Target acquisition archetypes include vertically integrated mid-cap specialists with strong portfolios in high-margin decorative or marine-grade panels. A signal to watch is the accelerated investment in advanced manufacturing technologies by regional champions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast US | Addresses persistent residential construction demand in the region. |
| Investment in Advanced Layup Technology | Improves panel consistency and strength, differentiating products from OSB. |
| Development of Low-Formaldehyde Adhesive Systems | Ensures compliance with EPA regulations and expands market access. |
| Expansion into Prefabricated Construction Supply | Captures growth in the offsite and modular building sector. |
| Certification for Sustainable Sourcing (FSC/SFI) | Accesses commercial and institutional projects requiring green materials. |
Research Approach
Multiple input streams — primary interviews, industry reports, and government publications — were reconciled to build a comprehensive market view. This approach combined insights from plywood mill operators, construction contractors, and timberland managers with secondary validation from EPA reports and US Census Bureau housing data. The analysis utilized both bottom-up aggregation of segment data and top-down market sizing for robust triangulation.
Historical market performance was cross-referenced with expert panel input to project market trajectories across the analysis window. The quantitative model segmented the market by product type, end user, grade, thickness, and US regional demand. Compound annual growth rates were derived from projected housing starts data and anticipated timber harvest volumes.
The model holds under stable residential construction activity and consistent timber supply; deviation in raw material costs or significant regulatory shifts would shift market dynamics. Forecasts reflect assumptions regarding OSB substitution rates and adhesive technology advancements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market