
 Drywall Compound and Drywall Mud Market | 2026-2036
Drywall Compound and Drywall Mud Market Size, Share, and Industry Trends Forecast 2026-2036
Drywall Compound and Drywall Mud Market Insights
LEED v4.1 material ingredient reporting is restructuring specification criteria for interior finishing products across commercial construction. USG Corporation leverages its captive gypsum reserves to sustain vertical integration advantages in North American distribution. Saint-Gobain anchors European supply through specialized lightweight compound manufacturing. Knauf Gips KG competes on formulation breadth across ready-mix and setting-type portfolios.
Drywall compound and drywall mud comprise gypsum-based or vinyl-based paste formulations applied to gypsum panel joints, corners, and fastener depressions to create seamless interior wall and ceiling surfaces; standard ready-mix products contain approximately 35-45% calcium sulfate hemihydrate suspended in water with limestone fillers and polymer modifiers for adhesion and shrinkage control. The primary industrial purpose is substrate preparation for paint, texture, or wallcovering in residential, commercial, and institutional buildings. Ready-mix compound dominates volume due to contractor preference for consistency and reduced on-site labor, while setting-type compounds capture premium positioning in time-sensitive commercial schedules where rapid hardness development reduces cycle times. Lightweight variants represent the fastest-growing formulation segment as builders seek transport efficiency and reduced worker fatigue on large-scale projects.
EPA regulates VOC emissions from architectural coatings under 40 CFR Part 59, directly affecting compound solvent content and driving water-based formulation investment. OSHA's permissible exposure limits for respirable crystalline silica shape jobsite handling protocols and dust-control product development. California Air Resources Board (CARB) SCM 2007 standards for architectural coatings impose the strictest state-level limits, effectively setting the compliance ceiling for national product lines. Stakeholders must monitor evolving state-level chemical disclosure mandates and building code amendments that could accelerate substitution toward pre-mixed, low-emitting systems.
Market Dynamics
EPA emissions guidelines and state-level VOC restrictions are forcing manufacturers toward water-based, low-odor formulations while contractor preference for ready-mix consistency locks in formulation standardization across residential and commercial channels.
Growth Catalysts
- CARB SCM 2007 Standards:California's architectural coating limits create a compliance ceiling that national product lines must meet, accelerating investment in low-emitting water-based systems across multi-state distribution networks.
- Lightweight Formulation Chemistry:Glass microsphere and expanded perlite additives reduce bucket weight by 25-30%, cutting transport costs and worker fatigue on large-scale commercial projects.
- Multi-Family Construction Concentration:United States apartment and condominium development sustains bulk contractor purchasing through dedicated supply agreements and just-in-time delivery requirements.
Market Restraints
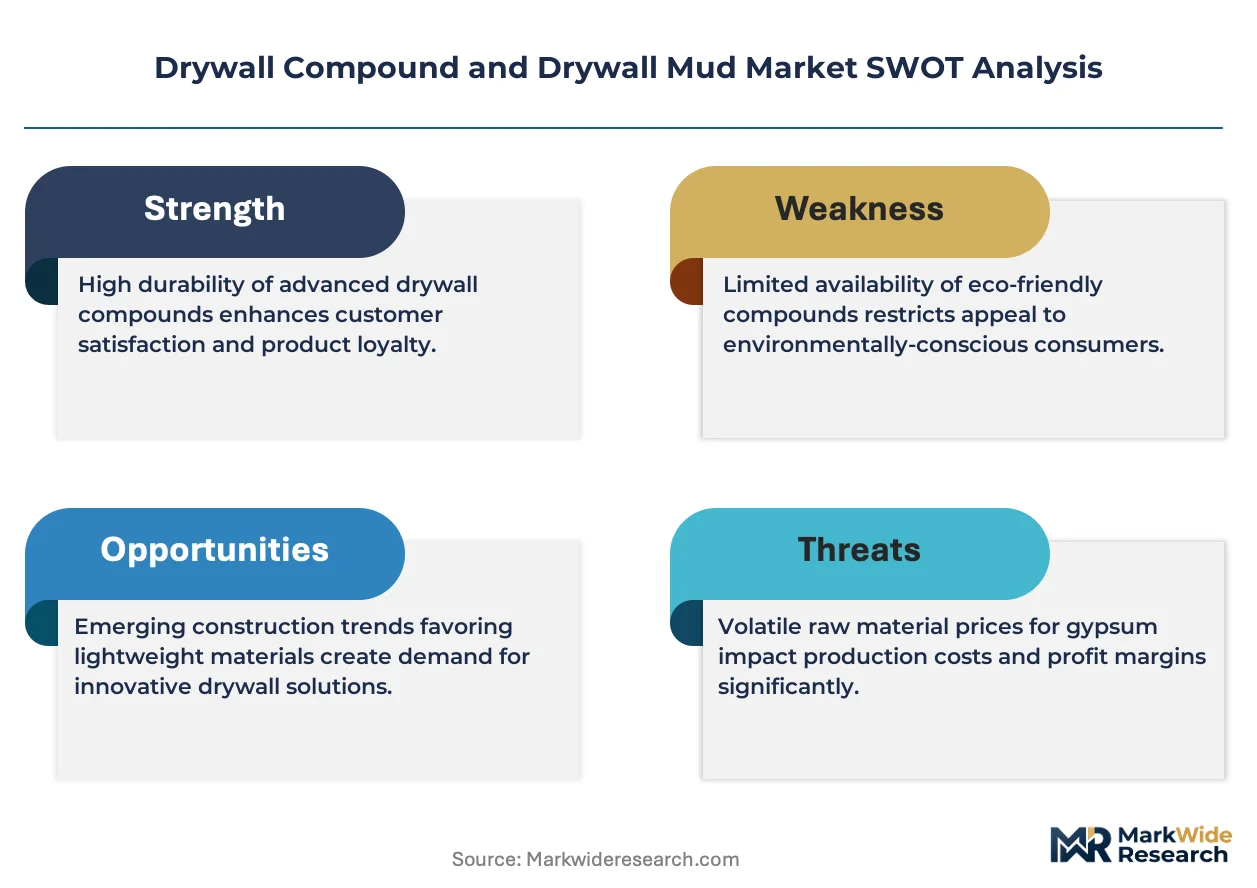
- Calcined Gypsum Price Volatility:Natural gas costs for gypsum calcination create margin pressure, with energy input fluctuations transmitted directly to compound pricing within 60-90 day windows.
- Respirable Silica Exposure Limits:OSHA's permissible exposure standards mandate dust-control investments and wet-sanding protocols that increase jobsite labor intensity and equipment costs.
- Setting-Type Compound Substitution Ceiling:Rapid-hardening formulations face application-skill barriers in residential renovation, limiting penetration beyond time-sensitive commercial schedules.
Strategic Opportunities
- Pre-Mixed Low-VOC Systems:EPA 40 CFR Part 59 compliance investments position manufacturers to capture specification-driven commercial projects seeking single-source LEED v4.1 material ingredient documentation.
- Lightweight Compound Portfolio Expansion:Formulation breadth across density grades enables premium positioning in large-scale developments where transport efficiency and worker productivity determine bid outcomes.
- Specialized Commercial Channels:Direct contractor supply relationships bypass traditional distribution markups in high-volume metropolitan construction corridors.
Industry Challenges
- Skilled Applicator Shortage:Finish quality requirements for Level 5 drywall specifications exceed available trained labor pools in rapid-growth construction markets.
- Reformulation Timeline Compression:State-level chemical disclosure mandates accelerate product redevelopment cycles, straining R&D bandwidth and testing validation pipelines.
- Legacy Inventory Obsolescence Risk:VOC regulation tightening in multiple jurisdictions threatens stranded stock of conventional solvent-containing formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drywall Compound and Drywall Mud Market |
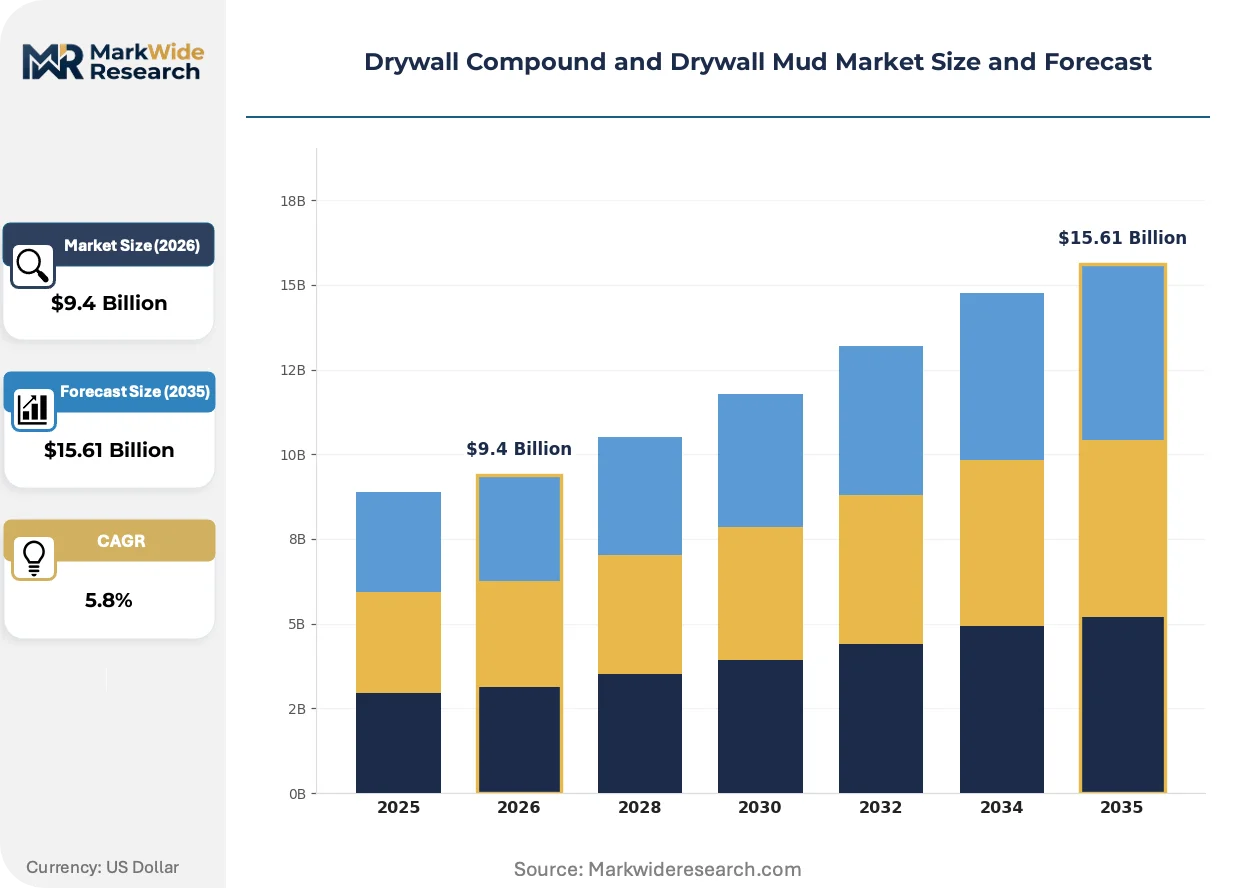
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $15.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-Mix Compound, Powdered Mud, Setting-Type Compound, All-Purpose Compound, Lightweight Compound Application: New Construction, Renovation Projects, Soundproofing, Fire Resistance, Decorative Finishing End User: Contractors, Drywall Installers, Builders, Homeowners, Specialty Trades Distribution Channel: Direct Sales, Retail Stores, Wholesalers, Online Platforms, Industrial Suppliers |
| Companies Covered | National Gypsum Company, CertainTeed Corporation, USG Corporation, American Gypsum Company, Etex Group, Saint-Gobain, Georgia-Pacific, Yoshino Gypsum Co., Ltd., Knauf Gips KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drywall Compound and Drywall Mud Market Trends and Innovations
Material science advances and regulatory disclosure requirements are compressing product development cycles while reshaping how contractors evaluate compound performance beyond basic adhesion and shrinkage metrics.
Polymer-modified lightweight compounds is unifying transport efficiency with application performance through controlled density reduction. Commercial contractors on large-scale developments are specifying these systems for ceiling work and multi-story applications where bucket weight directly impacts daily productivity. The technology is unifying what were previously separate purchasing decisions—compound performance versus worker safety—into single specification criteria that favor integrated lightweight portfolios.
REACH chemical registration requirements in Europe are extending substance documentation obligations through gypsum-based construction material supply chains. Manufacturers must now track and disclose full formulation chemistry down to 0.1% concentration thresholds for substances of very high concern. Interior finishing product lines destined for EU markets face reformulation pressure that exceeds North American disclosure standards, creating divergence in regional product portfolios.
Direct procurement from manufacturer distribution centers is displacing traditional two-step distribution in high-volume metropolitan construction corridors. Large commercial contractors with dedicated compound consumption are negotiating supply agreements that bypass regional distributor markups. The United States multi-family construction segment shows the strongest concentration of this channel shift, where project scale justifies dedicated logistics arrangements and consignment inventory positioning.
Drywall Compound and Drywall Mud Market Segmentation
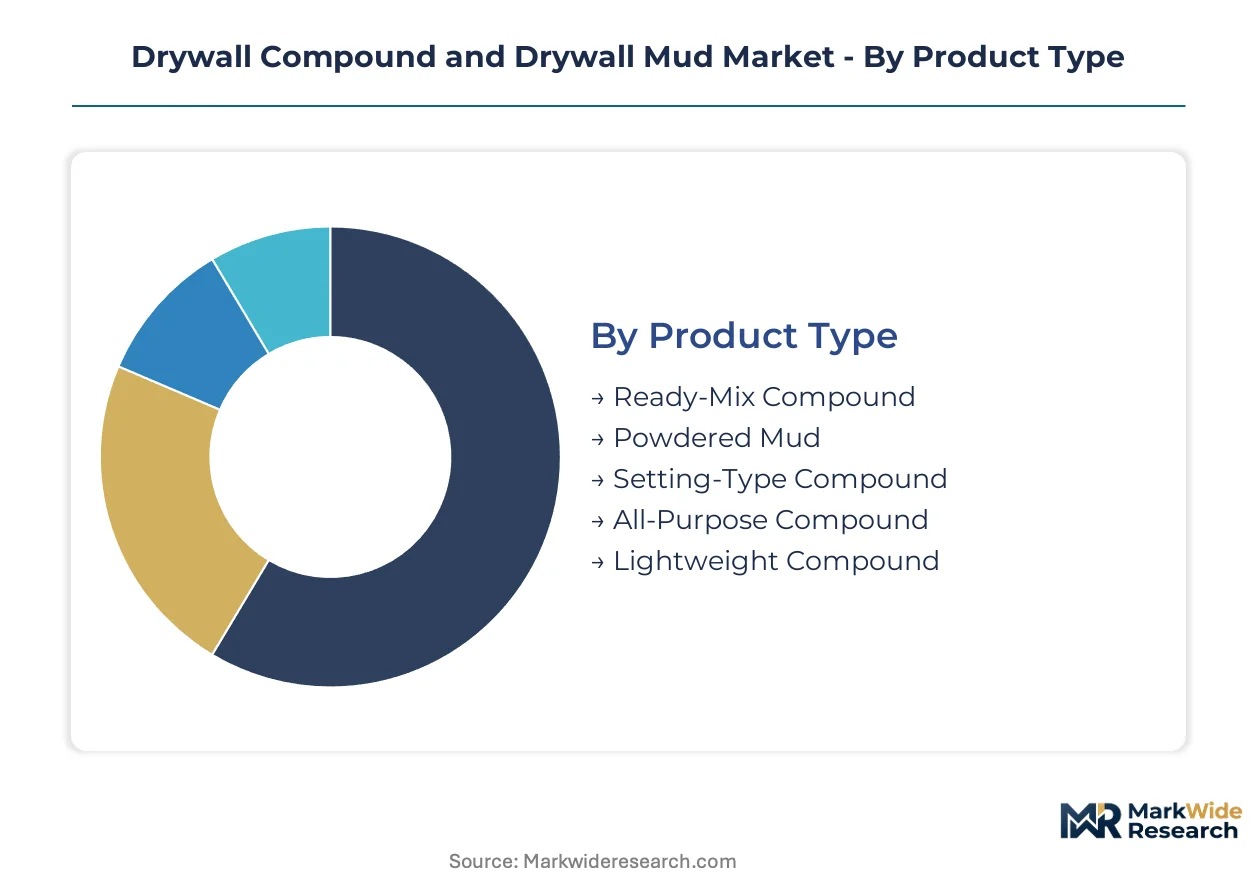
Product differentiation in drywall compounds follows contractor workflow requirements and project scale economics. Specification decisions hinge on drying time, transport weight, and surface finish level rather than price alone.
Product Type:
Formulation chemistry determines handling characteristics, set time, and application labor intensity across residential and commercial job sites.
- Ready-Mix Compound:Pre-hydrated gypsum paste with polymer modifiers delivers batch consistency and eliminates on-site water proportioning errors. Demand concentrates with multi-family contractors in the United States where just-in-time delivery and predictable workability reduce finishing cycle variability.
- Lightweight Compound:Glass microsphere or expanded perlite additives cut bucket weight by 25-30% while maintaining shrinkage control. Large-scale commercial developments specify these systems for ceiling work where worker fatigue and transport efficiency directly impact bid competitiveness.
- Powdered Mud:Dry calcium sulfate hemihydrate requires field mixing with water; cost-sensitive renovation segments favor this format for shelf stability and reduced shipping weight.
- Setting-Type Compound:Rapid-hardening formulations with crystallization accelerators target time-sensitive commercial schedules where same-day sanding is mandatory.
- All-Purpose Compound:Intermediate performance grade spans taping, topping, and texturing applications; residential contractors value SKU consolidation for inventory management.
Mature deployment sits with Ready-Mix Compound. Newer deployment is concentrated in Lightweight Compound.
Application:
Project type dictates surface preparation standards, drying time tolerance, and fire or acoustic rating requirements.
- New Construction:Green-field developments impose Level 5 finish specifications and tight sequencing schedules. United States multi-family builders drive volume through dedicated supply agreements and bulk purchasing leverage.
- Renovation Projects:Aging housing stock remediation favors low-odor, low-VOC formulations compatible with occupied dwelling constraints. CARB SCM 2007 compliance has become a baseline specification in California residential retrofit channels.
- Soundproofing:Mass-loaded gypsum systems with enhanced density target multi-family party wall assemblies and home theater installations.
- Fire Resistance:Intumescent and reinforced formulations meet UL 263 hourly ratings for commercial egress corridors and shaft enclosures.
- Decorative Finishing:Texture-grade compounds with controlled aggregate size enable skip-trowel, knockdown, and orange peel surface treatments.
Volume leadership belongs to New Construction. Steepest expansion trajectory is emerging in Renovation Projects.
End User:
Purchasing authority and technical sophistication vary sharply across professional and consumer segments.
- Contractors:Full-service general contractors with dedicated drywall crews negotiate direct manufacturer supply agreements in high-volume metropolitan corridors. Procurement decisions prioritize batch consistency and delivery reliability over per-unit price.
- Drywall Installers:Specialized finishing trades specify compound performance based on sandability, shrinkage, and open time. Skilled applicator shortages in rapid-growth construction markets constrain capacity expansion.
- Builders:Production homebuilders standardize on single-source compound portfolios to simplify inventory and warranty administration.
- Homeowners:DIY repair segments purchase small-format retail SKUs; price sensitivity limits premium formulation uptake.
- Specialty Trades:Acoustic and fireproofing contractors require certified performance documentation for inspection compliance.
Established purchasing dominance rests with Contractors. Emerging specification influence is shifting toward Drywall Installers.
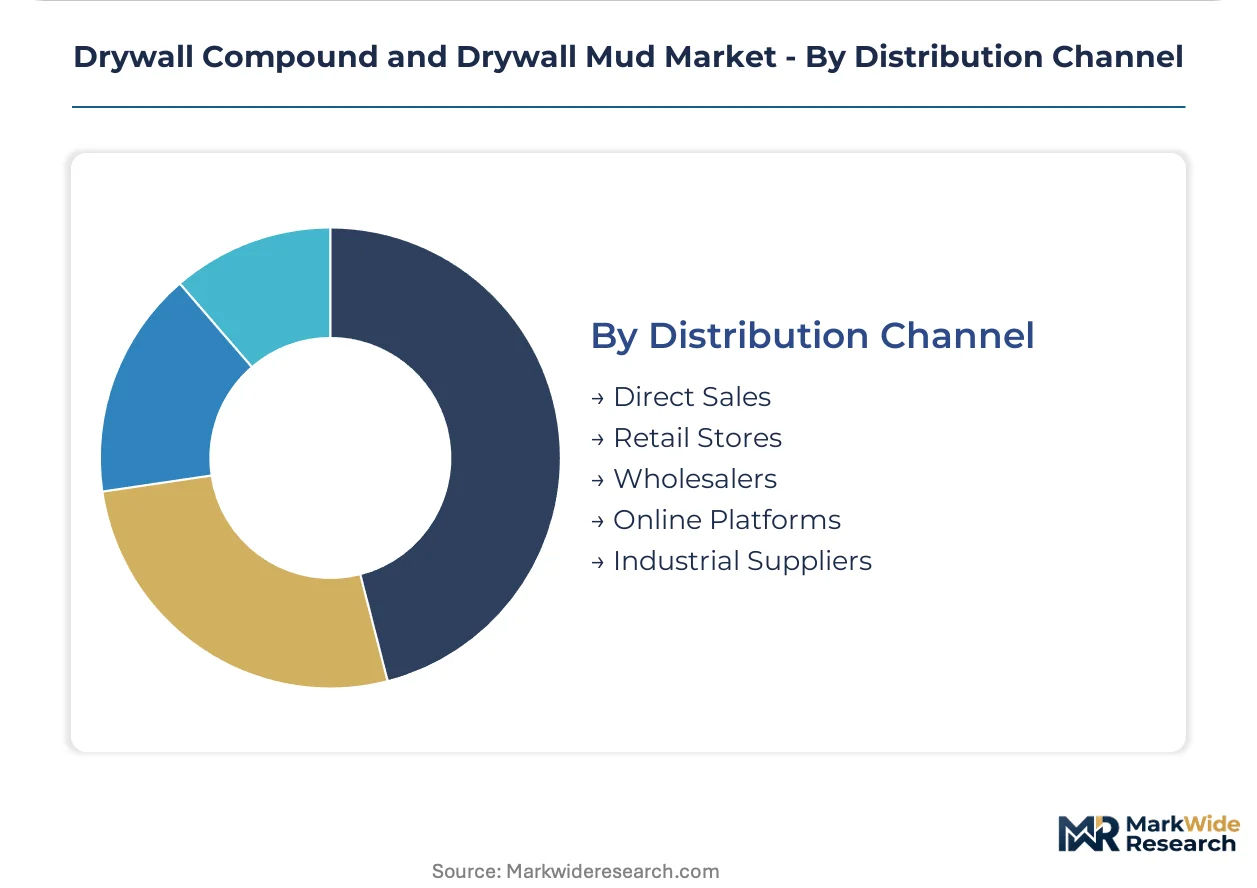
Distribution Channel:
Channel selection reflects order scale, delivery urgency, and technical support requirements.
- Direct Sales:Manufacturer distribution centers serve large commercial contractors with consignment inventory and dedicated logistics. This channel is gaining share fastest in United States multi-family construction corridors where project scale justifies bypassing distributor markups.
- Wholesalers:Regional building material distributors aggregate SKU breadth for mid-tier contractors with fragmented project portfolios.
- Retail Stores:Big-box and specialty retailer networks capture homeowner and small contractor spot purchases.
- Online Platforms:E-commerce penetration remains limited by weight-based shipping economics and contractor preference for immediate availability.
- Industrial Suppliers:MRO-focused distributors serve institutional maintenance departments with scheduled replenishment programs.
Traditional volume concentrates in Wholesalers. Channel displacement is accelerating through Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth Metroplex anchors North American drywall compound consumption through multi-family construction velocity and commercial development pipelines that outpace national averages.
United States
Multi-family housing starts in Sun Belt metros sustain bulk contractor purchasing through dedicated supply agreements. EPA 40 CFR Part 59 compliance investments dominate manufacturer R&D allocation. The Southeast construction corridor from Atlanta to Charlotte concentrates new manufacturing capacity expansion.
Canada
Urban densification in Toronto and Vancouver drives renovation-grade low-VOC formulation demand. Health Canada's PMRA oversees chemical registration for construction materials entering commercial distribution. Calgary-Edmonton energy sector commercial buildouts specify lightweight compounds for high-rise interior efficiency.
Germany
Energy-efficient building retrofit mandates accelerate gypsum-based interior system specification. ECHA REACH chemical registration requirements extend formulation disclosure obligations through supply chains. The Rhine-Ruhr industrial belt concentrates specialized lightweight compound manufacturing for Benelux export.
China
Urban renewal programs in tier-one cities generate renovation project volume exceeding new construction growth. MIIT industrial standards govern gypsum product quality certification for domestic distribution. The Yangtze River Delta manufacturing cluster supplies prefabricated wall systems with integrated finishing compounds.
United Arab Emirates
Mega-project construction in Dubai and Abu Dhabi specifies imported premium compounds for luxury finish standards. Dubai Municipality green building regulations align with LEED v4.1 material disclosure requirements. Jebel Ali logistics zones function as re-export hubs serving Saudi Arabian and Kuwaiti contractor markets.
Drywall Compound and Drywall Mud Market Competitive Landscape
The competitive structure tilts toward vertically integrated gypsum producers with captive mineral reserves. Three to five multinational building material conglomerates control formulation IP and distribution infrastructure across developed markets. Regional specialists compete on logistics proximity and contractor relationship density. Capacity expansion and portfolio diversification toward lightweight formulations represent the dominant competitive vectors.
Among North American building material conglomerates, USG Corporation and National Gypsum Company exemplify integrated supply chain control from gypsum extraction through finished compound distribution. Saint-Gobain anchors European market presence through specialized formulation manufacturing. Knauf Gips KG occupies a position spanning ready-mix and setting-type portfolio breadth across multiple continental markets. Yoshino Gypsum Co., Ltd. represents Asia-Pacific regional specialization with manufacturing concentration serving domestic Japanese and export demand.
| Leading Market Players |
|---|
| National Gypsum Company |
| CertainTeed Corporation |
| USG Corporation |
| American Gypsum Company |
| Etex Group |
| Saint-Gobain |
| Georgia-Pacific |
| Yoshino Gypsum Co., Ltd. |
| Knauf Gips KG |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap compound specialists with multi-generational management structures dominate regional supply pockets in the United States and Germany, anchoring pricing discipline through captive gypsum reserves and long-term contractor relationships that resist spot-market volatility.
Pricing Analysis
Value-based pricing anchored to application throughput and finish quality outcomes dominates contractor procurement decisions, separating premium lightweight formulations from commodity ready-mix tiers. Price differentiation separates LEED v4.1-compliant low-VOC systems from standard formulations, with volume scale and transport distance as secondary drivers. Cost compression in standard ready-mix segments is intensifying because natural gas input volatility transmits directly to calcined gypsum pricing within 60-90 day windows. DIY homeowners exhibit highest price sensitivity, while multi-family general contractors prioritize batch consistency and delivery reliability over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with United States gypsum quarrying operations concentrated in Oklahoma and Nevada, where regional logistics constraints create delivery bottlenecks for Atlantic and Pacific coastal construction corridors. Manufacturing draws from calcined gypsum, limestone fillers, and polymer modifier additives, with glass microsphere supply for lightweight formulations resting on specialized chemical suppliers. Tariff exposure on Canadian gypsum imports creates margin pressure for Great Lakes distribution networks. Distribution runs through manufacturer-direct consignment arrangements displacing traditional two-step wholesaler channels in high-volume metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EPA emissions compliance investments and state-level VOC disclosure mandates force undercapitalized regional formulators into strategic exit or acquisition.
For Market Incumbents: Extend formulation breadth across density grades to capture specification-driven commercial projects seeking integrated lightweight portfolios. Deepen backward integration into captive gypsum reserves in the Southeast United States construction corridor to defend margin position against energy input volatility. Invest in LEED v4.1 material ingredient documentation capabilities to preempt substitution threats from pre-mixed low-emitting systems. For New Entrants and Emerging Players: Capture renovation-grade low-VOC specification demand in California and Toronto where CARB SCM 2007 and Health Canada PMRA compliance create qualification barriers for legacy suppliers. Target direct procurement relationships with mid-tier multi-family developers in Sun Belt metros bypassing entrenched distributor relationships. Lead with specialized lightweight compound manufacturing for ceiling-intensive commercial developments where worker productivity determines bid outcomes. For Investors and Strategic Acquirers: Distressed-cycle entries favor family-owned regional compound manufacturers with underutilized quarry assets in the United States Mountain West and Prairie provinces. Long-term viability hinges on reformulation agility and direct channel penetration rather than raw scale. Watch for inflection in state-level chemical disclosure mandate acceleration as signal for stranded inventory risk and forced seller dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Formulation Portfolio Expansion | Glass microsphere integration captures specification premiums in large-scale commercial ceiling applications. |
| Backward Integration into Gypsum Reserves | Captive mineral supply in Oklahoma and Nevada insulates margin from natural gas price transmission. |
| Direct Contractor Supply Agreements | Consignment inventory positioning in Dallas-Fort Worth and Atlanta corridors displaces wholesaler markups. |
| Low-VOC Reformulation Investment | EPA 40 CFR Part 59 compliance enables specification capture in LEED v4.1 commercial projects. |
| Regional Manufacturing Capacity Addition | Southeast United States plant expansion reduces transport cost to Sun Belt multi-family construction velocity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drywall contractor procurement managers, plant engineers at gypsum processing facilities, distribution channel partners, and commercial construction project directors. Secondary sources included EPA enforcement databases, CARB SCM compliance filings, SEC 10-K disclosures from building material conglomerates, and gypsum industry association production statistics. Bottom-up volume modeling triangulated against top-down construction spending allocation estimates across residential, commercial, and institutional end-uses.
Granularity-level modeling deployed product-type segmentation at the SKU level, application-type at the project-phase level, and end-user at the purchasing-authority level across the analysis window. CAGRs derived from weighted regression against housing starts, commercial square footage permits, and renovation spending indices. Industry-specific forecast inputs included natural gas price scenarios for calcination energy costs and state-level regulatory adoption curves for VOC disclosure mandates.
The model holds under stable regulatory enforcement timelines and construction labor availability; deviation in accelerated state-level chemical disclosure mandates or severe skilled applicator shortages would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Silos Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Timber Floor Joist Market