
 Autonomous Mining Truck Market | 2026-2036
Autonomous Mining Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Mining Truck Market Analysis
Shortages of qualified heavy-vehicle operators is reorganizing investment priorities across open-pit mining operations worldwide. Caterpillar leverages its integrated MineStar Command platform to sustain technology leadership in autonomous haulage systems. Komatsu anchors its position through the FrontRunner AHS, which dominates deployment scale across Australian iron ore basins. Volvo Trucks competes by extending its autonomous transport solutions from quarrying into underground applications.
Autonomous mining trucks are self-driving heavy haul vehicles engineered to transport ore and overburden without onboard human operators, typically integrating GPS navigation, lidar systems, and automation software to achieve centimeter-level positioning accuracy in dust-laden, GPS-degraded environments. Their primary industrial purpose centers on eliminating fatal accidents in haulage loops while achieving continuous 24-hour production cycles that human-staffed fleets cannot replicate. Lidar systems and computer vision represent the fastest-growing technology segments, as sensor fusion architectures displace single-modality GPS-dependent systems in high-dust, high-vibration conditions. The 200-ton payload capacity class captures the dominant share of current deployments, though 100-ton configurations are gaining traction in quarrying and site preparation where lighter, more flexible fleets reduce capital intensity for mid-tier contractors.
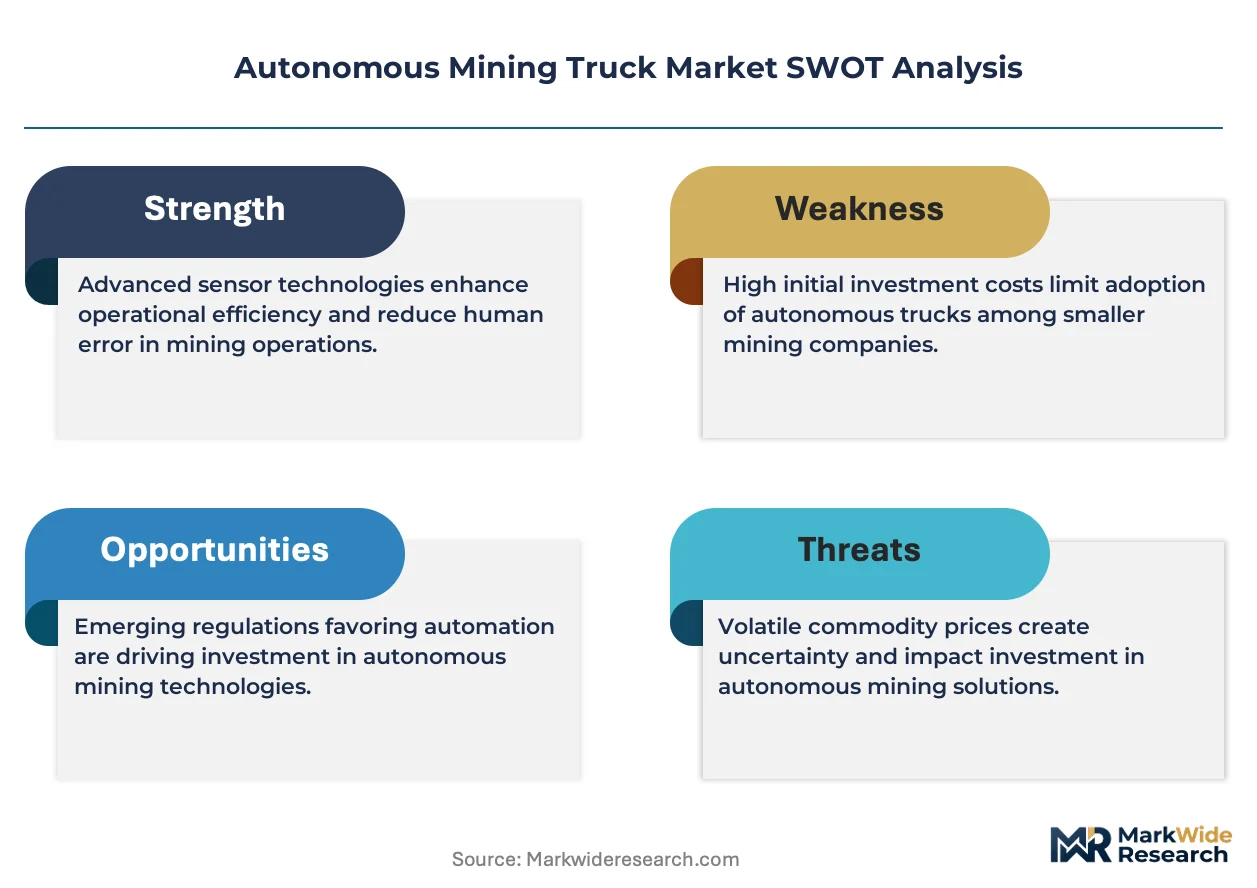
The Australian national mining regulator enforces ISO 17757 compliance for autonomous vehicle safety management systems, while the US Mine Safety and Health Administration (MSHA) is developing parallel standards for American surface operations. The EU Machinery Directive, transposed through national regulators like Germany's KBA, imposes CE-marking requirements on any autonomous haul platform imported for European quarrying or site preparation. Stakeholders must monitor how evolving functional-safety standards reshape supplier qualification barriers and determine which automation-software architectures achieve cross-jurisdictional certification portability.
Market Dynamics
ISO 17757 safety certification requirements are compressing supplier qualification timelines across Australian, Canadian, and Chilean mining jurisdictions, forcing automation-software architectures to achieve cross-border portability or face exclusion from tier-one fleet tenders.
Growth Catalysts
- Labor scarcity in surface haulage:Australian iron ore basins face acute shortages of qualified heavy-vehicle operators, redirecting capital toward autonomous fleet replacements.
- ISO 17757 adoption:National regulators in mining-intensive economies are mandating autonomous vehicle safety management systems, creating compliance-driven replacement cycles.
- Sensor fusion advancement:Lidar-computer vision integration achieves centimeter-level positioning in GPS-degraded, dust-laden conditions, expanding operational envelopes.
Market Restraints
- Capital intensity threshold:200-ton payload-class autonomous platforms require specialized maintenance infrastructure unavailable to mid-tier contractors.
- Supplier concentration risk:Automation-software stacks for haulage systems concentrate among three integrated platform providers, limiting buyer negotiation leverage.
- Technical limitation in underground:Lidar-dependent navigation faces signal degradation in confined, high-humidity tunnel environments, constraining deployment scope.
Strategic Opportunities
- Underpenetrated quarrying sector:100-ton configuration autonomous trucks address capital-constrained mid-tier contractors in Scandinavian aggregate operations.
- Technology convergence:Integration of predictive maintenance AI with autonomous drive systems enables condition-based fleet scheduling.
- Canadian regulatory tailwind:Alberta's oil sands regulators are evaluating autonomous haulage exemptions under MSHA-aligned safety frameworks.
Industry Challenges
- Functional-safety certification timeline:ISO 17757 compliance validation extends 18-24 months, delaying fleet deployment schedules.
- Integration complexity with legacy dispatch systems:Proprietary fleet-management software from incumbent suppliers creates interoperability barriers during mixed-fleet transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Mining Truck Market |
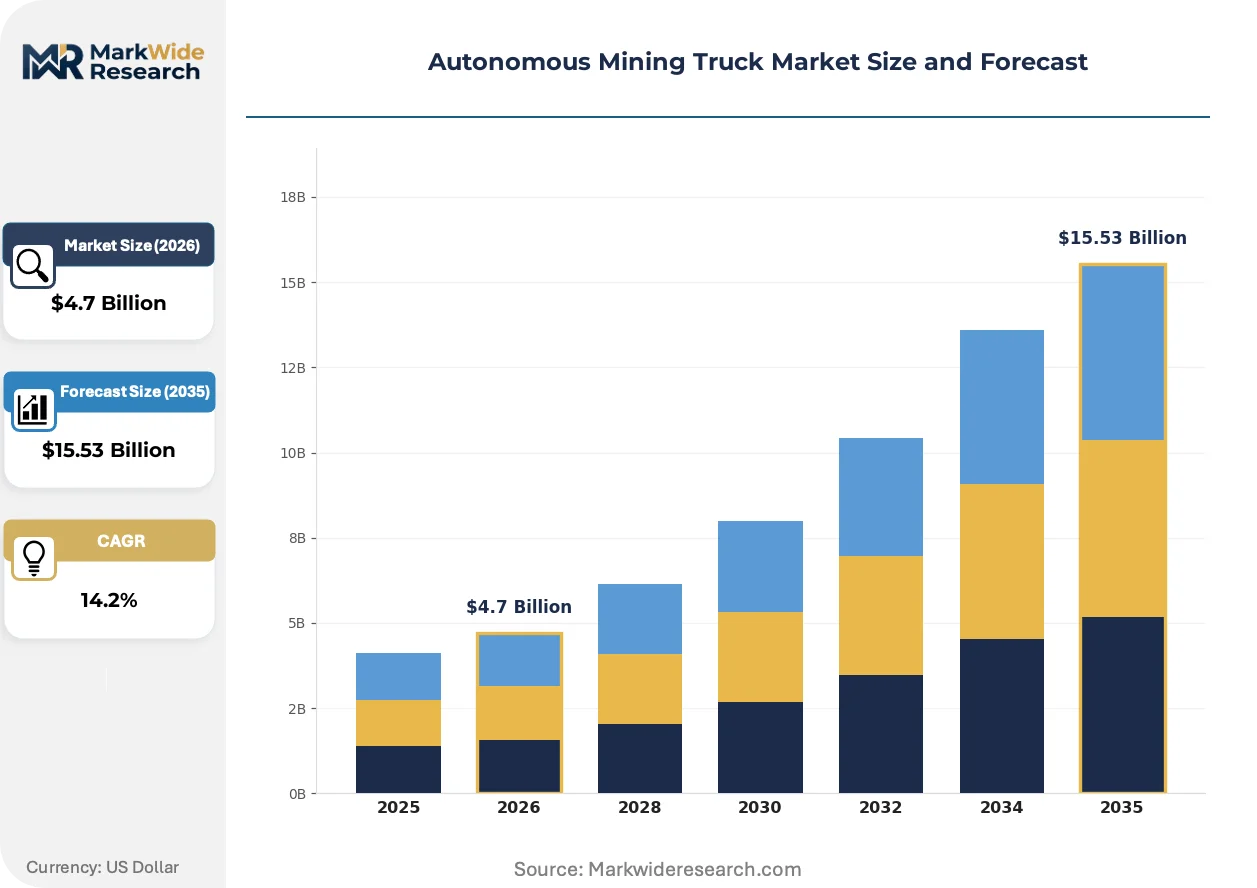
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Navigation, Lidar Systems, Computer Vision, Automation Software Payload Capacity: 50 Tons, 100 Tons, 150 Tons, 200 Tons Application: Coal Mining, Metal Mining, Quarrying, Site Preparation End User: Mining Companies, Contractors, Equipment Manufacturers, OEMs |
| Companies Covered | Kodiak Robotics, Liebherr, Caterpillar, Volvo Trucks, XCMG, Komatsu, BELAZ, PACCAR, Aurora Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Mining Truck Market Emerging Trajectories
Automation architectures are pivoting from single-modality GPS dependence toward redundant sensor-fusion stacks, while regulatory pressure accelerates cross-jurisdictional certification portability requirements.
Sensor fusion architectures combining lidar, radar, and computer vision are fragmenting the historical dominance of GPS-dependent navigation in high-dust haulage corridors. Australian iron ore operators are adopting these triple-redundant systems for 24-hour continuous operations. The technology is fragmenting supplier market power by enabling modular component sourcing from specialized perception vendors.
MSHA is developing parallel autonomous vehicle safety standards for American surface mining operations, mirroring Australian ISO 17757 enforcement patterns. This regulatory convergence will force automation-software providers to engineer single-stack compliance for both jurisdictions. Underground coal operators in Appalachia face the steepest adaptation curve due to legacy ventilation and communications infrastructure.
Buyers are unbundling after-sales service contracts from initial platform procurement, selecting specialized third-party maintainers for predictive analytics and component lifecycle management. This disintermediation compresses OEM service margins while expanding independent software vendor opportunities. The shift is most visible in Western Australia's Pilbara region, where Rio Tinto and BHP have established multi-vendor maintenance ecosystems.
Autonomous Mining Truck Market Segmentation
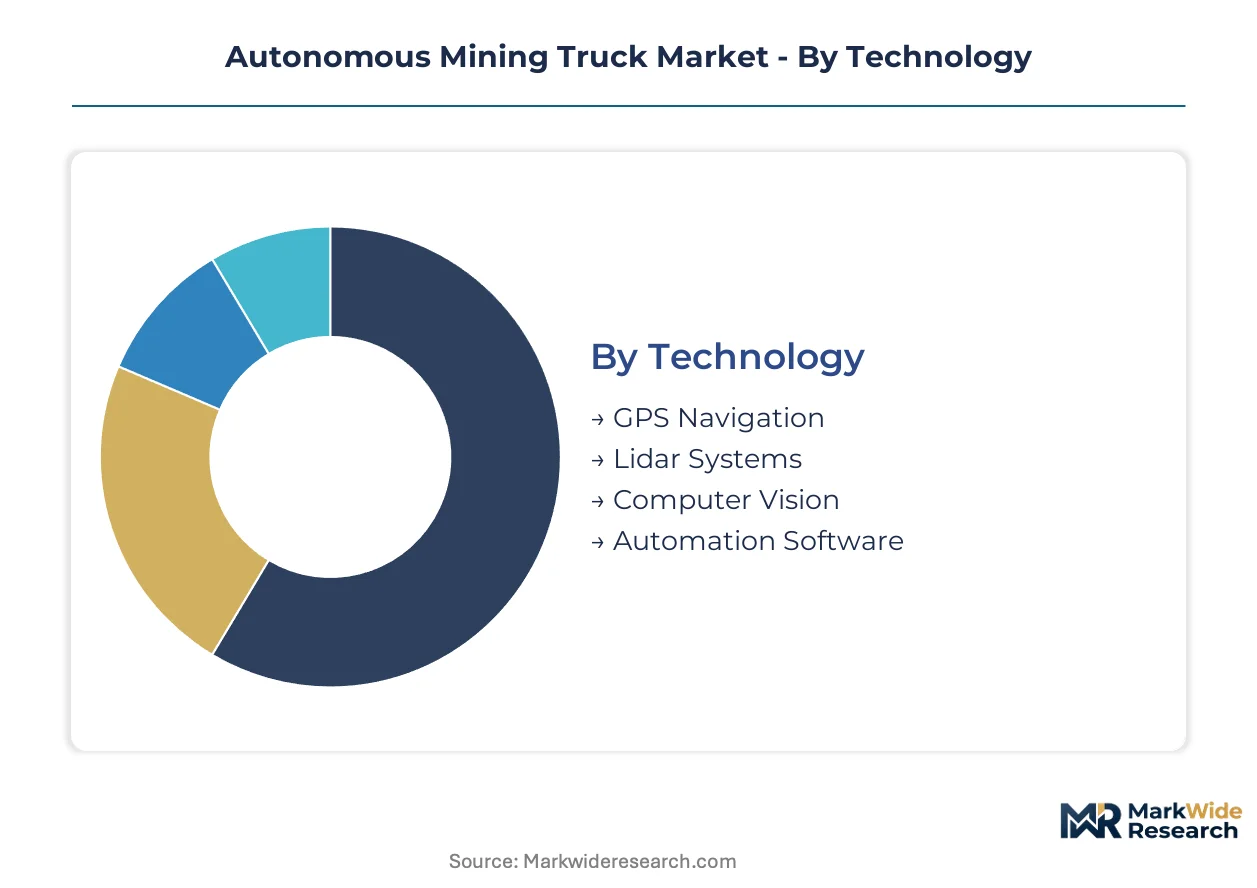
Segmentation reveals how autonomous mining truck procurement concentrates around payload-class economics and regulatory-driven technology choices. Buyers select technology stacks and capacity configurations based on ore body characteristics, labor cost structures, and ISO 17757 compliance timelines.
Technology:
GPS-dependent systems face the steepest substitution pressure as sensor-fusion architectures prove operational in dust-degraded conditions where satellite signals fail.
- Lidar Systems:These laser-based perception modules generate real-time 3D point clouds for obstacle detection and centimeter-level positioning in GPS-denied haulage loops. Australian iron ore operators in the Pilbara region specify triple-redundant lidar configurations for 24-hour continuous operations where dust storms interrupt satellite navigation.
- Computer Vision:Convolutional neural networks process camera feeds to classify haul road conditions, detect personnel incursions, and validate dump zone clearance. Surface coal operations in Alberta's oil sands are integrating computer vision with thermal imaging for night-shift haulage where wildlife encounters create collision risks.
- GPS Navigation:Satellite-dependent positioning remains the baseline architecture for open-pit operations with clear sky visibility.
- Automation Software:Fleet orchestration algorithms coordinate truck dispatch, speed optimization, and maintenance scheduling across heterogeneous vehicle platforms.
Lidar systems anchor the volume base while computer vision gains share at the steepest rate.
Payload Capacity:
Capital intensity stratification separates tier-one miners from mid-tier contractors, with 200-ton platforms requiring specialized maintenance infrastructure unavailable to smaller operators.
- 200 Tons:These ultra-class haulers dominate Australian iron ore basins where economies of scale justify dedicated autonomous corridors. BHP and Rio Tinto operate fully autonomous fleets in this class, achieving production cycles impossible with human-staffed operations.
- 100 Tons:Mid-capacity configurations address quarrying and site preparation markets where lighter, more flexible fleets reduce capital intensity. Scandinavian aggregate contractors in Norway and Sweden are adopting 100-ton autonomous trucks for seasonal operations with variable haul distances.
- 50 Tons:Compact autonomous platforms serve narrow-pit mining and urban construction material extraction.
- 150 Tons:Intermediate capacity bridges the gap between quarrying flexibility and bulk-haul efficiency.
200-ton platforms dominate current deployment value while 100-ton configurations expand most quickly into underpenetrated quarrying markets.
Application:
Underground deployment constraints fragment the addressable market, with surface applications capturing nearly all autonomous haulage investment.
- Metal Mining:Copper and iron ore operations in Chile's Atacama Desert and Western Australia's Pilbara region anchor autonomous fleet investment. These high-volume, low-grade deposits justify the capital intensity of 200-ton autonomous corridors with dedicated road maintenance and fueling infrastructure.
- Quarrying:Aggregate extraction in Germany's Rhineland and France's Massif Central regions is adopting 100-ton autonomous configurations for limestone and granite operations. CE-marking requirements under the EU Machinery Directive are accelerating certification timelines for European deployments.
- Coal Mining:Surface thermal coal operations in the Powder River Basin and Alberta oil sands evaluate autonomous exemptions under MSHA-aligned safety frameworks.
- Site Preparation:Civil earthmoving contractors deploy autonomous trucks for repetitive cut-and-fill operations with fixed haul profiles.
Metal mining anchors procurement volume while quarrying climbs the fastest as mid-tier contractors access autonomous technology at reduced payload classes.
End User:
Procurement authority concentration among integrated miners compresses contractor negotiation leverage and fragments equipment manufacturer service revenue.
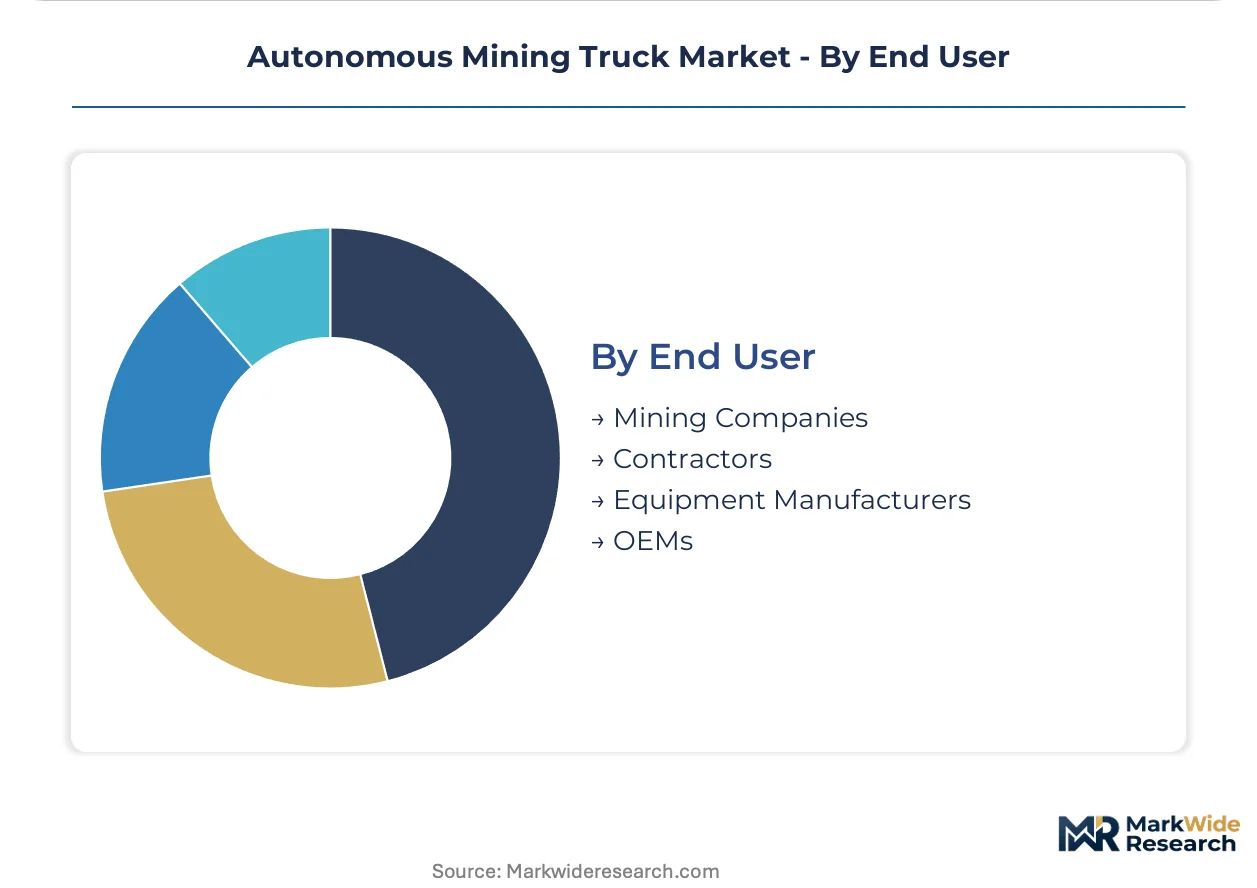
- Mining Companies:Tier-one diversified miners like BHP, Rio Tinto, and Vale specify autonomous platforms directly, unbundling after-sales contracts from initial procurement. These operators maintain multi-vendor maintenance ecosystems in Western Australia and Brazil's Carajás basin.
- Contractors:Mid-tier mining services firms in Canada's oil sands and Chile's copper belt lease autonomous capacity through equipment-as-a-service arrangements. This model transfers certification risk and maintenance complexity to OEM balance sheets.
- Equipment Manufacturers:Caterpillar and Komatsu integrate autonomous drive systems into new-build haulers for direct sale or lease.
- OEMs:Original equipment manufacturers supply automation retrofit kits for existing fleet conversions.
Mining companies anchor demand concentration while contractors gain procurement share through risk-transfer leasing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara operators in Western Australia command pricing leverage unavailable to Alberta oil sands contractors, compressing procurement timelines for tier-one miners while mid-tier North American players face extended certification cycles.
Australia
Acute shortages of qualified heavy-vehicle operators in Western Australia's iron ore basins redirect capital toward autonomous fleet replacements. The national mining regulator enforces ISO 17757 compliance for autonomous vehicle safety management systems. BHP and Rio Tinto operate fully autonomous haulage corridors across the Pilbara region, achieving continuous production cycles.
Canada
Alberta's oil sands operators evaluate autonomous haulage exemptions under MSHA-aligned safety frameworks for surface thermal coal operations. Health Canada coordinates with provincial regulators on functional-safety certification timelines for autonomous mining vehicles. Contractors in Fort McMurray lease autonomous capacity through equipment-as-a-service arrangements that transfer certification risk to OEM balance sheets.
Chile
Copper operations in the Atacama Desert anchor autonomous fleet investment for high-volume, low-grade deposits requiring dedicated road maintenance infrastructure. The country's national mining regulator mandates ISO 17757 certification for autonomous vehicle deployments. Codelco and BHP operate autonomous corridors in the Antofagasta Region, where sensor-fusion architectures prove operational in dust-degraded conditions.
United States
Surface coal operations in the Powder River Basin assess autonomous exemptions under developing MSHA autonomous vehicle safety standards. The Mine Safety and Health Administration mirrors Australian ISO 17757 enforcement patterns for American surface mining operations. Underground coal operators in Appalachia face steep adaptation curves due to legacy ventilation and communications infrastructure constraints.
Sweden
Scandinavian aggregate contractors adopt 100-ton autonomous configurations for seasonal quarrying operations with variable haul distances. The EU Machinery Directive, transposed through national regulators, imposes CE-marking requirements on autonomous haul platforms for European quarrying. Volvo Trucks extends autonomous transport solutions from quarrying into underground applications across the Bergslagen mining district.
Autonomous Mining Truck Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated platform providers dominate certification-intensive markets while regional fabricators capture price-sensitive quarrying segments. The vendor base concentrates among three automation-software stack providers, limiting buyer negotiation leverage in tier-one fleet tenders. Strategic archetypes include integrated mining-technology conglomerates, specialized autonomous-drive developers, and heavy-equipment manufacturers with automation retrofit capabilities. Dominant competitive moves encompass sensor-fusion technology licensing agreements and geographic expansion into underpenetrated quarrying markets.
Among integrated mining-technology providers, Caterpillar and Komatsu occupy positions exemplifying the scale-driven archetype, while Volvo Trucks represents the European specialist vector extending autonomous solutions across surface and underground applications.
| Leading Market Players |
|---|
| Kodiak Robotics |
| Liebherr |
| Caterpillar |
| Volvo Trucks |
| XCMG |
| Komatsu |
| BELAZ |
| PACCAR |
| Aurora Innovation |
| Others |
Supply Flow & Price Mechanics
200-ton payload-class production scale concentrates supplier market power, compressing price floors for mid-tier contractors while tier-one miners extract volume discounts through multi-fleet procurement leverage. Australian iron ore operators unbundle after-sales contracts from initial platform purchases, redirecting service revenue toward specialized third-party maintainers.
Pricing Analysis
Configured-to-order pricing for sensor-fusion architectures commands substantial premiums over standard GPS-dependent configurations, with triple-redundant lidar stacks priced at certification-grade tiers. Pricing stratifies across ISO 17757-compliant, MSHA-aligned, and CE-marking tiers, reflecting jurisdictional validation costs. Cost compression in 100-ton quarrying configurations is intensifying because Scandinavian aggregate contractors demand flexible lease structures. Mid-tier contractors exhibit highest price sensitivity, while Pilbara-based diversified miners absorb premium pricing for continuous-operation reliability.
Supply Chain Analysis
Japan and Germany anchor automation-software development and precision sensor manufacturing for autonomous haulage systems. Lidar modules draw from specialized optics foundries, while high-torque electric drivetrains rest on rare-earth magnet supply concentrated in Chinese processing facilities. Single-source vulnerability in perception-chip supply creates exposure to export-control restrictions. Distribution runs through OEM-direct sales for tier-one miners and equipment-as-a-service leasing channels for capital-constrained contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance software attach rates are expanding faster than autonomous hardware unit sales, creating recurring-revenue layers that reshape supplier economics. Service unbundling in Western Australia demonstrates how aftermarket specialization fragments traditional OEM margin structures.
For Market Incumbents: Compound platform stickiness by embedding predictive analytics into fleet orchestration software, creating switching costs that resist modular component sourcing. Deepen backward integration into lidar perception hardware to defend against specialized sensor vendors. Prioritize ISO 17757 certification portability across Australian, Canadian, and Chilean jurisdictions to preempt regulatory fragmentation. For New Entrants and Emerging Players: Differentiate on underground navigation architectures that resolve lidar signal degradation in high-humidity tunnel environments, a technical white space where surface-optimized incumbents hold limited IP. Target quarrying contractors in Norway and Sweden with 100-ton autonomous configurations priced for seasonal operational flexibility. Pursue equipment-as-a-service go-to-market structures that transfer certification risk from contractor balance sheets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors autonomous-drive software specialists with proven sensor-fusion stacks and cross-jurisdictional certification traction. Long-term viability hinges on five-to-ten-year fleet replacement cycles in Australian iron ore basins. Acquisition targets should demonstrate deployed autonomy in dust-degraded conditions with validated safety records. Monitor Alberta oil sands regulatory exemptions as inflection signal for North American market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Fusion Stack Certification | ISO 17757 validation across Australian, Canadian, and Chilean mining jurisdictions unlocks tier-one fleet tenders. |
| Predictive Maintenance Platform Integration | AI-driven condition monitoring at Rio Tinto's Pilbara operations enables condition-based fleet scheduling. |
| Underground Navigation Architecture Development | Lidar-radar fusion for confined tunnel environments addresses technical constraints limiting deployment scope. |
| Equipment-as-a-Service Model Expansion | Risk-transfer leasing structures attract mid-tier contractors in Alberta oil sands and Scandinavian quarrying. |
| Aftermarket Service Ecosystem Buildout | Multi-vendor maintenance partnerships at BHP's Western Australian sites fragment traditional OEM service margins. |
Methodological Framework
The analysis maps lidar systems, computer vision, GPS navigation, and automation software segments, each validated through fleet operations directors, maintenance managers at tier-one miners, and aftermarket service specialists. Primary interviews with procurement leads at diversified mining companies, equipment-as-a-service program managers, and regulatory compliance officers combined with secondary validation through MSHA docket filings, ISO certification registries, and national mining regulator enforcement notices. Bottom-up deployment tallies across Australian, Canadian, and Chilean operations triangulate against top-down equipment manufacturer revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models technology adoption by payload capacity tier, application segment, and end-user procurement authority, with regional regulatory cluster as an additional dimension. CAGRs derive from fitted growth curves applied to disclosed fleet deployment schedules and replacement cycle assumptions. Forecast inputs include labor scarcity indices in Western Australian iron ore basins and ISO 17757 certification timeline data from national mining regulators.
Material uncertainties — regulatory standard divergence, autonomous vehicle liability frameworks, and commodity price volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding sensor cost decline curves and certification portability across jurisdictions. Recalibration cycles align with material shifts in MSHA rulemaking and Australian national mining regulator enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Rock Duster Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Global Smart Mining Solution Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Auger Drilling Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Logging Cable Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Horizontal Shaft Impact Crusher Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Underground Mining Equipment Market