
 North America Non-Residential Polished Concrete Market | 2026-2036
North America Non-Residential Polished Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Residential Polished Concrete Market Analysis
Single-source supply arrangements for diamond abrasives and densifier chemicals is consolidating into multi-vendor frameworks among large flooring contractors. Sika leverages its chemical admixtures portfolio to bundle densifiers with repair systems. Husqvarna Group anchors the equipment layer through its planetary grinder distribution network across the United States and Canada. HTC Group competes on tooling longevity, extending replacement intervals for high-volume polishers.
Non-residential polished concrete denotes a mechanically refined concrete surface achieved through progressive diamond grinding to specified grit levels, typically 800 to 3000, followed by chemical densification with lithium- or sodium-silicate compounds that harden the cap and produce light-reflective finishes. The process yields abrasion-resistant floors for commercial and industrial environments where durability and low lifecycle cost override aesthetic complexity. Among market segments, industrial applications dominate current volume due to warehouse and logistics facility construction, while hospitality and showroom finishes command premium pricing through high-gloss specifications. Matte and satin finishes in office buildings represent a maturing tier where competition centers on installation speed rather than technical differentiation.
OSHA silica exposure standards and EPA VOC regulations for floor coatings shape product formulation and jobsite ventilation requirements across the United States. Canada's National Building Code and provincial environmental statutes in Ontario and British Columbia impose parallel compliance burdens on cross-border contractors. Stakeholders must monitor evolving state-level low-carbon procurement mandates and densifier chemistry certifications that could reshape specification criteria and contractor qualification thresholds.
Market Dynamics
The EPA's low-VOC mandates and OSHA silica exposure standards are compressing contractor qualification thresholds while lithium-silicate densifier chemistry rewrites specification criteria across industrial flooring procurement.
Growth Catalysts
- Warehouse construction permits:Texas, California, and Ontario industrial development is accelerating polished concrete specification for distribution center flooring systems.
- EPA low-VOC material emphasis:Federal procurement guidelines now favor chemical densifiers over epoxy coatings in federal facility renovations.
- Lithium-silicate chemistry advances:Penetration depth and cure speed improvements are displacing sodium-silicate alternatives in high-traffic specifications.
Market Restraints
- Diamond abrasive supply concentration:Synthetic diamond sourcing clusters in limited manufacturing geographies, exposing contractors to input cost volatility.
- OSHA silica compliance burden:Enhanced ventilation and PPE requirements add labor hours to every grinding operation, compressing margin structures.
- Epoxy coating substitution:Lower upfront cost and faster installation timelines retain specification share in budget-constrained commercial retrofits.
Strategic Opportunities
- Canadian provincial low-carbon mandates:British Columbia and Ontario procurement rules increasingly credit embodied-carbon reductions from polished concrete versus resinous systems.
- Hospitality high-gloss segment:Premium showroom and retail specifications remain underpenetrated relative to industrial volume, offering pricing power.
- Equipment rental channel expansion:Planetary grinder fleet operators are building turnkey service models that bundle tooling, chemicals, and training for mid-tier contractors.
Industry Challenges
- Skilled polisher shortage:Mastery of progressive grit sequencing and densifier application timing requires apprenticeship periods that outpace labor market supply.
- Cross-border certification friction:Canadian contractors bidding US projects face divergent OSHA and provincial safety training reciprocity gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Residential Polished Concrete Market |
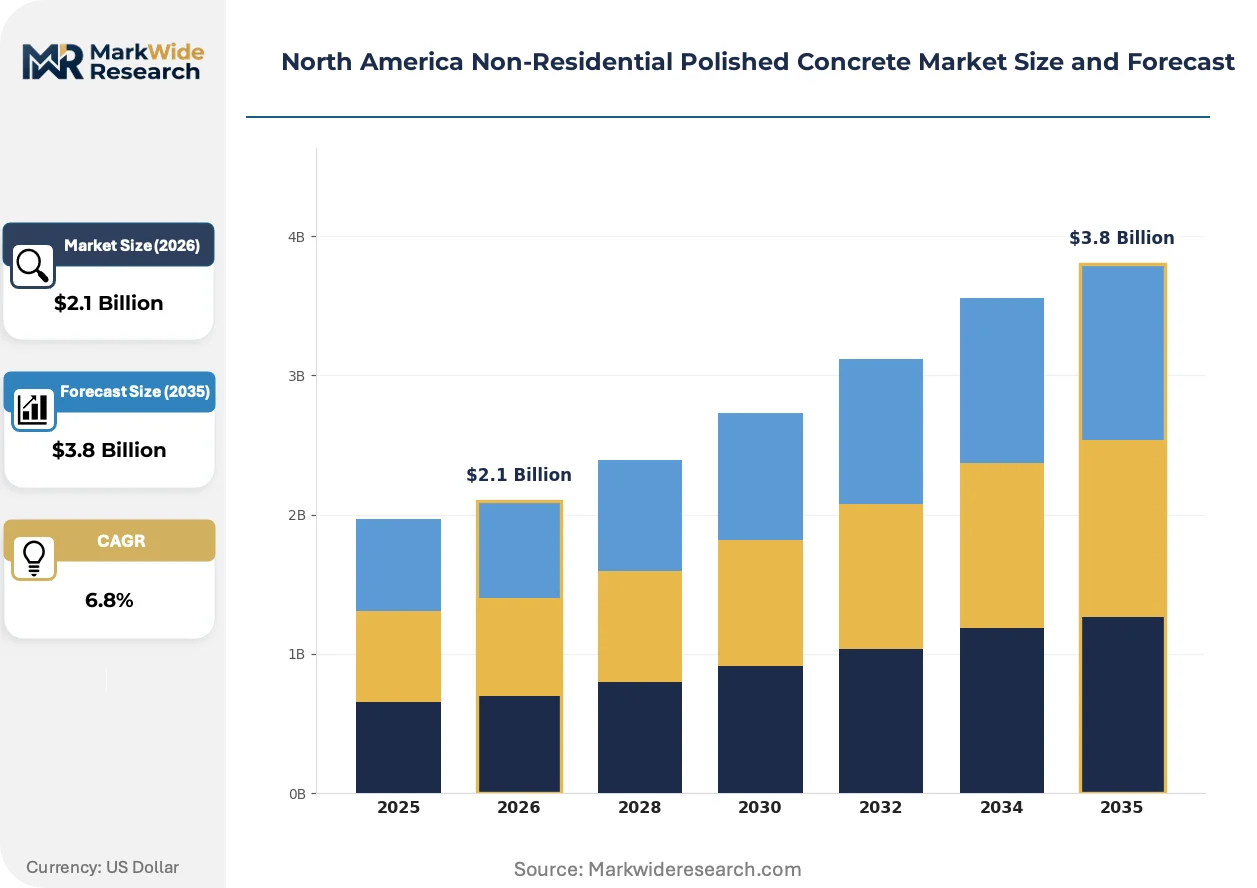
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail Spaces, Warehouses, Office Buildings, Showrooms Finish Type: High-Gloss, Matte, Satin, Textured Installation Method: Grinded, Polished, Burnished, Stained Market Segment: Commercial, Industrial, Institutional, Hospitality |
| Companies Covered | HTC Group, Husqvarna Group, Sika, Advanced Industrial Coatings, Carolina Concrete Floor Polishing, CG Flooring Systems, Concria, CPC Floor Coatings, Trucrete Surfacing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Residential Polished Concrete Market Emerging Trajectories
Specification behavior is pivoting toward lifecycle cost accounting while densifier chemistry and grinding automation compress installation timelines. Three forces are actively restructuring competitive positioning.
Hybrid lithium-silicate densifiers with nano-silica additives are overtaking conventional lithium-only formulations in high-wear industrial specifications. Warehouse operators in the Great Lakes corridor are specifying these chemistries for 3000-grit finishes that extend re-polishing intervals. The shift is compressing commodity densifier margins while rewarding formulation specialists with proprietary additive packages.
OSHA's crystalline silica rule for construction is tightening jobsite monitoring requirements across the United States. Contractors now deploy continuous air monitoring during planetary grinding operations, adding equipment capex and documentation labor. The burden falls heaviest on small independents bidding municipal and federal work where compliance documentation is mandatory.
Facility managers are consolidating flooring procurement under national account structures that bundle installation, maintenance, and re-polishing schedules. Third-party facility management firms are displacing direct contractor relationships in multi-site retail and logistics portfolios. The pattern is most visible in California and Texas where property management platforms manage Class A industrial footprints exceeding five million square feet.
North America Non-Residential Polished Concrete Market Segmentation
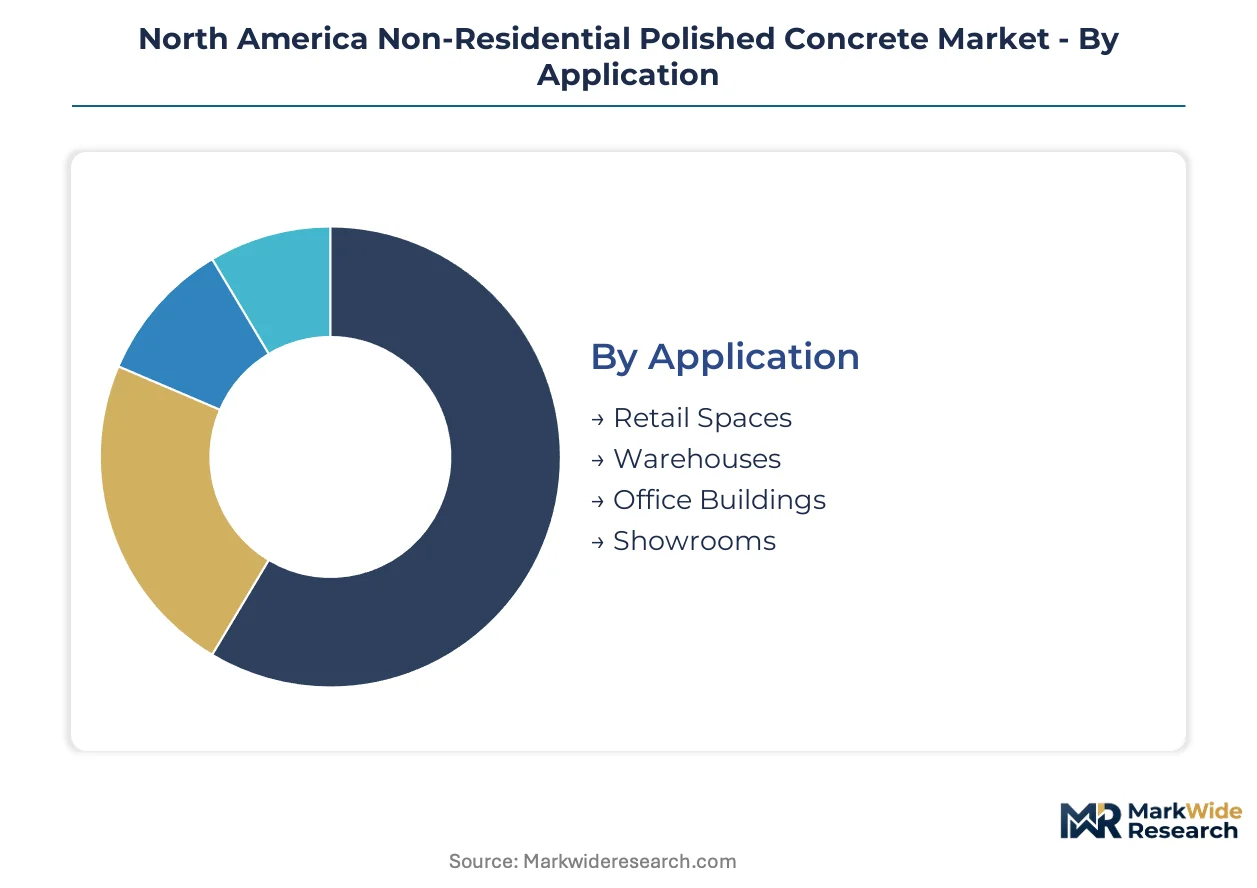
Polished concrete specification varies sharply by end-use durability requirements and aesthetic priorities. Contractors configure equipment, chemistry, and grit sequences differently across each segment, creating distinct margin profiles and competitive dynamics.
Application:
Standardization dominates warehouse flooring where specification templates repeat across distribution networks, while retail and showroom applications demand bespoke finish matching and color integration.
- Warehouses:High-traffic industrial slabs receive 800-1500 grit finishes with lithium-silicate densification for forklift abrasion resistance. Demand concentrates in Texas and California distribution corridors where e-commerce fulfillment construction drives specification volume. OSHA silica compliance adds documentation burden to every installation.
- Retail Spaces:Gloss-level consistency across multiple locations requires standardized crew deployment and densifier chemistry protocols. California and Ontario retail chains specify uniform reflectivity metrics to maintain brand presentation standards.
- Office Buildings:Matte and satin finishes balance maintenance simplicity with professional aesthetics. Installation speed rather than technical differentiation determines contractor selection in this maturing tier.
- Showrooms:Automotive and luxury goods displays demand 3000-grit mirror finishes with dye integration. Premium pricing reflects extended installation timelines and specialized polisher skill requirements.
Most installed capacity flows through Warehouses. Expansion is steepest in Showrooms.
Finish Type:
Cost tiers separate commodity industrial specifications from premium commercial applications, with gloss level directly correlating to labor intensity and densifier consumption.
- Matte:400-800 grit processing with minimal densifier penetration suits budget-constrained office retrofits. Texas and California institutional clients specify this tier for lifecycle cost control.
- Satin:Intermediate 1500 grit finishes balance light reflectivity with slip resistance. Hospitality operators in Ontario specify satin for dining and circulation areas.
- High-Gloss:3000 grit mirror finishes with extended polishing sequences command premium pricing. Automotive showrooms and luxury retail in California drive demand for maximum light reflectivity.
- Textured:Exposed aggregate or seeded finishes create slip-resistant surfaces for wet-process industrial environments. Food processing facilities in the Great Lakes corridor specify textured profiles for safety compliance.
Matte finishes dominate current volume. High-Gloss is gaining share fastest.
Installation Method:
Volume concentration favors mechanical refinement over chemical-only treatments, with method selection determining equipment capital requirements and skilled labor intensity.
- Grinded:Aggressive diamond cutting removes surface imperfections and opens concrete pores for densifier penetration. Warehouse specifications in Texas require grind-and-polish sequences for flatness tolerance compliance.
- Polished:Progressive grit refinement from 50 to 3000 produces specified gloss levels. California commercial contractors deploy planetary grinders with continuous silica monitoring for OSHA compliance.
- Burnished:High-speed propane or electric burnishers densify surface cream without deep grinding. Budget retrofits in Ontario office buildings use burnishing for rapid turnaround.
- Stained:Acid or water-based dyes integrate color before densification. Retail chains specify stained finishes for brand color matching across multiple locations.
Grinding capacity handles the majority of industrial square footage. Stained finishes are climbing the fastest.
Market Segment:
Customer type determines procurement structure, with national accounts consolidating industrial flooring and institutional buyers emphasizing compliance documentation.
- Industrial:Warehouse and logistics operators prioritize abrasion resistance and re-polishing interval extension. Texas and California Class A industrial construction drives specification volume through national account procurement.
- Commercial:Retail and office property managers balance upfront cost against maintenance burden. Third-party facility management firms are consolidating contractor relationships in multi-site portfolios.
- Institutional:Schools, hospitals, and government facilities require EPA low-VOC compliance and documented silica exposure controls. Federal procurement guidelines favor densified concrete over epoxy in renovation projects.
- Hospitality:Hotels and restaurants specify high-gloss finishes for lobby and dining aesthetics. Premium pricing reflects after-hours installation scheduling and finish consistency requirements.
Industrial absorbs the greatest installed square footage. Hospitality shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-California distribution corridor anchors North American polished concrete specification volume, with Ontario and British Columbia emerging as secondary demand clusters where provincial low-carbon procurement rules favor densified concrete over resinous alternatives.
United States
Texas and California industrial construction permits drive warehouse flooring demand across Dallas-Fort Worth, Houston, and the Inland Empire. OSHA silica exposure standards mandate continuous air monitoring during planetary grinding operations, adding compliance documentation burden to every installation. Federal procurement guidelines now favor EPA low-VOC densifiers over epoxy coatings in facility renovation contracts.
Canada
Ontario and British Columbia provincial mandates credit embodied-carbon reductions from polished concrete versus resinous systems in public procurement. The National Building Code imposes parallel compliance burdens on cross-border contractors bidding federal projects. Toronto and Vancouver construction clusters specify lithium-silicate densifiers for Class A industrial footprints exceeding five million square feet.
Mexico
Nuevo León and Mexico City industrial zones attract polished concrete specification from multinational logistics operators establishing regional distribution hubs. Mexican federal environmental standards lack equivalent VOC restrictions to EPA guidelines, creating specification divergence for cross-border facility portfolios. Monterrey manufacturing corridors increasingly specify 1500-grit satin finishes for automotive supplier facilities.
North America Non-Residential Polished Concrete Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue equipment rental and turnkey service bundling. The vendor base stratifies across chemical formulators, equipment manufacturers, and installation contractors with limited vertical overlap. Three archetypes dominate: multinational chemical conglomerates with densifier portfolios, specialized grinding equipment fabricators with distribution networks, and regional installation contractors with project execution capabilities. Competitive moves center on multi-vendor framework consolidation and national account procurement capture.
Among multinational chemical specialists, Sika leverages its admixtures portfolio to bundle densifiers with repair systems. Husqvarna Group anchors the equipment layer through planetary grinder distribution networks across the United States and Canada. HTC Group exemplifies tooling longevity positioning, extending replacement intervals for high-volume polishers in industrial specifications.
| Leading Market Players |
|---|
| HTC Group |
| Husqvarna Group |
| Sika |
| Advanced Industrial Coatings |
| Carolina Concrete Floor Polishing |
| CG Flooring Systems |
| Concria |
| CPC Floor Coatings |
| Trucrete Surfacing Systems |
| Others |
Supply Flow & Price Mechanics
Synthetic diamond abrasive costs flow from concentrated manufacturing nodes through three distinct pricing tiers, with lithium-silicate densifier chemistry commanding premium positioning against sodium-silicate alternatives in high-traffic industrial specifications. Contractors absorbing OSHA silica compliance burdens pass ventilation and PPE overhead into project bids, compressing margins on commodity matte finishes while preserving pricing power in 3000-grit showroom applications.
Pricing Analysis
Input-cost pass-through from synthetic diamond and lithium-silicate feedstocks anchors project-based transactional pricing, with densifier grade and grit-level specification serving as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels separates 3000-grit mirror finishes from 1500-grit satin and 400-grit matte tiers. Cost compression in economy-grade warehouse specifications is intensifying because epoxy coating alternatives retain bid competitiveness on upfront cost. Institutional buyers in federal procurement demonstrate lowest price sensitivity due to lifecycle cost accounting mandates, while budget-constrained commercial retrofits exhibit highest sensitivity to initial outlay.
Supply Chain Analysis
Dual-sourcing requirements from national account facility managers now mandate multi-vendor qualification for diamond abrasives and densifier chemicals, displacing single-source arrangements among large flooring contractors. Synthetic diamond production draws from China, Ireland, and South Africa manufacturing clusters, while lithium-silicate densifier formulation centers on United States and German chemical processing hubs. Single-source vulnerability in synthetic diamond sourcing exposes contractors to input cost volatility when geopolitical friction disrupts trade flows. Distribution runs through equipment rental channels bundling planetary grinders, tooling, and training for mid-tier contractors lacking capital for fleet ownership.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America non-residential polished concrete market functions as a stable compounder, with warehouse construction permits in Texas and California distribution corridors delivering predictable specification volume through national account procurement structures.
For Market Incumbents: Extend densifier chemistry portfolios into hybrid lithium-silicate formulations with nano-silica additives, capturing premium positioning as warehouse operators in the Great Lakes corridor specify extended re-polishing intervals. Deepen backward integration into synthetic diamond tooling production to defend margin structures against input cost volatility from concentrated overseas suppliers. National account procurement consolidation by third-party facility management firms threatens direct contractor relationships; anchor client retention through bundled maintenance and re-polishing service contracts. For New Entrants and Emerging Players: Enter via equipment rental fleet operations targeting mid-tier contractors in Ontario and British Columbia, where provincial low-carbon procurement mandates favor densified concrete over resinous alternatives and rental penetration remains below United States levels. The hospitality high-gloss segment offers the most penetrable white-space target, with automotive showrooms and luxury retail in California commanding premium pricing through specialized polisher skill requirements that deter commoditization. Position through turnkey service bundling that packages planetary grinder access, densifier chemistry, and OSHA-compliant silica monitoring training. For Investors and Strategic Acquirers: Roll-up economics work for regional installation contractors with established national account relationships because facility management platform consolidation is displacing fragmented direct bidding structures across multi-site retail and logistics portfolios. The acquisition target archetype combines project execution capabilities with documented silica compliance protocols qualifying for federal procurement. Long-term viability rests on densifier chemistry formulation expertise rather than equipment ownership. Watch lithium-silicate penetration rates in 3000-grit specifications as the inflection indicator for premium tier pricing power sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diamond Tooling | Captive supply of synthetic abrasives insulates margin structures from geopolitical supply shocks. |
| Hybrid Densifier Formulation Development | Nano-silica additive packages command premium positioning in Great Lakes warehouse specifications. |
| Equipment Rental Channel Expansion | Turnkey grinder-chemistry-training bundles penetrate mid-tier contractor segments lacking capital. |
| National Account Service Contracting | Multi-site maintenance and re-polishing schedules lock out competitors from facility management platforms. |
| Cross-Border Certification Investment | OSHA-provincial safety training reciprocity enables bidding on federal projects in both United States and Canada. |
Methodological Framework
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining structured interviews with flooring contractors, facility management procurement leads, densifier chemical formulators, and planetary grinder equipment distributors alongside secondary validation. Secondary sources included EPA enforcement guidance documents, OSHA silica exposure standard implementation records, provincial environmental statutes from Ontario and British Columbia, and industrial construction permit databases from Texas and California. Bottom-up project pipeline analysis triangulated against top-down national account spending estimates.
Granularity-level modeling operated at the intersection of finish type, application segment, and installation method dimensions, with densifier chemistry tier and grit specification providing additional industry-specific stratification. CAGRs were derived from polynomial trend fitting across permit-issuance trajectories and national account procurement disclosure patterns, with lithium-silicate penetration curves and silica compliance cost absorption rates serving as key forecast inputs across the projection horizon.
Inputs from contractor bidding databases and facility management procurement platforms were available through the study window; gaps in real-time densifier pricing transparency introduce uncertainty bands around margin structure projections. Forecasts reflect documented assumptions regarding OSHA enforcement intensity and provincial low-carbon mandate adoption timelines. Deviation in lithium-silicate formulation patent expirations or synthetic diamond trade policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Global Steel Pipe Piles Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Railing Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Building Insulation Market