
 Masonry Sealers Market | 2026-2036
Masonry Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Masonry Sealers Market Analytics
EPA VOC regulations is consolidating the competitive landscape for solvent-based masonry sealers in North America. Sika AG leverages its integrated silane manufacturing to sustain pricing power across specification-grade infrastructure projects. BASF SE anchors its position through R&D intensity in hybrid polymer chemistry for breathable waterborne systems. RPM International Inc. competes via geographic dominance in North American retail channels for contractor-grade applications.
Masonry sealers are liquid-applied protective coatings, typically formulated from acrylic resins, silane-siloxane oligomers, or polyurethane prepolymers, that penetrate or film-form on porous mineral substrates to repel water, resist chloride ingress, and mitigate freeze-thaw damage while preserving vapor permeability. Their primary industrial purpose is extending service life of concrete, brick, stone, and stucco envelopes in buildings, bridges, and marine structures. Silane-siloxane formulations command premium specification positions due to deep substrate penetration and long hydrophobic performance windows, while acrylic systems dominate volume in residential and light commercial maintenance cycles. The contractor end-user segment concentrates margin pools through specification influence and recurring maintenance contracts, whereas DIY consumers drive episodic retail volumes with higher price sensitivity.
EPA VOC rules, REACH registration requirements, and state-level California Air Resources Board protocols collectively restrict solvent content and mandate product re-registration, forcing reformulation investments that favor scaled chemical producers. OSHA exposure limits for isocyanates in polyurethane systems further shape workplace handling standards and personal protective equipment requirements across industrial application settings. Stakeholders must monitor evolving low-carbon building codes and embodied carbon disclosure mandates, as these frameworks will increasingly weight sealer selection criteria alongside traditional performance metrics.
Market Dynamics
Waterborne silane-siloxane chemistry is displacing solvent-based acrylics as the dominant platform specification, compressing reformulation timelines and forcing raw material backward integration decisions across specialty chemical portfolios.
Growth Catalysts
- Federal building energy retrofit mandates:Germany's EnEG amendments require breathable envelope treatments for historic masonry, pulling specification-grade silane volumes into renovation tenders.
- REACH Article 57 SVHC restrictions:ECHA's evolving candidate list is accelerating waterborne transitions among European formulators seeking continued market access.
- Marine infrastructure rehabilitation:Chloride-induced corrosion in coastal concrete is expanding specification of deep-penetrating siloxane systems for bridge substructures.
Market Restraints
- Petrochemical feedstock volatility:Acrylic resin precursors track propylene oxide and MMA monomer spreads, compressing margin stability for waterborne producers.
- Silane manufacturing concentration:Merchant supply of specialty alkoxysilanes clusters in German and Chinese chemical parks, creating single-source vulnerability.
- Application temperature sensitivity:Waterborne systems require substrate conditions above dew point thresholds, limiting seasonal contractor productivity in temperate climates.
Strategic Opportunities
- Indian commercial construction codes:BIS adoption of EN 1504 concrete repair standards is opening specification-grade sealer demand in Mumbai and Bangalore high-rise markets.
- Photocatalytic hybrid chemistries:Titanium dioxide integration with silane carriers offers self-cleaning facade performance for premium architectural envelopes.
- Direct-to-contractor digital platforms:Bypassing traditional distribution, manufacturers are capturing specification influence through BIM-integrated product selection tools.
Industry Challenges
- Applicator certification bottlenecks:Manufacturer-specific training programs for high-performance systems create workforce throughput constraints during peak construction seasons.
- Performance validation timelines:Accelerated weathering protocols for 20-year hydrophobicity claims require 12-18 month third-party testing cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Masonry Sealers Market |
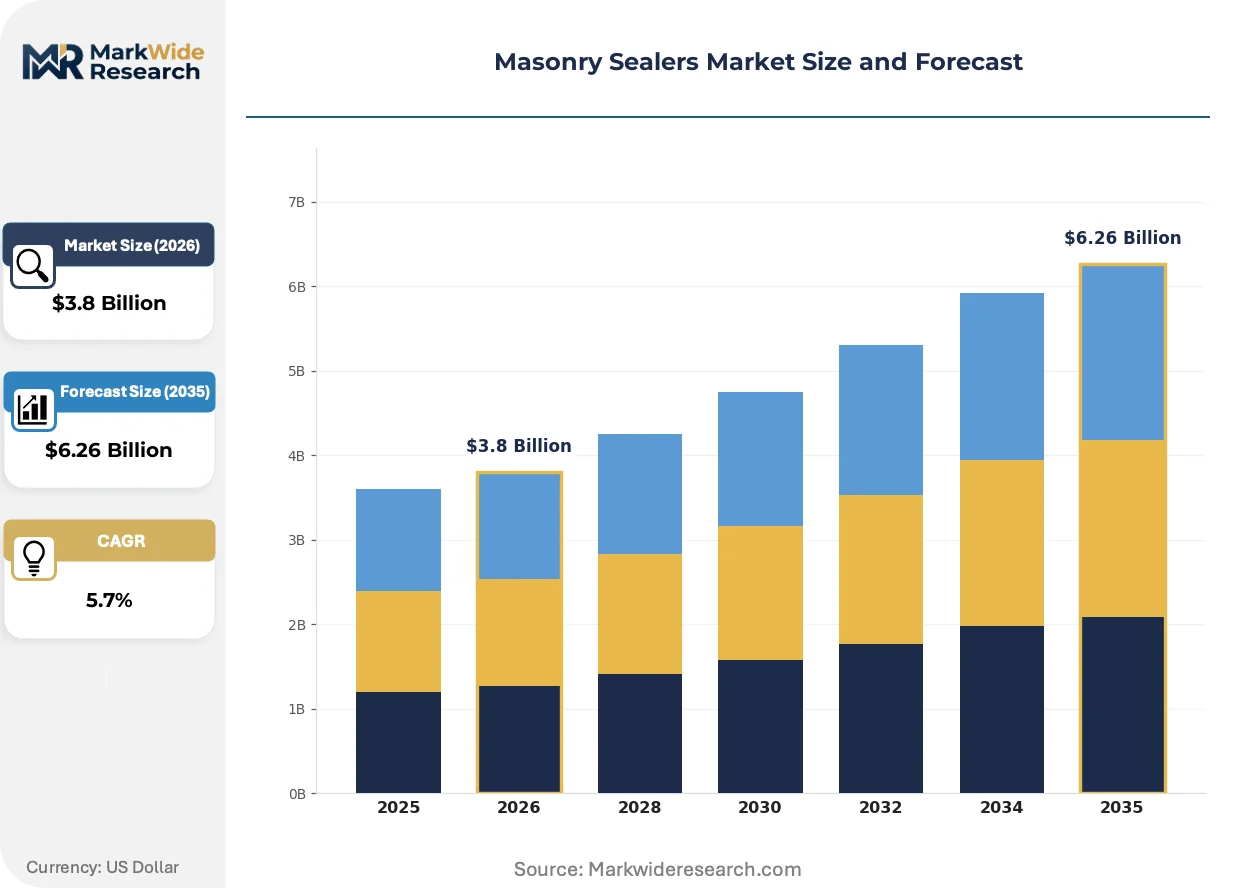
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Silane-Siloxane Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, DIY Consumers, Property Managers, Architects Distribution Channel: Online Retail, Distributors, Home Improvement Stores, Specialty Stores |
| Companies Covered | Sika AG, BASF SE, RPM International Inc., Mapei S.P.A., PPG Industries Inc., Arkema, Sherwin-Williams Company, Prosoco, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Masonry Sealers Market Evolving Landscape
Reformulation investments are concentrating around breathable, low-VOC platforms that satisfy tightening envelope energy codes while preserving substrate moisture management. The competitive frontier has shifted from raw performance metrics to regulatory pre-certification and digital specification integration.
Hybrid silane-siloxane oligomers with tuned molecular weight distributions are expanding into infrastructure rehabilitation specifications, penetrating deeper into carbonated concrete than conventional silanes. State transportation departments in the US are adopting these systems for bridge deck applications, compressing the performance gap between premium and standard-grade formulations. The technology is expanding into specification positions previously held by solvent-based penetrating sealers.
EPA VOC thresholds under 40 CFR 59 are tightening permissible solvent content in architectural coatings, forcing acrylic producers toward waterborne emulsion technologies. The industrial consequence is elevated capital intensity for dispersion equipment and film-forming aid substitution. Western US contractors face the most acute compliance pressure, with CARB SCM 2007 standards already below federal minimums.
Building envelope commissioning is compressing sealer selection cycles, with owners demanding WUFI hygrothermal modeling validation before product specification. Engineering firms are displacing traditional distributor influence through performance-guaranteed envelope packages. This pattern is most visible in German Passivhaus and US PHIUS-certified multifamily construction, where vapor permeability metrics override first-cost considerations.
Masonry Sealers Market Segmentation
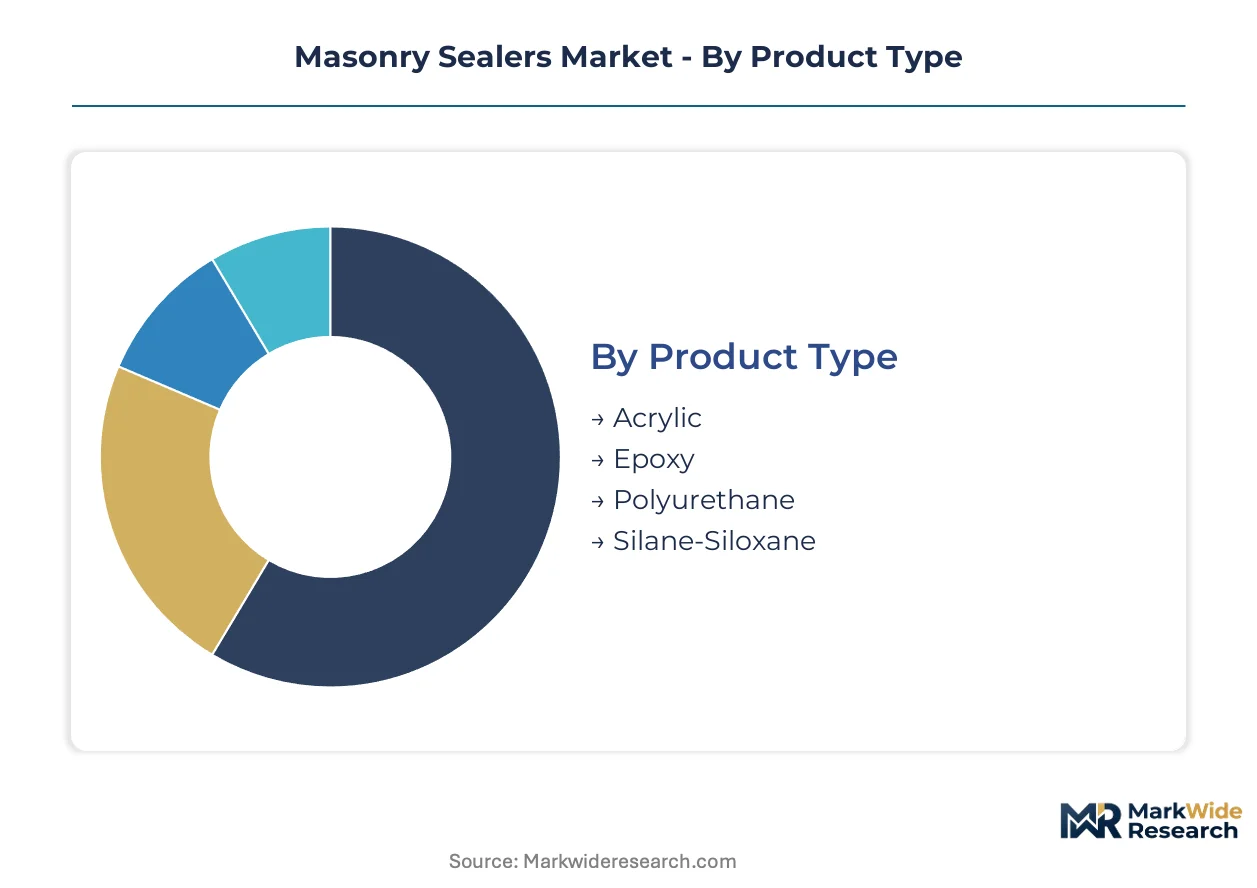
Masonry sealer purchasing decisions split across technical performance requirements, regulatory compliance burdens, and application scale economics. Specification-grade infrastructure projects demand silane-siloxane penetration depths and vapor permeability validation, while residential maintenance cycles prioritize cost-per-square-foot and seasonal availability.
Product Type:
Formulation chemistry dictates project specification tiers, with hydrophobic longevity and substrate breathability separating premium positioning from commodity alternatives.
- Silane-Siloxane:Oligomeric formulations penetrate carbonated concrete to 3-5mm depths, establishing long-duration hydrophobic barriers without surface film formation. German federal building energy retrofit mandates specify these systems for historic masonry envelopes, pulling volumes into renovation tenders with 20-year performance guarantees.
- Acrylic:Film-forming emulsions and solvent-borne solutions dominate residential and light commercial maintenance cycles through lower material costs and broader temperature application windows. EPA VOC thresholds under 40 CFR 59 are forcing waterborne transitions, elevating capital intensity for dispersion equipment.
- Polyurethane:Prepolymer systems deliver abrasion-resistant surface films for industrial flooring and marine deck applications. OSHA exposure limits for isocyanates shape workplace handling standards and PPE requirements across industrial settings.
- Epoxy:Two-component thermosetting resins provide chemical-resistant barriers for industrial containment structures and wastewater treatment facilities.
Volume sits with acrylic systems; growth tilts toward silane-siloxane as infrastructure rehabilitation budgets expand and energy codes tighten envelope breathability requirements.
Application:
Asset class durability standards and maintenance liability exposure determine formulation specification intensity and procurement channel selection.
- Infrastructure:Bridge decks, marine substructures, and transportation tunnels require deep-penetrating chloride barriers with accelerated weathering validation. State transportation departments in the US are adopting hybrid silane-siloxane oligomers for carbonated concrete rehabilitation, compressing the performance gap between premium and standard-grade systems.
- Commercial:High-rise facades and retail envelopes demand WUFI hygrothermal modeling validation before specification, with engineering firms displacing distributor influence through performance-guaranteed packages. Building envelope commissioning cycles are compressing sealer selection timelines.
- Industrial:Manufacturing floors and chemical processing facilities prioritize abrasion resistance and spill containment over vapor permeability metrics.
- Residential:Single-family maintenance and DIY renovation drives episodic retail volumes with acute price sensitivity and seasonal application constraints.
Revenue concentrates in infrastructure; specification-grade commercial applications are climbing the fastest as envelope commissioning standards proliferate.
End User:
Technical authority over material selection and recurring maintenance contract access determine margin capture and brand loyalty dynamics.
- Contractors:Specialty applicators with manufacturer certification control specification-grade infrastructure and commercial projects. Training program bottlenecks create workforce throughput constraints during peak construction seasons, limiting market expansion velocity.
- Architects:Design professionals increasingly specify through BIM-integrated product selection tools, bypassing traditional distribution to capture influence over envelope performance packages.
- Property Managers:Portfolio-scale maintenance operations negotiate volume pricing for recurring facade and parking structure treatments.
- DIY Consumers:Home improvement retail channels serve episodic demand with limited technical support requirements and high price elasticity.
Margin pools concentrate with contractors; architect-directed specification is expanding most quickly as digital platforms reshape material selection workflows.
Distribution Channel:
Channel selection balances specification influence, inventory carrying costs, and technical service intensity requirements.
- Distributors:Regional specialty chemical distributors maintain specification relationships with contractor applicators and provide just-in-time delivery for large-scale infrastructure projects. Geographic coverage and technical field support separate tier-one distributors from commodity handlers.
- Online Retail:Direct-to-contractor digital platforms are capturing specification influence through BIM-integrated tools and performance data repositories, compressing traditional distributor margins.
- Home Improvement Stores:Mass retail chains serve DIY residential demand with limited SKU breadth and minimal technical consultation.
- Specialty Stores:Independent coating retailers cater to professional applicators with localized inventory and manufacturer co-branded merchandising.
Transaction volume flows through distributors; digital platform penetration is gaining share fastest as procurement patterns shift toward specification-integrated purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for chemical manufacturing in China's coastal provinces concentrate silane precursor production, while Germany's Ruhr industrial corridor anchors European formulation capacity. Infrastructure rehabilitation tenders in OECD economies pull specification-grade volumes into concentrated urban markets.
United States
Federal bridge rehabilitation programs and coastal marine infrastructure renewal drive silane-siloxane specification volumes. EPA 40 CFR 59 VOC thresholds tighten solvent content limits, accelerating waterborne transitions among domestic formulators. California's CARB SCM 2007 standards already sit below federal minimums, pressuring Western US contractors toward compliant low-VOC platforms.
Germany
EnEG building energy retrofit mandates specify breathable envelope treatments for historic masonry structures. REACH Article 57 SVHC restrictions force continuous reformulation among European chemical producers. The Ruhr industrial corridor hosts concentrated silane manufacturing capacity serving specification-grade infrastructure tenders across Central Europe.
China
Municipal infrastructure investment in coastal provinces expands concrete protection specifications for bridge and tunnel assets. GB standards for construction chemicals evolve toward breathability metrics aligned with European norms. Yangtze River Delta chemical parks concentrate merchant alkoxysilane supply serving domestic formulators and export markets.
India
BIS adoption of EN 1504 concrete repair standards opens specification-grade sealer demand in high-rise commercial construction. Central government smart city mission funding channels into facade rehabilitation and parking structure protection. Mumbai and Bangalore metropolitan markets concentrate early specification adoption among engineering consultancies.
United Arab Emirates
Coastal marine infrastructure and high-rise facade specifications expand with Dubai Expo legacy development and Abu Dhabi cultural district construction. Local building codes incorporate vapor permeability requirements for envelope commissioning. Jebel Ali industrial zone hosts formulation facilities serving Gulf Cooperation Council infrastructure tenders.
Masonry Sealers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven chemical producers anchor premium specification positions while regional applicators capture maintenance-cycle volumes. The vendor base stratifies across three archetypes: integrated silane manufacturers with backward control over precursor supply, specialty coating formulators with specification-grade certification depth, and distribution-heavy operators with contractor channel dominance. M&A activity concentrates around waterborne technology acquisitions and regional applicator roll-ups, while capacity expansion focuses on low-VOC platform scale-up in regulated jurisdictions.
Among integrated chemical producers, Sika AG and BASF SE exemplify the precursor-integrated archetype with captive silane manufacturing positions, while RPM International Inc. occupies the distribution-consolidated tier with North American contractor channel density. These three anchors represent distinct competitive vectors: upstream chemical integration, hybrid polymer R&D intensity, and geographic retail dominance respectively.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| RPM International Inc. |
| Mapei S.P.A. |
| PPG Industries Inc. |
| Arkema |
| Sherwin-Williams Company |
| Prosoco |
| Wacker Chemie AG |
| Others |
Value Network & Pricing Analysis
Backward integration into silane precursor manufacturing anchors pricing power for specification-grade formulators, while merchant-dependent competitors absorb volatile alkoxysilane spreads. This upstream control separates premium infrastructure suppliers from acrylic commodity producers facing compressed margins under EPA VOC compliance costs.
Pricing Analysis
Short lead-time premiums distinguish specification-grade projects from spot acrylic purchases in residential channels. Three-tier pricing structure across premium silane-siloxane, standard waterborne acrylic, and economy solvent-based systems reflects certification depth and performance guarantee duration. Pricing pressure stems from petrochemical feedstock volatility in acrylic resin precursors. DIY consumers exhibit acute price sensitivity, whereas infrastructure contractors prioritize hydrophobic longevity over material cost per square foot.
Supply Chain Analysis
Dual-sourcing requirements for alkoxysilane precursors are emerging among state transportation departments seeking supply security for bridge rehabilitation programs. Merchant supply clusters in Germany's Ruhr corridor and China's Yangtze River Delta chemical parks, drawing from propylene oxide and methyl methacrylate feedstocks. Single-source vulnerability concentrates around specialty oligomer production. Distribution runs through regional specialty chemical distributors with contractor certification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as formulators pursue captive silane manufacturing to escape merchant precursor volatility. This upstream lever determines margin stability across specification-grade infrastructure tenders.
For Market Incumbents: Lock in specification influence through BIM-integrated product selection tools that bypass traditional distributor channels. Deepen certification depth with state transportation departments to defend against hybrid oligomer entrants. Capacity expansion in low-VOC platforms addresses EPA 40 CFR 59 compliance pressure.
For New Entrants and Emerging Players: Enter via digital direct-to-contractor platforms serving mid-tier commercial envelope commissioning markets. Target Indian high-rise construction in Mumbai and Bangalore where BIS EN 1504 adoption creates specification-grade demand without entrenched incumbent relationships. Photocatalytic hybrid chemistries offer differentiation for premium architectural facades.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified chemical conglomerates seeking waterborne technology capabilities. Five-to-ten year viability hinges on regulatory pre-certification assets rather than raw formulation expertise. Watch for REACH Article 57 SVHC list expansions as inflection indicators accelerating acquisition premiums for compliant portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Captive alkoxysilane supply insulates margins from German and Chinese merchant concentration. |
| Waterborne Platform Scale-Up | EPA VOC thresholds under 40 CFR 59 compel capital investment in low-emission formulation capacity. |
| BIM-Integrated Specification Tools | Digital product selection displaces distributor influence in commercial envelope commissioning. |
| Applicator Certification Program Expansion | Manufacturer-trained workforce throughput constraints limit peak-season market capture velocity. |
| Photocatalytic Hybrid Chemistry Development | Titanium dioxide integration with silane carriers targets self-cleaning premium facade specifications. |
Research Methodology
Independent corroboration across plant managers at alkoxysilane production facilities, procurement leads at downstream coating formulators, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Primary interviews with specialty applicators and envelope commissioning engineers combined with secondary validation from customs trade data, ACC and Cefic chemical industry reports, and SEC 10-K filings. Bottom-up volume triangulation against top-down expenditure flows tested segment-level assumptions.
Rate-of-change decomposition across the projection horizon separates volume growth from price mix effects. Segmentation dimensions modeled include formulation chemistry tier, end-use asset class, procurement channel, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy inflection points. Industry-specific forecast inputs encompass infrastructure rehabilitation budget flows and building energy code adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock disruption scenarios. Deviation in REACH SVHC restriction timing or EPA VOC threshold enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Global Steel Pipe Piles Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Israel Ceramic Tiles Market