
 Global Panelized and Modular Building System Market | 2026-2036
Global Panelized and Modular Building System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Panelized and Modular Building System Market Outlook
Net-zero-ready specification tiers is reorganizing competitive dynamics across the Global Panelized and Modular Building System Market. Kingspan Timber Solutions leverages proprietary insulated panel cores to dominate thermal performance benchmarks in Northern European projects. SAINT-GOBAIN Brüggemann Holzbau GmbH anchors its position through backward integration into engineered timber supply chains. Modulaire Group competes on fast-track deployment timelines for workforce accommodation contracts across resource extraction sites.
Panelized and modular building systems comprise prefabricated structural assemblies—typically dimensioned to ISO shipping module widths of 2.4–4.2 meters—manufactured under factory-controlled conditions for on-site crane placement and interconnection. These systems deliver compressed construction schedules, waste reduction, and repeatable quality assurance for commercial, institutional, and residential applications. Modular Units command the largest revenue share due to turnkey completeness and reduced site labor dependency, while Hybrid Solutions represent the fastest-expanding segment as developers blend permanent modular cores with conventional structural envelopes for design flexibility. Sustainable Building methods within the Construction Method dimension concentrate margin pools where suppliers certify whole-life carbon credentials through EPDs and cradle-to-grave LCA documentation.
The EU Green Deal's embodied carbon benchmarks and the F-Gas Regulation's thermal insulation requirements are reshaping material selection protocols across member states, compelling panel manufacturers to substitute low-GWP blowing agents and disclose product-level environmental footprints. The EPA's ENERGY STAR certification and IRA efficiency incentives in the United States are similarly redirecting procurement specifications toward high-performance envelope assemblies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance fragmentation in cross-border project portfolios.
Market Dynamics
Factory-controlled manufacturing is compressing construction timelines while regulatory carbon accounting forces material disclosure across supply chains. Developers now specify panelized systems based on verified embodied carbon data rather than first-cost alone.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Member states mandate whole-life carbon disclosure for public procurement, redirecting specification toward low-carbon panel assemblies.
- Healthcare facility expansion:Hospital developers procure modular clinical wings to minimize disruption to active medical campuses.
- Timber-frame engineering advances:Cross-laminated timber and mass timber connectors enable multi-story factory-built housing at density levels previously requiring steel or concrete.
Market Restraints
- Transportation cost volatility:Diesel fuel and specialized flatbed capacity fluctuations compress margins on oversized module deliveries to remote sites.
- Skilled factory labor concentration:Certified panel assembly technicians cluster in Central European manufacturing corridors, constraining capacity scaling elsewhere.
- F-Gas Regulation compliance friction:EU thermal insulation mandates force reformulation of polyurethane blowing agents, disrupting established supply relationships.
Strategic Opportunities
- India affordable housing shortfall:National urban housing targets exceed conventional construction capacity, creating entry points for prefabricated volumetric suppliers.
- IRA efficiency incentives:US tax credits for high-performance building envelopes accelerate specification of insulated panel systems in commercial retrofits.
- Digital twin integration:Convergence of BIM workflows with factory automation enables design-to-fabrication data continuity, reducing field rework.
Industry Challenges
- Installation crew certification gaps:Crane operators and module connection specialists require jurisdiction-specific credentials that training pipelines have not matched.
- Legacy utility integration:Grid connection protocols for modular multifamily units vary by municipality, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Panelized and Modular Building System Market |
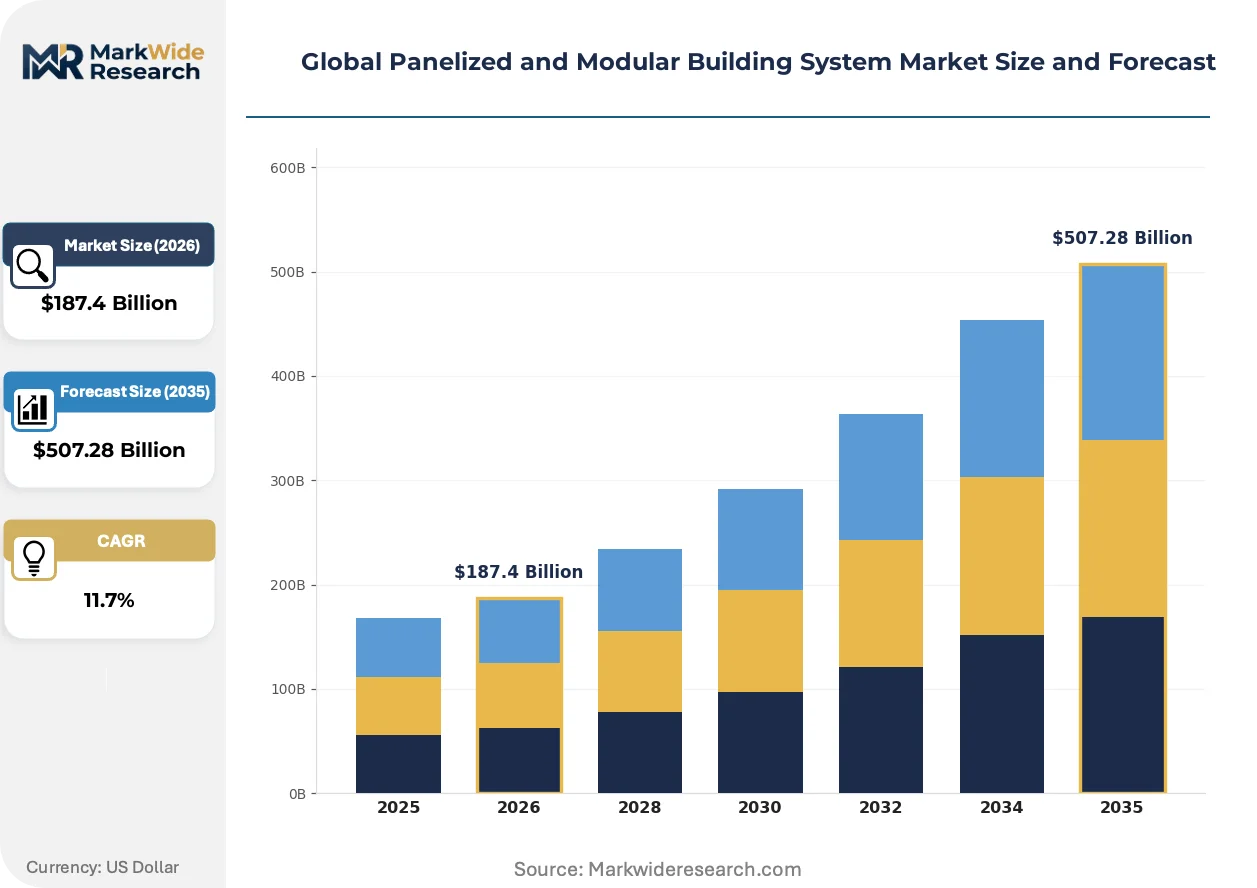
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panelized Systems, Modular Units, Hybrid Solutions, Pre-fabricated Components Construction Method: On-site Assembly, Off-site Fabrication, Fast-track Construction, Sustainable Building End User: Residential Sector, Commercial Sector, Hospitality Sector, Institutional Facilities Application: Temporary Structures, Permanent Buildings, Extension Projects, Disaster Relief Housing |
| Companies Covered | Algeco, Kingspan Timber Solutions, Etex Building Performance, Robertson Group Ltd, Metek Plc, SAINT-GOBAIN Brüggemann Holzbau GmbH, Hunter Douglas Group, ATCO Ltd, Modulaire Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Panelized and Modular Building System Market Strategic Shifts
Manufacturing automation and environmental certification protocols are restructuring how building components move from factory floor to final assembly. These shifts compress traditional construction timelines while elevating performance verification requirements.
Cross-laminated timber panel technology is bifurcating the mid-rise structural market. German and Austrian housing associations specify engineered timber cores for six-to-twelve-story residential blocks. Factory prefabrication of CLT floor cassettes and wall panels compresses weather-dependent site work from months to weeks.
REACH substance restrictions and the EU F-Gas Regulation are forcing insulation material transitions. Panel manufacturers reformulate polyurethane cores with hydrofluoroolefin blowing agents to meet thermal performance targets without high-GWP components. Nordic markets lead adoption, with building code updates in Sweden and Finland mandating disclosed GWP thresholds for envelope assemblies.
Developer procurement patterns are fragmenting across project delivery models. Design-build contractors increasingly source directly from panel fabricators, bypassing traditional general contractor markups. This disintermediation concentrates in UK and Irish residential markets, where housing associations negotiate multi-project framework agreements with modular suppliers.
Global Panelized and Modular Building System Market Segmentation
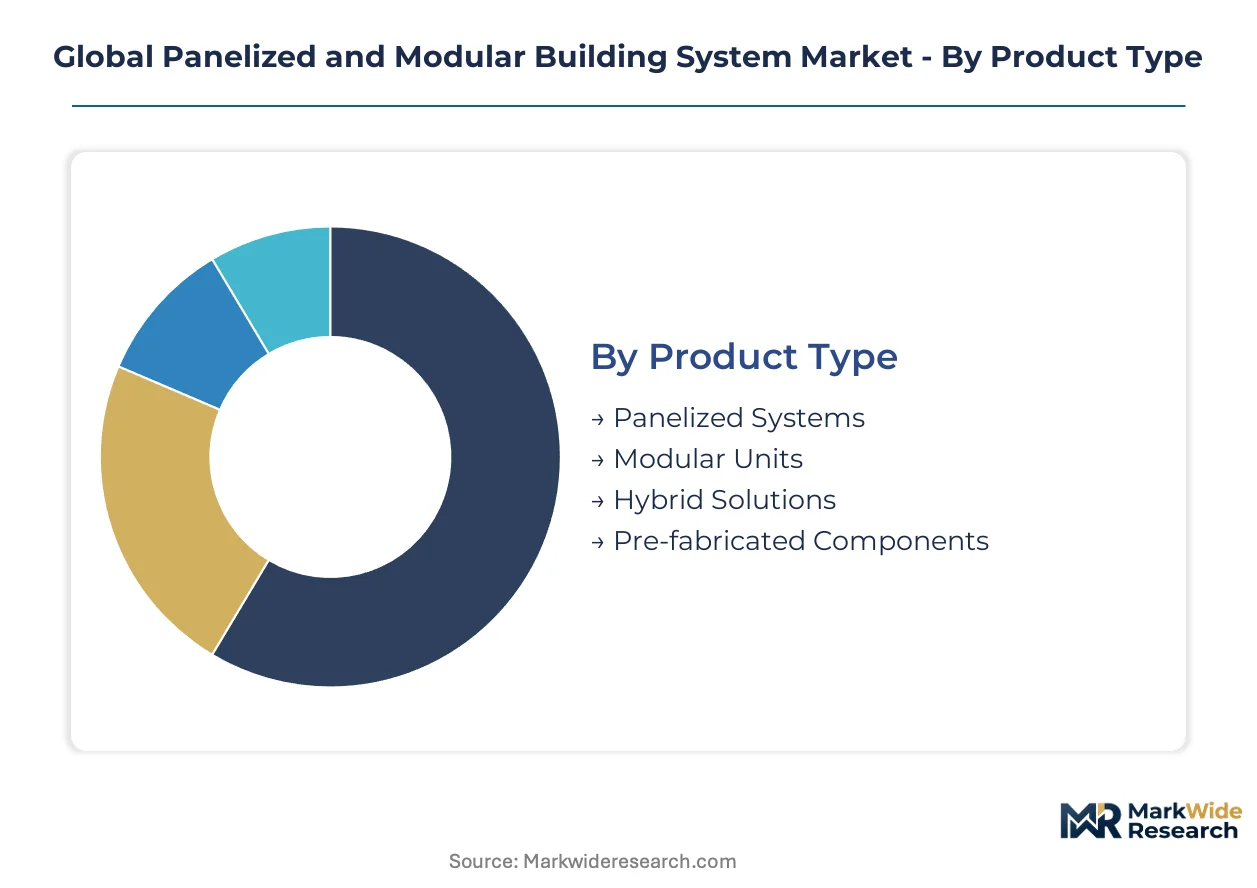
Product architecture and delivery methodology determine cost structures, regulatory compliance pathways, and supply chain configuration across the Global Panelized and Modular Building System Market. Segment boundaries increasingly blur as manufacturers bundle panelized envelopes with volumetric cores to meet carbon disclosure mandates.
Product Type:
REACH substance restrictions and the EU F-Gas Regulation differentiate thermal performance tiers through blowing agent chemistry and embodied carbon disclosure requirements.
- Modular Units:Complete volumetric assemblies factory-finished with MEP systems and interior fit-out. Hospital developers in Germany specify these for clinical wings to compress commissioning schedules while satisfying the EU Green Deal's whole-life carbon thresholds for public procurement.
- Hybrid Solutions:Permanent modular structural cores paired with conventional envelope systems. Swedish housing associations deploy this architecture for six-to-twelve-story timber-frame blocks, blending factory precision with design flexibility for complex urban infill sites.
- Panelized Systems:Precut wall, floor, and roof assemblies requiring on-site connection. German factory-built housing cooperatives scale multi-story developments using cross-laminated timber cassettes certified through Nordic EPD protocols.
- Pre-fabricated Components:Discrete structural or envelope elements. Indian affordable housing contractors source these to bridge conventional construction capacity shortfalls against national urban housing targets.
Established volume favors Modular Units; emerging adoption favors Hybrid Solutions.
Construction Method:
Margin concentration aligns with certification intensity—Sustainable Building commands premium pricing where EPD documentation and cradle-to-grave LCA verification are specified.
- Sustainable Building:Whole-life carbon methodologies with disclosed GWP thresholds and renewable material sourcing. Finnish building codes mandate this tier for public sector envelope procurement, redirecting specification toward hydrofluoroolefin-blown polyurethane panels.
- Off-site Fabrication:Factory-controlled production of structural assemblies under ISO-quality management. Austrian mass timber suppliers dominate this segment through backward integration into engineered timber supply chains.
- Fast-track Construction:Compressed delivery timelines for workforce accommodation and emergency response. Australian resource extraction contractors procure these systems for remote site deployment.
- On-site Assembly:Traditional construction integration of prefabricated elements. UK design-build contractors increasingly bypass general contractor markups by sourcing directly from panel fabricators under multi-project framework agreements.
Certification premiums concentrate in Sustainable Building; speed premiums concentrate in Fast-track Construction.
End User:
Procurement scale and repeatability determine supplier relationship structures—housing associations negotiate multi-project frameworks while institutional buyers demand turnkey accountability.
- Residential Sector:Single-family and multifamily housing developers. German factory-built housing associations scale procurement through timber-frame engineering advances enabling mid-rise density without steel or concrete.
- Institutional Facilities:Healthcare, education, and government buildings. US hospital developers utilize modular clinical wings to minimize disruption to active medical campuses while capturing IRA efficiency incentives for high-performance envelopes.
- Commercial Sector:Office, retail, and industrial applications. Irish commercial retrofits specify insulated panel systems to meet ENERGY STAR certification thresholds.
- Hospitality Sector:Hotels, resorts, and temporary accommodation. Modular suppliers compete on deployment timelines for workforce housing contracts across Middle Eastern resource extraction sites.
Repeat procurement volume concentrates in Residential Sector; project complexity premiums concentrate in Institutional Facilities.
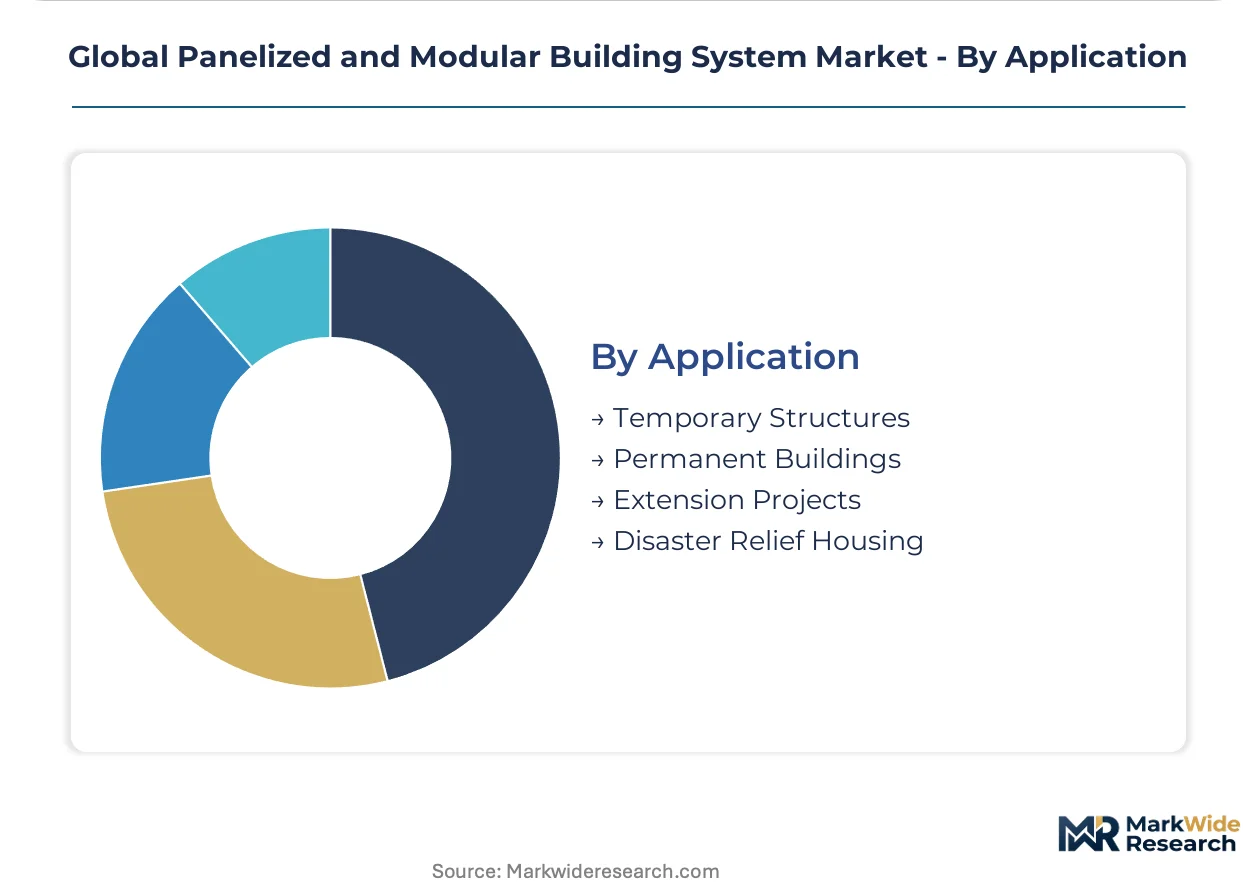
Application:
Duration of use dictates structural specification and regulatory pathway—permanent buildings face full building code compliance while temporary structures operate under expedited approval frameworks.
- Permanent Buildings:Code-compliant structures designed for multi-decade service life. Cross-laminated timber panel technology enables six-to-twelve-story residential blocks in Austria and Germany with factory-prefabricated floor cassettes.
- Disaster Relief Housing:Rapid-deployment shelter for emergency response. Indian urban housing targets exceed conventional construction capacity, creating entry points for volumetric suppliers in this application.
- Extension Projects:Additions to existing structures requiring utility integration and aesthetic matching. Grid connection protocol variation by municipality extends commissioning timelines for modular multifamily extensions.
- Temporary Structures:Short-term installations with expedited approval. UK festival and event contractors source these for seasonal deployment with minimal foundation requirements.
Regulatory stringency peaks in Permanent Buildings; deployment velocity peaks in Disaster Relief Housing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory-built housing associations in Germany and timber-frame engineering clusters in Austria concentrate supply-side capacity for cross-laminated timber systems. Regulatory carbon accounting in the EU and efficiency incentives in the US are redirecting procurement specifications across distinct national frameworks.
Germany
Factory-built housing cooperatives scale multi-story timber-frame developments using engineered timber cores for six-to-twelve-story residential blocks. The EU Green Deal's embodied carbon thresholds mandate whole-life carbon disclosure for public procurement, redirecting specification toward low-carbon panel assemblies. Manufacturing corridors in Bavaria and Baden-Württemberg host certified panel assembly technicians concentrated in Central European production clusters.
United States
Hospital developers procure modular clinical wings to minimize disruption to active medical campuses while capturing IRA efficiency incentives for high-performance envelopes. The EPA's ENERGY STAR certification redirects procurement specifications toward high-performance envelope assemblies in commercial retrofits. Industrial capacity concentrates in the Southeast and Pacific Northwest where design-build contractors negotiate multi-project framework agreements with modular suppliers.
Sweden
Housing associations deploy hybrid solutions for six-to-twelve-story timber-frame blocks, blending factory precision with design flexibility for complex urban infill sites. Building code updates mandate disclosed GWP thresholds for envelope assemblies, redirecting specification toward hydrofluoroolefin-blown polyurethane panels. Manufacturing clusters in the Stockholm region and southern industrial belt lead Nordic adoption of low-GWP insulation transitions.
India
Affordable housing contractors source pre-fabricated components to bridge conventional construction capacity shortfalls against national urban housing targets. The PLI scheme for manufacturing and urban housing mission programs create entry points for volumetric suppliers in disaster relief and rapid-deployment applications. Industrial corridors in Maharashtra and Gujarat host emerging prefabrication capacity serving urban housing shortfalls.
Australia
Resource extraction contractors procure fast-track construction systems for remote workforce accommodation and site deployment. State-level building code variations and grid connection protocol fragmentation by municipality extend commissioning timelines for modular multifamily extensions. Manufacturing capacity concentrates in New South Wales and Victoria serving mining and infrastructure project demand.
Global Panelized and Modular Building System Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Global Panelized and Modular Building System Market. The vendor base spans multinational building material conglomerates with backward integration into engineered timber supply chains, mid-scale modular specialists competing on deployment velocity, and regional panel fabricators serving discrete national markets. Three archetypes dominate: thermal-performance technology leaders, fast-track deployment specialists, and timber-frame engineering integrators. Competitive moves concentrate on strategic partnerships for digital twin integration and capacity expansion in certified factory corridors.
Among European-based fabricators, Kingspan Timber Solutions and SAINT-GOBAIN Brüggemann Holzbau GmbH occupy positions within the thermal-performance and engineered timber integration tiers respectively. Modulaire Group represents the fast-track deployment specialist archetype competing on compressed delivery timelines. These three entities exemplify distinct competitive vectors: proprietary insulated panel cores, backward integration into supply chains, and velocity-based contracting for remote site deployment.
| Leading Market Players |
|---|
| Algeco |
| Kingspan Timber Solutions |
| Etex Building Performance |
| Robertson Group Ltd |
| Metek Plc |
| SAINT-GOBAIN Brüggemann Holzbau GmbH |
| Hunter Douglas Group |
| ATCO Ltd |
| Modulaire Group |
| Others |
Value Chain & Pricing Dynamics
Factory utilization rates above 85% in Bavarian and Baden-Württemberg manufacturing corridors establish price floors for certified panel assemblies, while underutilized capacity in emerging Indian industrial corridors enables aggressive entry pricing for pre-fabricated components. This geographic asymmetry in scale economics concentrates margin capture among Central European incumbents while compressing returns for new capacity in cost-competitive regions.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure for thermal envelope assemblies across member states, separating hydrofluoroolefin-blown polyurethane panels certified through Nordic EPD protocols from conventional high-GWP alternatives. Three-tier pricing structure across premium, standard, and economy levels aligns with whole-life carbon disclosure grades, with Swedish and Finnish building codes mandating the premium tier for public procurement. Cost compression in the economy tier is intensifying because Indian affordable housing contractors source uncertified pre-fabricated components to bridge construction capacity shortfalls. Institutional healthcare developers in Germany exhibit the lowest price sensitivity due to fast-track commissioning requirements, while Indian urban housing contractors demonstrate acute sensitivity to first-cost differentials.
Supply Chain Analysis
Germany and Austria anchor engineered timber supply chains through backward-integrated mass timber producers controlling cross-laminated timber feedstock from forest certification through factory prefabrication. Panel assembly draws from hydrofluoroolefin blowing agents reformulated under REACH substance restrictions, certified timber truss connectors, and automated CNC cutting equipment. Single-source vulnerability concentrates in specialized flatbed logistics for oversized module deliveries to remote Australian resource extraction sites. Distribution runs through design-build contractors negotiating multi-project framework agreements directly with fabricators, bypassing traditional general contractor markups in UK and Irish residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified panel assembly technicians cluster in Central European manufacturing corridors at densities insufficient to match projected capacity scaling, creating a persistent bottleneck for factory-built housing associations seeking multi-story timber-frame expansion. This skill scarcity elevates the strategic value of automated fabrication investments and workforce development partnerships.
For Market Incumbents: Fortify positions through captive supply of engineered timber feedstocks and exclusive framework agreements with German housing associations scaling six-to-twelve-story developments. The threat of design-build contractor disintermediation demands direct channel control, while investment in hydrofluoroolefin-blown polyurethane capacity addresses EU F-Gas Regulation compliance friction before supply relationships destabilize. For New Entrants and Emerging Players: Differentiate on digital twin integration capabilities that compress design-to-fabrication timelines for complex urban infill sites. The Indian affordable housing shortfall represents the most penetrable geography, with national urban housing targets exceeding conventional construction capacity by substantial margins. A go-to-market angle anchored to disaster relief and rapid-deployment applications enables volume accumulation before permanent building code certification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors timber-frame engineering integrators with demonstrated multi-story density capabilities and disclosed GWP threshold compliance. Long-term viability over a 5-10 year window rests on regulatory carbon accounting permanence across EU member states and IRA efficiency incentive continuity in the United States. The signal to watch is F-Gas Regulation expansion to additional member states beyond Nordic early adopters, which would accelerate insulation material transition timelines and reward pre-positioned panel manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Timber | Captive CLT feedstock supply secures margin control for German factory-built housing cooperatives. |
| Digital Twin Platform Deployment | BIM-to-factory automation convergence reduces field rework for complex modular multifamily extensions. |
| Hydrofluoroolefin Formulation Transition | Low-GWP polyurethane core certification satisfies Swedish and Finnish building code mandates. |
| Multi-Project Framework Agreements | Direct design-build contractor relationships bypass general contractor markups in UK residential markets. |
| Certified Workforce Pipeline Development | Panel assembly technician training partnerships address Central European manufacturing corridor bottlenecks. |
Study Parameters
Desk research of EU regulatory filings, Nordic EPD protocols, and national building code databases preceded structured interviews with factory operations directors, design-build contractor procurement leads, housing association development officers, and timber-frame engineering specialists. Secondary validation drew from customs trade data for engineered timber imports, SEC filings of publicly traded modular suppliers, and FERC grid interconnection records for modular multifamily projects. Bottom-up project pipeline analysis and top-down construction spend allocation were triangulated against manufacturer capacity disclosures.
Variance decomposition across product type, construction method, end user, and application dimensions informed the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro construction forecasts and regulatory implementation timelines. Industry-specific inputs included EU Green Deal embodied carbon threshold phase-in schedules and IRA efficiency incentive uptake rates for high-performance envelope retrofits.
Material uncertainties — regulatory divergence between EU member states on F-Gas Regulation enforcement, diesel fuel volatility for oversized module logistics, and grid connection protocol fragmentation by municipality — sit outside the modeled envelope. Forecasts reflect assumptions regarding carbon accounting permanence and timber-frame engineering code acceptance for mid-rise density. Recalibration cycles align with material shifts in EU Green Deal implementation timelines and national affordable housing program funding authorizations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Brick Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
North America Concrete Superplasticizer Market