
 Granite Flooring Market | 2026-2036
Granite Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Granite Flooring Market Analysis
Buyer concentration in commercial real estate is restructuring procurement patterns for granite flooring, with hotel chains and mixed-use developers consolidating vendor lists to reduce project risk. M S International, Inc. leverages its North American distribution network to secure large-scale hospitality contracts. Levantina anchors European supply through its integrated quarrying operations in Spain and Brazil. Mohawk Industries, Inc. competes across multiple finish tiers, using its manufacturing scale to serve both premium and mid-market specification channels.
Granite flooring consists of dimension stone slabs cut from igneous rock formations, with Mohs hardness ratings between 6 and 7 and bulk densities typically exceeding 2.6 g/cm³, providing abrasion resistance for high-traffic commercial and institutional environments. Polished finishes command premium specification in luxury residential and hospitality settings where reflectivity and stain resistance drive selection. The commercial application segment sustains higher volume throughput, though outdoor installations are gaining specification share in warm-climate regions where freeze-thaw cycling is minimal. Matte finishes occupy a growing niche in contemporary residential design, particularly where slip resistance ratings align with wet-area building codes.
The U.S. EPA regulates silica exposure in stone fabrication facilities, pushing investment in waterjet cutting and automated polishing to reduce respirable crystalline silica levels. India's BIS dimensional stone standards and the EU's CE marking requirements for construction products create divergent compliance pathways that shape export-oriented production decisions. Stakeholders must monitor evolving building energy codes in key specification markets, as thermal mass properties of granite influence credit eligibility under green building certification systems.
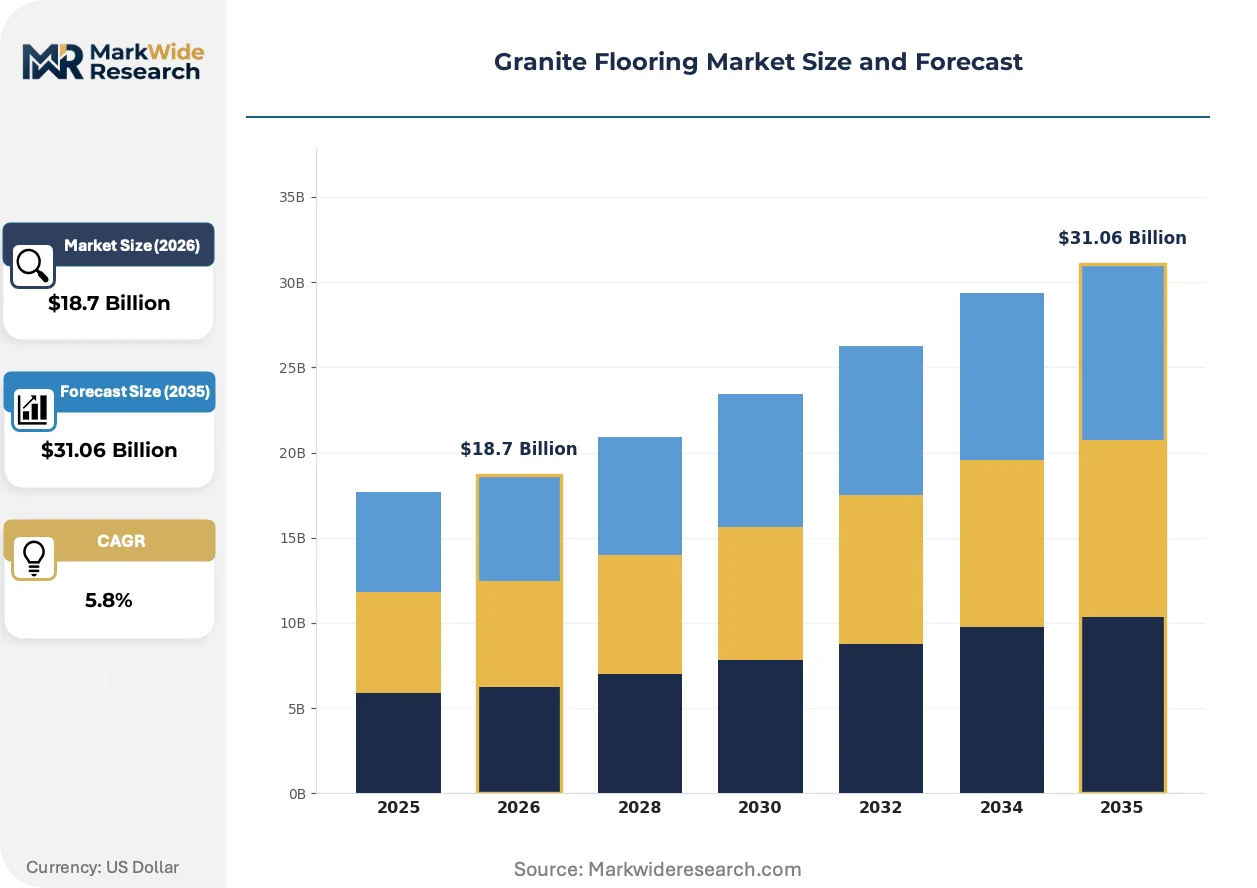
Market Dynamics
Integrated quarry-to-finish operations in Rajasthan's stone processing belt are restructuring supply-side economics, compressing lead times for export-grade material while tightening quality thresholds under India's BIS dimensional stone certification mandates.
Growth Catalysts
- Luxury hospitality procurement:Hotel chains in Dubai and Riyadh are consolidating vendor lists for high-traffic lobbies and suites, pulling volume through dedicated supply agreements with Rajasthan processors.
- Green building thermal mass credits:Granite's thermal properties are gaining specification weight under LEED and BREEAM certification systems, particularly in commercial real estate targeting net-zero operational energy.
- Waterjet cutting adoption:Stone fabrication facilities are deploying waterjet systems to meet EPA silica exposure limits, simultaneously improving edge precision for premium finish tiers.
Market Restraints
- Input cost volatility:Diesel and diamond wire saw consumables fluctuate with crude oil indices, squeezing margin predictability for mid-tier Rajasthan processors.
- Supply concentration risk:Over 60% of export-grade Indian granite originates from the Jaipur-Udaipur corridor, exposing procurement continuity to localized logistics disruptions or monsoon flooding.
- Ceramic tile substitution:Large-format porcelain with printed stone aesthetics is capturing mid-market residential specification where budget elasticity is constrained.
Strategic Opportunities
- Vietnam processing expansion:Greenfield stone fabrication parks near Ha Long Bay offer tariff-advantaged export positioning for North American hospitality specification.
- Outdoor living applications:Warm-climate regions including Florida, Texas, and Australia's Gold Coast are specifying granite for pool decks and alfresco kitchens where freeze-thaw cycling is absent.
- EU CE marking harmonization:Construction Products Regulation compliance is creating a two-tier export market where certified material commands specification priority in German and Dutch commercial projects.
Industry Challenges
- Silicosis remediation liability:Fabrication facilities face retroactive worker compensation claims and OSHA inspection intensity, forcing unplanned capital allocation to dust suppression infrastructure.
- Quarry lease renewal timelines:Rajasthan state mining department processing delays are extending captive stone access from 18 to 36 months, straining forward contract fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granite Flooring Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polished, Honed, Flamed, Acid-Washed Application: Residential, Commercial, Industrial, Outdoor Finish Type: Matte, Glossy, Textured, Brushed Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Arizona Tile, Emser Tile, M S International, Inc., Aro Granite Industries Ltd., Stone Source LLC, Mohawk Industries, Inc., Levantina, Polycor Inc., Antolini Luigi & C. S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granite Flooring Market Emerging Trajectories
Automation in stone finishing and regulatory pressure on workplace silica exposure are compressing the viable supplier base while elevating capital barriers to entry for new market participants.
Waterjet cutting technology is converging with automated polishing lines in high-volume fabrication facilities. Hospitality developers in the GCC are specifying these precision-finished slabs for luxury suite installations. The technology pairing is enabling Rajasthan processors to meet tight dimensional tolerances previously achievable only in Italian stone workshops.
EPA enforcement of respirable crystalline silica limits under 29 CFR 1910.1053 is accelerating capital redeployment across North American fabrication shops. Wet-cutting systems and enclosed cab equipment are becoming baseline compliance investments. Small-to-mid-tier operators without balance sheet capacity for retrofitting are exiting the commercial specification channel.
Buyer concentration among mixed-use developers is consolidating vendor relationships around integrated service providers. Single-source accountability for quarry extraction, finish selection, and logistics coordination is displacing fragmented multi-vendor procurement. This pattern is most visible in Dubai and Riyadh where master developers bundle flooring specification across phased tower deliveries.
Granite Flooring Market Segmentation
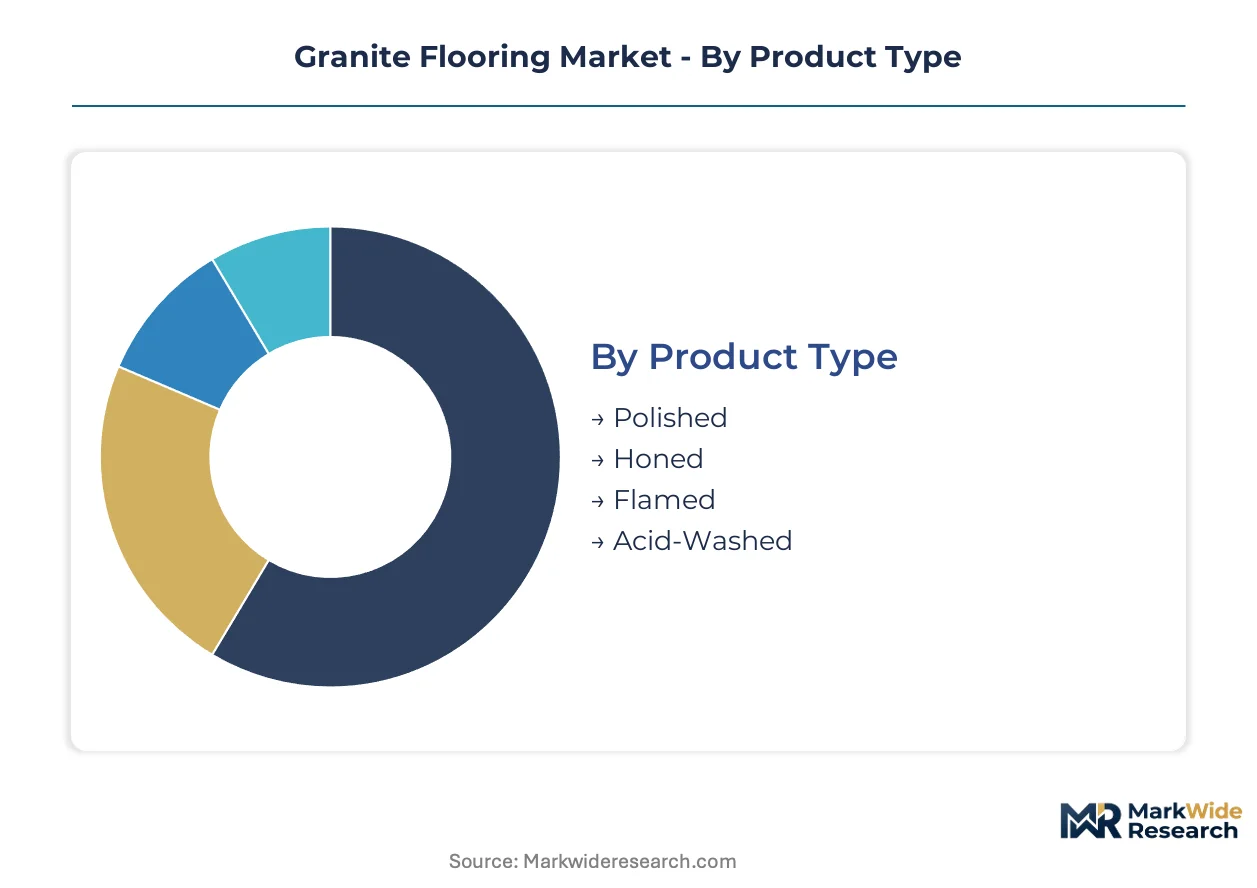
Granite flooring specification hinges on finish durability, installation environment, and procurement channel efficiency. Segmentation reveals how Rajasthan processors align quarry output with divergent end-use requirements across hospitality, residential, and industrial verticals.
Product Type:
Customization intensity varies from mirror-finish precision to rough-hewn utility, with specification engineers balancing aesthetic demands against traffic load and maintenance protocols.
- Polished:Mirror-finish slabs achieve 80+ gloss units through multi-stage diamond abrasive polishing. Demand concentrates in Dubai and Riyadh luxury hospitality lobbies where reflectivity drives spatial perception and stain resistance reduces housekeeping burden.
- Honed:Satin-smooth surfaces stop short of full polish, retaining slip resistance while offering refined aesthetics. Florida and Texas residential pool decks specify honed granite where wet-area building codes intersect with premium outdoor living design.
- Flamed:Thermal shock treatment creates textured, non-slip surfaces ideal for heavy-traffic industrial and exterior applications.
- Acid-Washed:Chemical etching produces antique, weathered appearances favored in heritage restoration and rustic commercial interiors.
Most installed capacity flows through Polished. Expansion is steepest in Honed.
Application:
Volume distribution tracks construction cycle intensity, with commercial real estate commanding batch consistency and residential favoring mixed-pattern flexibility.
- Commercial:Hotel chains, corporate headquarters, and retail flagships drive specification for large-format slabs with tight dimensional tolerances. GCC master developers bundle granite procurement across phased tower deliveries, consolidating vendor relationships around Rajasthan integrated processors.
- Residential:Luxury single-family and multi-family developments specify granite for kitchens, bathrooms, and entry foyers. Australia's Gold Coast and Florida markets favor outdoor living extensions where freeze-thaw cycling is absent.
- Industrial:Manufacturing floors and warehouse facilities prioritize abrasion resistance and load-bearing capacity over aesthetics.
- Outdoor:Patios, walkways, and landscape hardscaping demand weather-resistant finishes with slip-resistant properties.
Commercial channels absorb the highest absolute volume. Residential applications are climbing the fastest.
Finish Type:
Surface treatment selection reflects building code compliance, maintenance economics, and design trend cycles across specification markets.
- Glossy:High-reflectance surfaces command premium positioning in hospitality and luxury residential segments where visual impact justifies higher installed cost and periodic refinishing.
- Matte:Low-sheen finishes align with contemporary residential design trends and wet-area slip resistance requirements. German and Dutch commercial projects under EU CE marking prioritize matte specifications for safety compliance.
- Textured:Mechanically or thermally altered surfaces provide traction for exterior and industrial environments.
- Brushed:Wire-brushed treatment creates subtle linear patterns bridging rustic and modern aesthetic preferences.
Glossy finishes dominate hospitality specification. Matte is gaining share fastest in European commercial compliance markets.
Distribution Channel:
Channel selection determines lead time reliability, finish customization access, and project risk allocation between developers and material suppliers.
- Direct Sales:Quarry-to-site contracting eliminates intermediaries for large-scale hospitality and mixed-use developers. Dubai and Riyadh master developers leverage direct relationships with Rajasthan processors to secure dedicated production lines and compress delivery schedules.
- Distributors:Regional inventory holders buffer smaller commercial and residential projects from supply chain volatility. North American fabrication shops rely on distributor networks for just-in-time slab access.
- Retail:Showroom-based selection serves residential renovation and small-scale commercial specification with visual material confirmation.
- Online:Digital catalog platforms facilitate preliminary specification and price discovery, though physical slab inspection remains standard for final procurement decisions.
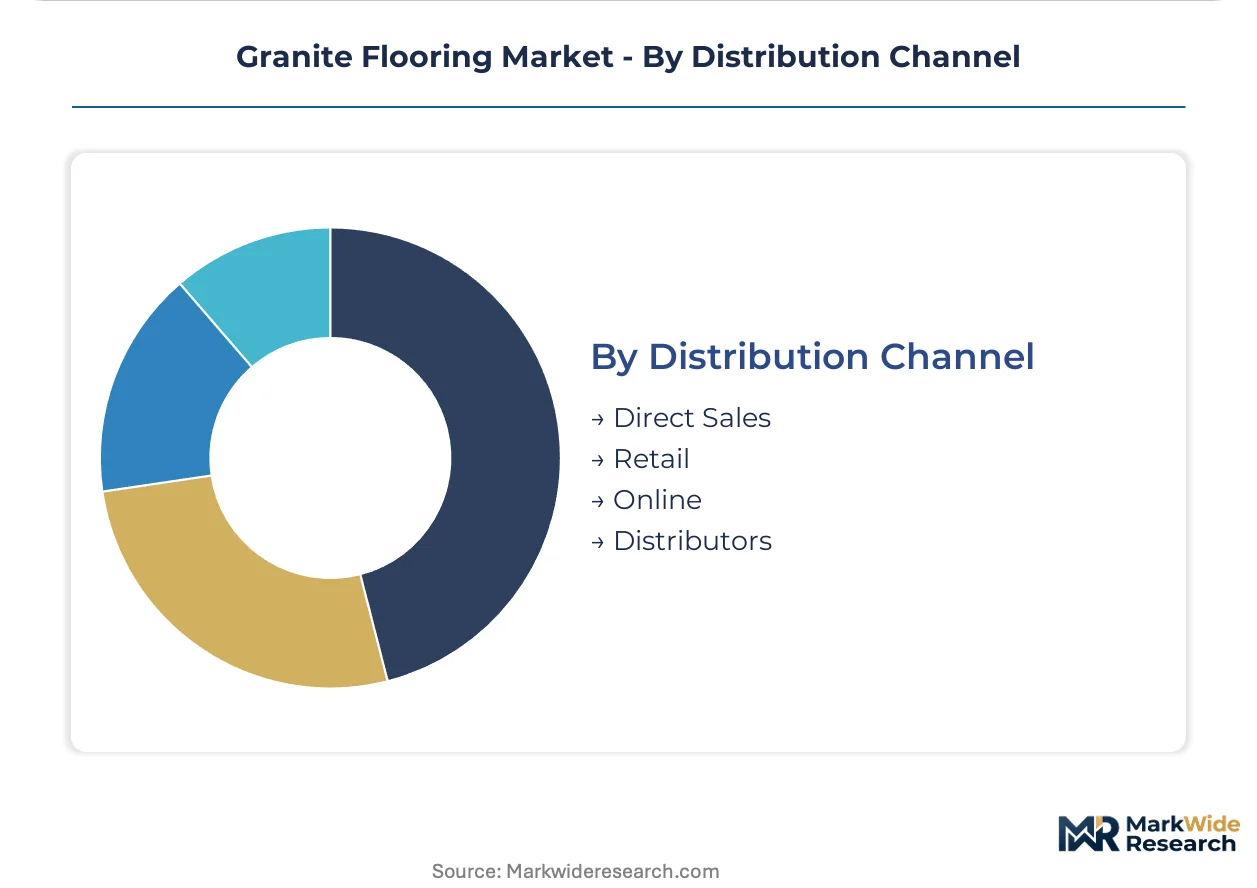
Distributor networks carry the majority of transaction volume. Direct sales channels are expanding most quickly among consolidated hospitality developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled stone artisans in Rajasthan's Jaipur-Udaipur corridor anchor global granite finishing capacity, with quarry-to-polish operations drawing labor from generations of masonry traditions across western India.
United States
Commercial real estate developers in Texas and Florida drive specification for large-format slabs in mixed-use towers and luxury hospitality. The EPA enforces respirable crystalline silica limits under 29 CFR 1910.1053, compelling fabrication shops to deploy waterjet cutting and wet-polishing systems. Dallas-Fort Worth fabrication clusters are consolidating around automated finishing lines to meet compliance deadlines.
India
Rajasthan's stone processing belt supplies over sixty percent of export-grade material to GCC hospitality developers and European commercial projects. The Bureau of Indian Standards mandates dimensional stone certification under revised IS 14223 protocols, tightening quality thresholds for polished and honed finishes. Integrated quarry-to-finish operations in Udaipur and Jodhpur are compressing lead times through captive block extraction.
United Arab Emirates
Master developers in Dubai bundle granite procurement across phased tower deliveries for hotel lobbies and luxury residential suites. MOHAP construction product safety standards align with Gulf Technical Regulation requirements for dimensional stone imports. Jebel Ali fabrication zones are expanding waterjet capacity to serve GCC hospitality specification with reduced lead times.
Germany
Commercial developers in Frankfurt and Munich specify matte-finish granite for LEED and BREEAM thermal mass credits in net-zero office buildings. CE marking under the Construction Products Regulation creates specification priority for certified material in Dutch and Belgian cross-border projects. Ruhr Valley distribution hubs are consolidating inventory for just-in-time delivery to Benelux commercial sites.
Saudi Arabia
Riyadh giga-project developers are consolidating vendor lists for high-traffic hospitality and residential flooring in Diriyah Gate and Qiddiya. The Saudi Food and Drug Authority enforces construction material safety standards parallel to Gulf Technical Regulation frameworks. Eastern Province stone yards near Dammam are expanding direct procurement relationships with Rajasthan processors.
Granite Flooring Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across finish tiers and geographic markets. The vendor base organizes around three strategic archetypes: integrated quarry-to-finish operators controlling upstream block access, regional distributors buffering inventory for just-in-time commercial projects, and fabrication specialists deploying precision waterjet systems for premium hospitality specification. Competitive moves concentrate on backward integration into captive quarry leases and automated finishing line deployment to meet silica exposure regulations.
Within the integrated operator tier, Levantina and Polycor Inc. exemplify quarry-anchored positioning with multi-continent block sourcing. M S International, Inc. represents the distribution-centric archetype, leveraging North American logistics networks to serve consolidated hospitality procurement. Mohawk Industries, Inc. occupies the diversified manufacturing position, competing across multiple finish tiers through manufacturing scale rather than captive stone extraction.
| Leading Market Players |
|---|
| Arizona Tile |
| Emser Tile |
| M S International, Inc. |
| Aro Granite Industries Ltd. |
| Stone Source LLC |
| Mohawk Industries, Inc. |
| Levantina |
| Polycor Inc. |
| Antolini Luigi & C. S.p.A. |
| Others |
Supply Flow & Price Mechanics
Backward integration into captive quarry leases anchors competitive positioning for Rajasthan processors, compressing input cost variability while enabling premium pricing for export-grade polished and honed finishes under tightening BIS certification thresholds. This upstream control insulates integrated operators from diamond wire saw and diesel cost spikes that squeeze mid-tier fabricators lacking captive block access.
Pricing Analysis
Capacity additions in Vietnam's Ha Long Bay fabrication parks are reshaping price floors for North American hospitality specification, intensifying cost competition against established Rajasthan supply. Pricing stratifies across premium, standard, and economy tiers based on finish precision and CE marking compliance, with certified material commanding specification priority in German and Dutch commercial projects. Cost compression in standard-grade polished slabs is intensifying because large-format porcelain substitution captures mid-market residential volume. Budget-constrained residential renovators exhibit highest price sensitivity; GCC master developers bundling phased tower deliveries show least elasticity.
Supply Chain Analysis
Skilled artisan availability in Rajasthan's Jaipur-Udaipur corridor and Vietnam's emerging stone parks shapes fabrication capacity expansion timelines. Supply draws from India, Brazil, and Spain for block extraction, with finishing capacity concentrating in western India and Iberian integrated operations. Raw material sourcing rests on diamond wire saw consumables, diesel fuel for quarry equipment, and resin-based polishing compounds. Single-source vulnerability runs through the Jaipur-Udaipur corridor where monsoon flooding disrupts export logistics. Distribution runs through direct quarry-to-site contracting for large-scale hospitality developers and regional distributor networks buffering North American fabrication shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Granite flooring functions as a stable compounder anchored by durable specification in luxury hospitality and commercial real estate, where thermal mass properties and abrasion resistance sustain replacement-cycle demand regardless of macro volatility.
For Market Incumbents: Anticipate ceramic tile and large-format porcelain substitution pressure in mid-market residential channels by accelerating automated waterjet deployment for precision-finish differentiation. Secure captive quarry lease renewals early given Rajasthan state mining department processing delays extending from 18 to 36 months. Prioritize BIS certification maintenance and CE marking harmonization to defend specification priority in European commercial projects facing Construction Products Regulation compliance deadlines. For New Entrants and Emerging Players: Waterjet cutting technology paired with automated polishing lines offers entry leverage into premium hospitality specification previously monopolized by Italian stone workshops. Target outdoor living applications in Florida, Texas, and Australia's Gold Coast where freeze-thaw cycling absence drives pool deck and alfresco kitchen specification. Pursue direct procurement relationships with GCC master developers bundling flooring specification across phased tower deliveries. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Rajasthan processors with captive quarry access because fragmented vendor relationships among mixed-use developers are consolidating around integrated service providers. Five-to-ten year viability hinges on silica compliance infrastructure and automation deployment capacity. Monitor EPA enforcement intensity under 29 CFR 1910.1053 as inflection indicator for North American fabrication shop consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Waterjet Deployment | Meets EPA silica limits while achieving Italian-grade dimensional precision for GCC hospitality suites. |
| Captive Quarry Lease Renewal | Secures 36-month forward block access against Rajasthan state mining department processing delays. |
| CE Marking Harmonization | Unlocks specification priority in German and Dutch commercial projects under Construction Products Regulation. |
| Direct Sales Channel Expansion | Eliminates intermediaries for Dubai and Riyadh master developers bundling phased tower deliveries. |
| Outdoor Living Specification Push | Captures Florida and Texas pool deck demand where freeze-thaw cycling absence enables granite durability. |
Methodological Framework
Coverage spans North America, India, the GCC, and Western Europe, with primary inputs from each region triangulated against secondary validation. Quarry operators, stone fabrication facility managers, hospitality procurement directors, commercial real estate developers, and distributor network heads provided stakeholder perspectives. Secondary sources include Bureau of Indian Standards certification records, EPA enforcement disclosures under 29 CFR 1910.1053, EU Construction Products Regulation documentation, and trade flow data from customs authorities. Bottom-up project pipeline analysis and top-down construction spend allocation were reconciled for volume estimation.
Rate-of-change decomposition separates volume growth from value growth across the analysis window. Segmentation dimensions encompass finish type, application vertical, distribution channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to construction cycle intensity and specification penetration rates. Forecast inputs incorporate LEED and BREEAM thermal mass credit adoption curves, waterjet technology diffusion timelines, and quarry lease renewal velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA silica enforcement intensity, Rajasthan monsoon disruption frequency, and ceramic tile substitution acceleration in residential channels. Assumptions reflect current regulatory trajectories and technology adoption patterns. Material deviation in silica compliance deadlines, BIS certification protocol revisions, or GCC hospitality construction cycle inflection warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Steel Pipe Piles Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Plastic Door and Window Market