
 Balustrade Market | 2026-2036
Balustrade Market Size, Share, and Industry Trends Forecast 2026-2036
Balustrade Market Analysis
Modular glass tempering and CNC-fabricated stainless steel connections is reconfiguring how balustrade systems achieve structural compliance with slimmer profiles. Feeney leverages its cable railing expertise to anchor premium residential specifications across North American coastal markets. Q-railing dominates European specification channels through its engineered handrail systems and project support infrastructure. JIANGSU AIRUS BALUSTRADES LIMITED sustains cost-competitive manufacturing scale for glass-and-aluminum assemblies serving Asian commercial towers.
A balustrade is a row of repeating vertical supports—balusters—topped by a handrail, engineered to prevent falls from elevated surfaces and typically fabricated from wood, metal, glass, or composite materials with specified load-bearing capacities per building code. Metal and glass type segments command the strongest specification pull in commercial atriums and transit infrastructure where visibility and durability requirements converge. Prefabricated and modular feature segments are gaining fastest traction as general contractors compress installation schedules and reduce on-site labor variables. Customizable decorative balustrades retain margin concentration in heritage restoration and luxury residential projects where craft differentiation resists commoditization.
Building codes enforced by the International Code Council in the United States and the CE marking framework under EU Construction Products Regulation govern balustrade load resistance, glass impact safety, and dimensional tolerances, directly shaping material certification costs and market access conditions. China's GB standards and MEE circular economy directives increasingly influence glass recycling content requirements and aluminum extrusion energy intensity benchmarks for domestic and export-bound producers. Stakeholders must monitor diverging national code cycles and embodied carbon disclosure obligations as specification gatekeepers.
Market Dynamics
Modular fabrication and CNC-machined stainless steel connections are compressing installation timelines while glass tempering automation reduces defect rates. These process innovations are redirecting specification authority from traditional fabricators toward system-integrated suppliers with certified manufacturing footprints.
Growth Catalysts
- High-rise residential construction in China's coastal provinces:Guangdong, Jiangsu, and Zhejiang provinces are adding residential tower stock requiring code-compliant glass-and-aluminum balustrade assemblies at scale.
- REACH compliance mandates in Europe:ECHA restrictions on chromium VI in metal finishing are accelerating specification migration toward powder-coated aluminum and tempered glass systems.
- Prefabricated modular systems:General contractors facing compressed construction schedules are specifying factory-integrated balustrade modules that reduce on-site labor hours.
Market Restraints
- Flat glass price volatility:Energy-intensive float glass production faces input cost pressure from natural gas and soda ash supply fluctuations.
- Concentration in Chinese aluminum extrusion:Shandong and Henan provinces control critical capacity for structural aluminum profiles, creating geographic supply risk.
- Substitution by solid panel guardrails:Perforated metal and composite solid panels are capturing share in industrial and transit applications where visibility is secondary.
Strategic Opportunities
- Heritage restoration projects in Italy and France:EU-funded building conservation programs are generating demand for craft-fabricated decorative metal balustrades with historical fidelity.
- MEA high-rise hospitality construction:Dubai and Riyadh tower developments are specifying premium glass balustrade systems for podium and pool deck applications.
- Convergence of BIM and modular fabrication:Digital fabrication workflows enabling parametric design-to-production pipelines for complex curved glass geometries.
Industry Challenges
- Certified welder and glass tempering technician shortages:Specialized fabrication skills required for structural metal and heat-soaked tempered glass production are constraining capacity expansion.
- Multi-jurisdiction code compliance complexity:Manufacturers serving cross-border projects must maintain parallel certifications under ICC, CE marking, and GB standards frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balustrade Market |
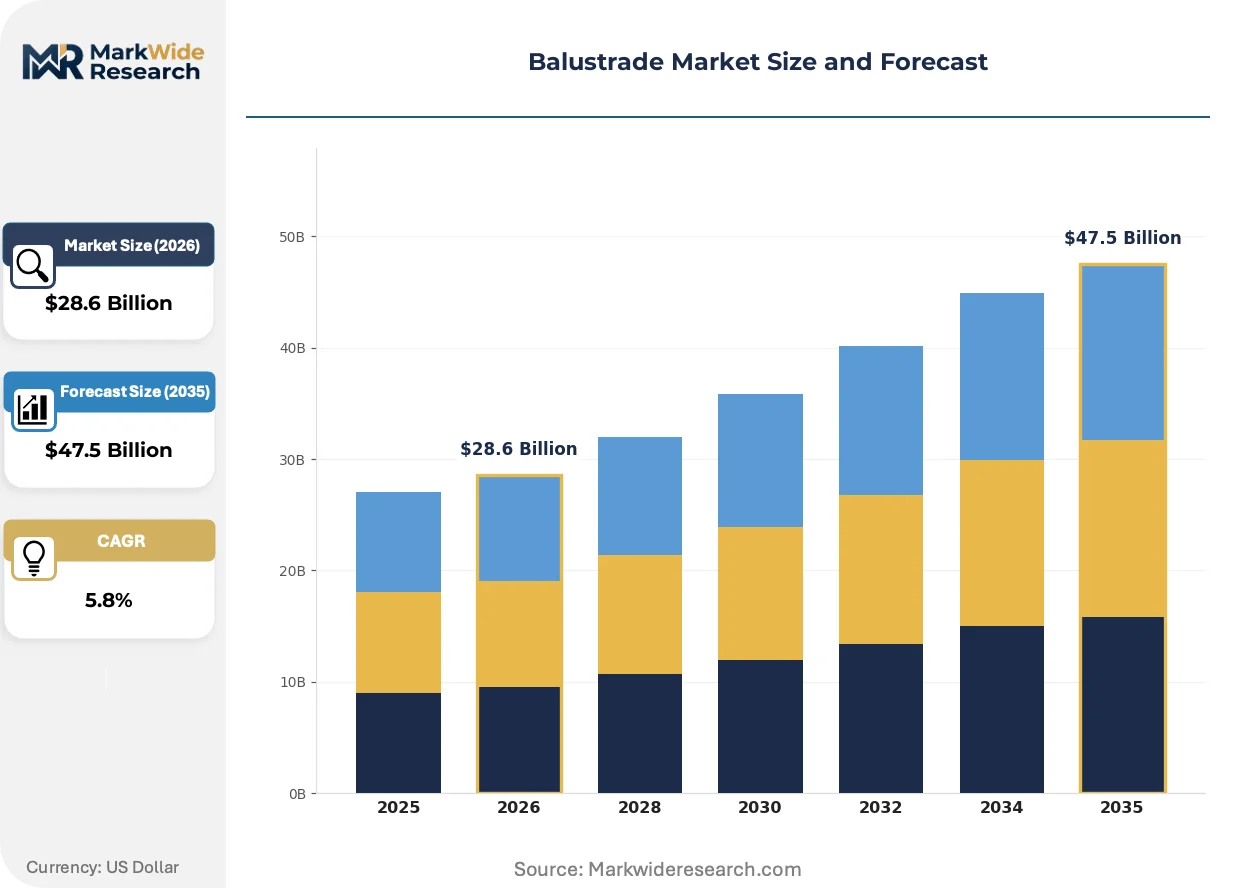
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wood, Metal, Glass, Composite Application: Residential, Commercial, Industrial, Outdoor Feature: Prefabricated, Customizable, Modular, Decorative Installation: New Construction, Renovation, DIY, Professional |
| Companies Covered | Feeney, Vista Railing Systems, C.R. Laurence, Bohle America, Viewrail, Q-railing, Kee Safety, JIANGSU AIRUS BALUSTRADES LIMITED, The Wagner Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balustrade Market Emerging Trajectories
Digital fabrication and regulatory disclosure requirements are compressing traditional supply chain hierarchies while enabling new specification pathways. Three developments are restructuring competitive positioning.
Laser-welded stainless steel node systems are collapsing the structural depth required for cable and glass balustrade assemblies. High-end residential architects in California and Florida are specifying these slimmer profiles for unobstructed coastal views. The technology is collapsing the traditional trade-off between structural compliance and visual transparency that favored thicker aluminum extrusions.
EU Construction Products Regulation transparency obligations are mandating embodied carbon disclosure for glass and aluminum balustrade systems placed on the European market. Manufacturers must now document cradle-to-gate carbon intensity through third-party verified EPDs. German and Dutch specification channels are prioritizing suppliers with verified low-carbon extrusion and recycled glass content.
Design-build procurement consolidation is compressing traditional distributor roles as facade contractors assume direct sourcing responsibility for integrated balustrade systems. This pattern is most visible in US commercial tower construction where general contractors are awarding package contracts to single-source envelope specialists. Traditional specification-dependent distributors are responding by adding installation capability and warranty backing.
Balustrade Market Segmentation
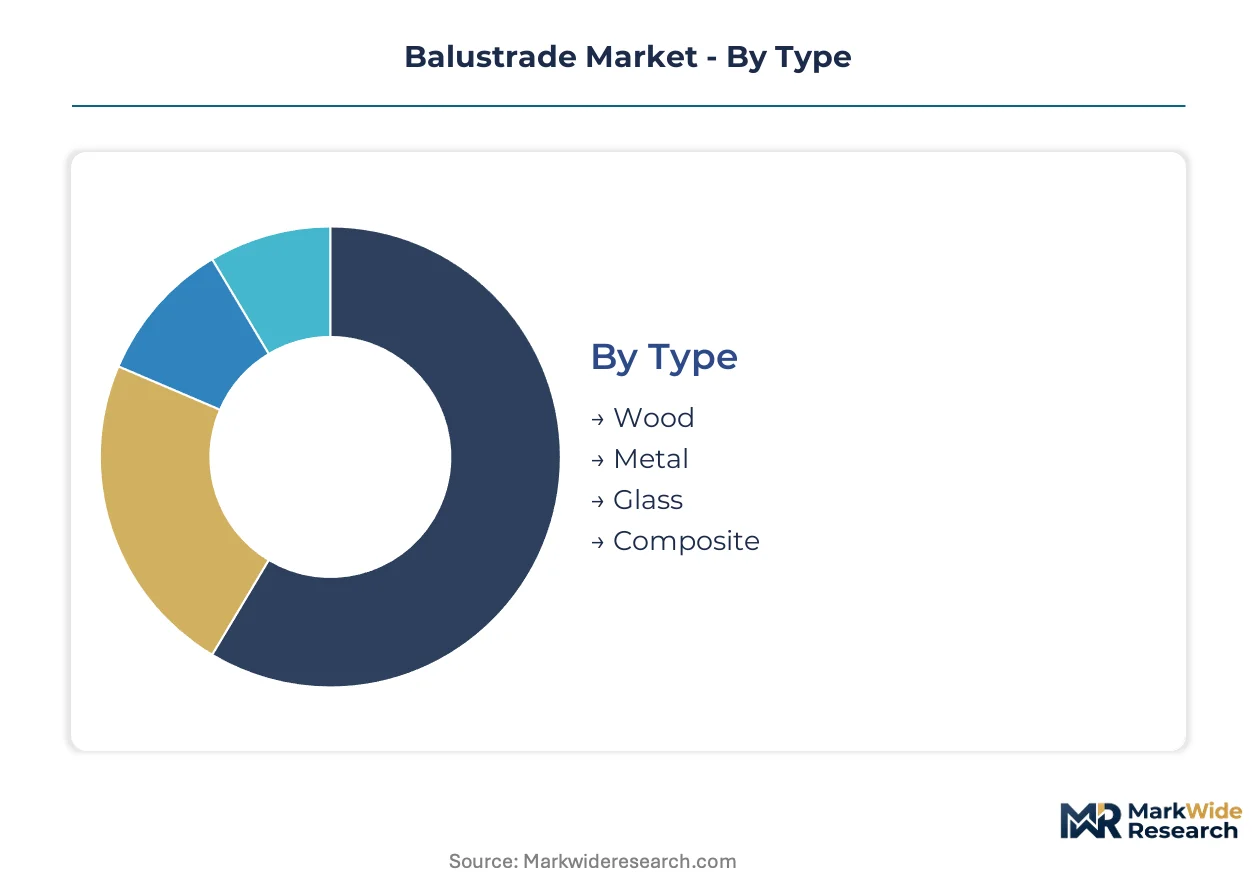
Balustrade procurement patterns diverge sharply across material types and installation contexts. Specification authority flows differently for new construction versus renovation cycles, while regulatory compliance thresholds reshape viable feature configurations.
Type:
Glass and metal systems turn over fastest in commercial tower construction where lease cycles drive facade refresh timelines, while wood and composite products persist longer in residential settings where replacement follows structural failure rather than aesthetic obsolescence.
- Metal:Fabricated from stainless steel, aluminum, or wrought iron with specified load-bearing capacities per ICC and CE marking frameworks. Demand concentrates in US transit infrastructure and German commercial atriums where durability requirements override first-cost sensitivity.
- Glass:Tempered or laminated panels with heat-soak testing for structural balustrade applications. Coastal high-rise towers in China's Guangdong and Zhejiang provinces specify these systems for unobstructed views, though flat glass price volatility constrains margin stability.
- Wood:Traditional material for residential porches and heritage restorations requiring craft fabrication. EU-funded conservation programs in Italy and France sustain niche demand.
- Composite:Glass-reinforced polymer or mineral-composite materials offering corrosion resistance for marine and poolside environments.
Metal anchors the volume base while glass gains share at the steepest rate.
Application:
Cost tier differentiation separates specification pathways, with commercial and industrial applications absorbing premium-engineered systems while residential procurement fragments across price points.
- Commercial:Office atriums, retail podiums, and hospitality lobbies requiring code-compliant visibility and crowd load resistance. Dubai and Riyadh tower developments specify premium glass systems for podium applications.
- Residential:Suburban North American single-family construction and Chinese coastal province high-rise towers drive volume. Prefabricated modular systems compress installation schedules for general contractors facing labor constraints.
- Industrial:Manufacturing facilities and logistics centers where perforated metal solid panels increasingly substitute traditional balustrades.
- Outdoor:Pool decks, balconies, and landscape structures exposed to weathering cycles.
Residential commands the largest revenue pool while commercial applications deliver the highest per-project specification values.
Feature:
Supply concentration favors system-integrated suppliers with certified manufacturing footprints for prefabricated and modular categories, while decorative segments retain fragmented craft-fabricator networks.
- Prefabricated:Factory-integrated balustrade modules reducing on-site labor hours and installation variables. General contractors in US commercial tower construction specify these for schedule compression.
- Modular:CNC-fabricated stainless steel connections and standardized glass panel dimensions enabling field assembly without specialized welding. This category is expanding most quickly as BIM-to-fabrication workflows mature.
- Customizable:Parametric design capabilities for curved glass geometries and heritage-matched metalwork. Heritage restoration projects in France and Italy require craft differentiation that resists commoditization.
- Decorative:Ornamental metal balustrades with historical fidelity for conservation programs.
Prefabricated systems dominate current volume while modular configurations are climbing the fastest.
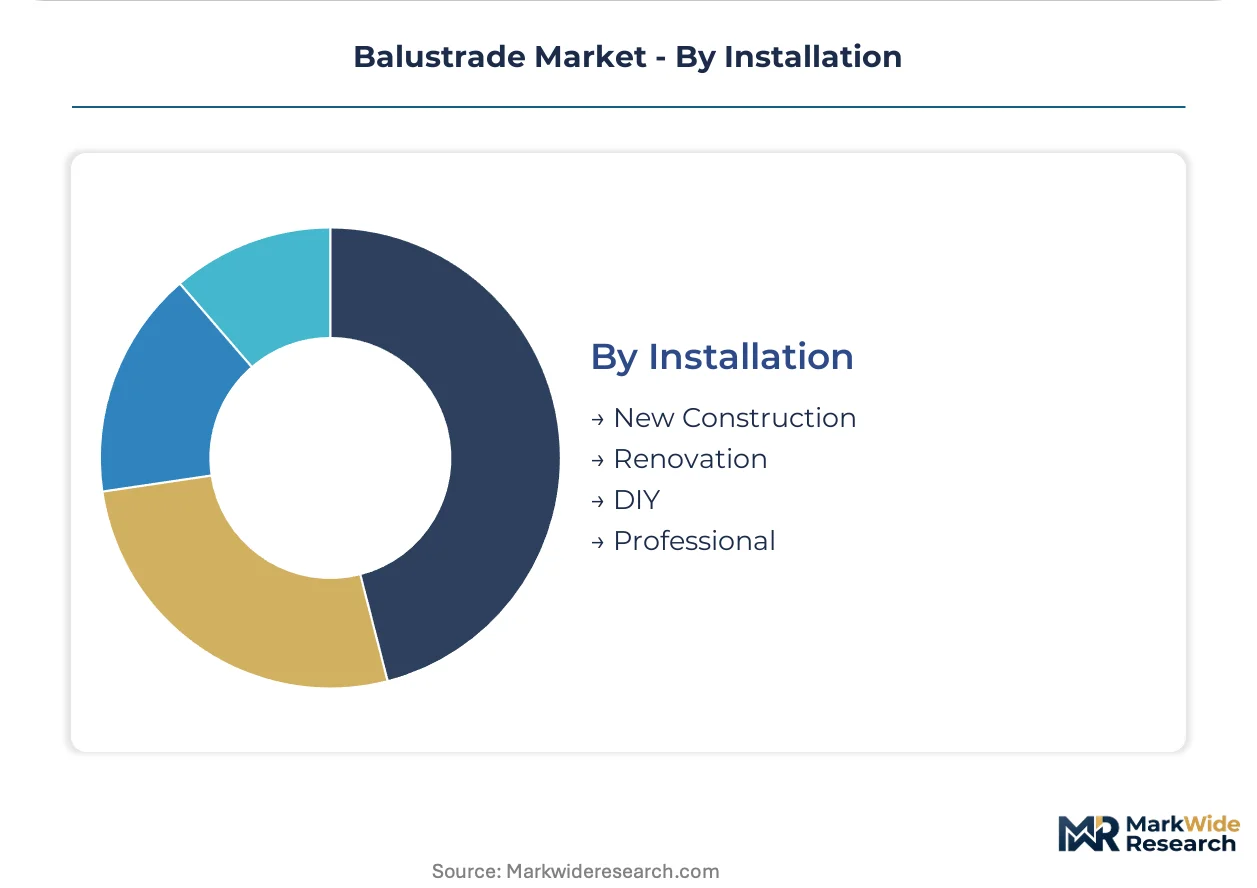
Installation:
Customer type splits the market between professional specification channels and retail-accessible replacement demand, with renovation cycles shorter than new construction timelines.
- New Construction:Specified during design phase with integrated facade contractor procurement. Design-build consolidation in US commercial towers compresses traditional distributor roles.
- Renovation:Triggered by code compliance upgrades or structural failure in existing buildings. Shorter decision cycles than new construction with greater price sensitivity.
- Professional:Architect-specified and contractor-installed systems with warranty backing and certified welder labor.
- DIY:Retail-channel products for residential replacement with simplified connection systems.
New construction absorbs the highest absolute volume while renovation channels are expanding most quickly in mature building stock markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Architects and general contractors in high-rise construction corridors drive balustrade procurement intensity. Specification authority clusters where building codes mandate tempered glass visibility and facade integration timelines compress.
United States
Coastal California and Florida markets specify slim-profile cable and glass systems for ocean-view residential towers. The International Code Council enforces load-resistance standards that elevate certified-fabricator procurement. Miami-Dade County's hurricane-impact glazing codes concentrate specification authority with envelope specialists capable of structural calculations.
Germany
Commercial atrium construction in Frankfurt and Munich sustains demand for engineered handrail systems with CE marking compliance. ECHA REACH restrictions on chromium VI metal finishing redirect specification toward powder-coated aluminum. Bavarian fabricators dominate modular stainless-steel connection supply for cross-border EU projects.
China
Guangdong, Jiangsu, and Zhejiang provinces add residential tower stock requiring code-compliant glass-and-aluminum assemblies at scale. GB standards and MEE circular-economy directives govern glass recycling content and aluminum extrusion energy benchmarks. Shenzhen and Shanghai facade contractors integrate balustrade modules into design-build envelope packages.
Italy
EU-funded heritage restoration programs in Rome and Florence generate demand for craft-fabricated decorative metal balustrades with historical fidelity. Conservation architects specify wrought-iron replication techniques that resist modular substitution. Tuscan metalworking clusters anchor artisan production capacity for continental conservation projects.
UAE
Dubai and Riyadh hospitality tower developments specify premium glass balustrade systems for podium and pool-deck applications. MOHAP building-safety regulations align with European CE marking frameworks for imported systems. Jebel Ali manufacturing zones host aluminum extrusion and glass tempering facilities serving Gulf Cooperation Council projects.
Balustrade Market Vendor Landscape
Channel-controlling players compete with product-specialist players across specification-dependent and contractor-direct procurement pathways. The vendor base separates into system-integrated suppliers with certified manufacturing footprints, regional fabricators serving renovation channels, and craft-metalwork specialists anchored in heritage conservation. Three archetypes dominate: envelope-integrated suppliers capturing design-build consolidation, modular-system fabricators compressing installation schedules, and decorative-metal specialists defending margin in restoration niches. M&A activity concentrates among facade contractors acquiring installation capability, while technology licensing spreads CNC-fabrication workflows between tier-one and tier-two producers.
Among North American specification-channel players, Feeney and Viewrail occupy positions within cable-railing and premium residential system tiers. Q-railing exemplifies the European engineered-handrail archetype with project-support infrastructure. JIANGSU AIRUS BALUSTRADES LIMITED anchors the cost-competitive manufacturing scale tier for Asian commercial tower supply. These three represent distinct geographic and capability positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| Feeney |
| Vista Railing Systems |
| C.R. Laurence |
| Bohle America |
| Viewrail |
| Q-railing |
| Kee Safety |
| JIANGSU AIRUS BALUSTRADES LIMITED |
| The Wagner Companies |
| Others |
Supply Flow & Price Mechanics
Shandong and Henan provinces control critical capacity for structural aluminum extrusions, concentrating margin capture with integrated facade contractors who bundle balustrade modules into design-build envelope packages. Glass tempering automation in China's coastal manufacturing zones feeds cost-plus contract structures indexed to flat glass and natural gas benchmarks.
Pricing Analysis
Cost-plus contracts with quarterly indexation to soda ash and natural gas benchmarks dominate procurement for glass balustrade assemblies. Pricing stratifies across premium, standard, and economy tiers based on heat-soak testing certification and CNC fabrication precision. Cost compression in standard-tier aluminum systems is intensifying because of energy-intensive extrusion margins. Residential renovation channels exhibit highest price sensitivity, while hospitality developers in Dubai and Riyadh absorb premium specifications.
Supply Chain Analysis
Tariff exposure between China and North American import markets dominates supply chain risk planning for aluminum profile sourcing. Manufacturing gravity centers on China for glass tempering and aluminum extrusion, Germany for engineered stainless-steel connections, and Italy for craft-fabricated decorative metalwork. Raw material dependencies include float glass, 6063 aluminum billet, and austenitic stainless steel. Distribution runs through facade contractors consolidating direct sourcing responsibility in US commercial tower construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation and warranty service layers are expanding faster than hardware sales as design-build procurement compresses traditional distributor roles. Recurring maintenance contracts for tempered glass inspection and structural recertification represent the fastest-attaching revenue stream.
For Market Incumbents: Entrench specification authority by acquiring certified welding and glass tempering technician capacity in constrained labor markets. Backward integration into CNC-fabricated stainless-steel node production defends margin against modular-system competitors. Investment in EPD certification and low-carbon extrusion capability secures priority positioning in German and Dutch specification channels threatened by EU embodied-carbon disclosure mandates.
For New Entrants and Emerging Players: Heritage restoration demand in Italy and France presents underpenetrated white-space with craft-fabrication barriers resisting commoditization. MEA high-rise hospitality construction offers specification entry points through podium and pool-deck applications where visibility requirements favor glass systems. Go-to-market leverage rests on parametric BIM-to-fabrication workflows for curved geometries that incumbent metalworkers cannot quote competitively.
For Investors and Strategic Acquirers: Capital is best deployed toward envelope-integrated suppliers with captive installation capability and warranty infrastructure. Long-term viability favors fabricators who control both modular-system IP and certified technician labor pools. The signal to watch is design-build procurement consolidation velocity in US commercial towers, which accelerates distributor displacement and favors acquisition targets with direct contractor relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captures margin from Shandong and Henan supply concentration while hedging against flat glass price volatility. |
| EPD Certification Investment | Unlocks German and Dutch specification channels prioritizing verified low-carbon balustrade systems under EU CPR transparency obligations. |
| CNC Fabrication Workflow Licensing | Spreads modular stainless-steel node technology to tier-two producers facing certified welder shortages. |
| Installation Capability Acquisition | Responds to design-build consolidation by adding warranty-backed labor to traditional distribution models. |
| Heritage Conservation Partnership | Secures EU-funded restoration project access through Tuscan metalworking cluster relationships in Italy. |
Methodological Framework
A standing panel of facade contractor procurement directors, certified glass tempering technicians, conservation architects, and envelope specialist project managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with specification-channel stakeholders and secondary validation through building code filings, customs trade data for aluminum extrusion and flat glass, and SEC disclosures from publicly traded construction materials distributors. Bottom-up project pipeline analysis triangulated against top-down construction spend forecasts.
Scenario-bracketing around energy price volatility and code cycle timing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, application context, feature configuration, and installation channel, with regional regulatory clusters treated as distinct adoption envelopes. CAGRs were derived from fitted growth curves calibrated to disclosed project awards and permit filings. Industry-specific forecast inputs encompassed GB standards evolution in China and ECHA REACH restriction implementation timelines in Europe.
Practitioners should monitor flat glass price volatility, certified technician wage inflation, and design-build procurement consolidation velocity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market