
 France Ceramic Tiles Market | 2026-2036
France Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
France Ceramic Tiles Market Foresight
Spanish and Italian producer investments into southern France distribution hubs is broadening supply-side capacity near Marseille and Toulouse. Saint-Gobain leverages its building materials ecosystem to anchor large-format porcelain distribution across French retail networks. Groupe Cerabati sustains regional manufacturing presence in Provence-Alpes-Côte d'Azur, competing on proximity to Mediterranean renovation markets. Novoceram differentiates through design-led collections targeting premium residential segments in Lyon and Bordeaux.
France ceramic tiles are fired clay or porcelain slabs, typically measuring 300x300mm to 600x1200mm, produced via dry pressing and kiln firing at 1,100–1,250°C for interior and exterior surface covering. Their primary commercial purpose spans flooring, wall cladding, and facade systems across residential, hospitality, and institutional construction. Porcelain commands structural margin pools due to density and frost resistance specifications, while glazed variants occupy volume leadership in residential renovation. Mosaic and quarry tiles lead niche applications where heritage restoration and outdoor slip resistance drive specification.
CE marking under the EU Construction Products Regulation governs mechanical performance and slip resistance declarations, while REACH restricts heavy metal content in glazes and pigments. ANSM and French environmental agencies enforce extended producer responsibility schemes for construction waste, shaping recycling infrastructure investments. Stakeholders must monitor evolving carbon footprint disclosure rules under the EU Green Deal and position supply chains for low-emission kiln technologies before compliance deadlines tighten.
Market Dynamics
France's ceramic tiles sector faces intensifying pressure from the EU Green Deal's embodied carbon disclosure mandates, which are forcing kiln technology upgrades and reshaping competitive positioning among domestic and imported supply sources.
Growth Catalysts
- Île-de-France Renovation Wave:Parisian residential stock renewal is accelerating porcelain tile specification for flooring and facade systems, with heritage building conversions driving demand for large-format slabs.
- REACH Compliance Differentiation:Heavy metal restrictions in glazes and pigments are rewarding early-adopting French manufacturers with preferential specification from institutional buyers seeking verified low-toxicity surfacing.
- Digital Inkjet Decoration:Advanced printing technologies are enabling shorter production runs and customized surface aesthetics, allowing regional producers to compete on design flexibility against volume imports.
Market Restraints
- Natural Gas Cost Volatility:Kiln firing energy inputs represent a structural cost vulnerability, with French industrial gas tariffs exposing domestic producers to margin compression versus solar-powered Spanish competitors.
- Italian Supply Concentration:Premium design-led collections remain dominated by Sassuolo-based manufacturers, limiting price-setting autonomy for French brands in architect-specified projects.
- Thin-Panel Substitution:Large-format sintered stone slabs from engineered quartz and porcelain hybrid technologies are displacing traditional thick ceramic tiles in commercial flooring applications.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Coastal Markets:Mediterranean climate renovation activity and second-home refurbishment present underpenetrated demand for frost-resistant porcelain in outdoor terraces and pool surrounds.
- Extended Producer Responsibility Schemes:ANSM-enforced construction waste recycling mandates are creating first-mover advantages for producers investing in closed-loop tile grinding and reconstitution infrastructure.
- CE Marking Plus Carbon Labeling:The EU Construction Products Regulation's evolving environmental performance declarations offer differentiation pathways for low-emission kiln operators seeking premium positioning.
Industry Challenges
- Electrified Kiln Engineering Talent:The transition from natural gas to electric or hydrogen-fired kilns requires scarce thermal process specialists, constraining compliance timelines for mid-cap producers.
- Slip Resistance Certification Complexity:Multi-standard testing for wet pendulum and ramp methods creates bottlenecks in product launch cycles, particularly for exporters serving both French and adjacent Benelux markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Ceramic Tiles Market |
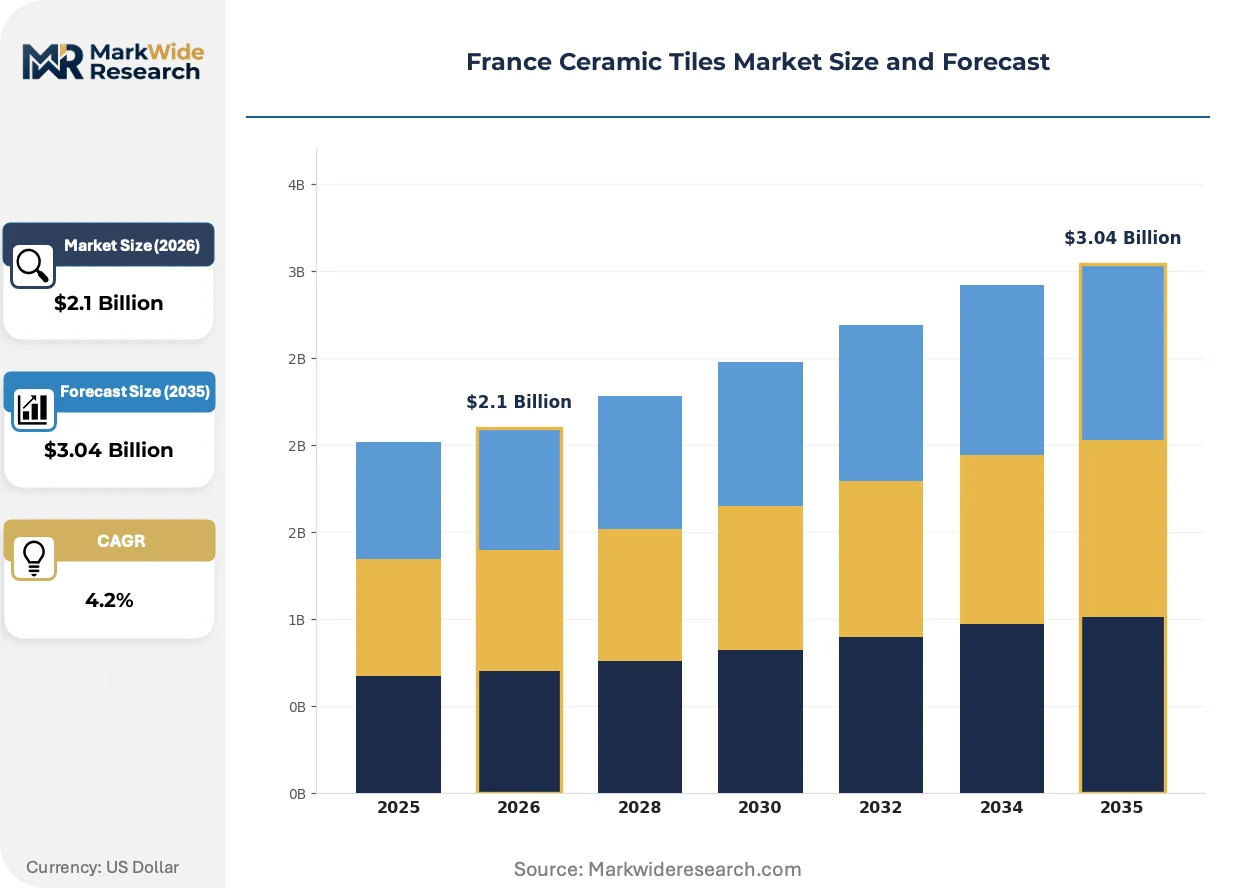
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glazed, Unglazed, Mosaic, Quarry Application: Flooring, Wall Covering, Countertops, Facades, Outdoor Paving Distribution Channel: Specialty Stores, Online Retailers, Wholesalers, Home Improvement Centers, Direct Sales Customer Type: Residential Builders, Commercial Contractors, Interior Designers, DIY Enthusiasts |
| Companies Covered | Saint-Gobain, Groupe Cerabati, Novoceram, Keros Ceramica, Diffusion Ceramique, Grespania Ceramica, Marazzi Group, Porcelanosa Group, Desvres Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Ceramic Tiles Market Shifts & Advancements
Digital manufacturing integration and regulatory environmentalism are converging to transform how French ceramic tiles are specified, produced, and distributed across residential and commercial construction channels.
Continuous inkjet printing with reactive pigments is electrifying surface decoration capabilities, enabling photorealistic stone and wood replication on porcelain bodies. High-end residential developers in Lyon and Bordeaux are specifying these digitally enhanced collections for luxury apartment fit-outs, compressing lead times from design conception to installed surface and displacing traditional silk-screen pattern limitations.
The EU Green Deal's Carbon Border Adjustment Mechanism is tightening disclosure requirements for imported ceramic products, with French environmental agencies coordinating verification protocols for embodied emissions declarations. Domestic producers with biomass or electric kiln investments are securing preferential listing in public procurement frameworks, while Spanish and Italian exporters face documentation friction entering the French market.
Architects and interior designers are consolidating specification authority through centralized procurement platforms, displacing traditional merchant distributor relationships in commercial projects. This channel compression is most visible in the Rhône-Alpes manufacturing belt, where Lyon-based design studios are negotiating direct mill relationships for large-format porcelain in hospitality and office developments, bypassing regional tile showrooms.
France Ceramic Tiles Market Segmentation
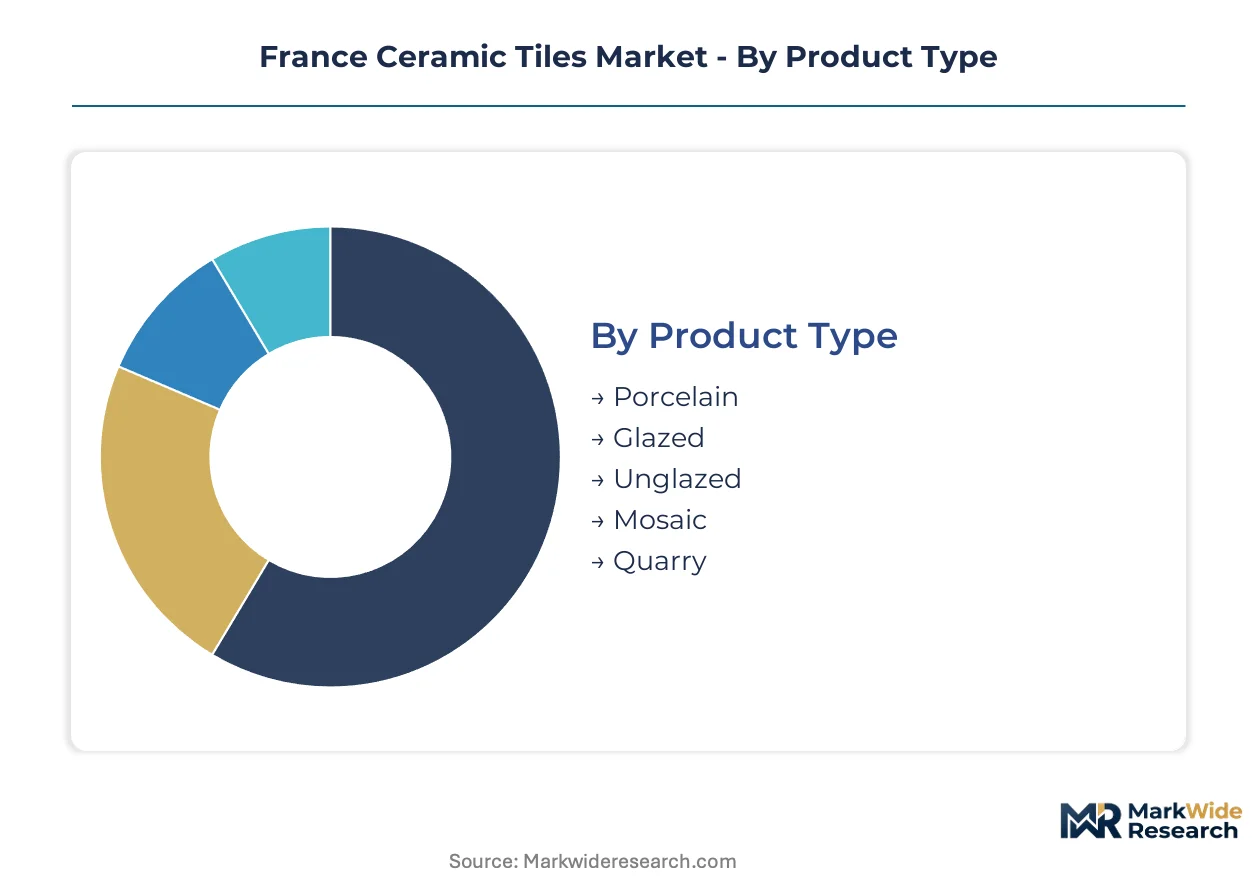
Segmentation in the France ceramic tiles market reveals how kiln capacity, distribution infrastructure, and specification authority concentrate across distinct product categories and customer channels. Understanding these divisions exposes where margin pools form and where compliance burdens fall heaviest.
Product Type:
Supply concentration in French ceramic tile manufacturing clusters around high-density porcelain output, with kiln investments in the Rhône-Alpes belt favoring technical specifications over decorative volume plays.
- Porcelain:Fired at 1,200–1,250°C, porcelain achieves water absorption below 0.5% and frost resistance mandatory for exterior applications. Parisian facade renovation projects and Île-de-France residential conversions specify large-format porcelain slabs, absorbing capacity from Saint-Gobain's distribution network and Spanish imports through Marseille hubs.
- Glazed:Surface vitrification through ceramic glaze application delivers design versatility at moderate density, with digital inkjet decoration enabling shorter production runs. Wall covering applications in Lyon and Bordeaux residential renovation dominate demand, though REACH heavy metal restrictions in pigments constrain formulation flexibility.
- Unglazed:Through-body color consistency suits high-traffic commercial flooring where surface wear must not expose contrasting substrate.
- Mosaic:Small-format tesserae serve heritage restoration in Provence-Alpes-Côte d'Azur and bathroom accent niches.
- Quarry:Extruded clay bodies with natural slip resistance specification concentrate in outdoor terrace and pool surround installations.
Porcelain absorbs the bulk of installed capacity; glazed variants are expanding most quickly through inkjet customization capabilities.
Application:
Application segmentation tracks how construction activity distributes across new-build versus renovation cycles, with the EU Green Deal's embodied carbon rules reshaping specification priorities in commercial versus residential channels.
- Flooring:Structural load-bearing requirements and slip resistance certification (wet pendulum testing under CE marking) dominate technical specification. Rhône-Alpes hospitality developments and Parisian office conversions drive large-format porcelain demand, with thin-panel sintered stone substitution threatening traditional thick ceramic in premium commercial segments.
- Wall Covering:Lower mechanical stress permits lighter substrates and broader decorative range, with digital printing enabling photorealistic surface replication. Interior designers in Lyon specify these collections for luxury residential fit-outs, compressing traditional silk-screen pattern limitations.
- Countertops:Edge profile fabrication and stain resistance specifications concentrate demand in kitchen renovation.
- Facades:Ventilated rainscreen systems and frost-thaw cycling resistance anchor technical compliance burdens.
- Outdoor Paving:Freeze-thaw durability and anti-slip grading concentrate demand in Mediterranean climate second-home refurbishment.
Flooring commands the deepest specification expertise; facades are climbing the fastest as Parisian building envelope renovation accelerates.
Distribution Channel:
Channel structure reflects a compression between centralized procurement platforms and residual merchant distributor relationships, with design authority consolidation reshaping how tiles reach installation sites.
- Specialty Stores:Curated showroom environments with sample libraries and specification support anchor architect and interior designer relationships. Lyon-based design studios negotiate direct mill access, bypassing these intermediaries in large commercial projects.
- Online Retailers:Digital catalog browsing and sample ordering convenience capture DIY enthusiast and small residential builder demand, though tactile surface evaluation limits category penetration for premium collections.
- Wholesalers:Volume aggregation and inventory holding serve commercial contractor procurement with project-scale logistics.
- Home Improvement Centers:Mass-market accessibility and economy-tier positioning concentrate residential renovation volume.
- Direct Sales:Manufacturer-to-contractor relationships eliminate margin extraction for institutional buyers with verified low-emission kiln sourcing.
Specialty stores retain specification authority; direct sales are gaining share fastest as carbon disclosure requirements favor traceable supply chains.
Customer Type:
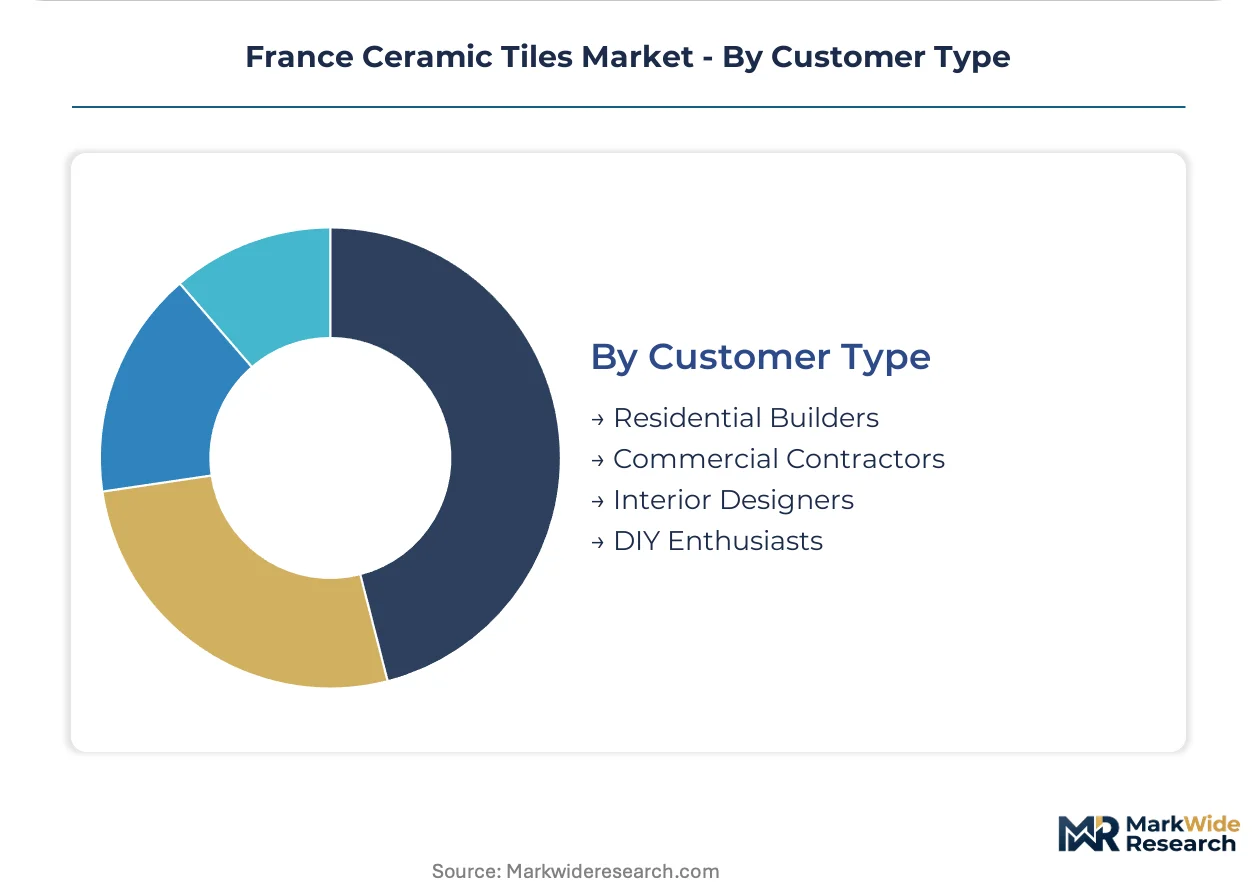
Customer segmentation exposes where decision authority concentrates, with procurement platform consolidation and extended producer responsibility schemes reshaping stakeholder relationships.
- Residential Builders:Volume procurement across multi-unit developments with standardized finish specifications. ANSM-enforced construction waste recycling mandates are creating compliance differentiation for producers with closed-loop grinding infrastructure.
- Commercial Contractors:Public procurement frameworks and CE marking plus carbon labeling requirements dominate specification authority. Biomass or electric kiln investments secure preferential listing, while documentation friction constrains imported supply.
- Interior Designers:Aesthetic curation and surface material specification authority concentrate in Lyon and Bordeaux luxury residential markets.
- DIY Enthusiasts:Cost sensitivity and online channel preference concentrate in economy-tier glazed wall tile demand.
Commercial contractors absorb the bulk of regulatory compliance attention; interior designers are expanding most quickly as design-led collection differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clay deposits in the Massif Central and kaolin reserves near Limoges anchor France's ceramic tile manufacturing geography, with finished goods distribution radiating from Rhône-Alpes production clusters toward Parisian renovation markets and Mediterranean coastal demand.
Île-de-France
Parisian residential stock renewal drives large-format porcelain specification for flooring and facade systems in heritage building conversions. ANSM-enforced extended producer responsibility schemes mandate construction waste recycling infrastructure for renovation debris. Saint-Gobain's distribution network anchors supply chain throughput across the metropolitan corridor.
Auvergne-Rhône-Alpes
Lyon-based hospitality developments and office conversions absorb technical porcelain output from regional kiln capacity. CE marking under the EU Construction Products Regulation governs slip resistance declarations for commercial flooring applications. Design studios in Lyon negotiate direct mill relationships, bypassing traditional tile showrooms for large-format specification.
Provence-Alpes-Côte d'Azur
Mediterranean climate second-home refurbishment generates demand for frost-resistant porcelain in outdoor terraces and pool surrounds. REACH restrictions on heavy metal content in glazes constrain formulation flexibility for decorative collections. Groupe Cerabati sustains regional manufacturing presence, competing on proximity to coastal renovation markets.
Hauts-de-France
Cross-border trade flows from Belgian and Dutch distribution hubs penetrate northern renovation markets with economy-tier glazed wall tile. EU Green Deal carbon border adjustment documentation creates friction for imported supply entering French procurement frameworks. Lille anchors logistics consolidation for Benelux-sourced ceramic products.
Nouvelle-Aquitaine
Bordeaux luxury residential fit-outs specify design-led collections from regional distributors. Digital inkjet decoration capabilities enable shorter production runs for customized surface aesthetics. Novoceram positions collections through local specification relationships in the southwestern residential market.
France Ceramic Tiles Market Competitive Landscape
Global majors compete with regional champions across distribution reach and compliance infrastructure, producing a tiered structure where scale-driven building materials conglomerates anchor volume throughput while specialized design houses capture premium specification. Three archetypes dominate: diversified materials groups with captive distribution networks, regional manufacturers competing on kiln proximity to end markets, and design-led specialists targeting architect-specified projects. Competitive moves concentrate on strategic partnerships with procurement platforms and capacity investments in low-emission kiln technologies ahead of tightening EU Green Deal deadlines.
Within the diversified materials tier, Saint-Gobain exemplifies the building materials ecosystem approach, anchoring large-format porcelain distribution across French retail networks through integrated logistics infrastructure. Regional manufacturers represented by Groupe Cerabati occupy positions based on manufacturing proximity to Mediterranean demand clusters. On the design-specialist vector, Novoceram sits within the premium residential specification tier, targeting differentiated collection development for Lyon and Bordeaux markets. These three archetypes illustrate how competitive positioning fragments across scale, geography, and aesthetic authority.
| Leading Market Players |
|---|
| Saint-Gobain |
| Groupe Cerabati |
| Novoceram |
| Keros Ceramica |
| Diffusion Ceramique |
| Grespania Ceramica |
| Marazzi Group |
| Porcelanosa Group |
| Desvres Company |
| Others |
Supply & Pricing Matrix
Electric kiln technology transitions are compressing cost structures for early adopters while amplifying margin pressure on gas-dependent producers, simultaneously redrawing supply concentration around biomass-powered manufacturing clusters in Spain and Italy versus French domestic capacity.
Pricing Analysis
Warranty and installation service bundling separates premium porcelain specification from unbundled economy-tier glazed wall tile transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with CE marking plus carbon labeling commanding measurable premiums in public procurement. Cost compression in standard-grade flooring is intensifying because solar-powered Spanish imports undercut French gas-fired production on energy input costs. DIY enthusiasts exhibit highest price sensitivity through online retail channels, while architect-specified commercial projects demonstrate lowest sensitivity to unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with Italian Sassuolo-based design-led collections dominating premium specification authority. Manufacturing concentration clusters in Spain, Italy, and domestic French Rhône-Alpes belt, with clay feedstock drawing from Massif Central deposits and Limoges kaolin reserves. Tariff exposure through EU Carbon Border Adjustment Mechanism documentation requirements creates friction for non-EU sourced ceramic products entering French procurement frameworks. Distribution runs through Saint-Gobain's integrated building materials network anchoring retail throughput, with direct mill relationships gaining share in Lyon-based commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's ceramic tiles sector occupies a technology-transition phase where electric and hydrogen-fired kiln methods displace legacy natural gas combustion, rewarding capital deployment into low-emission thermal infrastructure ahead of tightening EU Green Deal compliance deadlines.
For Market Incumbents: Hedge against margin erosion from Spanish solar-powered competitors by securing biomass kiln capacity in Rhône-Alpes and Provence-Alpes-Côte d'Azur manufacturing clusters. Prioritize backward integration into clay beneficiation infrastructure near Limoges kaolin reserves to insulate feedstock costs from commodity volatility. Defensive certification investment in REACH-compliant low-toxicity glaze formulations secures preferential listing in ANSM-enforced public procurement frameworks. For New Entrants and Emerging Players: The price-point gap between premium Italian design-led collections and economy-tier Benelux imports presents white-space opportunity for mid-market porcelain specification. Target underpenetrated Mediterranean coastal renovation demand in Provence-Alpes-Côte d'Azur second-home refurbishment, where frost-resistant outdoor terrace applications lack domestic supply proximity. Establish specification relationships with Lyon-based interior design studios negotiating direct mill access for hospitality developments. For Investors and Strategic Acquirers: Exit pathways concentrate in building materials conglomerates seeking design-specialist bolt-ons to anchor premium residential specification authority. Long-term viability over the next decade hinges on compliance infrastructure for EU Green Deal carbon disclosure mandates and electric kiln engineering talent retention. Monitor ANSM enforcement intensity on extended producer responsibility recycling mandates as inflection indicator for infrastructure-heavy target attractiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Kiln Capacity Investment | Biomass and hydrogen-fired thermal infrastructure secures preferential CE marking plus carbon labeling positioning ahead of compliance deadlines. |
| Direct Mill Relationship Development | Bypassing traditional distributor networks captures specification authority from Lyon-based design studios consolidating procurement platforms. |
| Closed-Loop Grinding Infrastructure | ANSM-enforced construction waste recycling mandates create first-mover compliance advantages for circular tile reconstitution capabilities. |
| Digital Inkjet Decoration Scale-Up | Reactive pigment printing technology enables shorter production runs competing against volume imports on customization flexibility. |
| Provence-Alpes-Côte d'Azur Distribution Hub | Proximity to Mediterranean renovation markets reduces logistics costs for frost-resistant porcelain in outdoor terrace applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ceramic plant managers, Saint-Gobain distribution network directors, Lyon-based interior design studio principals, ANSM regulatory compliance officers, and commercial contractor procurement leads. Secondary validation drew from EU Construction Products Regulation documentation, REACH heavy metal restriction enforcement records, ECHA substance registration databases, and French environmental agency carbon disclosure protocols. Bottom-up capacity utilization modeling triangulated against top-down construction activity indices across Île-de-France and Auvergne-Rhône-Alpes regional clusters.
Reconciliation of production volume data streams with renovation permit applications and new-build construction starts generated segment-level demand estimates across the projection horizon. Analytical framework modeled product type segmentation by density and frost resistance specifications, application segmentation by structural load-bearing versus decorative surface requirements, distribution channel segmentation by specification authority concentration, and customer type segmentation by procurement platform consolidation patterns. CAGRs derived from installed kiln capacity expansion schedules cross-referenced with EU Green Deal compliance timeline assumptions and natural gas price trajectory sensitivities.
Underlying measurement precision varies by segment; porcelain technical specifications and CE marking compliance data carry tighter precision than mosaic heritage restoration demand estimates. Forecasts reflect documented assumptions on electrification capital deployment rates, carbon border adjustment enforcement intensity, and slip resistance certification standard harmonization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Global Steel Pipe Piles Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
North America Fabricated Metal Products Market