
 Global Awning Market | 2026-2036
Global Awning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Awning Market Foresight
Residential property owners is collapsing as the dominant demand source while hospitality venue procurement contracts sharply. markilux leverages its German engineering heritage to dominate premium retractable systems across European capitals. Warema Renkhoff sustains manufacturing scale through captive textile production and automated assembly lines. SunSetter Products anchors North American distribution through direct-to-consumer channels and dealer networks.
An awning is a secondary covering attached to the exterior wall of a building, typically comprising aluminum frames, acrylic or polyester fabrics, and optional motorized retraction mechanisms operating at 24V or 120V, designed to reduce solar heat gain by blocking direct sunlight over windows, doors, or decks. Retractable awnings now lead product type demand as consumers prioritize seasonal flexibility and storm protection, while motorized variants capture the fastest growth trajectory driven by smart-home integration. Aluminum frames occupy the largest material share due to corrosion resistance and structural longevity, though acrylic fabric commands premium margin pools through solution-dyed colorfastness and ten-year warranties.
FDA regulates flame-retardant fabric treatments for commercial hospitality applications in the United States, while EU Green Deal building-efficiency targets and REACH chemical compliance reshape material specifications across European supply chains. China's GB standards for outdoor product safety and Japan's METI energy-efficiency labeling for building envelope components further fragment certification requirements for exporters. Stakeholders must monitor regulatory divergence between fire-safety standards and sustainability mandates as compliance costs increasingly determine market access and product positioning.
Market Dynamics
EU Green Deal building-efficiency mandates are compressing material upgrade cycles across European supply chains, forcing manufacturers to requalify fabric chemistries and frame alloys ahead of enforcement deadlines.
Growth Catalysts
- EU Green Deal retrofit mandates:Building-efficiency targets in Germany, France, and Italy are accelerating replacement demand for thermally performant awning systems in residential and commercial envelopes.
- Smart-home integration:Motorized retractable awnings with 24V and 120V automation are capturing preference among residential property owners seeking app-controlled shading and weather-responsive retraction.
- Acrylic fabric performance:Solution-dyed acrylic textiles with ten-year colorfastness warranties are displacing polyester in premium residential installations across Mediterranean climates.
Market Restraints
- Aluminum input volatility:Primary aluminum price swings tied to energy costs in Chinese smelters are compressing margin stability for frame manufacturers.
- REACH compliance friction:ECHA chemical restrictions on flame-retardant treatments are forcing reformulation cycles that extend product development timelines by 12-18 months.
- Fixed-frame substitution:Permanent pergola systems with integrated louvers are capturing deck-shading demand that retractable awnings previously served.
Strategic Opportunities
- US direct-to-consumer channels:Dealer network bypass models are opening addressable market expansion in suburban residential segments previously served only through contractor intermediaries.
- Japan METI energy labeling:Building envelope efficiency certification is creating specification pull for high-performance shading systems in Tokyo and Osaka commercial retrofits.
- Solar-awning convergence:Photovoltaic fabric integration with traditional retractable mechanisms is emerging as a distinct product category for net-zero building projects.
Industry Challenges
- Automation engineering talent:Shortages of 24V motor integration specialists and smart-home protocol engineers are constraining product development velocity for motorized variants.
- Multi-jurisdiction certification:Divergent flame-retardant standards between FDA hospitality requirements, REACH chemical compliance, and GB outdoor safety protocols are fragmenting testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Awning Market |
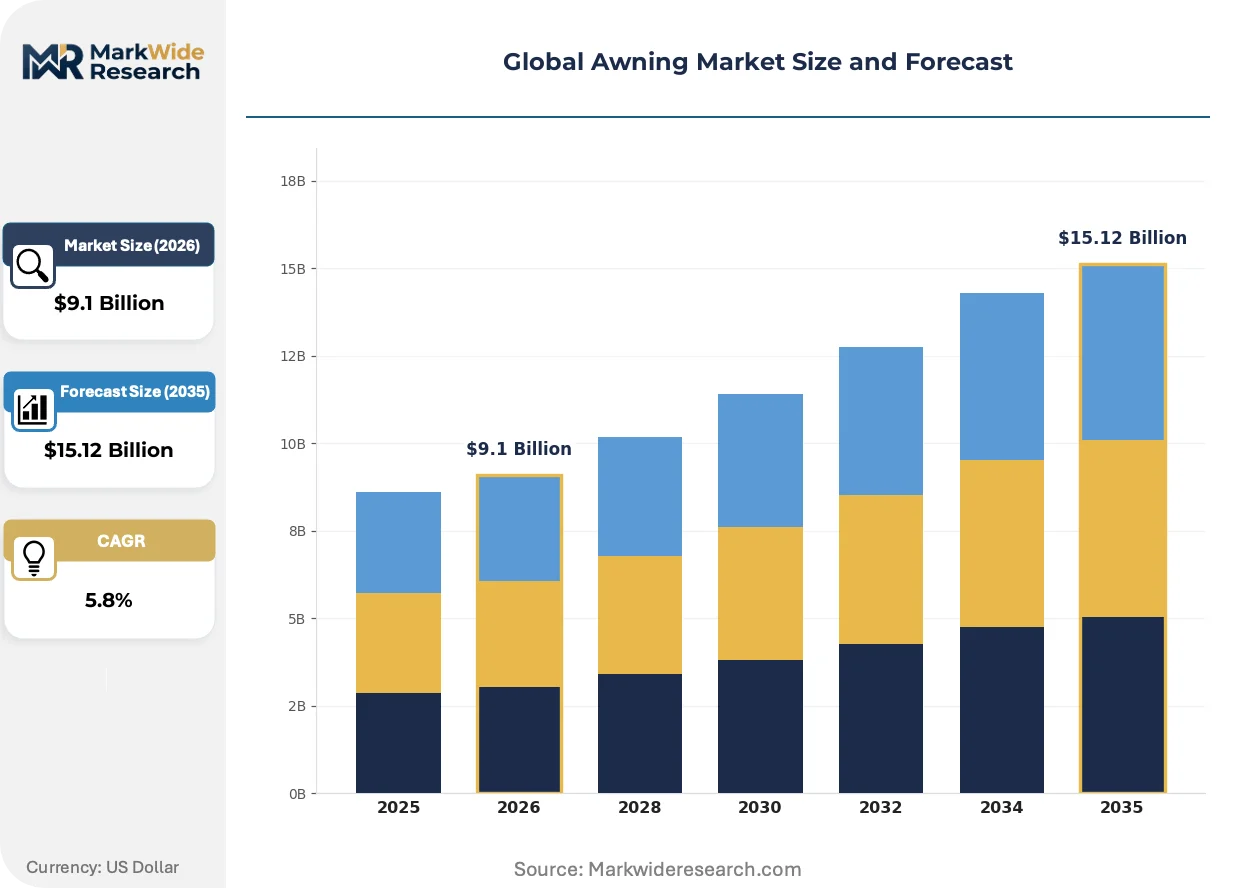
| Market Size in 2026 | $9.1 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable, Stationary, Portable, Motorized, Fixed Material: Aluminum, Steel, Acrylic Fabric, Polyester Fabric, Vinyl Application: Commercial Buildings, Hospitality Venues, Educational Institutions, Public Spaces, Residential Properties Installation Type: Wall Mounted, Roof Mounted, Freestanding, Ceiling Mounted, Balcony Mounted |
| Companies Covered | SunSetter Products, markilux, Warema Renkhoff, Somfy Systems, KE Durasol Awnings, Sunesta, Advanced Design Awnings & Signs, Carroll Awning Company, Eide Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Awning Market Shifts & Advancements
Fabric chemistry, motor architecture, and distribution architecture are undergoing simultaneous recalibration as regulatory pressure and connectivity expectations reshape product specifications.
Sensor-integrated wind and sun tracking systems are miniaturizing detection hardware into 24V motorized awnings, enabling automated deployment without manual intervention. Residential property owners in coastal Germany and Pacific Northwest North America are specifying these systems at accelerating rates. The technology is miniaturizing control modules to the point where retrofit installation no longer requires electrical panel upgrades, expanding the addressable installed base.
REACH chemical compliance deadlines are forcing fabric suppliers to eliminate legacy halogenated flame retardants from acrylic coatings used in commercial hospitality applications. ECHA substance restrictions are triggering reformulation investments across German and Italian textile mills. Commercial building specifiers are responding by demanding third-party certified alternatives ahead of mandatory phase-outs.
Direct-to-consumer digital configuration tools are displacing traditional dealer-led sales processes for standard-size residential retractable systems. SunSetter Products and comparable distributors are capturing suburban homeowner demand through online measurement guides and video installation support. This channel migration is most visible in North American markets where contractor labor shortages have extended project timelines.
Global Awning Market Segmentation
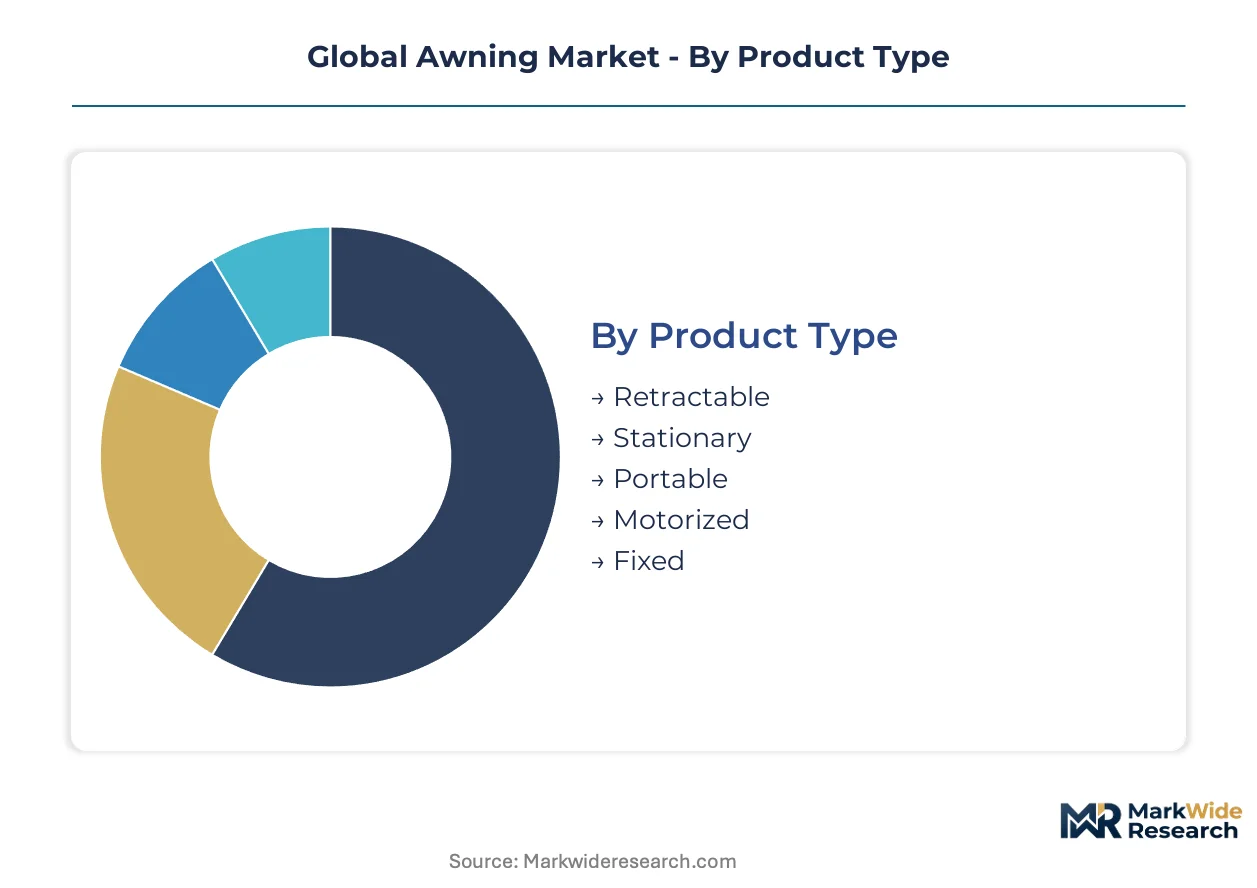
Segmentation in the awning market tracks how material specifications, mounting configurations, and end-use requirements fragment procurement patterns. Product differentiation across motorized versus fixed systems and residential versus commercial applications creates distinct margin pools that manufacturers navigate through specialized engineering and distribution strategies.
Product Type:
Margin pools concentrate in motorized retractable systems where smart-home integration commands price premiums, while fixed and stationary variants compete on installation efficiency and material cost discipline.
- Retractable:Fabric and frame assemblies deploy on lateral arms or lateral torsion systems, enabling seasonal deployment and storm retraction. Residential property owners in Germany and coastal California are specifying these systems at accelerating rates as weather-responsive automation reduces manual intervention.
- Motorized:24V and 120V drive mechanisms integrate with home automation protocols for app-controlled deployment. This segment is climbing the fastest as smart-home integration becomes standard specification in premium residential new construction across Tokyo, Munich, and Seattle.
- Stationary:Permanent frame structures with fixed fabric canopies serve commercial facades requiring constant branding visibility.
- Portable:Freestanding pop-up canopies with collapsible frames target event and temporary shade applications.
- Fixed:Rigid frame systems with permanent fabric attachment dominate budget-conscious commercial installations.
Retractable systems hold installed capacity. Motorized variants are rotating up the share rankings.
Material:
Cost tier stratification separates solution-dyed acrylic at the premium level from polyester and vinyl economy alternatives, with metal frame materials anchoring mid-tier positioning through durability claims.
- Acrylic Fabric:Solution-dyed synthetic textiles with ten-year colorfastness warranties resist UV degradation and mildew accumulation. Mediterranean climate installations across Spain, Italy, and southern France specify these fabrics exclusively for residential deck and terrace applications.
- Aluminum:Extruded alloy frames with powder-coat finishes provide corrosion resistance and structural longevity. German and Austrian manufacturers rely on this material for premium retractable systems serving EU Green Deal retrofit mandates.
- Polyester Fabric:Lower-cost woven textiles with shorter warranty periods serve price-sensitive residential segments.
- Steel:Heavier gauge frames support larger commercial span requirements in fixed installations.
- Vinyl:Laminated PVC fabrics offer waterproofing for commercial applications but sacrifice breathability.
Aluminum frames dominate volume throughput. Acrylic fabric is rotating up the share rankings.
Application:
Customer type fragmentation separates residential procurement—now expanding most quickly— from commercial building demand, where hospitality venue contraction is reshaping supplier priorities.
- Residential Properties:Single-family and multi-family dwelling installations prioritize motorized retractable systems with smart-home compatibility. Property owners in suburban Tokyo, Dallas-Fort Worth, and Sydney's North Shore are driving specification shifts toward automated weather-responsive deployment.
- Commercial Buildings:Office and retail facade installations require fire-retardant fabric certification under FDA and REACH protocols. EU Green Deal efficiency targets in Frankfurt, Milan, and Amsterdam are accelerating replacement cycles for thermally performant shading systems.
- Hospitality Venues:Restaurant and hotel terrace applications face procurement compression as venue operators defer capital expenditure.
- Educational Institutions:Campus walkway and outdoor classroom shade structures specify durable fixed-frame systems.
- Public Spaces:Municipal park and transit shelter installations prioritize vandal-resistant materials and low maintenance requirements.
Commercial buildings hold installed capacity. Residential properties are rotating up the share rankings.
Installation Type:
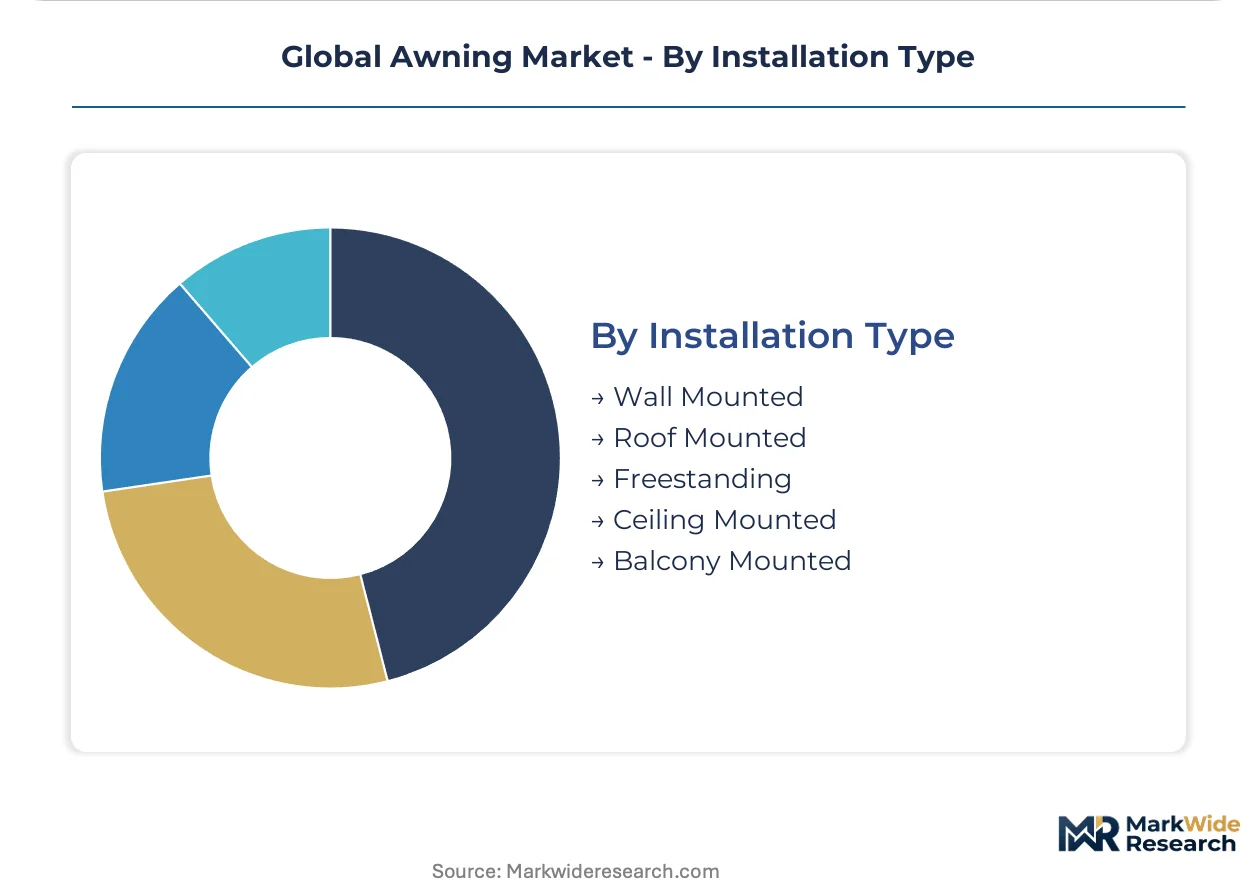
Mounting configuration determines labor cost structure and retrofit feasibility, with wall-mounted systems retaining volume leadership while balcony-mounted variants address urban density constraints.
- Wall Mounted:Bracket attachment to vertical building envelopes supports retractable and fixed systems across residential and commercial applications. This configuration dominates retrofit installations in existing building stock across Germany, Japan, and the United States.
- Balcony Mounted:Railing-integrated systems enable shade deployment without facade penetration, critical for apartment and condominium dwellers. Tokyo, Singapore, and Vancouver developers are specifying these systems in high-rise residential construction.
- Roof Mounted:Structural attachment above window lines accommodates buildings without suitable wall surfaces.
- Freestanding:Ground-anchored frame systems serve poolside and garden applications without building connection.
- Ceiling Mounted:Under-soffit attachment provides recessed aesthetic integration in contemporary architecture.
Wall-mounted systems hold installed capacity. Balcony-mounted configurations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters and North American distribution networks anchor supply-side capacity for retractable shading systems. Manufacturing concentrates in Baden-Württemberg and Bavaria, where EU Green Deal retrofit mandates accelerate specification cycles for thermally performant envelopes.
Germany
Baden-Württemberg manufacturers drive premium retractable system output for EU Green Deal building-efficiency retrofits. ECHA REACH chemical compliance deadlines force fabric chemistry reformulation across Stuttgart and Karlsruhe textile mills. markilux and Warema Renkhoff anchor engineering clusters in Ravensburg and Würzburg, sustaining automated assembly scale for motorized variants.
United States
Suburban residential property owners in Dallas-Fort Worth and Pacific Northwest metro areas specify smart-home-integrated motorized systems. FDA flame-retardant fabric regulations govern commercial hospitality applications in California and Florida. SunSetter Products anchors direct-to-consumer distribution through Massachusetts-based dealer networks and digital configuration platforms.
Japan
Tokyo and Osaka commercial retrofits pull high-performance shading under METI energy-efficiency labeling for building envelope components. Kanto region developers specify balcony-mounted systems for high-rise residential density constraints. Nagoya manufacturing clusters produce 24V motor integration modules for automated weather-responsive deployment.
China
Guangdong and Zhejiang fabricators supply aluminum frame extrusions and polyester textiles for export markets. GB standards for outdoor product safety reshape certification requirements for European and North American shipments. Yangtze River Delta assembly plants concentrate motorized mechanism production for smart-home protocol integration.
Australia
Sydney's North Shore and Melbourne residential markets prioritize solution-dyed acrylic fabrics with ten-year warranties for UV-intensive Mediterranean-equivalent climates. TGA-equivalent building product safety standards govern commercial installation specifications. Queensland distributors capture coastal storm-protection demand for retractable systems with wind-sensor automation.
Global Awning Market Competitive Landscape
Concentration sits with German engineering heritage players and North American direct-to-consumer specialists, creating a bifurcated structure across premium and volume tiers. Mid-scale fabricators compete on installation efficiency and regional service density. Two strategic archetypes dominate: vertically integrated manufacturers with captive textile production, and distribution-anchored brands bypassing contractor intermediaries. Competitive moves center on smart-home protocol licensing and automated assembly line expansion.
Among German heritage manufacturers, markilux GmbH and Warema Renkhoff SE occupy positions exemplifying engineering-led premium positioning through Baden-Württemberg and Bavaria production clusters. SunSetter Products LLC represents the direct-to-consumer archetype, anchoring North American volume through Massachusetts-based distribution infrastructure and digital sales channel development. These three entities illustrate the geographic and strategic bifurcation structuring competitive dynamics.
| Leading Market Players |
|---|
| SunSetter Products |
| markilux |
| Warema Renkhoff |
| Somfy Systems |
| KE Durasol Awnings |
| Sunesta |
| Advanced Design Awnings & Signs |
| Carroll Awning Company |
| Eide Industries |
| Others |
Supply & Pricing Matrix
Automated assembly line utilization rates above eighty percent at Baden-Württemberg manufacturing clusters create scale economies that compress unit economics for motorized retractable systems while establishing price floors that smaller fabricators cannot match. This concentration of production capacity in German engineering centers directly shapes margin structures across premium and volume tiers, with captive textile production further insulating integrated manufacturers from acrylic fabric cost volatility.
Pricing Analysis
Volume-discount tiering structures separate project-scale commercial procurement from single-unit residential transactions, with motorized variants commanding premium positioning through smart-home protocol licensing. Certification grade under EU Green Deal efficiency standards and REACH chemical compliance tiers drive price differentiation between German-manufactured and import alternatives. Cost compression in standard fixed-frame segments is intensifying because aluminum input volatility from Chinese smelter energy costs transmits directly to frame manufacturers. Hospitality venue procurement shows highest price sensitivity as capital expenditure deferrals accelerate, while residential property owners in premium segments demonstrate lowest sensitivity to motorized automation premiums.
Supply Chain Analysis
Yangtze River Delta port congestion periodically chokes aluminum extrusion and polyester textile shipments bound for European and North American assembly plants. Manufacturing capacity concentrates in Germany, China, and the United States, with Baden-Württemberg and Bavaria anchoring premium motorized system output while Guangdong and Zhejiang feed mid-tier component demand. Raw material dependencies rest on primary aluminum from Chinese smelters, solution-dyed acrylic yarn from European textile mills, and 24V motor modules from Japanese electronics suppliers. Single-source vulnerability in Chinese aluminum supply creates structural exposure to energy-cost-driven price spikes. Distribution runs through direct-to-consumer digital platforms and contractor dealer networks in North America, with specification-driven project channels dominating European commercial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Awning Market is recovering from hospitality procurement contraction as residential property owner demand accelerates through EU Green Deal retrofit mandates and smart-home integration cycles.
For Market Incumbents: Compound defensive positioning by deepening captive textile production capacity in Ravensburg and Karlsruhe manufacturing clusters to offset REACH compliance-driven reformulation costs. Extend automated assembly scale for 24V motorized variants to capture specification pull from Tokyo and Munich premium residential construction. Fixed-frame substitution by integrated louver pergola systems represents the primary demand threat requiring product portfolio response. For New Entrants and Emerging Players: Differentiate on balcony-mounted system engineering for high-rise residential density constraints in Singapore, Vancouver, and Tokyo where incumbent coverage remains thin. Target direct-to-consumer digital configuration tools for suburban North American residential segments previously served only through contractor intermediaries. Deploy video installation support and online measurement guides as the primary go-to-market angle to bypass established dealer network barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive acrylic textile production and automated motorized assembly lines over pure distribution plays. Long-term viability over the next decade hinges on smart-home protocol licensing depth and EU regulatory compliance infrastructure rather than geographic expansion alone. Watch solar-awning convergence product development velocity as the signal indicating which engineering clusters will capture net-zero building specification pull.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Textile Production | Captive yarn supply insulates margin stability from REACH-driven reformulation cycles at Stuttgart mills. |
| Smart-Home Protocol Licensing Agreement | Home automation integration partnerships with platform providers secure specification priority in Munich and Seattle new construction. |
| Direct-to-Consumer Digital Platform Launch | Online configuration tools bypass contractor labor shortages extending project timelines in Dallas-Fort Worth suburbs. |
| Photovoltaic Fabric Product Development | Solar-awning convergence captures net-zero building envelope demand from EU Green Deal retrofit mandates. |
| Balcony-Mounted System Engineering Expansion | Railing-integrated designs address high-rise density constraints in Tokyo and Vancouver residential towers. |
Research Methodology
Operator-level perspectives from awning manufacturing plant managers, residential property developer procurement leads, commercial building facade specification consultants, and smart-home integration specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through EU ECHA regulatory filings, METI energy-efficiency labeling databases, customs trade data on aluminum extrusion shipments, and SEC disclosures from publicly traded building products distributors. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the projection horizon.
Sensitivity analysis around aluminum price volatility scenarios and REACH compliance timeline shifts informed the forecast framework. Segmentation dimensions modeled include product type, material specification, application category, and installation configuration across the analysis window. CAGRs were derived from installed base replacement cycles, new construction permit data, and technology adoption curve fitting. Motorization penetration rates and smart-home protocol integration velocity served as industry-specific forecast inputs alongside EU Green Deal enforcement phase schedules.
Material uncertainties — regulatory deadline acceleration, primary aluminum supply disruptions, and fixed-frame substitution by integrated pergola systems — sit outside the modeled envelope. Forecasts reflect assumptions about residential property owner preference stability and commercial hospitality venue capital expenditure recovery trajectories. Practitioners should keep alternative scenarios live as ECHA chemical restriction scope and smart-home platform consolidation dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
US Windows Market