
 Wood House Frame Market | 2026-2036
Wood House Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Wood House Frame Market Analytics
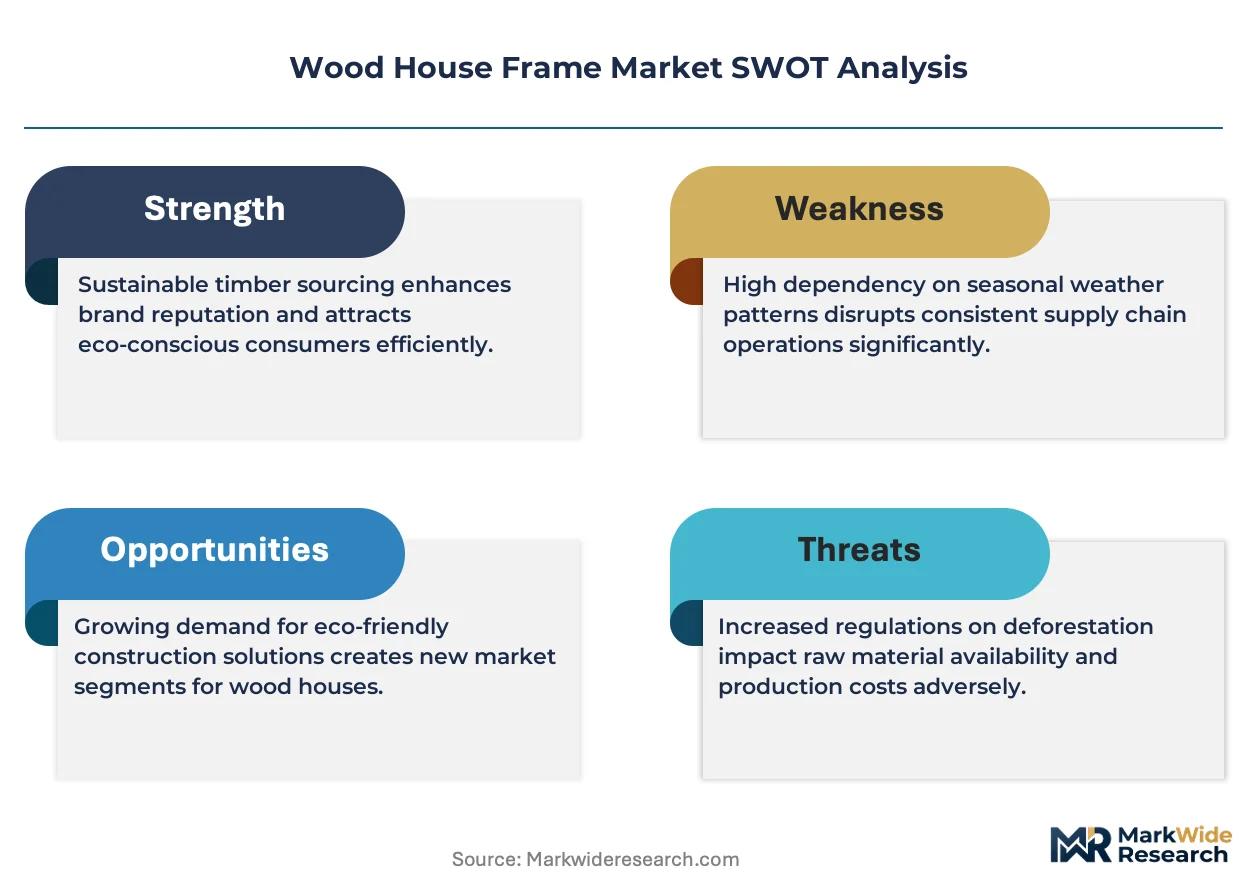
Subscription-based structural design software is hardening into a core revenue layer for timber frame suppliers, shifting one-time material sales toward recurring digital-service contracts. Weyerhaeuser Company leverages its vertically integrated fiber supply to anchor prefabricated wall-panel programs across the southeastern United States. Stora Enso Oyj competes through controlled Nordic spruce sourcing and certified mass-timber engineering capacity. Louisiana-Pacific Corporation specializes in oriented strand board sheathing products that dominate wind-load-rated assemblies in hurricane corridors.
Wood house frames are structural skeletons fabricated from dimensional lumber, engineered wood products, or mass timber assemblies, typically engineered to withstand gravity and lateral loads per IRC or IBC standards. Their primary commercial purpose is to create cost-efficient, code-compliant building envelopes that sequester atmospheric carbon within long-lived building stock. Framing lumber still occupies the largest volume share across single-family applications, though engineered wood is capturing margin pools in multi-family and passive-house segments where deflection limits and thermal bridging rules tighten. Modular installation is growing fastest as factory automation reduces on-site labor exposure and compresses construction schedules for residential builders.
The International Code Council publishes structural provisions that directly determine allowable heights and fire-resistance ratings for wood-frame construction across US jurisdictions. EPA emissions standards for composite wood products, derived from CARB ATCM and formaldehyde labeling rules, shape panel-product market access and manufacturing compliance burdens. EMA and national building institutes within Europe enforce CE-marked performance declarations for structural timber. Stakeholders must monitor whether evolving carbon-accounting frameworks will credit biogenic carbon storage sufficiently to offset concrete and steel in mid-rise specification decisions.
Market Dynamics
Platform-framed construction is hardening into the dominant structural paradigm across North American residential development, compressing traditional stick-built timelines and concentrating specification power among engineered-wood suppliers with certified prefabrication capacity.
Growth Catalysts
- EU Green Deal embodied-carbon regulations:The framework mandates whole-life carbon accounting for commercial buildings, redirecting mid-rise specification toward mass timber systems that sequester biogenic carbon.
- Prefabrication hub concentration in the US Pacific Northwest:Integrated softwood supply chains serving factory-built wall-panel operations compress construction schedules for regional residential builders.
- Engineered wood products:Cross-laminated timber and laminated veneer lumber gain structural code acceptance for taller wood-frame construction under International Building Council provisions.
Market Restraints
- Softwood lumber price volatility:Spot-market fluctuations in SPF and SYP species create margin compression for unhedged framing contractors.
- Formaldehyde emissions compliance:EPA standards derived from CARB ATCM impose labeling and testing burdens on oriented strand board and medium-density fiberboard manufacturers.
- Concrete and steel substitution threat:Mid-rise developers in seismic zones retain preference for reinforced concrete moment frames despite mass timber code expansion.
Strategic Opportunities
- Passive-house thermal bridging rules:European and North American energy codes tighten deflection limits, opening specification for engineered I-joists and insulated headers in high-performance envelopes.
- Subscription-based structural design software:Timber frame suppliers convert one-time material sales into recurring digital-service contracts with residential builders.
- Modular installation channel expansion:Factory automation reduces on-site labor exposure, creating new revenue pools for vertically integrated panel producers serving multifamily developers.
Industry Challenges
- Mass timber fire-resistance certification timelines:Extended testing protocols for tall wood buildings delay project approvals in jurisdictions with conservative building officials.
- Skilled truss technician shortage:Factory automation requires operators trained in CNC cutting and robotic assembly, creating recruitment bottlenecks for prefabrication hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood House Frame Market |
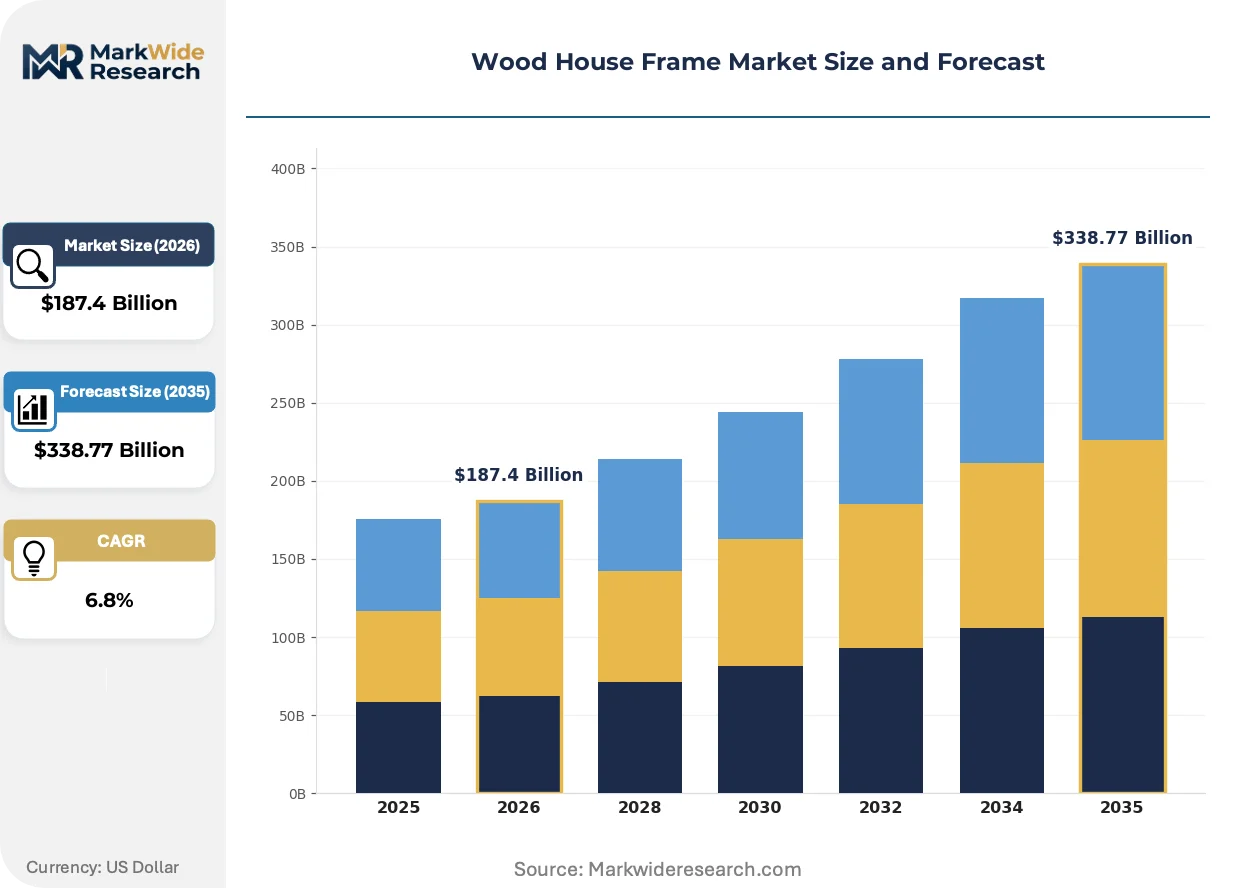
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Framing Lumber, Engineered Wood, Plywood, Oriented Strand Board End User: Residential Builders, Commercial Constructors, DIY Enthusiasts, Architects Installation Type: New Construction, Renovation, Pre-fabricated, Modular Application: Single-family Homes, Multi-family Units, Light Commercial, Passive Houses |
| Companies Covered | Canfor Corporation, Stora Enso Oyj, Weyerhaeuser Company, Hamill Creek Timber Homes, Interfor Corporation, West Fraser Timber Co. Ltd, Louisiana-Pacific Corporation, Norbord Inc., Boise Cascade Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood House Frame Market Evolving Landscape
Digital fabrication and regulatory carbon accounting are converging to restructure how structural timber moves from forest to frame, with software-enabled prefabrication overtaking site-built methods in volume-sensitive segments.
Cross-laminated timber is overtaking conventional steel-reinforced concrete in mid-rise commercial podiums. Architects specify five-ply and seven-ply CLT panels for gravity and lateral load resistance. European and Canadian manufacturers expand press capacity to serve US developers pursuing carbon-neutral certification.
CE-marked performance declarations under EMA and national building institute frameworks now govern structural timber market access across European Union member states. Manufacturers must submit declared values for bending strength and stiffness to notified bodies. Nordic suppliers leverage certified spruce sourcing to capture specification in German and French low-rise commercial projects.
Residential builders compress procurement cycles through direct factory relationships that bypass traditional lumberyard distribution. Large multifamily developers in the southeastern United States negotiate wall-panel programs with integrated fiber suppliers. This channel shift concentrates purchasing power among prefabrication specialists with captive softwood supply.
Wood House Frame Market Segmentation
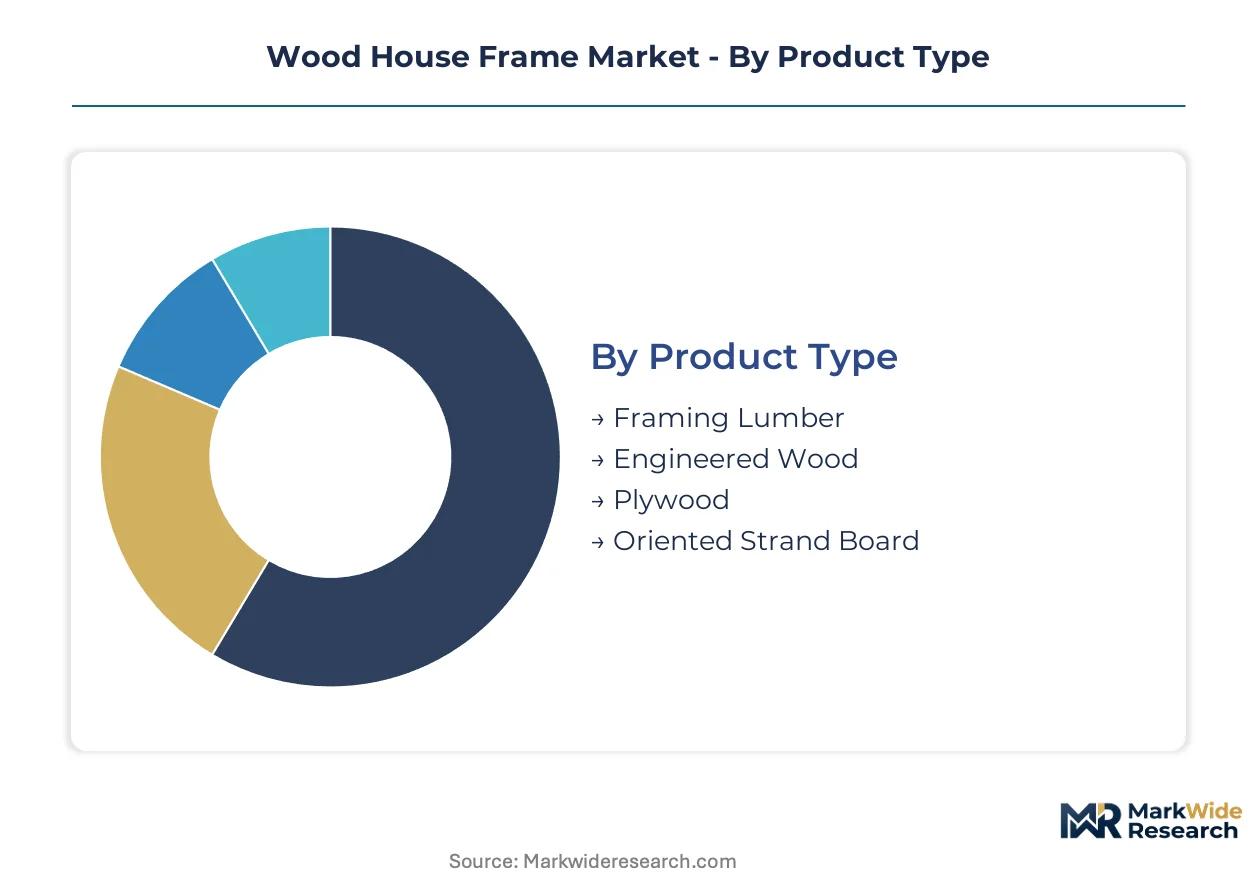
Wood house frame suppliers configure product portfolios around structural code requirements, end-user procurement scale, and factory automation readiness. Segmentation reveals where engineered wood commands margin premiums versus where commodity lumber retains volume dominance.
Product Type:
Material selection hinges on load-bearing specifications and thermal performance targets.
- Framing Lumber:Dimensional softwood studs and joists cut to IRC-standard lengths. Single-family builders in the United States Pacific Northwest specify SPF and SYP grades for platform-framed walls where cost efficiency outweighs engineered alternatives.
- Engineered Wood:Laminated veneer lumber and I-joists fabricated under controlled moisture conditions. Multi-family developers in passive-house corridors specify these for reduced thermal bridging and tighter deflection limits under stringent energy codes.
- Plywood:Cross-banded veneer panels rated for shear resistance in roof and floor diaphragms.
- Oriented Strand Board:Flake-based structural panels dominating wind-load-rated sheathing in hurricane corridors.
Volume sits with Framing Lumber; growth tilts toward Engineered Wood.
End User:
Procurement scale and specification authority determine channel access and pricing leverage.
- Residential Builders:Production homebuilders and custom contractors purchasing dimensional lumber and prefabricated assemblies in volume. Large southeastern US developers negotiate direct wall-panel programs with integrated fiber suppliers, bypassing traditional distribution.
- Commercial Constructors:Mid-rise developers specifying mass timber for carbon-neutral certification. EU Green Deal embodied-carbon regulations redirect their specification toward CLT and glulam systems in German and French low-rise commercial projects.
- DIY Enthusiasts:Small-lot purchasers through retail lumberyards for renovation and accessory structure projects.
- Architects:Design professionals influencing specification through structural software subscriptions and certified mass-timber engineering partnerships.
Revenue concentrates among Residential Builders; specification authority is shifting toward Commercial Constructors.
Installation Type:
Project delivery method determines labor exposure, schedule compression, and factory automation penetration.
- New Construction:Ground-up framing where site-built methods still dominate single-family detached housing. Platform-framed construction hardens into the structural paradigm across North American residential development.
- Pre-fabricated:Factory-built wall and roof panels with CNC-cut openings and pre-installed sheathing. Prefabrication hub concentration in the US Pacific Northwest compresses construction schedules through integrated softwood supply chains.
- Renovation:Structural modifications to existing buildings requiring selective demolition and engineered beam insertion.
- Modular:Volumetric units fully finished in factory conditions. Factory automation reduces on-site labor exposure, creating new revenue pools for vertically integrated panel producers serving multifamily developers.
Project starts favor New Construction; factory throughput is expanding most quickly in Pre-fabricated and Modular channels.
Application:
Building typology dictates fire-resistance requirements, height limitations, and carbon-accounting rigor.
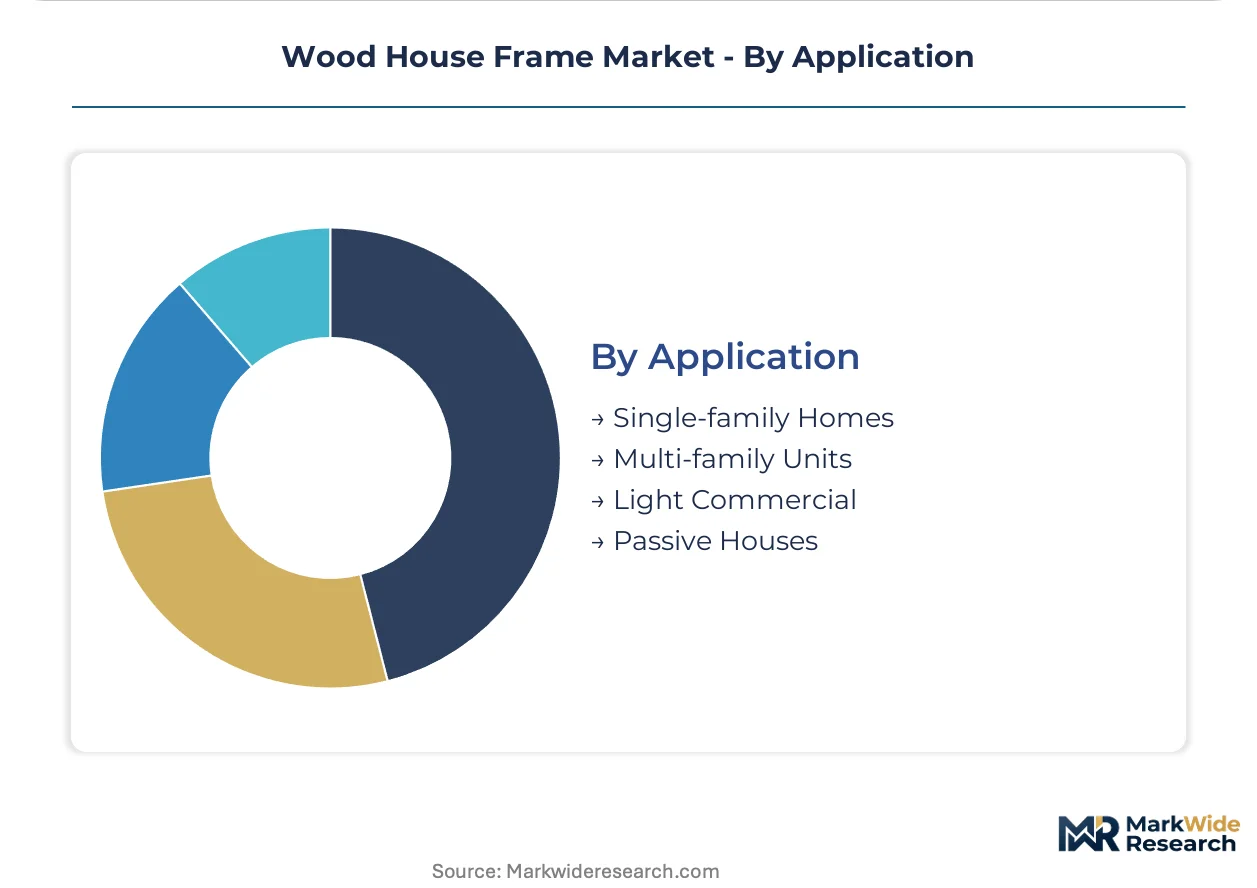
- Single-family Homes:Detached and attached dwellings under three stories governed by IRC provisions. Framing lumber occupies the largest volume share across this application.
- Passive Houses:Ultra-low-energy buildings where thermal bridging rules tighten deflection limits. European and North American energy codes open specification for engineered I-joists and insulated headers in high-performance envelopes.
- Multi-family Units:Mid-rise structures five to twelve stories where mass timber gains code acceptance under International Building Council provisions.
- Light Commercial:Retail and office podiums under four stories where cost pressures sustain conventional steel and concrete in seismic zones.
Unit volume concentrates in Single-family Homes; steepest expansion trajectory appears in Passive Houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portland anchors North American prefabrication capacity, where integrated softwood supply chains feed automated wall-panel factories serving regional residential builders.
United States
Platform-framed construction dominates single-family development across the Southeast and Pacific Northwest. EPA emissions standards derived from CARB ATCM impose labeling burdens on oriented strand board manufacturers. Prefabrication hubs in Oregon and Washington compress construction schedules through direct mill-to-factory fiber flows.
Canada
Mass timber engineering capacity concentrates in British Columbia and Quebec as developers pursue carbon-neutral certification. CSA standards and provincial building codes govern structural timber performance declarations. Vancouver and Montreal anchor cross-laminated timber manufacturing clusters serving US mid-rise markets.
Germany
Passive-house thermal bridging rules tighten specification for engineered I-joists in low-rise commercial envelopes. CE-marked performance declarations under EU Green Deal frameworks redirect procurement toward certified spruce systems. Bavarian and Baden-Württemberg fabricators supply German and French multi-family developers.
Sweden
Nordic spruce sourcing commands premium positioning in German and UK specification markets. Boverket building regulations enforce stringent energy performance standards for timber-frame residential construction. Stockholm and Gothenburg anchor engineered wood research clusters developing robotic prefabrication systems.
Japan
Seismic-resistant platform framing gains code acceptance for mid-rise residential development under revised Building Standard Law provisions. METI promotes mass timber adoption through carbon-storage credits in building certification schemes. Nagoya and Osaka prefectures concentrate laminated veneer lumber manufacturing for domestic and export markets.
Wood House Frame Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure. Integrated forest-products companies control fiber supply and captive prefabrication capacity, while specialized engineering firms license structural software and certification services. Three archetypes dominate: vertically integrated timberland owners, engineered-wood technology licensors, and regional panel fabricators with automated cutting lines. Competitive moves concentrate on backward integration into fiber supply and strategic partnerships with residential developers for direct procurement channels.
Among North American timberland owners, Weyerhaeuser Company and Louisiana-Pacific Corporation exemplify the integrated-fiber archetype, anchoring prefabrication programs through captive softwood supply. Stora Enso Oyj represents European mass-timber engineering capacity, occupying a position shaped by controlled Nordic spruce sourcing and CE-marked certification authority.
| Leading Market Players |
|---|
| Canfor Corporation |
| Stora Enso Oyj |
| Weyerhaeuser Company |
| Hamill Creek Timber Homes |
| Interfor Corporation |
| West Fraser Timber Co. Ltd |
| Louisiana-Pacific Corporation |
| Norbord Inc. |
| Boise Cascade Company |
| Others |
Value Network & Pricing Analysis
Family-owned Pacific Northwest timberland operators anchor fiber supply for prefabrication hubs, translating long-term stumpage contracts into pricing discipline that resists spot-market volatility. Their captive mill-to-factory relationships compress procurement cycles for residential builders while insulating margins from commodity lumber swings.
Pricing Analysis
Throughput-based pricing anchors framing lumber contracts, with volume commitments securing preferential rates against spot-market exposure. Three-tier pricing structure across premium, standard, and economy levels separates certified mass-timber systems from commodity dimensional lumber and utility-grade sheathing. Cost compression in standard-grade SPF studs is intensifying because unhedged contractors face margin squeeze during price spikes. DIY enthusiasts through retail lumberyards exhibit highest price sensitivity, while commercial constructors pursuing carbon-neutral certification absorb premiums for engineered I-joists and CLT panels.
Supply Chain Analysis
Single-source vulnerability sits with British Columbia coastal sawmills feeding US Pacific Northwest prefabrication hubs. Fiber supply draws from Canada, the United States, and Sweden, with Nordic spruce commanding premium positioning in German specification markets. Structural panel production rests on oriented strand board flake supply, SPF dimensional lumber, and adhesive resin systems. Tariff exposure on Canadian softwood imports creates margin pressure for cross-border distributors. Distribution runs through direct mill-to-factory channels for large developers, bypassing traditional lumberyard intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA formaldehyde emissions standards derived from CARB ATCM erect barrier-to-entry moats for certified panel manufacturers.
For Market Incumbents: Lock in prefabrication capacity through backward integration into Pacific Northwest fiber supply, securing captive mill-to-factory flows that compress competitor delivery timelines. Add robotic cutting and CNC assembly capacity in Oregon and Washington to address skilled truss technician shortages threatening throughput expansion. Defend against concrete and steel substitution in seismic zones by accelerating mass timber fire-resistance certification with conservative building officials. For New Entrants and Emerging Players: Passive-house retrofit contractors represent an underserved buyer archetype seeking engineered I-joists and insulated headers for thermal bridge elimination in existing envelopes. White-space concentration appears in southeastern US wall-panel programs where large multifamily developers negotiate direct procurement outside traditional distribution. Target modular installation channels serving multifamily developers through factory automation partnerships that reduce on-site labor exposure. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional panel fabricators with automated cutting lines in the US Southeast, where lumber price volatility creates acquisition opportunities for capital-heavy consolidators. Long-term viability hinges on carbon-accounting framework evolution crediting biogenic storage sufficiently to offset concrete and steel in mid-rise specification. Watch EU Green Deal embodied-carbon regulation enforcement intensity as inflection indicator for mass timber demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Supply | Weyerhaeuser anchors prefabricated wall-panel programs through captive southeastern softwood supply. |
| Mass Timber Fire-Resistance Certification | Extended testing protocols with ICC provisions delay approvals but secure taller building code acceptance. |
| Subscription-Based Structural Design Software | Timber frame suppliers convert material sales into recurring digital-service contracts with residential builders. |
| Robotic Prefabrication System Deployment | Swedish engineered wood research clusters automate CNC cutting to address truss technician shortages. |
| CE-Marked Performance Declaration Investment | Nordic spruce suppliers capture German and French specification through certified bending strength submissions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted across timberland portfolio managers, prefabrication plant engineers, residential builder procurement directors, and structural design software developers. Bottom-up volume modeling triangulated against top-down macroeconomic indicators, with EPA emissions compliance databases and International Code Council structural provision updates providing regulatory boundary conditions.
Product-type, end-user, and installation-type dimensions were modeled at country-level granularity across the projection horizon, with engineered wood versus framing lumber splits calibrated to passive-house code adoption curves. CAGRs derived from regression analysis against construction starts and prefabrication penetration rates, incorporating softwood lumber price volatility indices and mass timber fire-resistance certification timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon-accounting framework evolution and EU Green Deal enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Rebars Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Vapor Barriers Market