
 China Oriented Strand Board Market | 2026-2036
China Oriented Strand Board Market Size, Share, and Industry Trends Forecast 2026-2036
China Oriented Strand Board Market Insights
Prefabricated construction buyers are rotating demand away from traditional plywood toward OSB as structural sheathing in modular housing projects. Luli Group leverages integrated timber supply chains across Shandong Province to secure raw material cost advantages. Jilin Forest Industry Group Co., Ltd anchors production capacity in Northeast China's forest belt, sustaining year-round log access. Guangxi Fenglin Wood Industry Group Co., Ltd specializes in decorative-grade OSB surfaces, differentiating through veneer-overlay capabilities for interior applications.
Oriented strand board consists of layered wood strands arranged in cross-oriented configurations and bonded with waterproof phenolic or MDI resin under heat and pressure, yielding panel strength comparable to plywood at lower density. The structural product type dominates volume as load-bearing wall and roof applications in residential framing specify OSB sheathing per Chinese building codes. Decorative-grade OSB posts faster growth as furniture manufacturers adopt exposed-edge tabletops and shelving units. Thickness segmentation splits between standard panels for general construction and heavy-duty grades for flooring systems in commercial builds.
China's national standardization administration enforces GB/T 4897 for particleboard and OSB structural performance, while the Ministry of Ecology and Environment monitors formaldehyde emissions under GB 18580 limits for indoor use. MIIT's green manufacturing guidelines incentivize low-emission adhesive transitions, reshaping supplier qualification thresholds for state-contracted projects. Stakeholders must track provincial building code amendments and timber import tariff shifts to anticipate raw material cost trajectories.
Market Dynamics
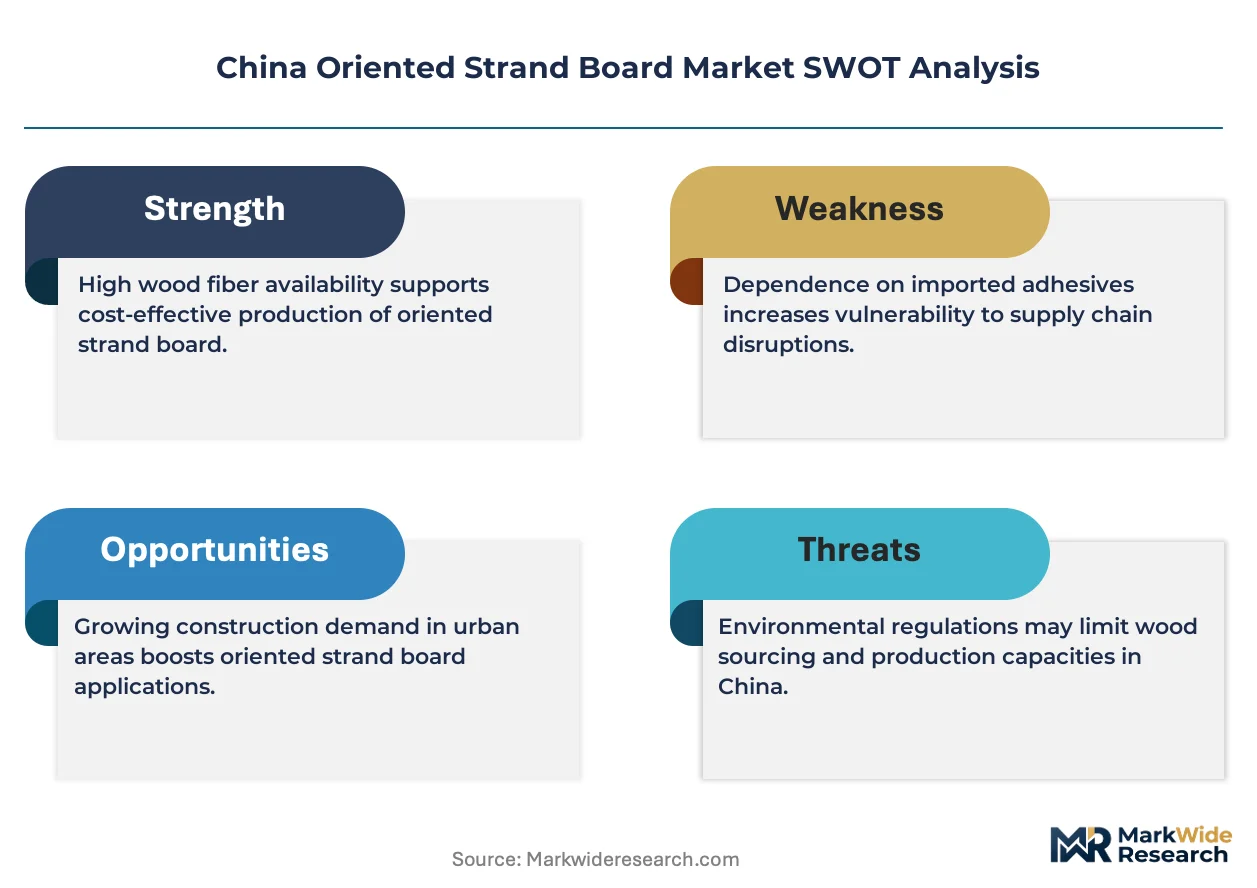
China's Oriented Strand Board sector faces a structural squeeze between tightening GB 18580 formaldehyde emission ceilings and persistent softwood log import dependency, forcing adhesive system upgrades while raw material costs fluctuate with Russian and New Zealand supply cycles.
Growth Catalysts
- Prefabricated Housing Mandates:China's Ministry of Housing and Urban-Rural Development targets 30% prefabrication share in new construction, specifying OSB sheathing for modular wall systems under updated building codes.
- GB Standards Stringency:MIIT's green manufacturing guidelines incentivize low-emission phenolic and MDI resin transitions, creating qualification advantages for compliant suppliers in state-contracted projects.
- Yangtze River Delta Clustering:Concentrated modular housing manufacturing in Jiangsu and Zhejiang provinces generates predictable, high-volume OSB procurement from integrated panel producers.
Market Restraints
- Softwood Log Import Volatility:Russian timber export restrictions and New Zealand radiata pine price swings expose Chinese OSB mills to raw material cost instability.
- Northeast China Supply Concentration:Over 40% of domestic log supply chains through Heilongjiang and Jilin provinces creates weather-dependent disruption risks and regional pricing asymmetry.
- Plywood Substitution Persistence:Traditional carpentry trades and legacy building inspectors maintain specification bias toward plywood in rural and Tier-3 city construction markets.
Strategic Opportunities
- Western China Penetration:Chengdu-Chongqing economic corridor infrastructure investment and resettlement housing programs remain underserved by engineered wood distributors.
- Decorative-Grade Furniture Adoption:Exposed-edge OSB tabletops and shelving units gain traction among millennial furniture buyers and boutique interior designers in Shanghai and Shenzhen.
- MDI Resin Technology Convergence:Polyurethane adhesive systems meeting E0 emission benchmarks open premium positioning against European-imported structural panels.
Industry Challenges
- Adhesive Chemistry Expertise Gap:Formulation chemists capable of balancing waterproof performance with GB 18580 compliance command premium wages and limited talent pools.
- Continuous Press Capex Intensity: German and Italian 8-foot continuous press installations require 150-200 million RMB outlays, freezing out mid-tier producers from scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Oriented Strand Board Market |
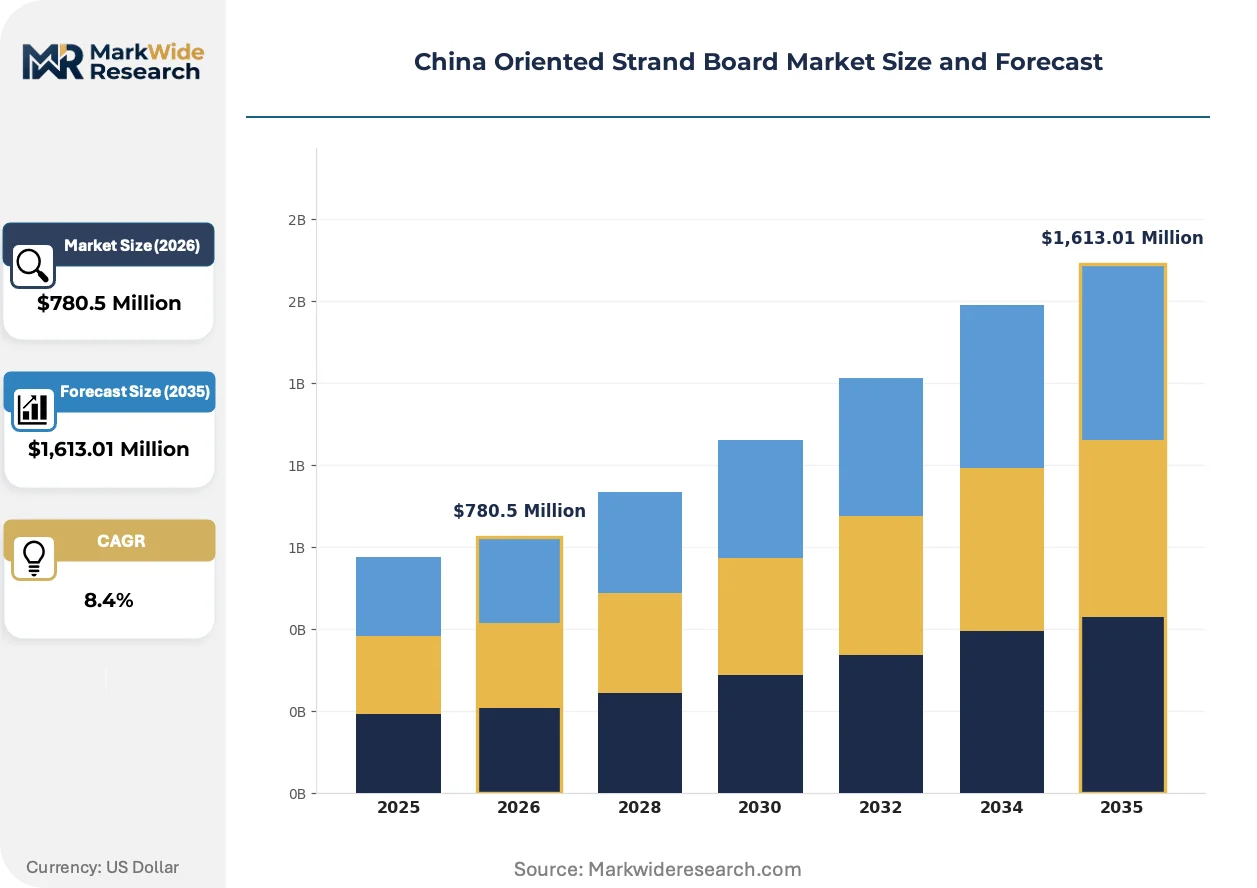
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,613.01 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural, Decorative, Particleboard, Medium Density Fiberboard End Use: Furniture, Construction, Flooring, Packaging Thickness: Standard, Heavy-duty, Lightweight, Custom Distribution Channel: Direct Sales, Retailers, Online Platforms, Wholesalers |
| Companies Covered | Luli Group, Dalian WADA International Trading Co., Ltd., Shandong Huiyu International Trade Co., Ltd, Jilin Forest Industry Group Co., Ltd, Guangxi Fenglin Wood Industry Group Co., Ltd, Yalong Wood, Nine Dragons Paper (Holdings) Limited, Shandong Lingang Wood Industry Co., Ltd, Suzhou Dongshan Precision Manufacturing Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Oriented Strand Board Market Trends and Innovations
Chinese OSB manufacturing is pivoting from commodity structural panels toward differentiated product architectures, driven by regulatory chemistry mandates and downstream buyer specification evolution in modular construction and furniture verticals.
MDI resin bonding systems are displacing traditional phenol-formaldehyde formulations in high-performance OSB production. Prefabricated housing contractors in the Yangtze River Delta specify MDI-bonded sheathing for moisture-resistant wall assemblies. This chemistry transition compresses formaldehyde emission testing cycles while raising adhesive input costs per cubic meter.
MIIT's 2024 green manufacturing guidelines enforce stricter volatile organic compound monitoring across wood-based panel facilities. Manufacturers must retrofit emission capture systems or face procurement disqualification from state-backed construction projects. Northeast China's integrated forest-product conglomerates are responding fastest due to captive chemical engineering capabilities.
Builder procurement committees now require third-party structural performance certification before specifying OSB for load-bearing applications. Traditional distributor relationships and price-based sourcing are losing ground to certified-supplier prequalification in Beijing and Guangzhou municipal housing tenders. This behavioral shift concentrates volume with mills maintaining in-house testing laboratories and SAMR-recognized quality management systems.
China Oriented Strand Board Market Segmentation
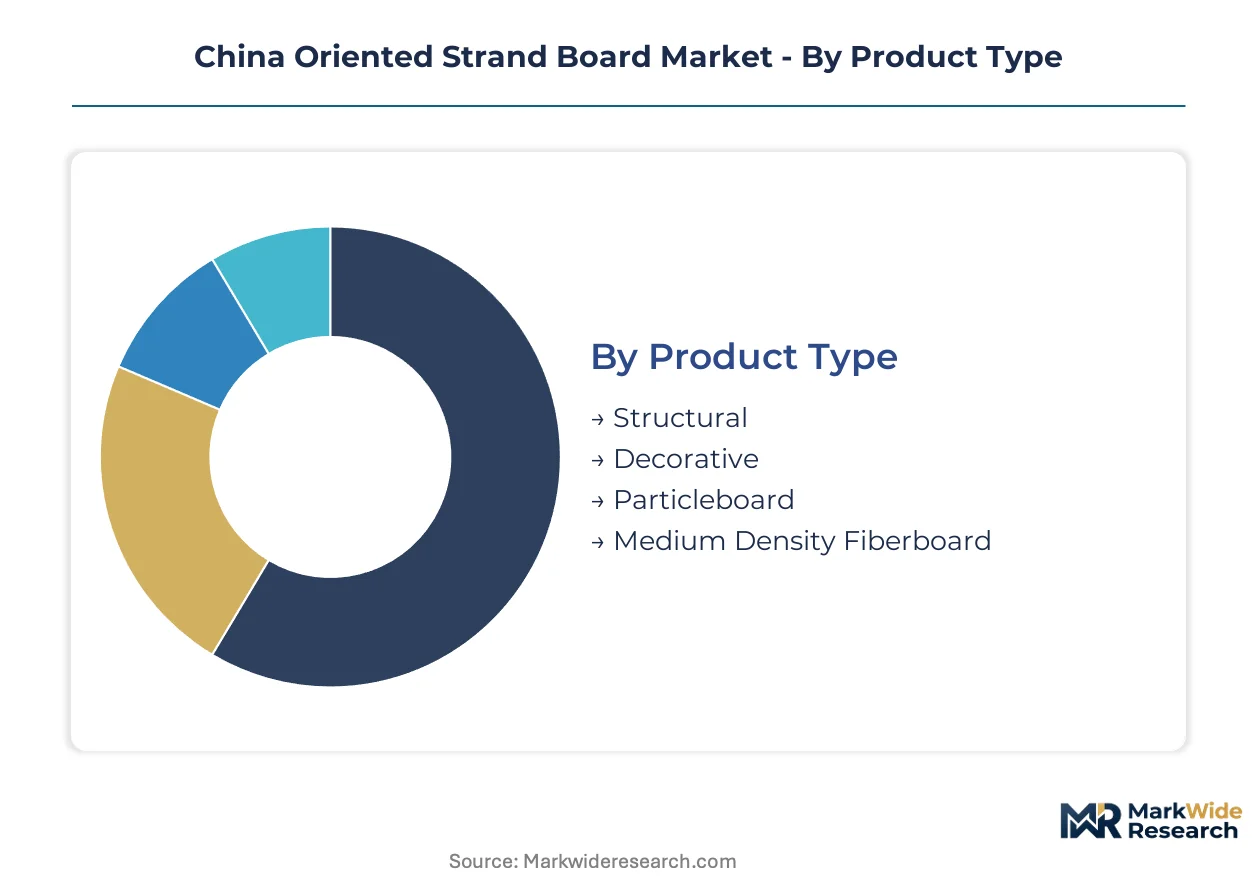
Segmentation reveals how OSB procurement channels fragment across project scales and buyer sophistication tiers. Prefabricated housing contractors, furniture manufacturers, and retail distributors each demand distinct panel specifications, resin chemistries, and fulfillment models.
Product Type:
Structural panels dominate direct sales to large contractors, while decorative grades flow through retailers and online platforms to furniture makers and interior designers.
- Structural:Cross-oriented wood strands bonded with waterproof phenolic or MDI resin deliver load-bearing performance for wall sheathing and roof decking. Yangtze River Delta modular housing clusters specify structural OSB under updated building codes, with procurement committees requiring third-party certification before tender qualification.
- Decorative:Veneer-overlay surfaces and exposed-edge aesthetics serve furniture manufacturers adopting visible-strand tabletops and shelving units. Shanghai and Shenzhen boutique interior designers specify decorative grades for millennial-targeted residential and commercial fit-outs, climbing the fastest among product types.
- Particleboard:Lower-density wood particle construction serves cost-sensitive furniture and interior applications through wholesale distributors.
- Medium Density Fiberboard:Uniform fiber matrix suits detailed machining and painted finishes in cabinetry and molded components.
By volume, structural leads. By growth pace, decorative is ahead.
End Use:
Application-based cost tiers separate premium structural specifications from economy packaging grades, with resin chemistry and density calibration determining margin profiles.
- Construction:Load-bearing wall and roof sheathing in residential framing commands premium pricing through certified direct sales channels. GB/T 4897 compliance and SAMR-recognized quality systems qualify mills for Beijing and Guangzhou municipal housing tenders.
- Furniture:Exposed-edge tabletops, shelving, and cabinetry components drive decorative-grade demand through retail and online procurement.
- Flooring:Heavy-duty thickness grades with enhanced moisture resistance serve commercial build subfloor systems.
- Packaging:Economy-grade panels with standard resin formulations supply industrial crating and export logistics through wholesale networks.
Construction commands the highest volume throughput. Furniture exhibits the steepest expansion trajectory.
Thickness:
Volume concentration tilts toward standard panels for general construction, while custom specifications capture margin premiums in specialized architectural applications.
- Standard:General wall sheathing and roof decking specifications align with mainstream residential and light commercial framing codes.
- Heavy-duty:Enhanced density and thickness calibrations support commercial flooring systems and high-load structural applications.
- Lightweight:Reduced-density formulations serve non-structural interior partitions and furniture substrates where weight reduction matters.
- Custom:Project-specific dimensional and performance requirements command premium positioning in architectural and specialty industrial contracts.
Standard thickness moves the most cubic meters. Custom specifications achieve the highest per-unit margins.
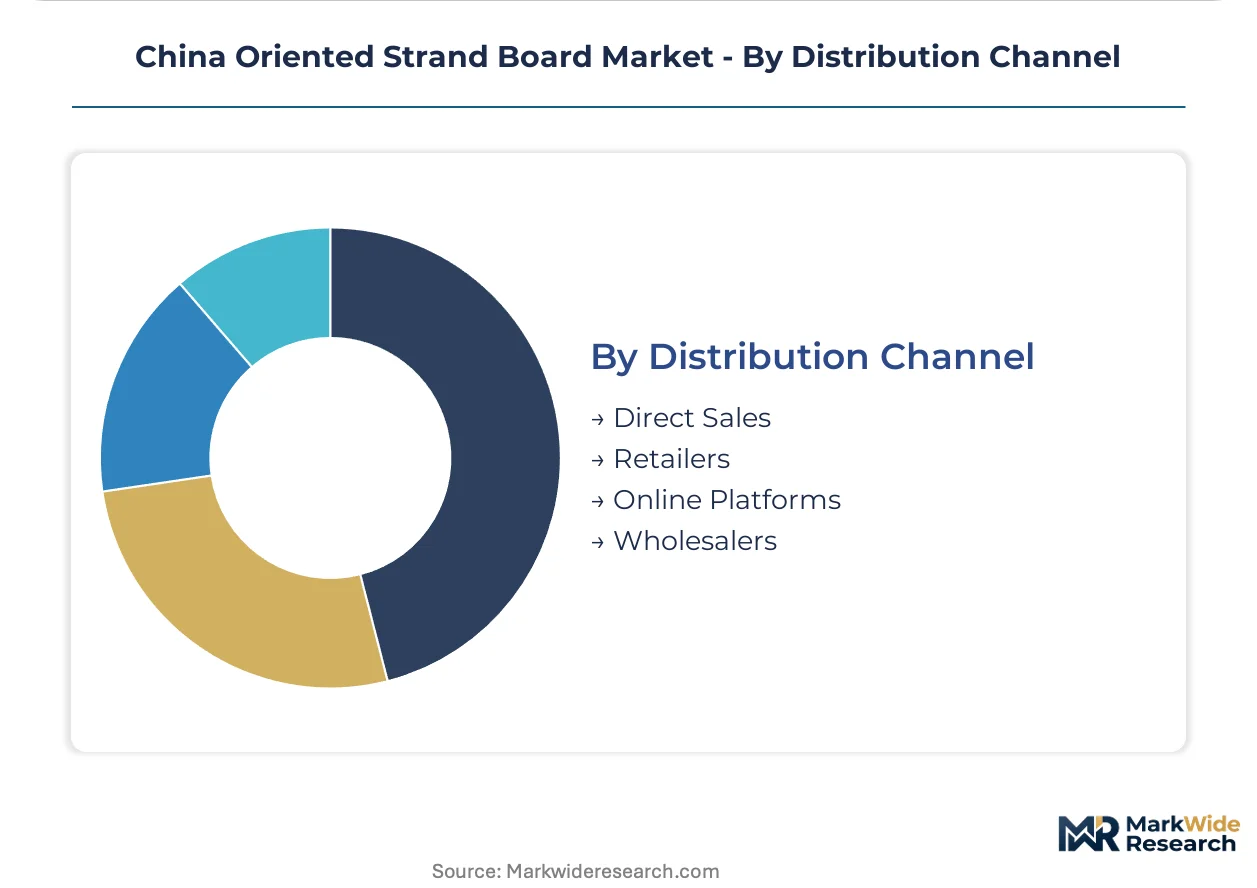
Distribution Channel:
Customer type and procurement sophistication determine channel selection, with state-contracted projects consolidating through direct relationships while fragmented buyers access product through intermediaries.
- Direct Sales:Large prefabricated housing contractors and state-backed developers negotiate volume contracts with integrated mills. MIIT green manufacturing qualification and in-house testing laboratories determine supplier preselection for municipal tenders.
- Retailers:Regional building material chains and specialty wood product distributors serve mid-tier contractors and furniture workshops.
- Online Platforms:E-commerce procurement gains traction among small furniture manufacturers and interior designers seeking sample-to-volume fulfillment.
- Wholesalers:Bulk aggregation and break-bulk distribution serves Tier-3 cities and rural construction markets where plywood substitution persists.
Direct sales channels handle the largest individual contracts. Online platforms are expanding most quickly among emerging buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai high-speed rail corridor underwrites material distribution velocity across eastern China's prefabricated construction belt, compressing delivery windows for engineered wood panels.
Yangtze River Delta
Jiangsu and Zhejiang provinces host the densest modular housing manufacturing clusters, driving predictable bulk procurement of structural OSB for wall assemblies. MIIT's green manufacturing guidelines enforce E0 emission benchmarks on suppliers qualifying for state-contracted projects. Suzhou and Hangzhou anchor integrated panel distribution networks serving prefabricated construction contractors.
Pearl River Delta
Guangdong's furniture manufacturing ecosystem generates specialty demand for decorative-grade OSB with exposed-edge finishes. GB 18580 formaldehyde limits apply stringently to panels entering indoor residential applications. Shenzhen and Guangzhou boutique interior designers specify visible-strand tabletops for millennial-targeted commercial fit-outs.
Beijing-Tianjin-Hebei
Municipal housing tenders in Beijing require SAMR-recognized quality management systems for structural panel prequalification. The Ministry of Housing and Urban-Rural Development's prefabrication mandates concentrate state-backed developer procurement in this corridor. Tianjin port infrastructure facilitates radiata pine imports from New Zealand for regional OSB mills.
Shandong Peninsula
Integrated timber supply chains across Shandong Province secure year-round softwood log access for panel manufacturers. GB/T 4897 structural performance standards govern load-bearing applications in regional residential framing. Qingdao and Yantai host chemical engineering capabilities supporting phenolic and MDI resin formulation upgrades.
Northeast China
Heilongjiang and Jilin provinces channel over 40% of domestic log supply through captive forest-product conglomerates. Weather-dependent harvesting cycles create seasonal disruption risks for mills dependent on regional feedstock. Harbin and Changchun maintain year-round production continuity through vertical timber integration.
China Oriented Strand Board Market Competitive Landscape
Concentration sits with integrated forest-product conglomerates controlling captive timber supply and chemical engineering capabilities. The vendor base splits between state-affiliated entities with legacy forest concessions and private manufacturers investing in continuous press technology. Three archetypes dominate: timber-integrated conglomerates, specialty decorative-grade producers, and trading houses facilitating import substitution. Competitive moves center on adhesive chemistry upgrades for GB 18580 compliance and geographic expansion into western China infrastructure corridors.
Among timber-integrated conglomerates, Jilin Forest Industry Group Co., Ltd exemplifies the captive-supply archetype through Northeast China forest belt positioning. Guangxi Fenglin Wood Industry Group Co., Ltd occupies the specialty-tier vector with decorative-grade surface capabilities. Luli Group represents scale-driven manufacturing across Shandong Province's integrated supply chains.
| Leading Market Players |
|---|
| Luli Group |
| Dalian WADA International Trading Co., Ltd. |
| Shandong Huiyu International Trade Co., Ltd |
| Jilin Forest Industry Group Co., Ltd |
| Guangxi Fenglin Wood Industry Group Co., Ltd |
| Yalong Wood |
| Nine Dragons Paper (Holdings) Limited |
| Shandong Lingang Wood Industry Co., Ltd |
| Suzhou Dongshan Precision Manufacturing Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Sixty-day softwood log inventory cycles at Northeast China mills compress pricing power during Russian supply disruptions, concentrating cost volatility in the hands of timber-integrated conglomerates while spot buyers absorb margin squeezes. This lead-time exposure shapes how GB 18580 compliance investments flow through to panel quotations, with adhesive chemistry upgrades commanding premium positioning against commodity-grade competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MDI-bonded E0-grade panels from phenolic structural grades and commodity particleboard substitutes. Price differentiation hinges on MIIT green manufacturing qualification status and SAMR-recognized quality certification, with state-contracted projects paying premiums for compliant suppliers. Pricing pressure stems from New Zealand radiata pine import cost swings, squeezing mid-tier mills without captive timber supply. Small furniture workshops exhibit highest price sensitivity, while Yangtze River Delta prefabricated housing contractors prioritize certification reliability over unit cost.
Supply Chain Analysis
Forty-five to sixty-day softwood log inventory cycles expose Chinese OSB mills to Russian export restriction volatility and New Zealand shipping schedule disruptions. Geographic supply concentration centers on Heilongjiang and Jilin provinces for domestic logs, with import dependency on Russian birch and New Zealand radiata pine. Raw material sourcing draws from phenolic resin formulations, MDI adhesive systems, and continuous press equipment from German and Italian suppliers. Single-source vulnerability sits with MDI resin technology licensing from multinational chemical conglomerates. Distribution runs through direct mill relationships for large contractors, regional building material chains for mid-tier buyers, and e-commerce platforms for fragmented furniture makers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where GB 18580 compliance investments and SAMR-recognized quality systems create switching costs that freeze out undercapitalized competitors.
For Market Incumbents: Consolidate adhesive chemistry expertise through captive chemical engineering capabilities or exclusive MDI resin supply agreements, locking in formulation advantages as formaldehyde ceilings tighten. Acquire distressed mid-tier mills in Shandong Province to extend integrated timber supply chains and deny feedstock access to emerging competitors. Threat of European-imported structural panels with superior emission benchmarks demands preemptive E0-grade capacity expansion. For New Entrants and Emerging Players: Custom thickness specifications for architectural specialty contracts represent an underserved service-layer gap where incumbent mills prioritize volume throughput over project-specific flexibility. Target western China infrastructure corridors around Chengdu-Chongqing with lightweight OSB grades for non-structural interior partitions, bypassing entrenched Yangtze River Delta procurement relationships. Go-to-market angle centers on rapid sample-to-volume fulfillment through online platforms for boutique interior designers in Shenzhen. For Investors and Strategic Acquirers: Carve-out targets emerge from state-affiliated forest-product conglomerates seeking to divest non-core panel manufacturing assets amid SOE restructuring mandates. Long-term viability frames around consolidation into three to five vertically integrated national champions controlling both timber supply and resin formulation capabilities. Signal to watch is MIIT enforcement action against non-compliant mills, accelerating disqualification from state-contracted projects and forcing distressed asset sales.| Strategic Initiative | Industry Significance |
|---|---|
| MDI Resin Technology Licensing | Secures E0 emission compliance ahead of GB 18580 ceiling reductions, qualifying mills for Beijing municipal housing tenders. |
| Continuous Press Capacity Expansion | Captures scale economies in structural panel production, freezing out mid-tier competitors from Yangtze River Delta volume contracts. |
| Western China Distribution Buildout | Establishes first-mover presence in Chengdu-Chongqing infrastructure corridors underserved by incumbent distributors. |
| Decorative-Grade Surface Capability Investment | Differentiates through veneer-overlay production for Shanghai furniture manufacturers seeking exposed-edge aesthetics. |
| Captive Softwood Plantation Development | Reduces import dependency on Russian and New Zealand supply cycles, stabilizing raw material cost trajectories. |
Research Methodology
A spread of perspectives from OSB plant managers, prefabricated housing procurement directors, furniture manufacturer supply chain leads, and MIIT regulatory affairs officers converged on the working assumptions around adhesive chemistry transition timelines and GB standard enforcement intensity. Primary interview insights combined with secondary validation from customs trade data, GB/T 4897 standard documentation, SAMR quality system registries, and MIIT green manufacturing guideline disclosures. Bottom-up capacity and utilization estimates triangulated against top-down construction sector wood-based panel consumption forecasts.
Segmentation dimensions modeled span structural versus decorative product types, construction versus furniture versus flooring end uses, standard versus heavy-duty versus custom thickness grades, and direct sales versus retail versus online platform distribution channels. CAGRs derived from regression analysis of historical panel production volumes against prefabricated housing completion rates and furniture sector engineered wood adoption curves. Industry-specific forecast inputs incorporated radiata pine import price indices and provincial building code amendment tracking.
Forecasts assume regulatory continuity in China's GB standard regime and MIIT green manufacturing enforcement; material policy shifts such as accelerated formaldehyde ceiling reductions or timber import tariff restructuring would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market