
 South Korea Aluminum Door and Window Market | 2026-2036
South Korea Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Aluminum Door and Window Market Insights
Modular window-wall systems that integrate glazing, framing, and sealing into prefabricated units is recalibrating buyer choice across South Korea's construction sector. LG Hausys leverages its polymer and metal composite expertise to supply integrated facade modules for large-scale residential towers. Namsun Aluminum anchors domestic supply through its extensive extrusion capacity and distribution network serving regional builders. YKK AP Inc. differentiates through precision-engineered hardware and thermal break technology that meets stringent energy performance thresholds.
South Korea aluminum doors and windows comprise extruded aluminum alloy frames, typically 6063-T5 or 6063-T6 grade, assembled with polyamide thermal breaks, EPDM gaskets, and multi-point locking hardware to provide structural weather resistance and thermal insulation for building envelopes. The primary commercial purpose is to enclose structures while managing heat transfer, air infiltration, and acoustic transmission in compliance with building energy codes. Thermal break aluminum frames command premium positioning as Seoul's building energy standards tighten and developers pursue zero-energy building certifications. Casement windows sustain dominant share in residential applications due to superior sealing performance against monsoon-driven precipitation, while sliding doors capture expanding share in commercial and mixed-use developments where space efficiency and panoramic sightlines drive specification. New construction installations lead volume, though renovation and retrofit activity accelerates as aging apartment stock from South Korea's 1980s-1990s building boom reaches renewal cycles.
MFDS oversees material safety compliance for aluminum alloys used in construction applications, while KOLAS-accredited laboratories verify thermal transmittance and air permeability under Korean standards aligned with international ISO protocols. Seoul Metropolitan Government enforces local building energy codes that mandate U-value thresholds for fenestration in new construction, directly shaping product specifications and manufacturer R&D priorities. Stakeholders must monitor evolving municipal green building mandates and the pace of apartment renewal cycles to calibrate capacity and product portfolio investments.
Market Dynamics
Seoul Metropolitan Government's tightening U-value mandates for fenestration products are forcing manufacturers to reconfigure thermal break designs and recalibrate extrusion-to-fabrication workflows across domestic supply chains.
Growth Catalysts
- Seoul's Building Energy Code:Municipal U-value thresholds for windows and doors mandate thermal break performance upgrades, pulling specification toward high-efficiency aluminum systems in new high-rise residential towers.
- Apartment renewal cycles:Aging housing stock from South Korea's 1980s-1990s construction boom is entering mandatory redevelopment phases, generating sustained retrofit demand for modernized fenestration.
- Thermal break polyamide:Advanced insulating barrier technology enables aluminum frames to meet zero-energy building certification requirements under the Green Building Certification System.
Market Restraints
- Primary aluminum price volatility:LME-linked ingot costs transmit directly to extrusion margins, compressing fabricator profitability during commodity spike periods.
- EPDM gasket import dependency:Sealing component supply concentrates among Southeast Asian specialty rubber producers, exposing assemblers to freight cost and currency fluctuation risks.
- PVC-u substitution in low-rise housing:Vinyl frames capture cost-sensitive single-family and rural segments where thermal performance mandates remain less stringent.
Strategic Opportunities
- Gyeonggi Province satellite cities:Suwon, Yongin, and Goyang are experiencing accelerated residential densification with limited local fabrication capacity, creating white space for distributed manufacturing nodes.
- Modular window-wall prefabrication:Factory-integrated facade units reduce on-site labor hours and weather dependency, aligning with construction productivity mandates from the Ministry of Land, Infrastructure and Transport.
- Acoustic performance tiering:Highway-adjacent developments in Incheon and northern Seoul corridors are specifying STC-rated aluminum systems as traffic noise mitigation becomes a planning requirement.
Industry Challenges
- Thermal simulation expertise gap:KOLAS-accredited laboratory capacity for U-value and air permeability verification is concentrated in Seoul, creating testing bottlenecks for regional fabricators.
- Multi-point hardware integration complexity:Precision-engineered locking systems from specialized suppliers require calibrated assembly protocols that extend fabrication training cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Aluminum Door and Window Market |
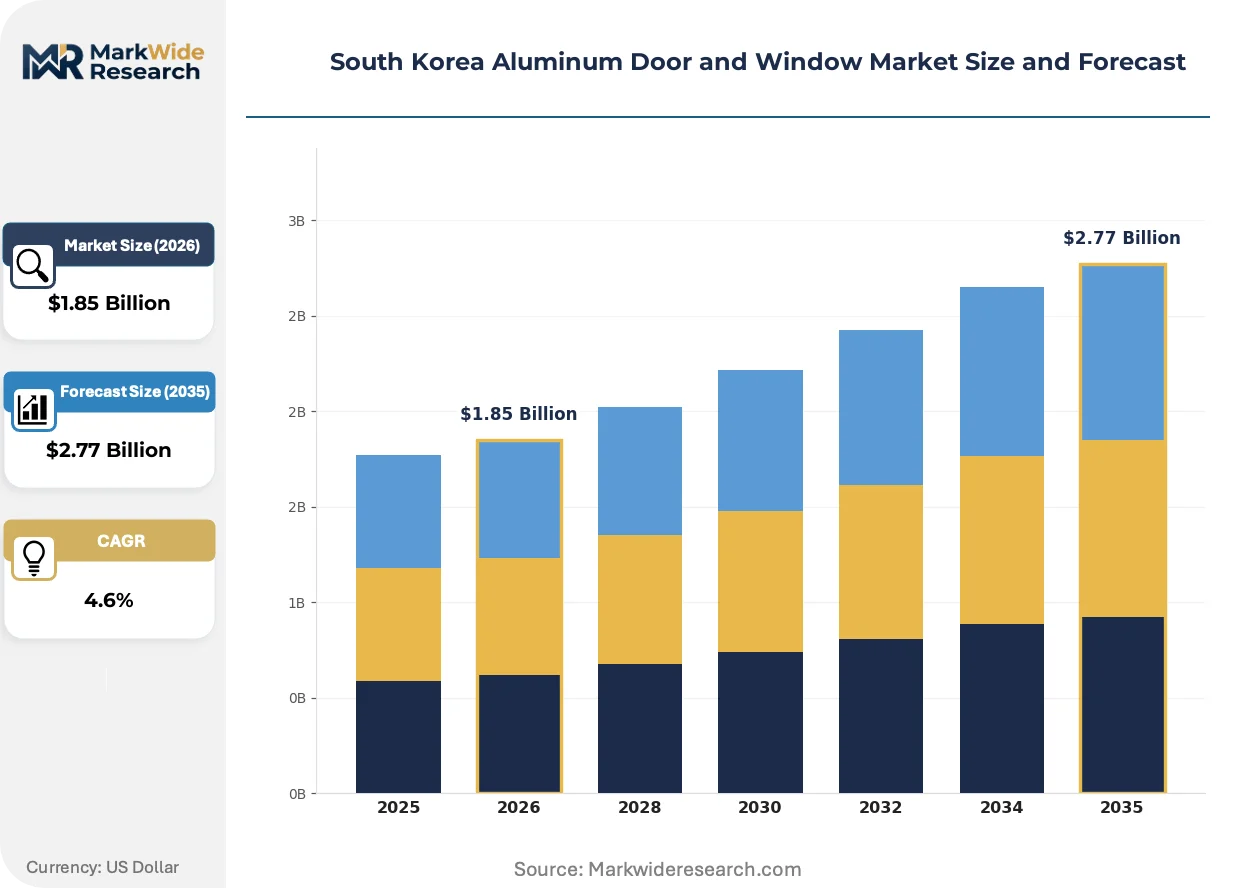
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Bi-Fold Doors, Casement Windows, Fixed Windows Installation Type: New Construction, Renovation, Replacement, Retrofit End User: Residential, Commercial, Industrial, Institutional Frame Material: Thermal Break Aluminum, Standard Aluminum, Composite, Others |
| Companies Covered | LG Hausys, Namsun Aluminum, YKK AP Inc., LIXIL Corporation, Reynaers Aluminium, Schüco International, KOMMERLING, Alumil S.A., Aluplex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Aluminum Door and Window Market Trends and Innovations
Product architecture is converging toward factory-integrated systems that compress installation timelines and eliminate field tolerances. Three developments are restructuring competitive positioning across South Korean fenestration supply chains.
Modular window-wall systems that pre-integrate glazing, thermal breaks, and gaskets into factory-sealed units are rewriting project delivery economics for high-rise residential towers. Major developers in Seoul's Gangnam and Yongsan districts are specifying these units to compress construction schedules and reduce on-site labor dependency. The shift is compressing demand for traditional stick-built aluminum framing methods in projects above twenty stories.
Seoul Metropolitan Government's local building energy code amendments are mandating progressive U-value reductions for fenestration in new construction permits. The policy is forcing manufacturers to deepen thermal break configurations and upgrade polyamide barrier specifications. High-rise residential developers pursuing zero-energy certifications are absorbing premium pricing for compliant systems, while mid-market builders in secondary cities face specification-cost compression.
Direct procurement relationships between national apartment developers and extrusion-integrated fabricators are displacing traditional distributor-mediated channel structures. Large-scale residential constructors in Gyeonggi Province are negotiating volume frameworks that bypass regional wholesalers. The channel consolidation is most visible in bundled tower projects where single-source facade responsibility reduces interface risk and warranty fragmentation.
South Korea Aluminum Door and Window Market Segmentation
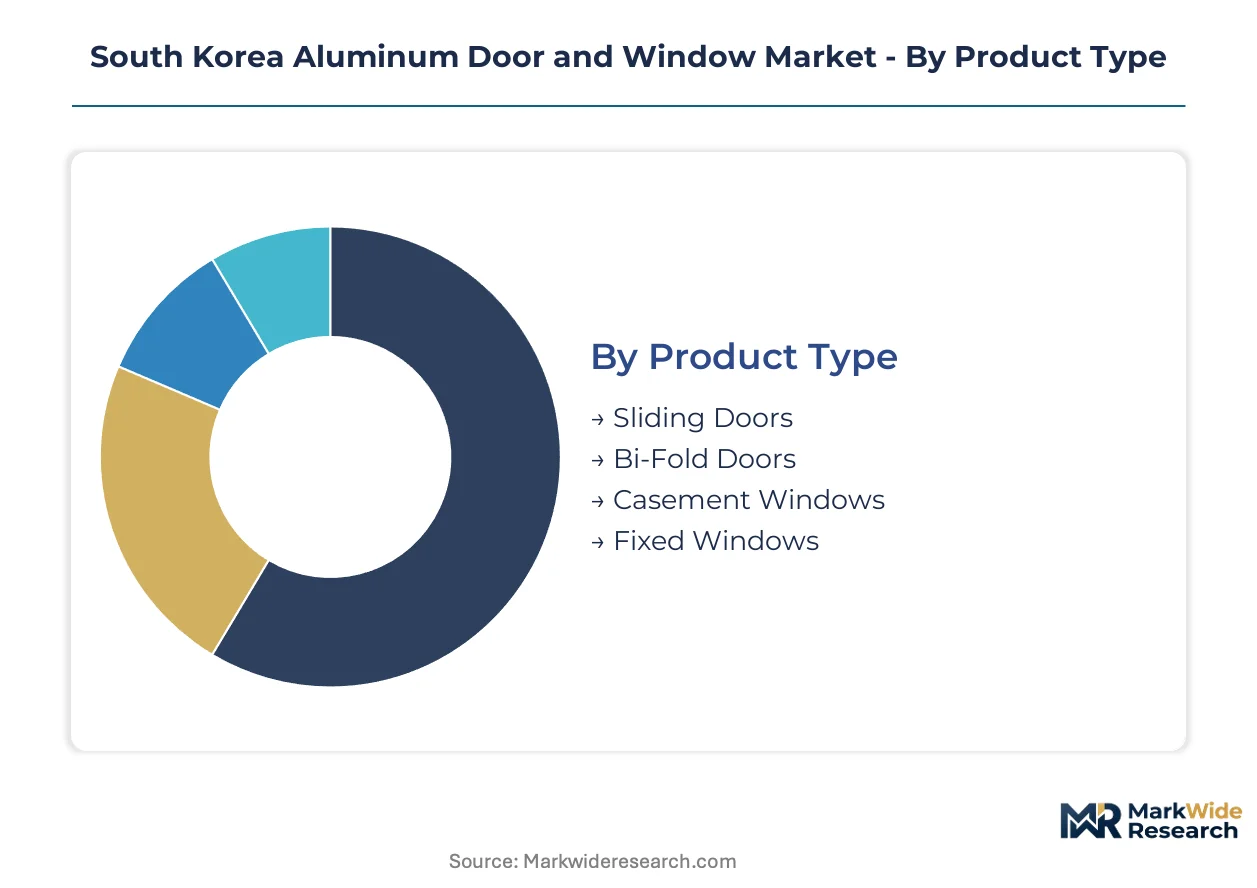
Product architecture and installation context determine specification pathways across South Korea's aluminum fenestration market. Thermal performance mandates and construction cycle timing create divergent demand profiles that manufacturers must align against.
Product Type:
Supply concentration tilts toward sealing-intensive designs as Seoul's building energy codes tighten water and air infiltration standards.
- Casement Windows:Hinged sashes with compression-sealed perimeters deliver superior weather resistance against monsoon precipitation. Seoul high-rise residential towers specify these units for their air tightness performance under KOLAS-verified testing protocols. Demand concentrates in Gangnam and Yongsan redevelopment zones where zero-energy certification requirements apply.
- Sliding Doors:Horizontal track systems with multi-point locking hardware enable panoramic sightlines and space efficiency in commercial and mixed-use developments. Gyeonggi Province satellite cities including Suwon and Yongin are absorbing expanding volumes as residential densification accelerates. Rail and roller mechanism precision determines warranty positioning across price tiers.
- Bi-Fold Doors:Accordion-folding panels with continuous thermal breaks create wide apertures for luxury residential and hospitality applications. Premium villa developments in Seongnam and Goyang specify these systems.
- Fixed Windows:Non-operable glazing units with minimal frame sightlines serve curtain wall and clerestory applications. Commercial towers in Incheon's Songdo district utilize these for daylight optimization.
Today's leader: Casement Windows. Tomorrow's challenger: Sliding Doors.
Installation Type:
Cost tier differentiation separates high-volume new construction from labor-intensive renovation workflows.
- New Construction:Factory-integrated facade modules reduce on-site labor hours and weather dependency for high-rise residential towers. Seoul Metropolitan Government productivity mandates from the Ministry of Land, Infrastructure and Transport favor prefabricated delivery methods.
- Renovation:Aging apartment stock from South Korea's 1980s-1990s construction boom generates sustained demand for modernized fenestration with improved U-values.
- Replacement:Single-unit swap-outs address component failure in existing buildings. Regional fabricators in Busan and Daegu capture this mid-market activity through distributor networks.
- Retrofit:Building envelope upgrades with secondary glazing or frame-over-frame installation extend thermal performance without full demolition. Energy audit requirements are expanding this segment in municipal housing stock.
Volume dominance sits with New Construction. Margin expansion favors Retrofit.
End User:
Application-specific performance requirements drive material specification and certification depth.
- Residential:High-rise apartment towers dominate volume, with thermal break aluminum commanding premium positioning as Seoul's building energy standards tighten. MFDS material safety compliance applies to all alloys specified.
- Commercial:Mixed-use developments and office towers specify acoustic-rated systems for highway-adjacent locations in northern Seoul corridors. STC performance tiering is becoming a planning requirement.
- Industrial:Warehousing and logistics facilities utilize standard aluminum frames where thermal performance mandates remain less stringent. Cost sensitivity drives PVC-u substitution in this segment.
- Institutional:Schools and healthcare facilities require enhanced durability and security hardware. Multi-point locking systems from specialized suppliers extend fabrication training cycles for these specifications.
Residential absorbs the deepest thermal break penetration. Commercial is climbing the fastest on acoustic performance tiering.
Frame Material:
Customer type stratification separates premium-mid-economy positioning through thermal performance certification.
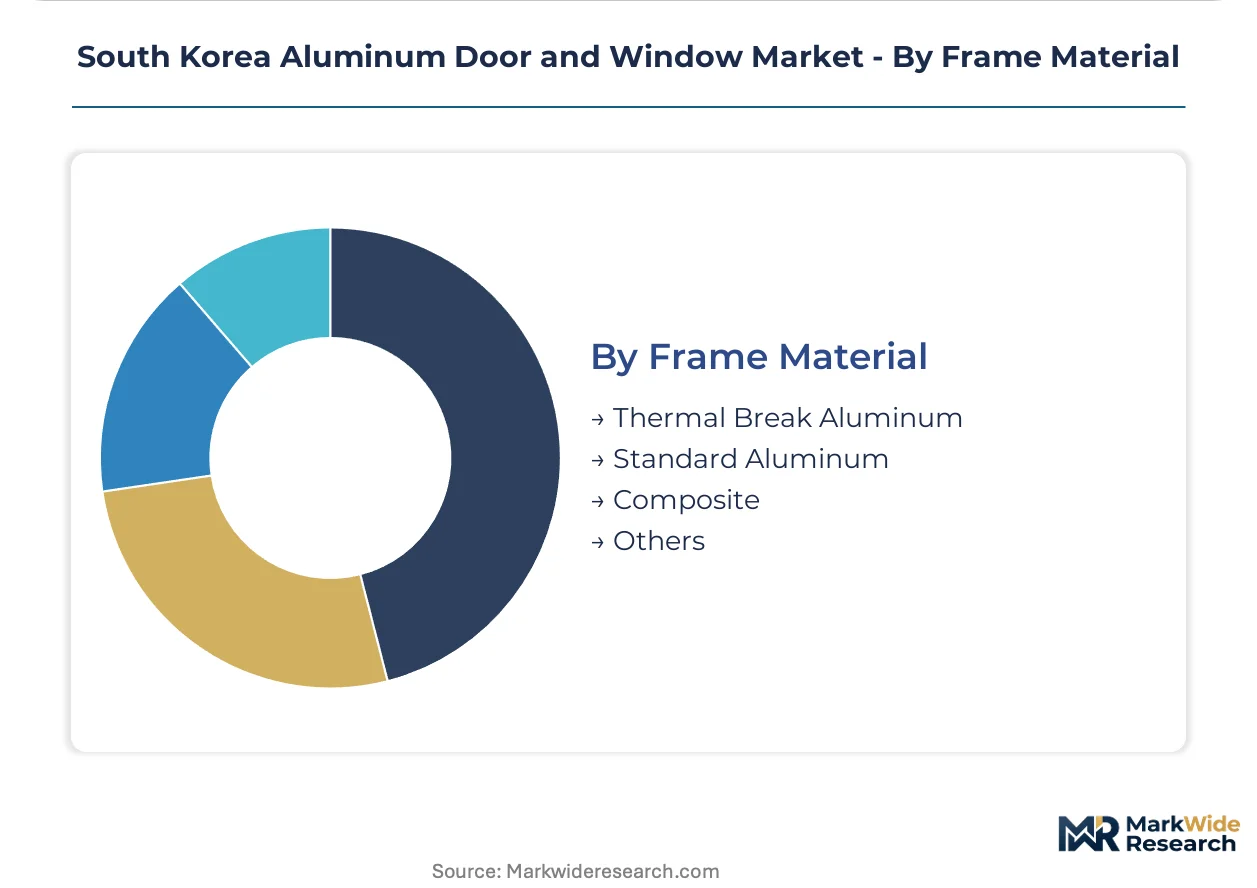
- Thermal Break Aluminum:Polyamide barrier technology enables 6063-T5 and 6063-T6 alloy frames to meet zero-energy building certification requirements. Seoul Metropolitan Government U-value mandates are forcing specification toward these systems in new permits.
- Standard Aluminum:Non-thermally-broken extrusions serve cost-sensitive applications and secondary cities where code enforcement varies. Primary aluminum price volatility from LME-linked ingot costs compresses margins.
- Composite:Aluminum-clad timber or polymer-core systems hybridize structural and insulating properties. Niche positioning in heritage-sensitive districts of central Seoul.
- Others:Experimental materials including recycled content alloys and bio-based thermal breaks. Early-stage pilot projects in government-sponsored green building demonstrations.
Thermal Break Aluminum holds specification leadership. Composite offers differentiation potential for sustainability-focused developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's aluminum fenestration industry traces its modern scale to the 1980s-1990s apartment construction boom, when mass housing programs in Seoul established domestic extrusion and fabrication capacity that now serves renewal-driven demand cycles.
Seoul Capital Area
High-rise residential redevelopment in Gangnam and Yongsan districts drives specification toward zero-energy certified thermal break systems. Seoul Metropolitan Government enforces progressive U-value reductions for new construction permits. Factory-integrated facade modules from extrusion-integrated fabricators are displacing traditional distributor channels in bundled tower projects.
Busan-Ulsan
Port-adjacent commercial and logistics development generates demand for acoustic-rated aluminum systems as highway noise mitigation becomes a planning requirement. Regional fabricators capture replacement activity through established distributor networks. Aging industrial building stock from the 1990s heavy industry expansion is entering envelope upgrade cycles.
Daegu-Gyeongbuk
Secondary city residential densification lags Seoul's code enforcement stringency, creating price-tier segmentation between thermal break and standard aluminum frames. KOLAS-accredited testing capacity is concentrated in Seoul, creating verification bottlenecks for regional manufacturers. Local builders source through distributor-mediated channels rather than direct procurement.
Daejeon-Sejong
Government complex relocation and administrative city construction generated institutional demand for security-enhanced aluminum systems with multi-point locking hardware. Public sector procurement favors MFDS-compliant material safety certification. Sejong's planned city development incorporates modular window-wall specifications from national-scale fabricators.
Gwangju-Honam
Rural and single-family housing segments exhibit cost sensitivity that sustains PVC-u substitution where thermal performance mandates remain less stringent. Agricultural and light industrial facilities utilize standard aluminum frames without thermal breaks. Regional distribution networks serve mid-market replacement demand with compressed lead times.
South Korea Aluminum Door and Window Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal performance certification depth, with Seoul's tightening U-value mandates widening the spread between code-compliant and non-compliant supply. The vendor base clusters around three strategic archetypes: extrusion-integrated fabricators with direct developer relationships, hardware-specialized system suppliers, and regional distributors serving secondary cities. Dominant competitive moves include backward integration into polyamide thermal break production and factory-integrated facade module capacity expansion.
Among Korea-based fabricators, LG Hausys and Namsun Aluminum occupy positions reflecting polymer-metal composite expertise and extrusion-scale supply respectively, while YKK AP Inc. exemplifies the hardware-precision tier. These three represent distinct competitive vectors—materials integration, domestic manufacturing scale, and engineered component specialization—that define the market's structural segmentation. Each anchors a different procurement pathway: direct developer frameworks, regional builder networks, and specification-driven architectural channels.
| Leading Market Players |
|---|
| LG Hausys |
| Namsun Aluminum |
| YKK AP Inc. |
| LIXIL Corporation |
| Reynaers Aluminium |
| Schüco International |
| KOMMERLING |
| Alumil S.A. |
| Aluplex |
| Others |
Pricing and Supply Chain Analysis
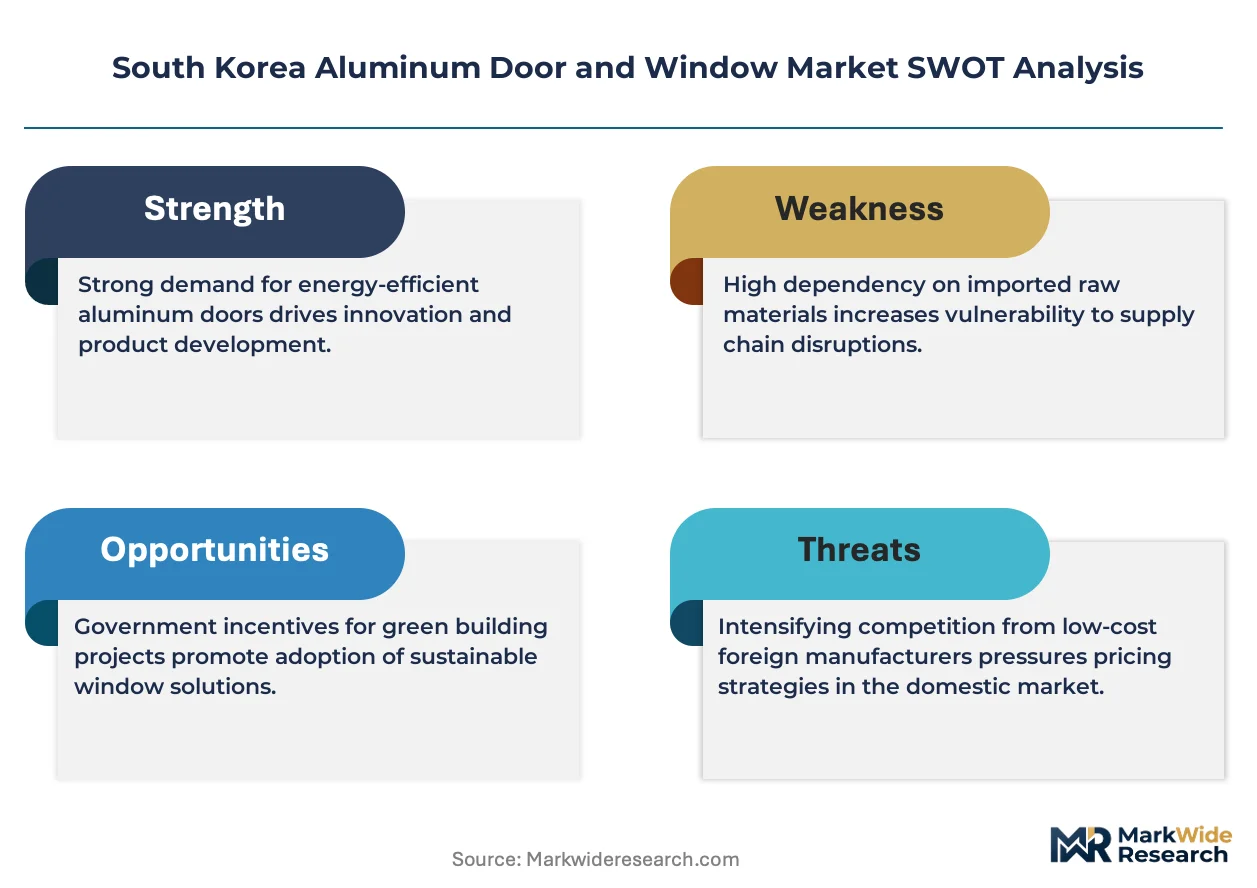
Primary aluminum ingot costs from LME-linked suppliers transmit directly through South Korea's extrusion-to-fabrication pipeline, compressing margins at each conversion stage and forcing tiered pricing separation between thermal break-certified systems and standard frames.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs South Korea aluminum door and window transactions. Certification grade under Seoul Metropolitan Government U-value mandates and volume scale in bundled tower projects drive price differentiation. Pricing pressure stems from LME-linked ingot volatility, with residential developers absorbing premium thermal break costs while rural single-family builders exhibit highest price sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian EPDM gasket producers concentrated in Thailand and Malaysia. Raw material flows draw from Chinese primary aluminum smelters, Korean domestic 6063-T5 extrusion mills, and Japanese polyamide thermal break suppliers. Tariff exposure on Chinese aluminum ingot imports compounds supply chain risk. Distribution runs through extrusion-integrated fabricators serving national developers and regional distributors feeding secondary city builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea aluminum door and window margins expand through thermal break premiumization as Seoul's U-value mandates tighten and apartment renewal cycles sustain retrofit demand at higher price points.
For Market Incumbents: Lock in direct procurement relationships with Gyeonggi Province residential developers before channel consolidation accelerates. Deepen backward integration into polyamide thermal break production to defend against commodity margin compression from LME-linked aluminum volatility. For New Entrants and Emerging Players: Regional fabricators in Busan and Daegu represent underserved buyer archetypes facing KOLAS testing bottlenecks. Capture replacement activity through acoustic-rated system specialization for highway-adjacent commercial developments in Incheon. For Investors and Strategic Acquirers: Consolidation pressure builds where KOLAS-accredited laboratory capacity concentrates in Seoul while regional fabricators lack verification access. Target mid-scale extruders with untapped modular window-wall capacity as inflection indicator for factory-integrated facade adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Break Production | Captive polyamide supply insulates margins against LME aluminum volatility and Korean energy cost spikes. |
| Modular Window-Wall Capacity Expansion | Factory-integrated facade modules align with Ministry of Land, Infrastructure and Transport productivity mandates for high-rise residential towers. |
| KOLAS Laboratory Accreditation Investment | Regional testing capacity eliminates Seoul-centric bottlenecks for U-value verification in Busan and Daegu markets. |
| Acoustic Performance Tiering Development | STC-rated systems capture highway-adjacent commercial specifications in Incheon and northern Seoul corridors. |
| Direct Developer Procurement Frameworks | Bypassing distributor channels reduces warranty fragmentation in bundled Gyeonggi Province apartment tower projects. |
Research Methodology
Multiple input streams — primary interviews with extrusion plant managers, thermal break R&D directors, and national apartment developer procurement leads; secondary validation through Korean customs trade data, MFDS material safety filings, and Seoul Metropolitan Government building permit records; plus KOLAS laboratory certification databases — were reconciled through bottom-up and top-down triangulation.
Historical shipment volumes were cross-referenced against panel input from fabricator production planners and distributor inventory managers. Segmentation dimensions modeled include product architecture, installation context, end-user application, and thermal performance certification tier. CAGRs were derived from trend extrapolation calibrated against apartment renewal cycle timing and municipal code amendment schedules.
Underlying measurement precision varies by segment; new construction installations carry tighter precision than fragmented replacement activity. Forecasts reflect assumptions about Seoul U-value mandate enforcement pace and primary aluminum price trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market