
 North America Gypsum Board Market | 2026-2036
North America Gypsum Board Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gypsum Board Market Intelligence
Multifamily residential construction is pivoting toward higher-volume gypsum board procurement as housing density increases across major metropolitan corridors. USG Corporation leverages its integrated supply chain and manufacturing scale to dominate distribution in the Midwest and Southeast. Georgia-Pacific LLC anchors its position through extensive channel control with large home improvement retailers and contractor-direct programs.
North America gypsum board consists of a calcium sulfate dihydrate core pressed between thick paper facings, manufactured through continuous calcination and hydration processes to achieve specified flexural strength and fire resistance ratings. The product serves primarily as interior wall and ceiling surfacing in commercial and residential structures. Fire-resistant board leads specification value in commercial high-rise and institutional projects where code mandates drive premium placement. Moisture-resistant board captures expanding share in bathroom and kitchen applications across renovation projects where water damage claims have intensified. Standard board remains the volume base for residential construction though margin compression persists at the commodity tier.
EPA Clean Air Act enforcement shapes plant-level emissions compliance and capital allocation for kiln upgrades across US manufacturing facilities. OSHA silica exposure limits influence jobsite cutting practices and dust control product development. NHTSA fuel efficiency standards indirectly affect gypsum board logistics costs through trucking fleet compliance requirements. Stakeholders must monitor how evolving DOE building energy codes and state-level stretch codes recalibrate insulation and air-sealing specifications that compete with or complement gypsum board systems.
Market Dynamics
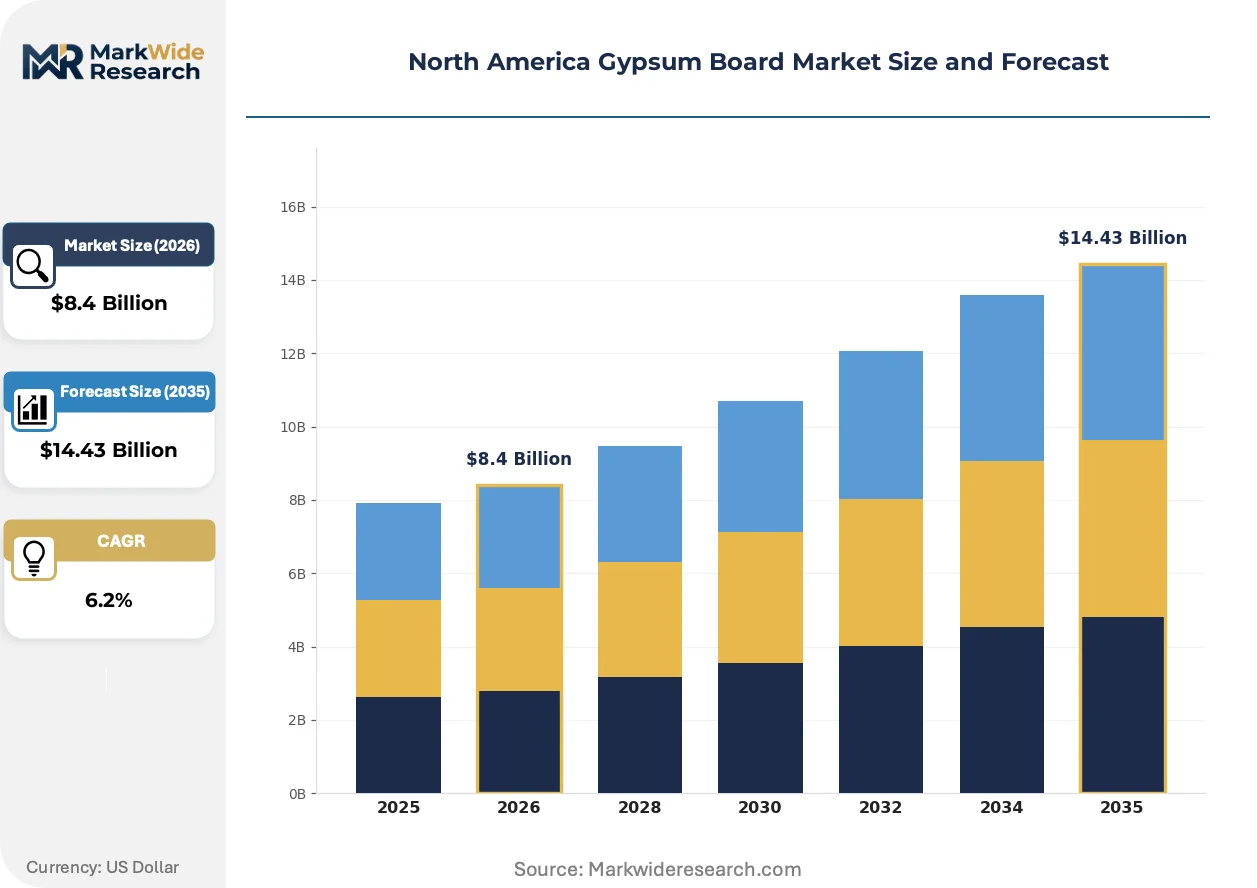
EPA Clean Air Act enforcement is compressing manufacturing margins while accelerating kiln modernization cycles across US production facilities. This regulatory pressure, combined with southern US construction concentration, is restructuring competitive positioning toward integrated supply chain control.
Growth Catalysts
- Multifamily Housing Density:Metropolitan corridors from Houston to Phoenix are driving higher-volume gypsum board procurement as residential developers optimize floor-area ratios.
- LEED v4.1 Certification:The US Green Building Council's updated materials credit framework is pulling specification toward low-embodied-carbon board products in commercial high-rise construction.
- Southern Warehouse Construction:E-commerce fulfillment center expansion across Texas, Georgia, and the Carolinas is sustaining commercial-grade fire-resistant board demand.
Market Restraints
- Natural Gas Price Volatility:Calcination kiln operations remain exposed to input energy cost swings that compress operating margins during winter demand spikes.
- Midwest Supply Concentration:A limited corridor of high-purity gypsum deposits across Michigan and Iowa creates geographic vulnerability to localized logistics disruptions.
- OSHA Silica Exposure Limits:Jobsite cutting compliance requirements add friction to renovation contractor adoption and extend project timelines.
Strategic Opportunities
- Mexico Manufacturing Expansion:Untapped production capacity in Coahuila and Nuevo León offers tariff-advantaged supply positioning for US border-state construction markets.
- Prefabricated Wall Panels:Offsite construction integrators in Florida and California are creating channel demand for dimensionally optimized board products.
- Inflation Reduction Act Tax Credits:Energy-efficient building envelope incentives are pulling complementary specification of insulated gypsum board systems in commercial retrofits.
Industry Challenges
- Calcination Technician Shortage:Specialized kiln operation expertise is aging out of the workforce faster than vocational programs can replenish qualified personnel.
- Legacy ERP Integration:Batch manufacturing scheduling systems require costly middleware upgrades to synchronize with modern logistics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gypsum Board Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Board, Moisture-Resistant Board, Fire-Resistant Board, Soundproof Board Application: Residential Construction, Commercial Construction, Industrial Applications, Renovation Projects Thickness: 1/4 Inch, 1/2 Inch, 5/8 Inch, 3/4 Inch End User: Contractors, Builders, Architects, DIY Homeowners |
| Companies Covered | USG Corporation, American Gypsum Company LLC, Saint-Gobain, PABCO Building Products LLC, Etex Group, Georgia-Pacific LLC, National Gypsum Company, CertainTeed, Knauf, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gypsum Board Market Strategic Shifts & Innovations
Lightweight core formulations and digitized specification tools are compressing traditional product hierarchies while enabling more precise fire-rating optimization. These shifts are restructuring how contractors bid multifamily and commercial projects.
Glass-fiber reinforced gypsum board is absorbing specification share from traditional Type X fire-rated products in mid-rise residential construction. Builders in California and Florida are specifying these panels to achieve equivalent fire ratings at reduced weight and faster installation pace. The technology is absorbing margin from conventional fire-rated board while compressing the premium tier's price elasticity.
EPA's updated National Emission Standards for Hazardous Air Pollutants is mandating continuous emissions monitoring systems at calcination facilities. Plant operators must deploy real-time kiln exhaust analytics to maintain operating permits. The regulation is forcing capital allocation toward scrubber upgrades and predictive maintenance infrastructure, with the largest integrated producers absorbing compliance costs more efficiently than regional competitors.
Contractor-direct procurement platforms are consolidating specification influence away from traditional distributor networks. Large multifamily developers in Texas and Arizona are bypassing wholesale channels to negotiate volume pricing directly with manufacturers. This channel compression is most visible in the Sun Belt, where project scale justifies dedicated logistics arrangements and erodes distributor margin capture.
North America Gypsum Board Market Segmentation
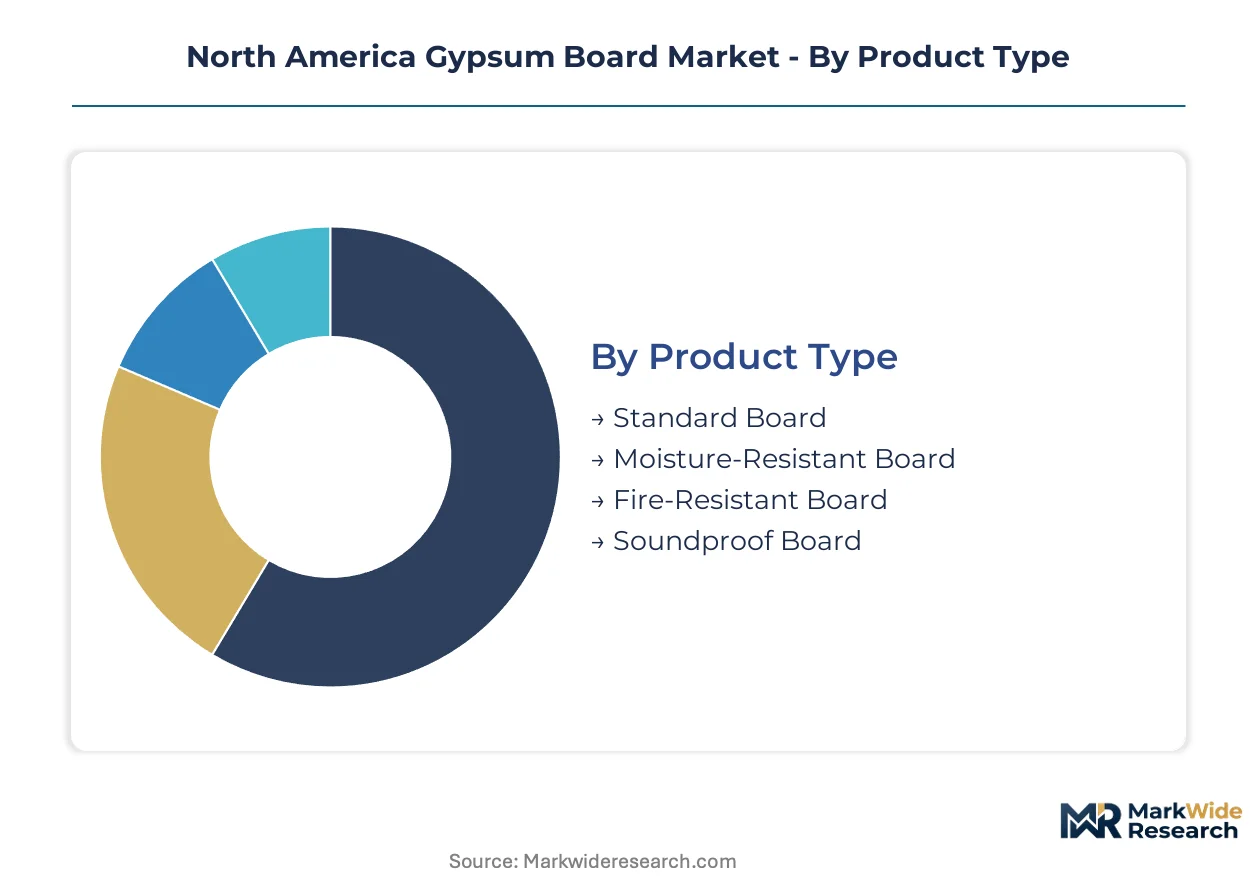
Product differentiation in gypsum board hinges on code compliance, moisture exposure risk, and acoustic performance specifications. Procurement patterns diverge sharply between residential volume buyers seeking commodity pricing and commercial specifiers prioritizing fire ratings and LEED alignment.
Product Type:
Buyer priorities split between cost minimization on basic interior surfacing versus premium payment for code-mandated performance attributes.
- Standard Board:Unfaced calcium sulfate dihydrate core with paper facings serves as the baseline for non-rated interior walls and ceilings. Single-family residential construction across Texas, Florida, and Arizona consumes the highest volumes where builder-grade specifications dominate procurement.
- Fire-Resistant Board:Type X formulations integrate glass fiber reinforcement to achieve ASTM E119 fire ratings required in commercial high-rise and multifamily corridor assemblies. Houston, Atlanta, and Phoenix metropolitan corridors are driving specification intensity as mid-rise residential density accelerates.
- Moisture-Resistant Board:Green-tapered edge board with wax-treated facings and water-repellent core additives targets bathroom, kitchen, and basement applications where insurance claim frequency has elevated specification standards.
- Soundproof Board:High-density core laminates and viscoelastic damping layers deliver STC ratings above 50 for multifamily party walls and hotel corridor separations.
Standard board leads volumes today; fire-resistant board is gaining share fastest.
Application:
Project type determines specification authority, with commercial architects wielding stricter performance mandates than residential builders optimizing material cost per square foot.
- Residential Construction:Single-family and multifamily new builds specify standard and moisture-resistant grades through builder-direct procurement channels concentrated in Sun Belt metropolitan statistical areas.
- Commercial Construction:Office, retail, and institutional projects mandate fire-resistant and soundproof grades with certified chain-of-custody documentation for LEED materials credits.
- Renovation Projects:Aging housing stock in the Northeast and Midwest drives moisture-resistant board replacement where water damage and mold litigation have intensified contractor liability exposure.
- Industrial Applications:Manufacturing facilities and cold storage warehouses specify abuse-resistant and fiberglass-mat faced boards for impact durability in high-traffic zones.
Residential construction anchors volume absorption; renovation projects are climbing the fastest as housing stock ages.
Thickness:
Structural loading requirements and fire-rating duration dictate dimensional selection, with building codes prescribing minimum thickness for specific assembly ratings.
- 1/2 Inch:Standard residential wall thickness balancing material economy with adequate fastener holding power for interior partition systems.
- 5/8 Inch:Thicker core delivers enhanced fire resistance and sound attenuation required in commercial and multifamily code assemblies across jurisdictions with stringent IBC adoption.
- 1/4 Inch:Flexible curve-forming board for archway and specialty architectural applications where radius construction demands pliable surfacing material.
- 3/4 Inch:Maximum thickness for shaftwall systems and elevator hoistway enclosures requiring extended fire resistance ratings in high-rise construction.
1/2 inch dominates residential procurement; 5/8 inch is expanding most quickly as multifamily density intensifies.
End User:
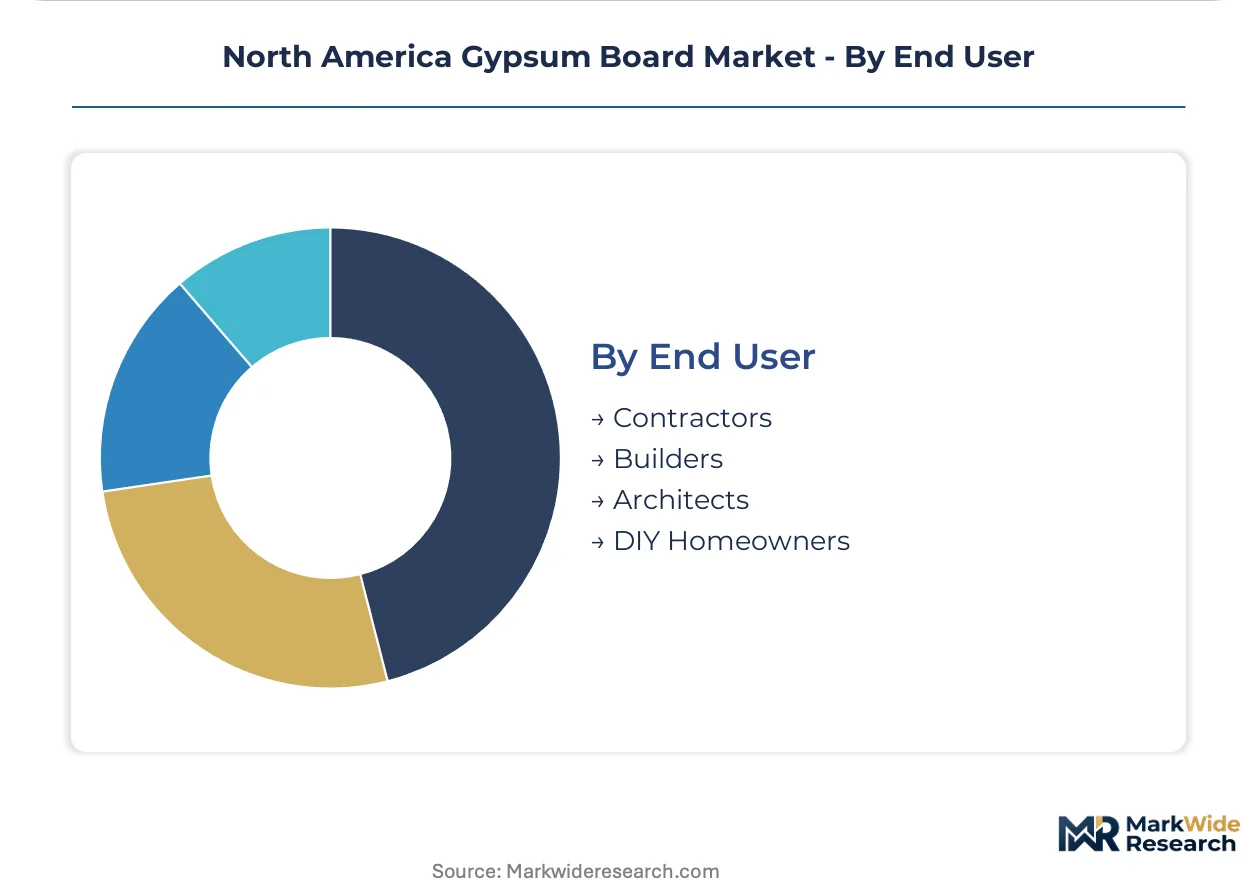
Purchasing authority fragments across professional specifiers, volume contractors, and retail consumers with divergent technical knowledge and price sensitivity profiles.
- Contractors:Multifamily and commercial general contractors negotiate manufacturer-direct pricing on large-scale projects, bypassing traditional distribution in Texas, Arizona, and Georgia markets.
- Builders:Production homebuilders specify standard and moisture-resistant grades through national purchasing agreements with integrated manufacturers.
- Architects:Commercial design professionals specify fire-resistant and soundproof grades with certified environmental product declarations for LEED v4.1 compliance.
- DIY Homeowners:Retail channel purchasers drive small-format moisture-resistant board sales through home improvement centers for bathroom and basement renovation projects.
Contractors control the largest procurement volumes; architects are gaining specification influence fastest through green building mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity is migrating toward jurisdictions where EPA compliance costs and natural gas pricing create arbitrage advantages for integrated producers. This geographic repositioning concentrates investment in southern US states and northern Mexico border regions where logistics access and regulatory burden achieve optimal balance.
United States
Housing starts across Texas, Florida, and Arizona are absorbing the highest gypsum board volumes as metropolitan density accelerates. EPA National Emission Standards for Hazardous Air Pollutants enforcement is mandating continuous emissions monitoring at calcination facilities nationwide. The I-35 corridor from Dallas-Fort Worth through San Antonio anchors the densest concentration of distribution yards serving multifamily construction.
Mexico
Untapped production capacity in Coahuila and Nuevo León is attracting capital allocation for tariff-advantaged supply to US border-state markets. Mexican environmental regulations under SEMARNAT create compliance cost differentials versus US EPA standards. Monterrey industrial parks are emerging as manufacturing hubs with rail connectivity to Texas construction corridors.
Canada
Renovation-driven demand in Ontario and Quebec is intensifying as aging housing stock requires moisture-resistant board replacement. Health Canada building code harmonization with US standards facilitates cross-border product certification. The Greater Toronto Area concentrates specification activity for commercial high-rise projects requiring fire-rated assemblies.
North America Gypsum Board Market Key Industry Players
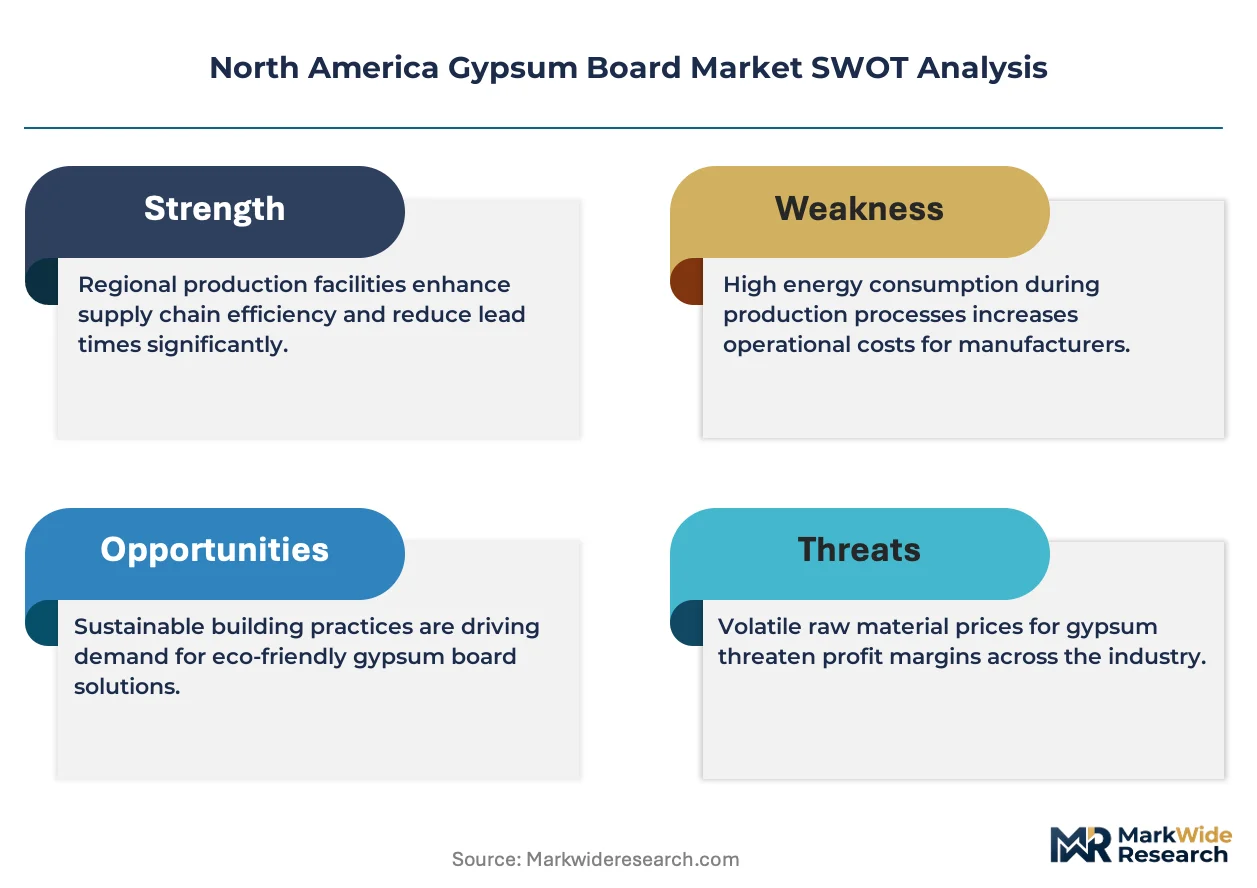
Capacity expansion dominates the current landscape as integrated manufacturers deploy capital toward kiln modernization and southern US distribution infrastructure. The market structure consolidates around a handful of vertically integrated producers with captive gypsum reserves and national distribution networks. Two strategic archetypes prevail: scale-driven integrated manufacturers controlling raw material through finished product, and regional specialists leveraging geographic proximity to specific construction corridors. Competitive intensity centers on M&A activity for mineral reserve access and strategic partnerships with multifamily developers for direct procurement arrangements.
Among North American integrated producers, USG Corporation, Georgia-Pacific LLC, and Saint-Gobain occupy positions representing the scale-driven archetype with extensive manufacturing footprints and distributor channel control. These companies exemplify the integrated model where captive gypsum supply and continuous calcination capacity underpin competitive positioning. Regional specialists such as American Gypsum Company LLC and PABCO Building Products LLC represent the proximity-focused tier, anchoring supply relationships within specific western and southwestern US construction markets.
| Leading Market Players |
|---|
| USG Corporation |
| American Gypsum Company LLC |
| Saint-Gobain |
| PABCO Building Products LLC |
| Etex Group |
| Georgia-Pacific LLC |
| National Gypsum Company |
| CertainTeed |
| Knauf |
| Others |
Cost & Logistics Intelligence
Captive gypsum reserve ownership across Michigan and Iowa anchors both supply security and pricing power for integrated North American producers. This upstream control insulates kiln operators from spot mineral volatility while enabling volume-based contract negotiations with Sun Belt multifamily developers.
Pricing Analysis
Distributor margin compression is restructuring how gypsum board reaches end users as contractor-direct procurement platforms in Texas and Arizona bypass traditional wholesale channels. Three-tier pricing structure across fire-resistant, moisture-resistant, and standard grades reflects ASTM certification levels and LEED v4.1 compliance documentation. Cost compression in the commodity standard tier is intensifying because production homebuilders negotiate national purchasing agreements with integrated manufacturers. Production homebuilders exhibit the highest price sensitivity; commercial architects specifying fire-rated assemblies for high-rise projects demonstrate the lowest.
Supply Chain Analysis
LEED v4.1 environmental product declaration requirements and EPA National Emission Standards for Hazardous Air Pollutants permitting are gating supply access for regional competitors lacking compliance infrastructure. Manufacturing concentrates in the United States, with emerging capacity expansion in Coahuila and Nuevo León, Mexico. Raw material inputs draw from high-purity gypsum deposits, natural gas for calcination kilns, and glass fiber reinforcement for fire-rated formulations. Single-source vulnerability persists in the Michigan-Iowa mineral corridor where localized logistics disruptions ripple through Midwest distribution networks. Distribution runs through manufacturer-direct arrangements with large multifamily developers and traditional distributor yards serving renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America gypsum board market functions as a stable compounder where housing density mandates in metropolitan corridors drive steady replacement and new construction demand.
For Market Incumbents: Anticipate glass-fiber reinforced board technology displacing traditional Type X fire-rated products in California and Florida mid-rise construction. Defend market position by deepening captive gypsum reserve access through mineral rights acquisitions in the Michigan-Iowa corridor and accelerating kiln modernization ahead of EPA enforcement timelines. Channel control investments in contractor-direct procurement platforms will offset distributor margin erosion. For New Entrants and Emerging Players: Prefabricated wall panel integrators in Florida and California represent the most penetrable channel partner type for tariff-advantaged Mexican production capacity. Target the moisture-resistant board segment in Northeast and Midwest renovation markets where aging housing stock intensifies replacement cycles. A go-to-market angle emphasizing expedited LEED v4.1 environmental product declaration certification will differentiate specification influence with commercial architects. For Investors and Strategic Acquirers: Roll-up economics work for regional gypsum specialists because EPA compliance cost differentials favor scaled operators with existing scrubber infrastructure and continuous emissions monitoring systems. The five-to-ten year viability window favors acquisition of western and southwestern US regional producers with proximity to Sun Belt construction corridors. The signal to watch is OSHA silica exposure limit enforcement tightening, which would accelerate consolidation toward integrated manufacturers with dust control product development capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gypsum Reserves | Captive mineral supply in Michigan and Iowa secures kiln feedstock against logistics disruptions. |
| Kiln Modernization and Emissions Compliance | EPA National Emission Standards for Hazardous Air Pollutants mandates scrubber upgrades for operating permits. |
| Contractor-Direct Procurement Platform | Texas and Arizona multifamily developers bypass distributors for volume pricing and dedicated logistics. |
| Glass-Fiber Reinforced Board Product Launch | California and Florida builders specify lighter panels achieving equivalent ASTM E119 fire ratings. |
| Mexico Manufacturing Footprint Expansion | Coahuila and Nuevo León capacity offers tariff-advantaged supply positioning for US border-state markets. |
Research Approach
Direct dialogue with calcination plant managers, multifamily developer procurement directors, commercial architect specifiers, and gypsum distributor channel partners grounded the qualitative foundation. Secondary validation drew from EPA enforcement records, USGS mineral commodity summaries, SEC 10-K filings of integrated producers, and LEED project certification databases. Bottom-up and top-down triangulation cross-checked volume estimates against housing starts data and kiln capacity utilization metrics.
Bottom-up modeling aggregated product-type segments across fire-resistant, moisture-resistant, soundproof, and standard grades with thickness and application dimensions. Top-down validation referenced construction spending flows and regional building permit issuance across the analysis window. CAGRs were derived from trend extrapolation of housing density mandates, e-commerce fulfillment center construction pipelines, and renovation cycle intensity in aging Northeast and Midwest housing stock.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural gas price volatility, EPA enforcement intensity, and OSHA silica regulation finalization. The analysis reflects assumptions about continued Sun Belt population migration and multifamily housing policy support. A model refresh is warranted upon material change in federal building energy code adoption or Inflation Reduction Act tax credit extension timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Sawn and Profiled Wood Products Market