
 Construction Elastomers Market | 2026-2036
Construction Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Elastomers Market Analysis
Southeast Asian petrochemical producers is expanding synthetic rubber output to serve regional infrastructure buildouts. Dow leverages backward integration into propylene oxide feedstocks to secure cost positions in polyurethane systems. BASF anchors its construction elastomers portfolio through geographic proximity to German automotive-adjacent industrial flooring markets. Arkema specializes in bio-based polyamide elastomer grades that navigate tightening sustainability specifications across European public tenders.
Construction elastomers are polymeric materials exhibiting reversible elastic deformation under stress, typically formulated with tensile strengths ranging from 7 MPa to over 25 MPa and elongation-at-break values exceeding 200 percent to accommodate thermal cycling and structural movement in built environments. These materials function primarily as flexible barriers, bonding layers, and impact-absorbing surfaces that maintain integrity across temperature extremes from minus 40 degrees Celsius to above 80 degrees Celsius in exterior applications. Thermoplastic elastomer formulations are capturing margin pools in sealant applications where processing speed and recyclability offset higher raw material costs against conventional vulcanized rubbers. Infrastructure end-use demand is outpacing residential and commercial segments in volume terms, driven by bridge expansion joints, tunnel gaskets, and rail pad applications requiring fatigue resistance over multi-decade design lives. Injection molding technology is displacing compression molding in standardized construction components where cycle time reductions of 40 to 60 percent reshape unit economics at scale.
EPA regulations on volatile organic compound content in architectural coatings and sealants constrain formulation flexibility for US-manufactured products, while REACH registration requirements and the EU Green Deal's embodied carbon tracking pressure European suppliers to document supply chain chemistry. China's GB standards for building waterproofing materials, administered by SAMR, mandate specific elongation and tensile retention metrics that filter import eligibility. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized formulation adaptation or regional manufacturing footprint expansion offers lower compliance cost trajectories.
Market Dynamics
Infrastructure buildouts across Asia-Pacific are absorbing thermoplastic elastomer volumes at a pace that outstrips regional synthetic rubber capacity expansion, tightening feedstock allocation and compressing formulation margins for sealant producers serving bridge and tunnel applications.
Growth Catalysts
- REACH VOC limits:European flooring specifications are tightening volatile organic compound thresholds, forcing specification upgrades that favor high-performance polyurethane membranes in commercial and residential builds.
- Injection molding speed:Cycle time reductions of 40 to 60 percent versus compression molding are capturing margin pools in standardized construction components where throughput economics dominate supplier selection.
- China-India-Indonesia residential clusters:Concentrated new housing starts are absorbing polyurethane-based waterproofing membrane volumes at scale, anchoring regional formulation demand.
Market Restraints
- Propylene oxide feedstock volatility:Polyurethane system costs fluctuate with propylene oxide availability, squeezing margin stability for construction sealant formulators without backward integration.
- European supply concentration:German and Benelux petrochemical corridors control specialty polyol output, exposing downstream compounders to single-source risk during turnaround seasons.
- Vulcanized rubber substitution ceiling:Thermoplastic elastomers face performance limits in multi-decade fatigue applications like rail pads and expansion joints where cross-linked structures retain specification dominance.
Strategic Opportunities
- EU Green Deal embodied carbon tracking:Suppliers documenting supply chain chemistry through ECHA-registered pathways gain preferential access to European public tender frameworks.
- Bio-based polyamide grades:Arkema's specialty positioning demonstrates viable white space for renewable feedstock elastomers navigating tightening sustainability procurement rules.
- Indonesian infrastructure pipeline:Underpenetrated waterproofing specification in Southeast Asian megaprojects offers first-mover advantage for membrane suppliers with localized technical service.
Industry Challenges
- Multi-jurisdiction formulation adaptation:EPA VOC rules, REACH registration tiers, and China's GB standards for elongation retention create divergent compliance cost structures that fragment R&D allocation.
- Injection molding technical migration:Compression molding expertise pools are thinning as equipment suppliers prioritize thermoplastic elastomer system training, creating workforce transition friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Elastomers Market |
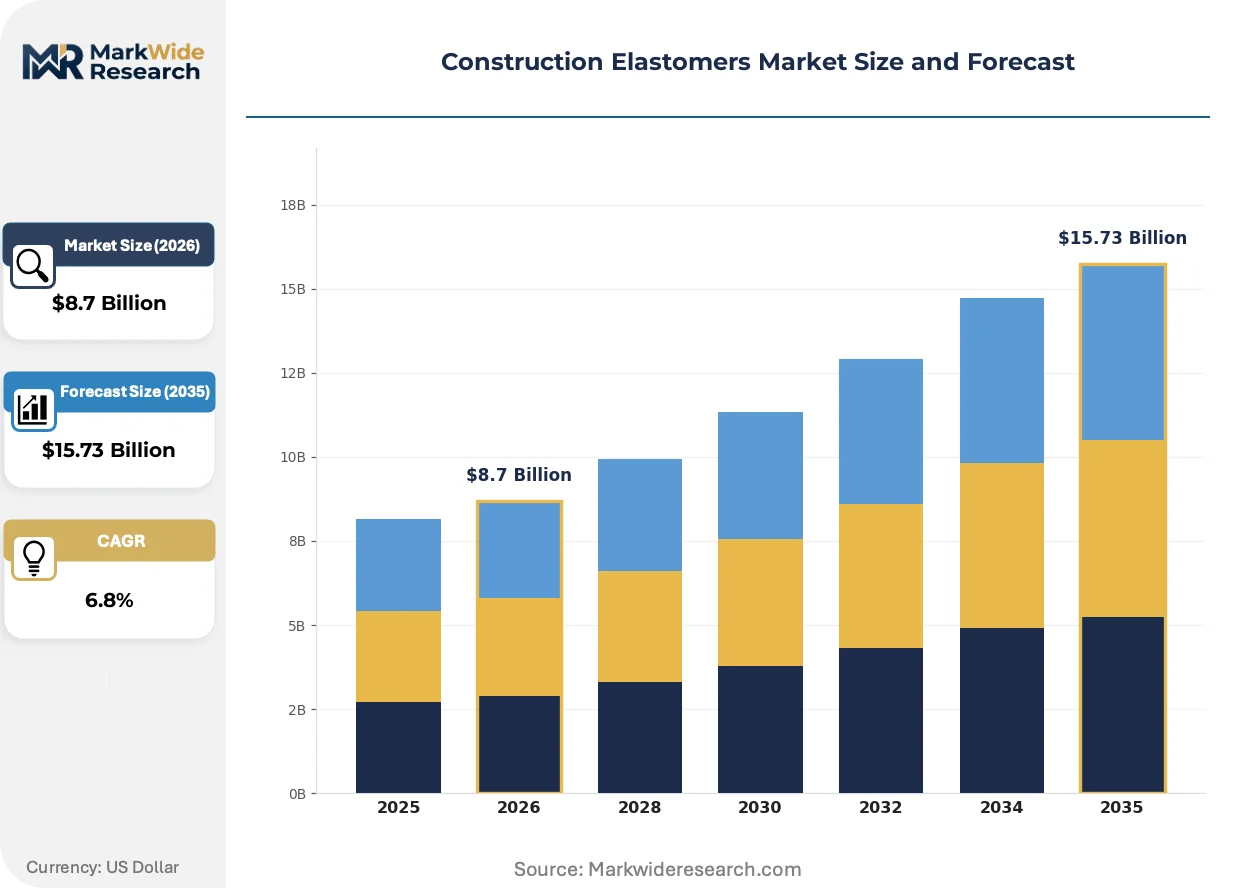
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Thermoplastic Elastomer, Polyurethane End User: Residential, Commercial, Industrial, Infrastructure Application: Sealants, Adhesives, Coatings, Flooring Technology: Extrusion, Injection Molding, Compression Molding, Calendering |
| Companies Covered | BASF, Dow, Arkema, DuPont, Covestro, Huntsman International LLC, Lubrizol Corporation, Evonik Industries, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Elastomers Market Emerging Trajectories
Thermoplastic elastomer processing architectures are fragmenting traditional vulcanized rubber strongholds while regulatory chemistry disclosure requirements and procurement digitization reshape how specifications flow from engineer to applicator.
Reactive hot-melt polyurethane adhesive systems are modularizing on-site membrane installation by eliminating primer stages and compressing cure windows. Railway maintenance contractors in Germany and Japan are specifying these systems for tunnel gasket refurbishment where track possession time limits demand rapid return-to-service. The technology is modularizing supplier value capture away from commodity sealant volumes toward integrated application system sales.
REACH registration requirements combined with EU Green Deal embodied carbon tracking are forcing European construction elastomer suppliers to document polymerization chemistry through ECHA-registered supply chains. Flooring and waterproofing membrane producers face audit trail investments that smaller compounders struggle to fund, concentrating specification access among integrated petrochemical houses with in-house analytics capabilities. German industrial flooring markets are responding fastest, with public tenders already mandating cradle-to-gate carbon disclosure.
Digital specification platforms are compressing the traditional architect-to-applicator information chain, enabling real-time elastomer grade substitution based on availability and certified performance equivalence. Infrastructure procurement offices in Singapore and the Netherlands are piloting these systems for bridge expansion joint and bearing pad sourcing. The shift is most visible in transportation infrastructure verticals where design-build contracts consolidate material decision authority with contractors rather than specifying engineers.
Construction Elastomers Market Segmentation
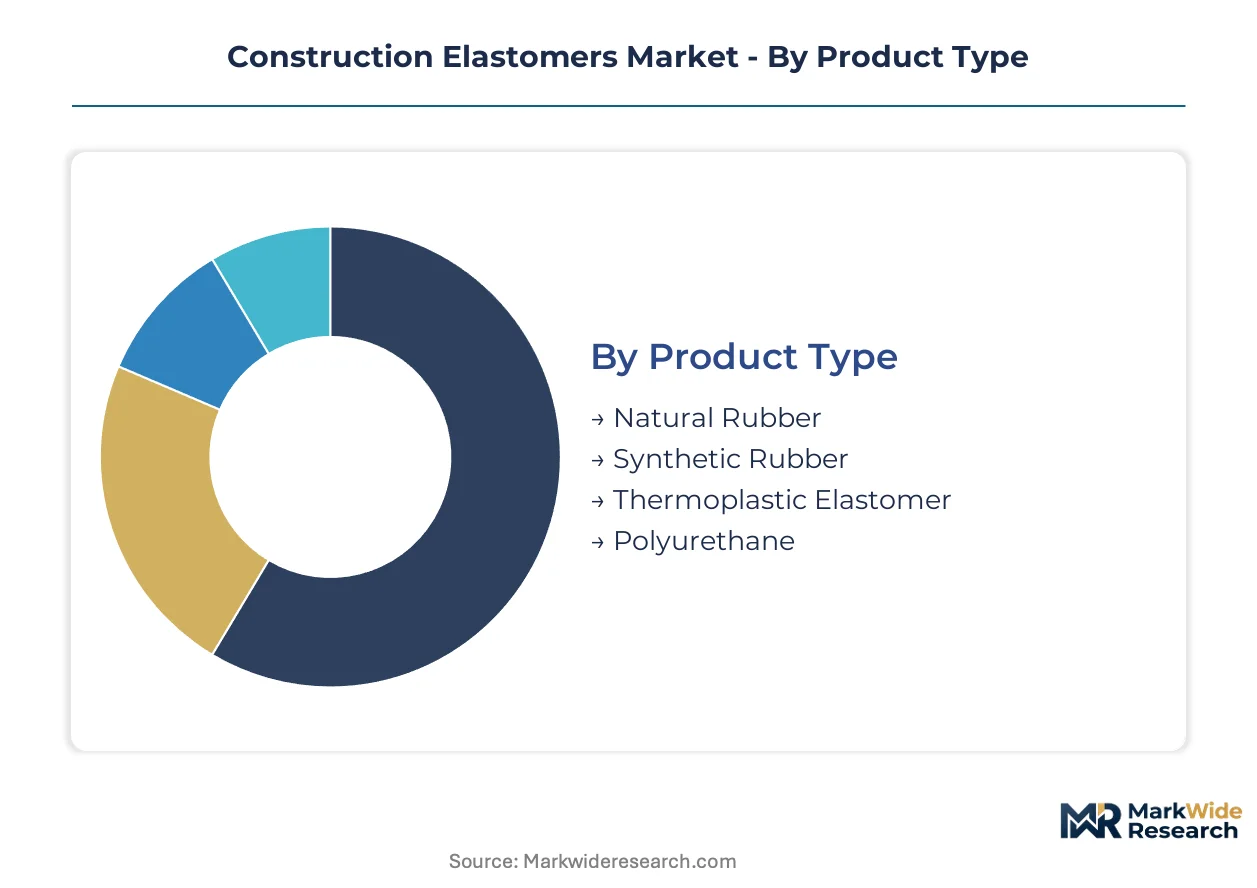
Construction elastomers segment along four axes that determine formulation complexity, processing economics, and specification access. Product chemistry defines thermal performance limits. End-user concentration shapes regional demand geography. Application function dictates durability requirements. Processing technology governs capital intensity and cycle economics.
Product Type:
Some chemistries function as standalone structural barriers; others embed within composite systems requiring primer layers or reinforcement fabrics.
- Natural Rubber:Harvested from Hevea brasiliensis latex with high resilience and tear resistance. Bridge bearing pad specifications in Malaysia and Indonesia specify natural rubber compounds for their superior dynamic load recovery under cyclic stress.
- Synthetic Rubber:Petroleum-derived elastomers including SBR, EPDM, and nitrile grades with controlled molecular architecture. EPDM dominates single-ply roofing membrane specifications across North American commercial construction for ozone and UV stability.
- Thermoplastic Elastomer:Block copolymer structures combining rubber elasticity with thermoplastic processability. Injection molding compatibility drives adoption in standardized window gaskets and door seals where scrap recycling offsets virgin material costs.
- Polyurethane:Isocyanate-polyol reaction products forming cross-linked or thermoplastic structures. Liquid-applied waterproofing membranes for podium decks and green roofs concentrate demand in high-rise residential clusters across China and India.
Synthetic rubber leads volumes today; polyurethane is gaining share fastest.
End User:
Cost tier stratification separates specification-grade infrastructure demand from price-sensitive residential volume plays.
- Residential:New housing starts absorb waterproofing membranes and flooring underlayments where cost-per-square-meter dominates procurement. China's tier-two city expansion anchors regional volume concentration.
- Commercial:Office, retail, and hospitality construction specifies high-performance sealants and coatings with extended warranty terms. LEED certification requirements in US commercial builds filter elastomer selection toward low-VOC formulations.
- Industrial:Manufacturing facilities and warehouses demand chemical-resistant flooring and expansion joint systems. Food processing plants specify polyurethane concrete coatings that withstand thermal shock from washdown cycles.
- Infrastructure:Transportation and utilities projects require multi-decade fatigue resistance in bridge bearings, tunnel gaskets, and rail pads. German railway specifications for expansion joints mandate EPDM compounds with validated 50-year service life projections.
Infrastructure commands premium pricing; residential delivers volume scale.
Application:
Functional role in the building envelope determines whether elastomers serve primary weather barriers or secondary bonding layers.
- Sealants:Flexible joint fillers accommodating thermal movement and structural settlement. Curtain wall specifications in Singapore and Dubai specify movement-capable silicone and polyurethane sealants for high-rise facades.
- Adhesives:Structural and non-structural bonding systems for membrane attachment and panel installation. Reactive hot-melt polyurethane adhesives are displacing solvent-based systems in European roofing applications.
- Coatings:Protective and waterproofing layers applied by spray, roller, or trowel. Liquid polyurethane coatings for parking decks specify crack-bridging elongation exceeding 400 percent under ASTM testing protocols.
- Flooring:Resilient surfaces and underlayments providing impact absorption and acoustic dampening. REACH VOC limits are filtering specification toward water-based polyurethane systems in German and French public tenders.
Sealants anchor current revenue; coatings show steepest expansion trajectory.
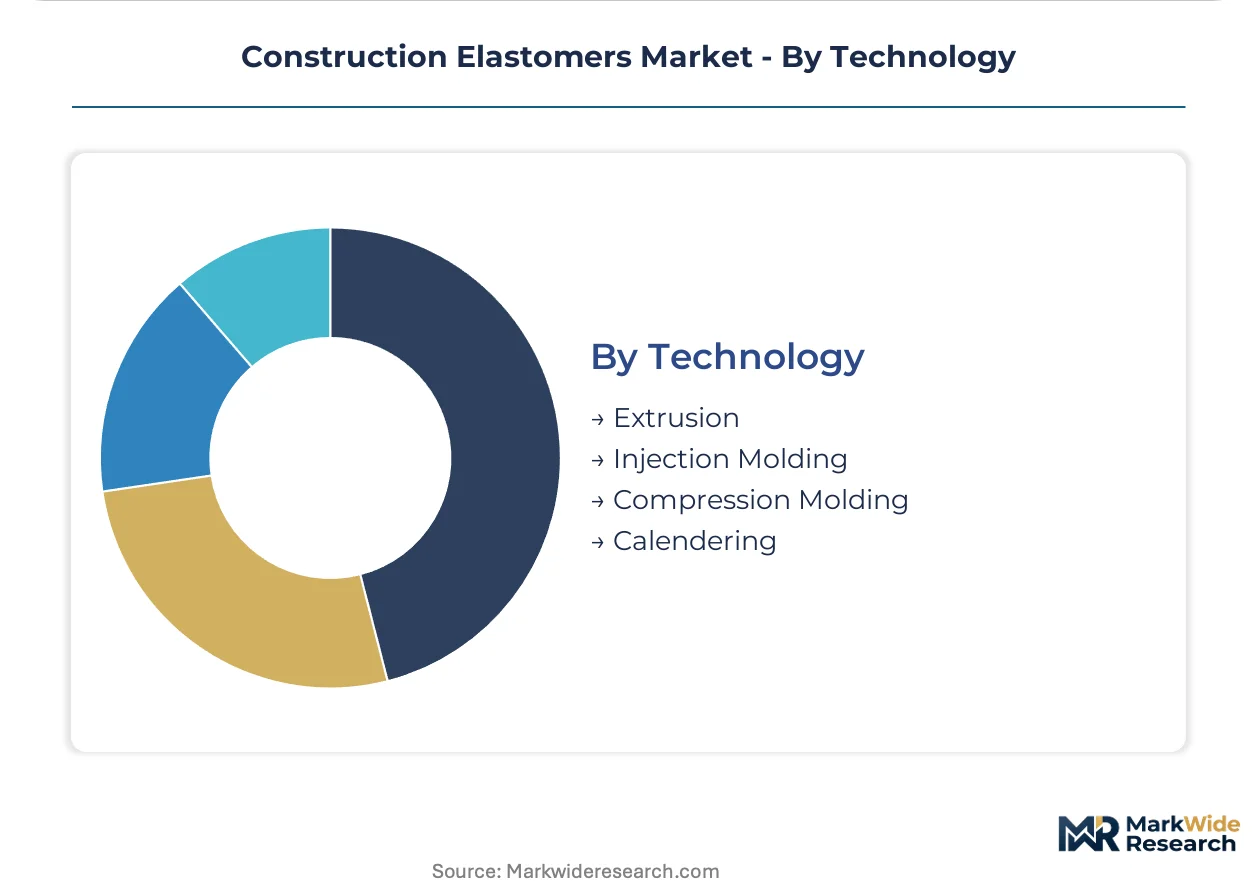
Technology:
Processing maturity separates high-volume standardized output from low-volume custom fabrication.
- Extrusion:Continuous profile production for gaskets, tubing, and weatherstripping. Window and door manufacturers specify extruded EPDM and TPV profiles for consistent dimensional tolerance across long production runs.
- Injection Molding:High-speed cavity filling for complex three-dimensional parts. Cycle time advantages of 40 to 60 percent versus compression molding capture margin pools in construction hardware components.
- Compression Molding:Matched-die forming for large-section parts requiring controlled density. Bridge bearing pads and rail pads specify compression-molded natural rubber compounds for uniform stress distribution.
- Calendering:Sheet forming for membrane and flooring applications requiring precise gauge control. PVC and TPO roofing membrane producers rely on calendering lines for consistent thickness across wide web widths.
Injection molding is climbing fastest; compression molding retains infrastructure dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions creates arbitrage opportunities where formulation costs vary by compliance burden. Production footprints are shifting toward markets with lower chemistry disclosure thresholds while specification-grade demand concentrates in jurisdictions with stringent durability mandates.
China
Urban residential clusters in tier-two cities absorb polyurethane waterproofing membrane volumes at scale. SAMR-administered GB standards for elongation retention and tensile performance filter import eligibility and shape domestic formulation priorities. The Yangtze River Delta manufacturing corridor hosts compounding facilities serving both local infrastructure and export markets.
Germany
Industrial flooring specifications in automotive-adjacent plants demand low-VOC polyurethane systems with documented cradle-to-gate carbon profiles. REACH registration tiers and EU Green Deal embodied carbon tracking pressure suppliers to maintain ECHA-registered supply chain documentation. The North Rhine-Westphalia petrochemical corridor anchors specialty polyol production for downstream construction sealant compounders.
United States
Commercial construction specifications filter elastomer selection through LEED certification requirements that favor low-VOC formulations. EPA regulations on volatile organic compound content in architectural coatings and sealants constrain formulation flexibility for domestic manufacturers. The Gulf Coast petrochemical complex supplies propylene oxide feedstocks to polyurethane system houses serving residential and infrastructure end-uses.
India
New residential construction in tier-one and tier-two cities drives waterproofing membrane demand as building code enforcement tightens. BIS standards for building materials create compliance pathways that domestic compounders navigate more efficiently than importers. The Gujarat chemical manufacturing belt houses expanding synthetic rubber capacity targeting regional infrastructure buildouts.
Indonesia
Megaproject infrastructure pipelines in Jakarta and Surabaya underutilize specification-grade waterproofing relative to regional peers. The country's national standards body administers building material certifications that create entry barriers for foreign membrane suppliers without localized technical service. Southeast Asian petrochemical producers are expanding synthetic rubber output to serve this demand pool.
Construction Elastomers Market Vendor Landscape
German and Benelux petrochemical corridors anchor one tier of specialty polyol supply; Asia-Pacific compounders hold volume positions in standardized sealant applications. The vendor base stratifies between integrated petrochemical houses with in-house analytics capabilities and regional compounders serving price-sensitive residential segments. Three archetypes dominate: backward-integrated polyurethane system suppliers, bio-based specialty grade developers, and extrusion-focused profile manufacturers. Competitive moves center on geographic footprint expansion to capture localized specification access and portfolio diversification into adjacent adhesive and coating chemistries.
Among European integrated suppliers, BASF SE anchors positions through proximity to German industrial flooring markets. Dow exemplifies backward integration strategies through captive propylene oxide feedstock positions. Arkema SA occupies the specialty tier with bio-based polyamide elastomer grades targeting sustainability procurement rules in European public tenders.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Arkema |
| DuPont |
| Covestro |
| Huntsman International LLC |
| Lubrizol Corporation |
| Evonik Industries |
| ExxonMobil Chemical |
| Others |
Supply Flow & Price Mechanics
Specification-grade certification divergence separates REACH-registered European suppliers from commodity compounders in Asia-Pacific, manifesting in both price premiums for documented cradle-to-gate carbon profiles and supply chain configurations that concentrate specialty polyol production in German and Benelux corridors while standardized sealant manufacturing disperses across Chinese coastal provinces.
Pricing Analysis
Distributor margins compress pricing transparency for construction elastomers, with direct-to-infrastructure-contractor contracts commanding 15-20 point discounts versus spot market transactions. Three-tier pricing structure across premium, standard, and economy levels filters through certification grade and volume scale, with EPDM rail pad specifications bearing least price sensitivity due to validated fatigue-life requirements. Cost compression in commodity thermoplastic elastomer grades is intensifying because Southeast Asian synthetic rubber capacity expansion outpaces regional demand absorption.
Supply Chain Analysis
Workforce availability constraints in China's Yangtze River Delta manufacturing corridor and India's Gujarat chemical belt are forcing automation investments that reshape unit economics at scale. Geographic supply concentration centers on China, Germany, and the United States for polyurethane system houses, with propylene oxide feedstock sourcing drawing from Gulf Coast and North Rhine-Westphalia petrochemical complexes. Single-source vulnerability during European turnaround seasons exposes downstream compounders to specialty polyol allocation risk. Distribution runs through regional distribution centers serving specification-grade infrastructure contractors and bulk tanker deliveries for residential waterproofing volume plays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction elastomers constitute a late-cycle quality story as infrastructure procurement offices shift specification authority toward contractors demanding documented multi-decade fatigue resistance.
For Market Incumbents: Extend ECHA-registered supply chain documentation investments to capture EU Green Deal embodied carbon tracking mandates that filter public tender access. Deepen backward integration into propylene oxide feedstocks to defend margin stability against raw material volatility. Counter thermoplastic elastomer substitution threats in sealant applications by emphasizing validated service-life performance in bridge expansion joint specifications. For New Entrants and Emerging Players: Indonesian infrastructure contractors represent an underserved buyer archetype with underpenetrated waterproofing specification relative to regional peers. Establish localized technical service capabilities to navigate national standards body certification barriers that exclude foreign membrane suppliers. Target reactive hot-melt polyurethane adhesive systems for tunnel gasket refurbishment where rapid return-to-service demands modularize supplier value capture. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and ECHA analytics investments concentrate specification access among integrated petrochemical houses with in-house capabilities. Long-term viability favors acquisition targets with bio-based polyamide development pipelines aligned to tightening European sustainability procurement rules. Monitor Indonesian megaproject award announcements as inflection indicators for regional waterproofing membrane demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Dow's captive feedstock strategy secures margin stability against propylene oxide price volatility. |
| REACH Registration Tier Advancement | BASF's ECHA-registered supply chain documentation captures EU public tender preference. |
| Bio-Based Polyamide Grade Development | Arkema's renewable feedstock positioning navigates tightening European sustainability specifications. |
| Indonesian Technical Service Localization | First-mover membrane suppliers gain specification access in underpenetrated megaproject pipelines. |
| Injection Molding Technology Migration | Cycle time advantages of 40-60 percent reshape unit economics for standardized construction components. |
Methodological Framework
Multiple input streams — technical specification databases, customs trade records, and regulatory filing repositories — were reconciled through structured primary interviews with plant managers at polyurethane system houses, procurement leads at infrastructure contractors, distribution channel partners, and technical R&D directors at compounders. Secondary validation drew from ECHA registration databases, SAMR GB standard filings, SEC 10-K disclosures, and ACC industry reports. Bottom-up volume modeling and top-down value reconciliation triangulated market estimates across chemistry and application segments.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling spanning product chemistry, end-use concentration, application function, and processing technology dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure spending pipelines and residential construction permit flows. Industry-specific forecast inputs included propylene oxide feedstock cost trajectories and REACH registration tier migration timelines.
Inputs from ECHA registration portals and SAMR certification databases were available through the study window; gaps in real-time Indonesian megaproject award data introduce uncertainty bands around Southeast Asian demand acceleration assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and feedstock capacity expansion schedules. Material deviation in named triggers — REACH tier deadlines, propylene oxide supply disruptions, or Indonesian infrastructure procurement acceleration — warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market