
 Non Meat Ingredients Market | 2026-2036
Non Meat Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Non Meat Ingredients Market Intelligence
The shift from single-source to multi-source procurement for functional ingredients is hardening supply chain requirements for processors. Kerry Group plc leverages its extensive portfolio of flavorings and texturizers to serve diverse food applications. Ingredion specializes in plant-based proteins and starches, critical for meat alternative formulations. Meanwhile, Cargill controls significant parts of the raw material supply chain, from soy to pea protein, giving it a cost advantage.
Non-meat ingredients are functional additives and components used to improve the sensory, structural, and nutritional profiles of food products, especially in meat-free formulations. These include hydrocolloids for texture modulation and protein isolates with specific water-holding capacities. Vegetable protein represents the largest ingredient type by volume, driven by the expansion of the meat alternatives application segment. Flavorings and texturizers, though smaller in volume, command higher margins due to their direct impact on final product taste and consumer acceptance.
Regulatory frameworks like the FDA's GRAS notifications in the United States and the EFSA's novel food authorization process in Europe govern market entry for new ingredients. In parallel, China's GB standards for food additives dictate permissible use levels and purity criteria for all products sold locally. Suppliers must navigate these complex, country-specific approvals while adapting to consumer demands for clean-label and transparently sourced components.
Market Dynamics
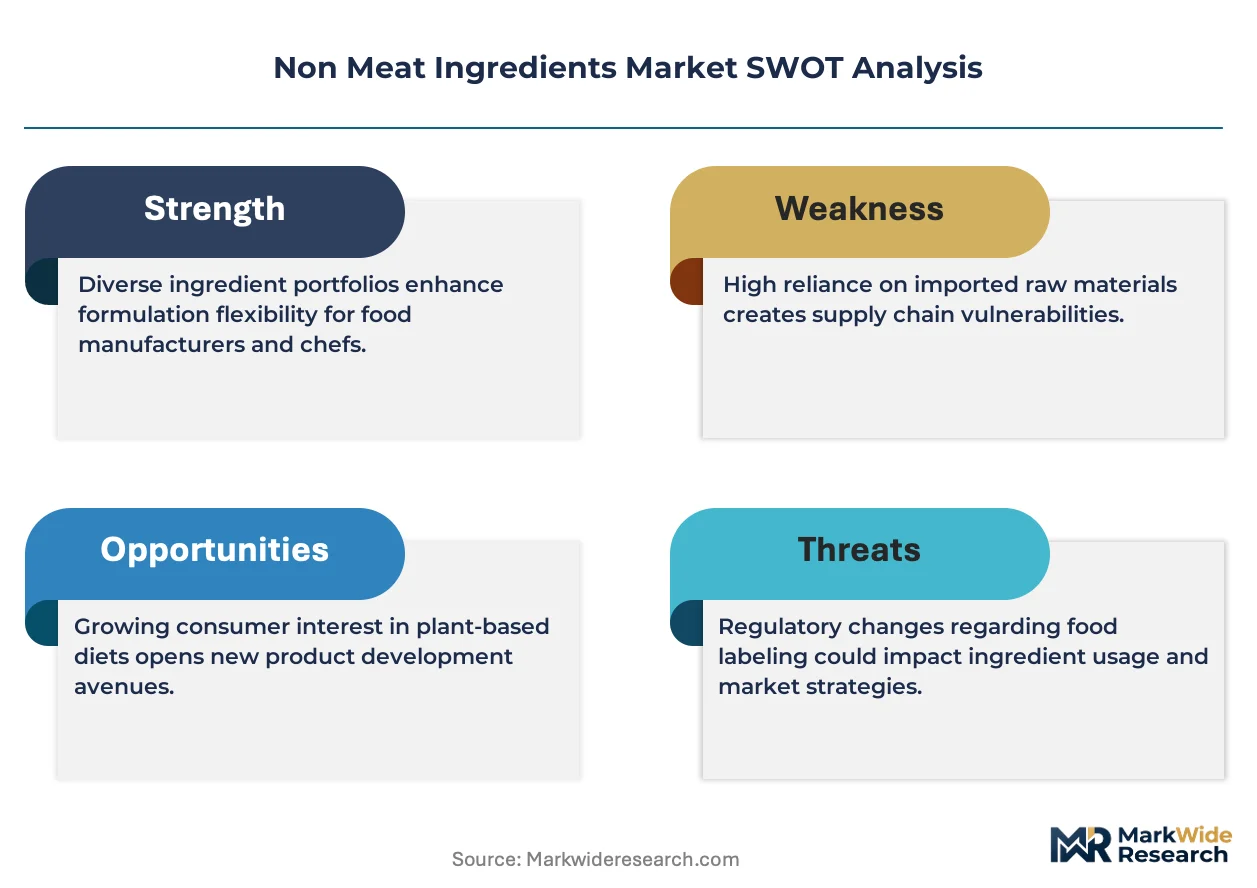
The bifurcation of the market into high-volume, commoditized proteins and high-margin, specialized functional ingredients is forcing processors to manage increasingly complex supply chains. This dynamic requires suppliers to offer both scale in core proteins and specialized R&D in texturizers and flavors.
Growth Catalysts
- High-Moisture Extrusion:This technology enables the creation of fibrous, meat-like textures from vegetable proteins, directly supporting the expansion of the plant-based whole-muscle-style product category and increasing ingredient offtake.
- Clean-Label Consumer Demand:European and North American consumer preference for transparent, minimally processed foods pushes manufacturers to source non-GMO, allergen-free ingredients, creating a premium for certified hydrocolloids and starches.
- Plant-Based Seafood Alternatives:The emerging application for seafood analogues requires novel ingredient combinations, including specific algae-based hydrocolloids and flavor systems, to mimic the texture and taste of fish and shellfish.
Market Restraints
- Input Cost Volatility:Prices for key raw materials, particularly pea and soy proteins, are subject to significant fluctuations based on weather events in primary cultivation regions, crop yields, and global trade policies.
- Sensory Gap:Current texturization and flavoring technologies struggle to perfectly replicate the complex sensory profile, particularly the fat mouthfeel and cooking behavior, of conventional animal-based meat products.
- Regulatory Delays:The European Food Safety Authority's (EFSA) comprehensive novel food authorization process, while ensuring safety, can significantly extend the time-to-market for innovative ingredients like new protein isolates or fermentation-derived components.
Strategic Opportunities
- Geographic Expansion:Significant white space exists in markets like South Korea and Australia, where consumer interest in plant-based diets is rising faster than the local availability of sophisticated non-meat ingredient manufacturing.
- Dairy Alternative Ingredients:Developing specialized emulsifiers, fat mimetics, and protein isolates tailored for plant-based cheese and yogurt applications addresses a major formulation challenge in a high-growth adjacent category.
- AI-Powered Formulation:Utilizing artificial intelligence to model ingredient interactions can accelerate the R&D process for creating new flavor and texture systems, reducing trial-and-error and shortening development cycles for food manufacturers.
Industry Challenges
- Specialized Talent Scarcity:A shortage of food scientists and engineers with dual expertise in plant protein chemistry and the operation of advanced processing equipment like high-moisture extruders limits production scale-up.
- Global Compliance Burden:Navigating disparate regulatory frameworks, such as the FDA's GRAS notification system in the US versus China's prescriptive GB standards for food additives, creates complexity for global ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Meat Ingredients Market |
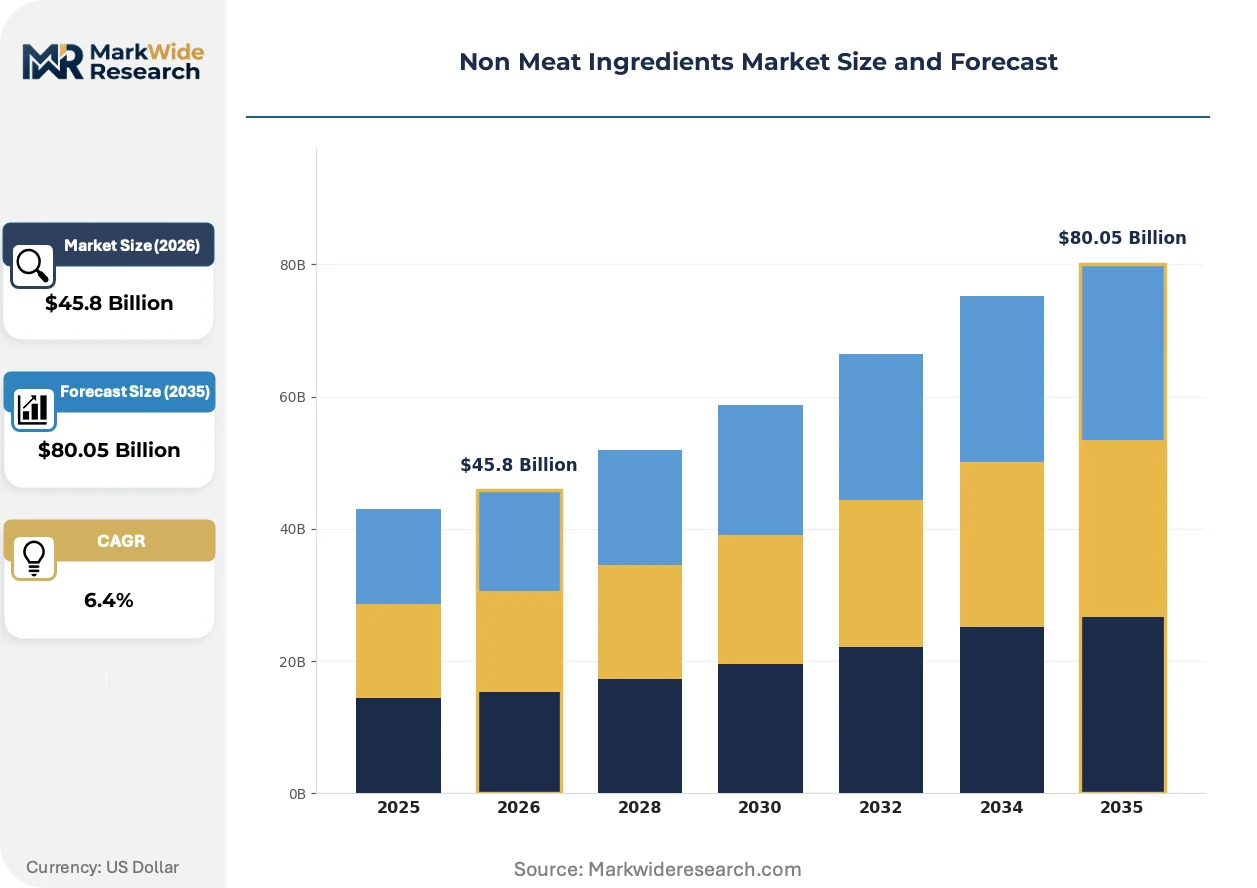
| Market Size in 2026 | $45.8 Billion |
| Market Size in 2035 | $80.05 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Starch, Vegetable Protein, Flavorings, Texturizers Application: Meat Alternatives, Sauces, Seasonings, Processed Foods Form: Powder, Liquid, Granules, Gel Source: Plant-Based, Fermented, Seaweed, Others |
| Companies Covered | Kerry Group plc, Ingredion, Associated British Foods plc, Archer Daniels Midland Company, Cargill, BASF SE, DSM, International Flavors & Fragrances Inc., Wenda Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Meat Ingredients Market Strategic Shifts & Innovations
A convergence of material science and computational chemistry is redefining ingredient functionality. This shift moves development beyond simple substitution toward creating novel textures and flavors from the molecular level, driven by consumer demand for both sustainability and sensory parity.
Precision fermentation is a biomanufacturing process that produces specific, high-value proteins or fats without animal agriculture. Food technology firms and major CPGs are adopting this method to create bio-identical ingredients like whey, casein, and lipids for next-generation products. This production technique is absorbing R&D investment previously focused on basic plant protein texturization, promising higher fidelity in the final food item.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates extensive disclosure on environmental impacts throughout the supply chain. This forces ingredient suppliers to provide verifiable data on the carbon footprint and water usage associated with raw materials like soy and peas. The flavorings and texturizers segment is most affected, as sustainability metrics become a key point of competition, influencing procurement by food processors in Germany and the Netherlands.
Food manufacturers are actively diversifying their ingredient procurement away from single-supplier dependencies for critical inputs like hydrocolloids and protein isolates. This de-risking strategy is replacing long-term exclusive contracts with a more flexible portfolio approach, blending multiple suppliers to balance cost, innovation, and supply chain security. The trend is most visible in the North American meat alternatives sector, where processors aim to mitigate risks from crop failures or trade disputes.
Non Meat Ingredients Market Segmentation
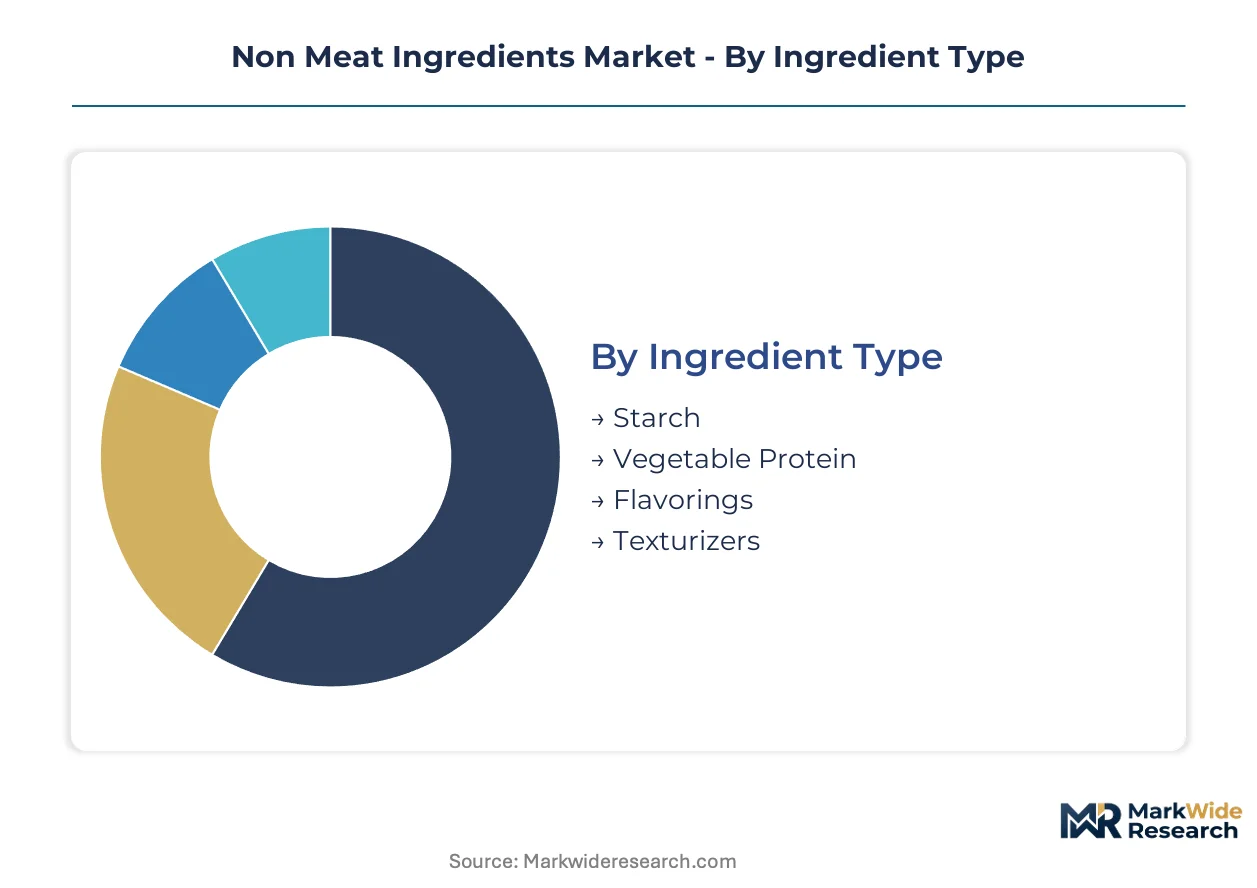
Understanding the varied requirements of food manufacturers and consumers necessitates a granular view of the non-meat ingredients market. This segmentation analysis dissects the market by ingredient type, application, physical form, and source, highlighting the distinct drivers and challenges within each category.
Ingredient Type:
Buyers in the non-meat ingredients market differentiate their sourcing based on the specific functional attributes and cost-effectiveness required for their final product formulations.
- Vegetable Protein:These ingredients, derived from sources like soy, pea, and wheat, provide essential amino acids and structural integrity to meat alternatives. Demand is concentrating in European markets, driven by the expansion of plant-based burger and sausage production, which relies heavily on texturized vegetable proteins.
- Flavorings:These compounds impart specific tastes and aromas, crucial for mimicking traditional meat profiles and enhancing sensory appeal in plant-based products. European consumers' preference for authentic taste experiences drives innovation in natural flavor systems, commanding higher margins for specialized solutions.
- Starch:Starches serve as thickeners, binders, and texturizers, providing viscosity and stability in various food systems.
- Texturizers:These additives modify the mouthfeel and structure of food products, essential for replicating the fibrous texture of meat.
Vegetable protein leads volumes today; flavorings are gaining share fastest.
Application:
The functional requirements for non-meat ingredients vary significantly across different food applications, dictating specific formulation needs for manufacturers.
- Meat Alternatives:This segment encompasses plant-based burgers, sausages, and whole-muscle analogues, requiring complex combinations of proteins, texturizers, and flavorings. Innovation in high-moisture extrusion technology directly supports the expansion of this application, particularly in North America.
- Processed Foods:This broad category includes convenience meals, snacks, and baked goods, where non-meat ingredients enhance nutritional value, texture, and shelf life. Consumer demand for clean-label options influences ingredient selection in this segment, favoring naturally derived hydrocolloids.
- Sauces:Non-meat ingredients like starches and hydrocolloids contribute to desired viscosity, stability, and emulsification in various sauce formulations.
- Seasonings:Flavorings and spices, often combined with carriers like starches, form the core of seasoning blends for diverse food products.
Meat alternatives represent the largest application, with processed foods maintaining consistent demand.
Form:
Ingredient form profoundly influences handling, storage, and processing efficiency for food manufacturers, impacting supply chain logistics and final product characteristics.
- Powder:Powdered ingredients offer high concentration, extended shelf life, and ease of transport, making them ideal for bulk handling and dry blending applications. The prevalence of protein isolates and starches in this form supports their widespread use in diverse food production facilities.
- Liquid:Liquid ingredients provide precise dosing capabilities and can be easily integrated into wet formulations, often used for flavorings, emulsifiers, and some hydrocolloids. Their application in beverages and dairy alternatives is notable for consistency.
- Granules:Granular forms offer improved flowability and reduced dusting compared to powders, beneficial for certain mixing and handling processes.
- Gel:Gel-based ingredients, typically hydrocolloids, provide specific textural properties and water-holding capacity, often used in confectionery and dairy alternative products.
Powdered forms dominate for ease of transport and storage, while liquid ingredients offer precise dosing capabilities.
Source:
The origin of non-meat ingredients determines not only their chemical composition but also their sustainability profile and regulatory approval pathways.
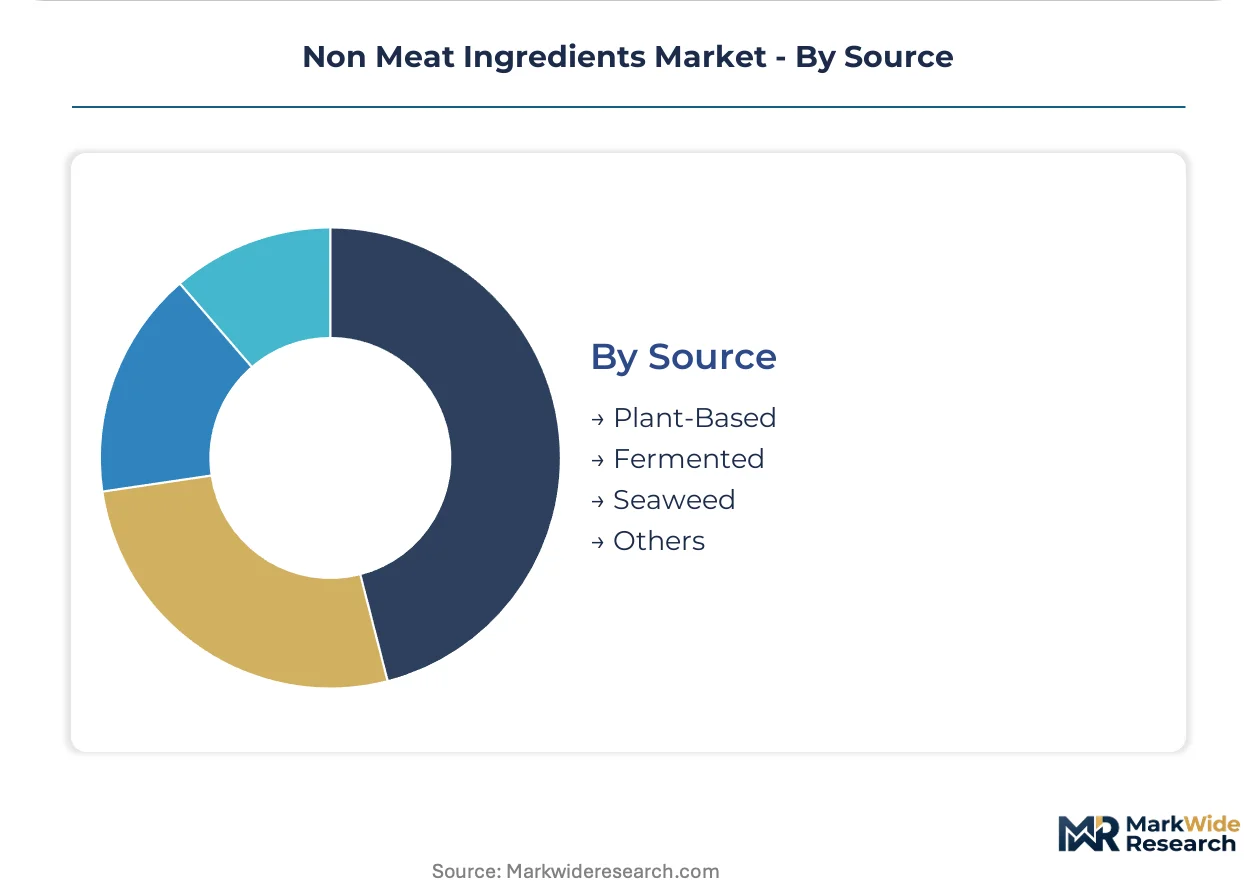
- Plant-Based:Derived from crops like soy, pea, wheat, and rice, plant-based ingredients are foundational for meat and dairy alternatives due to their protein content and functional versatility. Consumer preferences for sustainable diets in Germany drive significant investment in plant protein sourcing.
- Fermented:Ingredients produced through precision fermentation offer highly specific proteins, fats, or enzymes without traditional animal agriculture. This innovative source is absorbing R&D investment for bio-identical ingredients like whey and casein, promising higher fidelity in final products.
- Seaweed:Seaweed-derived ingredients, such as certain hydrocolloids, provide unique gelling and thickening properties, finding emerging applications in seafood analogues.
- Others:This category includes a range of other emerging and niche sources, such as insect proteins or cell-cultured components, under various stages of development and regulatory review.
Plant-based sources hold the largest market share, as fermentation-derived ingredients demonstrate rapid advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European food technology cluster, centered around Germany and the Netherlands, drives significant demand for non-meat ingredients, particularly in advanced plant-based formulations. Consumer preferences for sustainable and clean-label products shape ingredient procurement across these markets. North America also demonstrates robust growth in meat alternatives, influencing ingredient innovation.
Germany
German consumer preference for sustainable diets fuels strong demand for plant-based proteins and specialized texturizers. The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates extensive environmental disclosures, impacting ingredient suppliers. Northern Germany, particularly Hamburg and Berlin, concentrates food tech startups and ingredient innovation hubs.
Netherlands
The Netherlands exhibits high demand for plant-based food products, driving innovation in ingredient functionality. The European Food Safety Authority's (EFSA) novel food authorization process governs market entry for new ingredients. Wageningen Food Valley serves as a prominent research and development cluster for alternative proteins and food science.
United States
The United States meat alternatives sector expands rapidly, increasing ingredient off-take for proteins and flavorings. The FDA's GRAS notifications regulate the introduction of novel food ingredients in American markets. California's Silicon Valley and other innovation hubs attract significant investment in food technology and ingredient development.
China
China's large population and evolving dietary preferences present significant opportunities for non-meat ingredient suppliers. China's GB standards for food additives dictate permissible use levels and purity criteria for all products sold locally. Major food manufacturing centers like Shanghai and Guangzhou drive demand for both bulk proteins and functional ingredients.
South Korea
South Korean consumer interest in plant-based diets is rising, creating white space for sophisticated non-meat ingredient manufacturing. The Ministry of Food and Drug Safety (MFDS) oversees food safety regulations and ingredient approvals within the country. Seoul's vibrant food scene and emerging tech hubs foster innovation in plant-based product development.
Non Meat Ingredients Market Key Industry Players
Global majors compete with regional champions across the non-meat ingredient value chain, managing complex supply chains. The market structure is bifurcated between high-volume, commoditized protein suppliers and specialized functional ingredient providers. Strategic archetypes include diversified food ingredient conglomerates, specialized plant-based protein innovators, and raw material controllers. Competitive moves focus on portfolio diversification and geographic expansion.
Diversified food ingredient conglomerates like Kerry Group plc and Ingredion exemplify companies leveraging extensive portfolios of flavorings, texturizers, and plant-based proteins to serve diverse food applications. Cargill, a major agricultural processor, occupies a position controlling significant parts of the raw material supply chain, from soy to pea protein. These companies anchor the market through their scale and ability to offer comprehensive ingredient solutions.
| Leading Market Players |
|---|
| Kerry Group plc |
| Ingredion |
| Associated British Foods plc |
| Archer Daniels Midland Company |
| Cargill |
| BASF SE |
| DSM |
| International Flavors & Fragrances Inc. |
| Wenda Ingredients |
Cost & Logistics Intelligence
The global pea protein index directly influences ingredient pricing, cascading through the supply chain into various non-meat ingredient tiers. This volatility impacts both high-volume commoditized proteins and specialized functional ingredients.
Pricing Analysis
Input cost pass-through remains a significant challenge for non-meat ingredient processors, especially for pea and soy proteins. Pricing operates on a hybrid model, combining contract-based long-term offtake for stable volumes with commodity spot purchasing for flexibility. Price differentiation stems from ingredient purity and specific functional attributes, such as clean-label certifications for hydrocolloids. Pricing softness reflects intense competition for commoditized proteins, while specialized flavorings maintain higher margins due to their direct sensory impact. The processed foods segment exhibits higher price sensitivity for bulk ingredients compared to premium meat alternative formulations.
Supply Chain Analysis
Logistics and freight costs significantly influence the final landed price of non-meat ingredients, particularly for bulk proteins shipped globally. Supply concentrates in agricultural powerhouses like China for soy and North America for pea protein, with specialized ingredients often originating from European innovation hubs. Raw material dependencies hinge on key inputs such as pea protein, soy protein, and specialized hydrocolloids. Commodity price volatility presents a structural risk, driven by weather events and global trade policies. Distribution runs through direct sales channels from ingredient manufacturers to food processors, with some reliance on regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-meat ingredients market functions as a stable compounder, driven by the sustained global shift towards plant-based diets and demand for sustainable food options. Innovations in high-moisture extrusion technology further underpin this consistent growth trajectory.
For Market Incumbents: Cement existing market leadership by continuously investing in advanced R&D for flavorings and texturizers to close the sensory gap with animal products. Diversify ingredient portfolios beyond single-source dependencies to mitigate raw material input cost volatility. Expand manufacturing capabilities in emerging markets like South Korea to serve rising plant-based demand. This strategy defends against specialized protein innovators and addresses evolving consumer preferences for clean-label solutions.
For New Entrants and Emerging Players: Precision fermentation technology provides a significant wedge for new entrants to create bio-identical ingredients like whey and casein, targeting high-fidelity dairy alternatives. Focus on specialized algae-based hydrocolloids for plant-based seafood analogues, a nascent but high-growth application. Target white space in markets like South Korea, where sophisticated ingredient manufacturing is less developed. A go-to-market strategy leveraging AI-powered formulation accelerates product development and reduces R&D cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized plant-based protein innovators and firms possessing unique precision fermentation intellectual property. The long-term viability of this market is anchored in enduring consumer demand for sustainable diets and clean-label products. Acquisition targets should include companies with advanced high-moisture extrusion capabilities or novel algae-based ingredient portfolios. Watch for accelerated regulatory approvals for fermentation-derived proteins, particularly through EFSA and FDA GRAS notifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Moisture Extrusion | This initiative directly supports the production of fibrous meat-like textures from vegetable proteins for plant-based whole-muscle products. |
| R&D Investment in Flavor Systems | Developing authentic taste profiles is crucial for enhancing consumer acceptance of plant-based meat and dairy alternatives. |
| Geographic Market Entry in South Korea | Expanding into South Korea addresses rising consumer interest in plant-based diets within an underserved manufacturing landscape. |
| Enhanced Corporate Sustainability Reporting | Compliance with directives like the EU's CSRD becomes a key competitive differentiator for ingredient suppliers in Europe. |
| Adoption of AI-Powered Formulation Tools | Utilizing artificial intelligence accelerates the discovery and optimization of new ingredient interactions for novel food products. |
Research Approach
Coverage spans European markets, North America, and key Asian economies, drawing primary inputs from each. This analysis integrates insights from food scientists, R&D directors, procurement leads at food manufacturers, and regulatory affairs specialists. Secondary validation leverages FDA filings, EFSA novel food authorizations, China GB standards, and corporate sustainability reports. Bottom-up and top-down triangulation ensures data accuracy.
Market granularity was modeled across ingredient type, application, source, physical form, and regional demand to capture distinct dynamics. The analytical framework projects market expansion throughout the forecast period, with compound annual growth rates derived from historical trends and future innovation pipelines. Key forecast inputs include consumer preference for sustainable diets and high-moisture extrusion adoption rates.
The model holds under current regulatory frameworks and sustained consumer demand; deviation in input cost volatility or significant regulatory changes would shift projections. Forecasts reflect documented assumptions regarding technological adoption. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bleached Flour Market
Ingredients
Orange Powder Market
Ingredients
Fats and Oils Market
Ingredients
Cheese Powder Market
Ingredients
China Gelatin Market
Ingredients
Interesterified CBE Market
Ingredients
Hen Egg White Protein Market
Ingredients
Lentils Flour Market
Ingredients
Baobab Powder Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
Bean Pasta Market
Ingredients
Mung Bean Starch Market
Ingredients
Salt Market
Ingredients
Cocoa Liquor Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market