
 Cheese Powder Market | 2026-2036
Cheese Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Powder Market Intelligence
Custom blending and formulation services is rebalancing how cheese powder suppliers capture value beyond commodity sales. Kerry Group leverages its technical application centers to anchor long-term contracts with snack manufacturers. Lactosan A/S specializes in clean-label and organic cheese powder variants for European food brands. The Kraft Heinz Company dominates retail seasoning blends through its extensive grocery channel control.
Cheese powder consists of dehydrated cheese solids produced through spray-drying or roller-drying of processed cheese slurries, typically containing 35-65% actual cheese content with carriers such as whey or maltodextrin. The ingredient delivers concentrated dairy flavor, fat, and protein to formulations where fresh cheese proves impractical due to moisture constraints or shelf-life requirements. Cheddar powder leads volume in North American snack seasoning applications where bold flavor profiles command premium positioning. Ready-to-eat Meals represent the fastest-growing application as frozen and shelf-stable meal producers seek authentic cheese taste without refrigeration dependency. Parmesan powder occupies a distinct margin pool within Italian-themed product lines where protected designation of origin claims support price premiums.
The FDA oversees cheese powder labeling under its standardized identity requirements for processed cheese products, while the USDA regulates dairy ingredient procurement through its grading and inspection protocols. EFSA evaluates novel enzymatic modification processes that alter cheese powder flavor intensity and functional performance. Food manufacturers must monitor evolving sodium reduction mandates from Health Canada and the FDA, as these directly constrain formulation flexibility in cheese-based seasonings. Stakeholders should track which suppliers invest in microencapsulation technologies that mask salt perception without sacrificing the umami depth that drives consumer repeat purchases.
Market Dynamics
Clean-label reformulation mandates from the EU's Food Information to Consumers regulation are forcing cheese powder suppliers to re-engineer carrier systems and disclosure protocols, compressing formulation timelines while opening premium positioning for transparent ingredient decks.
Growth Catalysts
- Clean-label mandates:The EU's updated Food Information to Consumers regulation tightens allergen disclosure requirements for dairy-derived ingredients, accelerating supplier investment in traceable sourcing systems and natural carrier alternatives.
- Enzymatic modification:Novel enzymatic processes evaluated by EFSA are intensifying cheese powder flavor profiles without sodium load expansion, enabling snack manufacturers to meet Health Canada sodium reduction targets.
- Quick-service restaurant procurement:United States-based quick-service chains are consolidating bulk seasoning procurement through long-term technical partnerships, locking in volume commitments that stabilize supplier capacity planning.
Market Restraints
- Dairy input volatility:Whey and milk solid prices fluctuate with commodity dairy cycles, compressing margins for standardized powder grades that cannot pass through cost spikes.
- Supply concentration risk:Cheddar powder production clusters in Wisconsin and California processing corridors, creating geographic vulnerability to climate-driven milk supply disruptions.
- Fresh cheese substitution:Refrigerated distribution improvements and extended shelf-life packaging technologies enable fresh cheese use in applications previously reserved for dehydrated alternatives.
Strategic Opportunities
- Microencapsulation technology:Salt perception masking through lipid-shell encapsulation is converging with umami enhancement protocols, creating patentable formulation platforms for reduced-sodium snack seasonings.
- Protected designation of origin:Parmigiano-Reggiano powder commands margin premiums in Italian-themed product lines where authenticity claims support pricing power unavailable to generic hard cheese alternatives.
- Ready-to-eat meal penetration:Frozen and shelf-stable meal producers in Germany and France are adopting cheese powder to deliver authentic dairy taste without cold-chain dependency, expanding addressable application scope.
Industry Challenges
- Application technical talent scarcity:Spray-drying optimization and carrier compatibility expertise concentrates among legacy dairy scientists, constraining formulation service expansion at mid-tier suppliers.
- Dual certification timelines:Simultaneous USDA grading compliance and FDA processed cheese identity standard verification extends new product qualification cycles, delaying contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Powder Market |
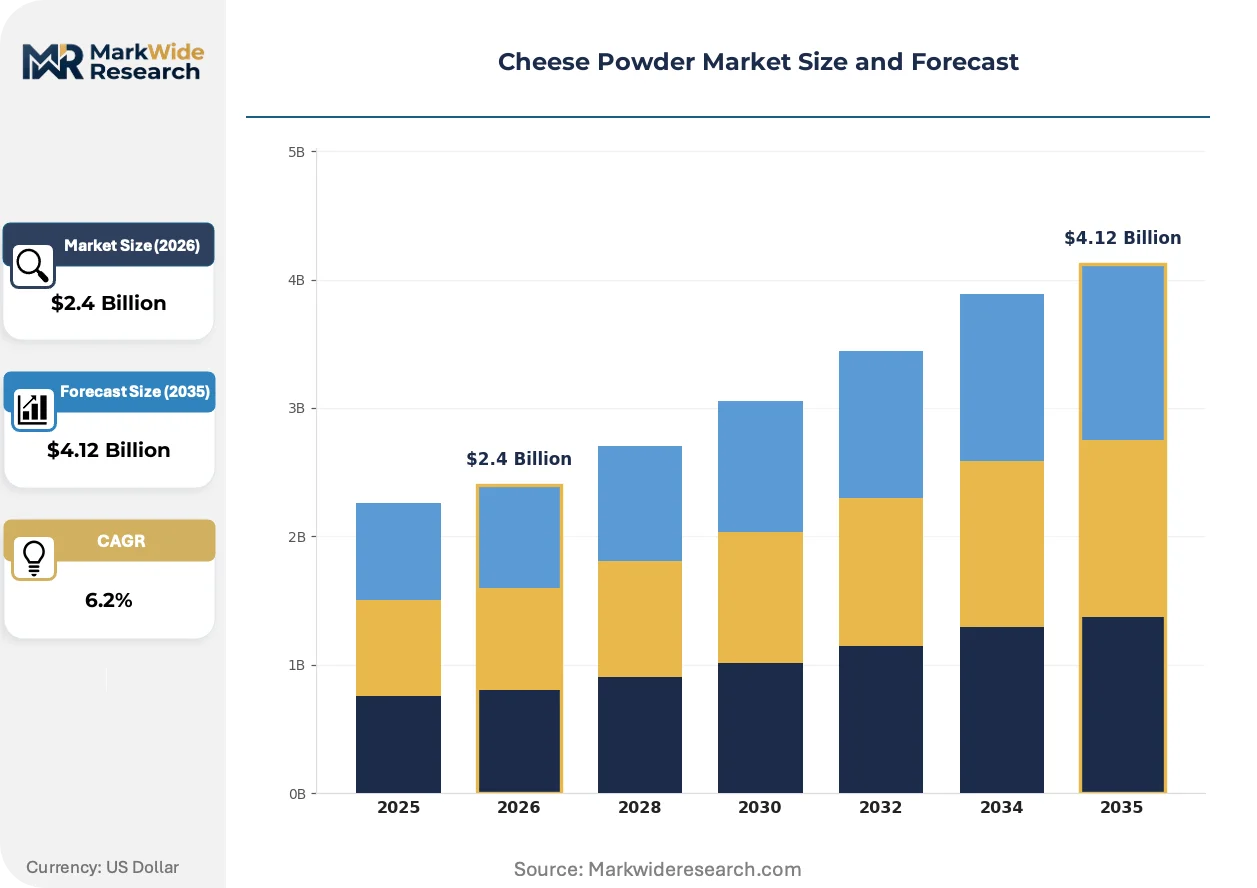
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Parmesan, Gouda Application: Snacks, Seasonings, Sauces, Ready-to-eat Meals End User: Food Manufacturers, Restaurants, Bakeries, Households Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Land O'Lakes, Inc., Kerry Group, Fonterra Co-operative Group, Lactosan A/S, The Kraft Heinz Company, Archer Daniels Midland, Commercial Creamery Company, Aarkay Food Products Ltd., DairiConcepts, L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Powder Market Strategic Shifts & Innovations
Processing technology advances and regulatory disclosure requirements are reshaping how cheese powder suppliers capture value, with formulation services displacing commodity trading as the primary margin engine.
Microencapsulation technology is converging with enzymatic flavor enhancement to create reduced-sodium cheese powders that maintain consumer repeat purchase rates. Snack seasoning manufacturers in the United States are adopting these systems fastest, driven by FDA sodium reduction guidance and quick-service chain procurement specifications. This convergence is compressing the competitive advantage of legacy commodity powder suppliers while rewarding technical application centers with multi-year exclusive supply agreements.
REACH and RoHS compliance frameworks in Europe are extending chemical disclosure requirements to food contact materials and processing aids used in cheese powder manufacturing. Industrial consequence includes mandatory substitution of certain anti-caking agents and modified starch carriers. Clean-label European food brands are responding by qualifying organic-certified powder variants from specialized Danish and Dutch suppliers, shifting procurement criteria toward full supply chain transparency.
Buyer concentration among multinational snack and convenience food manufacturers is consolidating technical service relationships around fewer, deeper partnerships. Regional mid-tier processors are losing access to premium formulation support as application engineering resources concentrate at top-three global suppliers. This pattern is most visible in North American snack seasoning procurement, where bulk volume commitments now bundle R&D collaboration rights into multi-year supply contracts.
Cheese Powder Market Segmentation
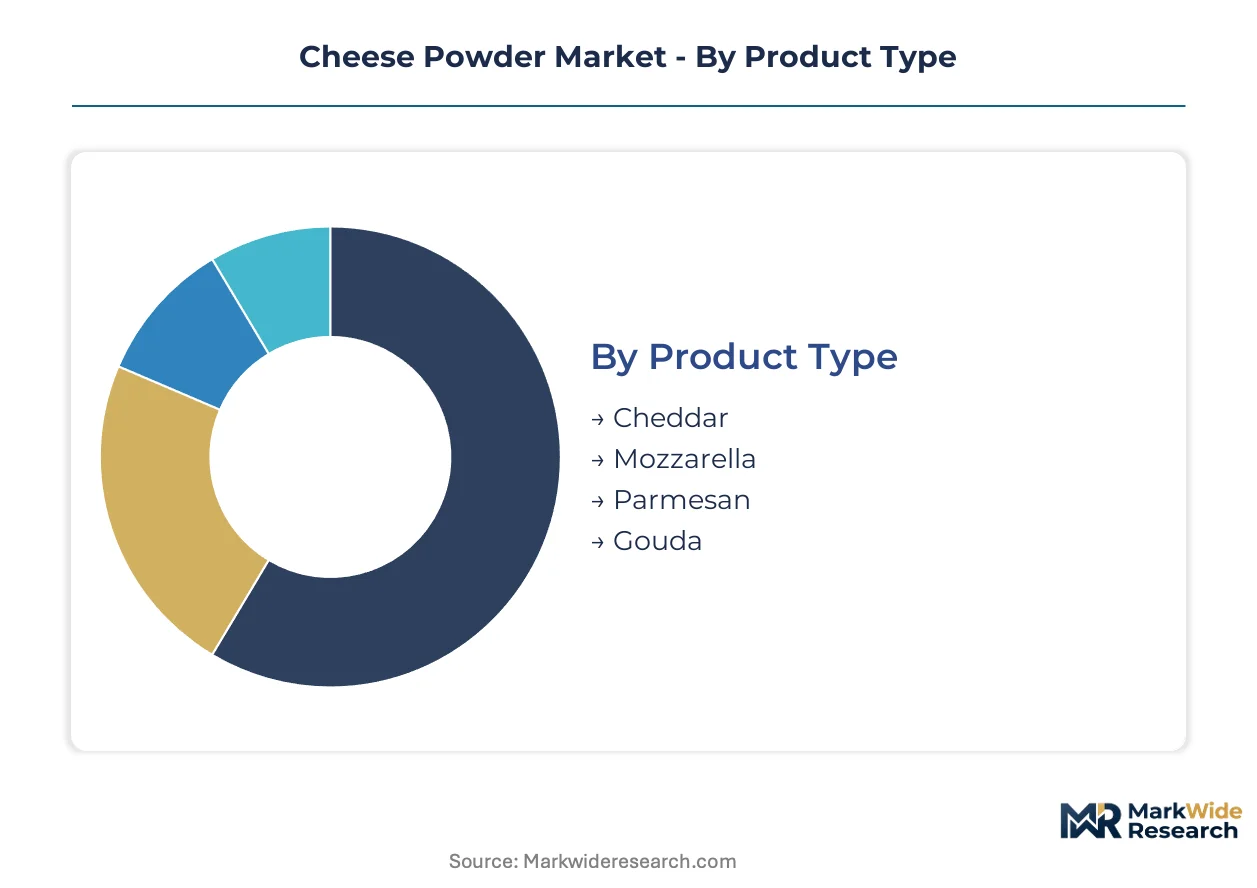
Cheese powder segmentation reveals how formulation requirements and procurement scale fragment demand across distinct value pools. Technical specifications, cold-chain constraints, and buyer scale determine which powder variants capture margin premiums versus commodity positioning.
Product Type:
Flavor intensity and melting behavior separate buyers seeking bold snack seasoning from those requiring stretchable pizza applications or granular pasta topping.
- Cheddar:Spray-dried powders with 40-60% actual cheese content deliver sharp flavor profiles optimized for North American snack coatings. Quick-service restaurant chains in the United States consolidate bulk procurement around Wisconsin-sourced cheddar variants, locking in multi-year technical partnerships that stabilize supplier capacity planning.
- Parmesan:Hard-grating cheese powders with protected designation of origin claims command authentic positioning in Italian-themed product lines. European meal kit producers in Germany and France specify Parmigiano-Reggiano powder to satisfy transparency mandates under the EU's Food Information to Consumers regulation.
- Mozzarella:Low-moisture pizza cheese powders with controlled melt elasticity serve frozen food manufacturers seeking stretch simulation without refrigeration dependency.
- Gouda:Smoked and aged variants target premium European snack brands requiring differentiated flavor positioning in saturated retail categories.
Volume sits with Cheddar; growth tilts toward Parmesan as authenticity claims harden into procurement specifications.
Application:
Moisture tolerance and shelf-stability requirements dictate whether buyers prioritize flavor concentration or functional performance in hydrated systems.
- Snacks:Coating-grade powders with optimized adhesion properties bind to fried and baked substrates through oil-based slurry application. Seasoning manufacturers specify enzymatically modified cheddar variants to intensify umami perception while complying with FDA sodium reduction guidance.
- Ready-to-eat Meals:Freeze-thaw stable powders with encapsulated fat systems prevent syneresis in frozen pasta and casserole applications. Shelf-stable meal producers adopt these formulations to eliminate cold-chain costs in European retail distribution.
- Seasonings:Fine-grind powders with instant dispersibility blend into dry rubs and tabletop shakers for household and foodservice use.
- Sauces:Agglomerated powders with rapid reconstitution properties hydrate into smooth cheese sauces without lump formation in industrial kettle systems.
Snacks dominate current offtake; ready-to-eat meals are climbing the fastest as frozen and shelf-stable formats expand.
End User:
Technical service requirements and volume scale separate enterprise buyers with dedicated formulation support from price-sensitive spot purchasers.
- Food Manufacturers:Multinational snack and convenience food producers demand application engineering resources bundled into supply contracts. Kerry Group anchors long-term agreements through technical centers that customize carrier systems and flavor intensity to specific production lines.
- Restaurants:Quick-service chains standardize bulk seasoning procurement across franchise networks, requiring consistent lot-to-lot performance and allergen documentation.
- Bakeries:Artisan and industrial bakers source smaller volumes of specialty powders for stuffed bread and savory pastry applications.
- Households:Retail-packaged cheese powders serve home cooking and emergency pantry stocking through grocery and e-commerce channels.
Food manufacturers command volume concentration; restaurants are gaining share fastest as chain expansion accelerates bulk seasoning standardization.
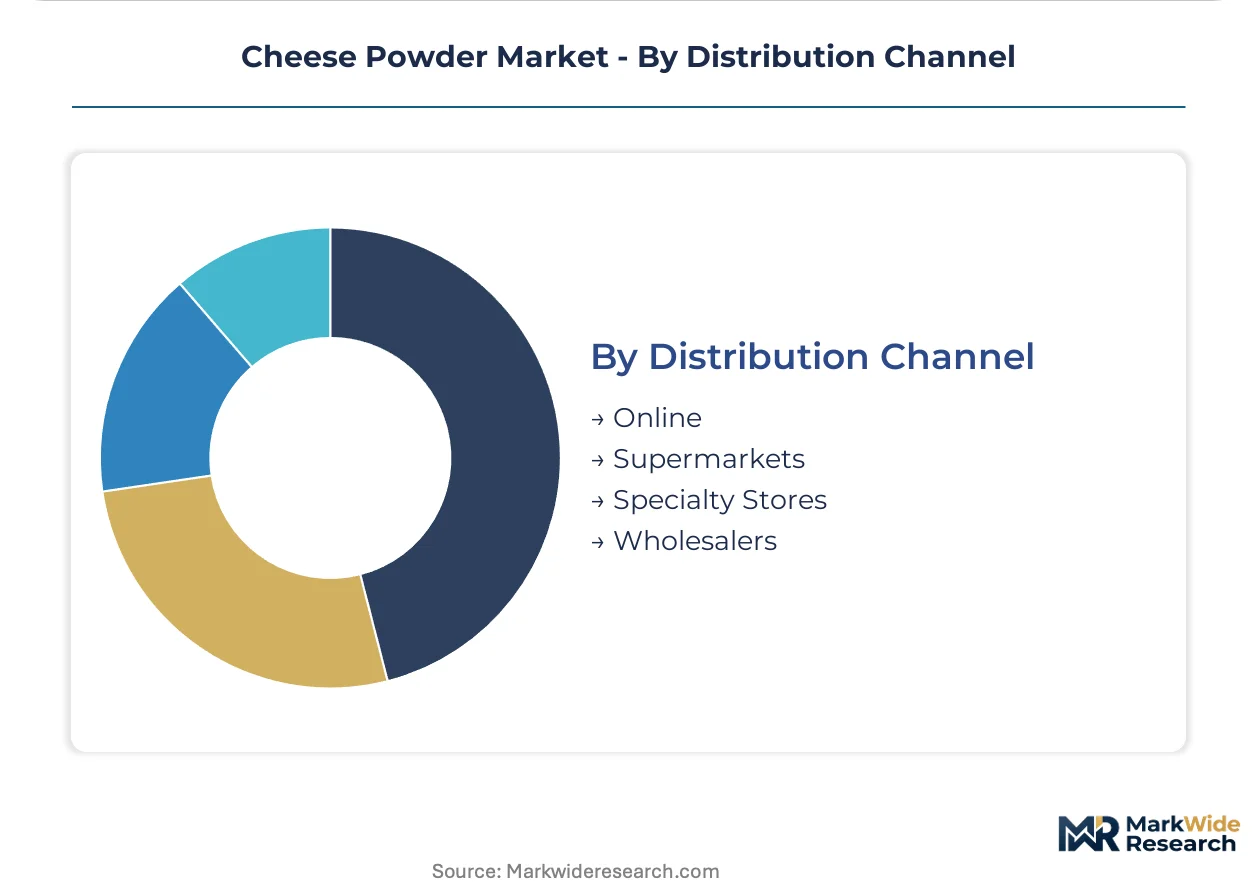
Distribution Channel:
Order size and technical consultation needs determine whether buyers access powders through direct supplier relationships or intermediated retail and wholesale pathways.
- Wholesalers:Broadline foodservice distributors consolidate procurement for mid-tier restaurants and institutional kitchens, bundling cheese powder with complementary dairy ingredients. These intermediaries absorb inventory risk and provide just-in-time delivery that smaller operators cannot negotiate directly.
- Online:Direct-to-manufacturer e-commerce platforms enable specialty powder sourcing with transparent certification documentation. Clean-label European brands qualify organic-certified variants through specialized Danish and Dutch suppliers bypassing traditional distribution layers.
- Supermarkets:Retail grocery channels move consumer-packaged cheese powders for household cooking and tabletop seasoning use.
- Specialty Stores:Gourmet and ethnic food retailers stock premium imported powders with protected designation of origin credentials.
Wholesalers anchor current throughput; online is expanding most quickly as traceability requirements push buyers toward direct supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cheese powder production clusters in Wisconsin and California, while consumption concentrates in quick-service restaurant chains across the United States and clean-label reformulation hubs in Western Europe. This geographic mismatch creates trade flows and regional specialization patterns.
United States
Quick-service restaurant chains consolidate bulk seasoning procurement through long-term technical partnerships. The FDA oversees cheese powder labeling under standardized identity requirements for processed cheese products. Wisconsin's dairy processing corridor anchors cheddar powder production, with spray-drying facilities supplying North American snack manufacturers.
Germany
Frozen and shelf-stable meal producers adopt cheese powder to eliminate cold-chain costs in retail distribution. The EU's Food Information to Consumers regulation tightens allergen disclosure rules for dairy-derived ingredients. Bavaria's food technology cluster hosts application engineering centers serving Central European convenience food brands.
France
European meal kit producers specify Parmigiano-Reggiano powder to satisfy transparency mandates under clean-label procurement criteria. EFSA evaluates novel enzymatic modification processes that alter flavor intensity. The Paris basin concentrates dairy ingredient trading and premium powder distribution for Italian-themed product lines.
Canada
Health Canada's sodium reduction mandates constrain formulation flexibility in cheese-based seasonings. Snack manufacturers adopt microencapsulation technologies to mask salt perception without sacrificing umami depth. Ontario's food processing corridor hosts reformulation service providers supporting reduced-sodium product development.
Denmark
Clean-label European food brands qualify organic-certified powder variants from specialized Danish suppliers. REACH and RoHS compliance frameworks extend chemical disclosure requirements to processing aids. Copenhagen's food ingredient cluster leads supply chain transparency initiatives for natural carrier alternatives.
Cheese Powder Market Key Industry Players
Top-tier vendors anchor technical application services, while commodity-grade suppliers compete on dairy input sourcing efficiency. The vendor base stratifies across three tiers: global dairy conglomerates with integrated powder operations, regional specialists in clean-label and organic variants, and private-label manufacturers serving price-sensitive retail channels. Strategic archetypes include formulation service providers bundling R&D collaboration into supply contracts, protected designation of origin specialists capturing authenticity premiums, and scale-driven processors optimizing spray-drying throughput. Competitive moves concentrate on multi-year exclusive supply agreements and microencapsulation technology licensing.
Within the formulation service tier, Kerry Group and Lactosan A/S represent contrasting geographic and specialization anchors. Kerry Group exemplifies the technical application center model through its global network of customer-facing innovation facilities. Lactosan A/S occupies a specialist position within the clean-label and organic variant segment, serving European food brands with transparent supply chain requirements. The Kraft Heinz Company sits within the retail channel control archetype, leveraging grocery network access for consumer-packaged seasoning blends. Fonterra Co-operative Group anchors the dairy cooperative model with backward integration into milk powder supply.
| Leading Market Players |
|---|
| Land O'Lakes, Inc. |
| Kerry Group |
| Fonterra Co-operative Group |
| Lactosan A/S |
| The Kraft Heinz Company |
| Archer Daniels Midland |
| Commercial Creamery Company |
| Aarkay Food Products Ltd. |
| DairiConcepts, L.P. |
| Others |
Cost & Logistics Intelligence
REACH and RoHS compliance frameworks in Europe gate qualified supply access and premium-tier pricing power, forcing manufacturers to substitute conventional anti-caking agents and modified starch carriers with certified-natural alternatives that command formulation service premiums from clean-label buyers.
Pricing Analysis
Cost-down pressure on commodity cheddar powder accelerates as Wisconsin and California dairy input volatility compresses margins for standardized grades unable to pass through whey and milk solid price spikes. Three-tier pricing structure across premium PDO-certified, standard commercial-grade, and economy private-label levels differentiates based on cheese content percentage and carrier system transparency. Food manufacturers with multi-year technical partnerships absorb least price sensitivity; spot-buying mid-tier snack processors face acute margin compression.
Supply Chain Analysis
Direct-to-manufacturer channels handle multinational food manufacturer demand while broadline foodservice distributors consolidate procurement for mid-tier restaurant and institutional buyers. Cheddar powder production concentrates in the United States, Denmark, and the Netherlands; enzymatic modification inputs and natural carrier alternatives draw from specialized European ingredient suppliers. Single-source vulnerability clusters in Wisconsin's dairy processing corridor where climate-driven milk supply disruptions threaten spray-drying capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a backward-integration race where control over enzymatic modification capabilities and natural carrier supply determines formulation service pricing power and multi-year contract capture.
For Market Incumbents: Acquire spray-drying optimization expertise and microencapsulation patent portfolios to defend against emerging clean-label specialists. Lock in exclusive dairy supply agreements across Wisconsin and California processing corridors to secure capacity against climate volatility. Anchor technical application centers in Bavaria and Copenhagen to capture EU Food Information to Consumers regulation-driven reformulation demand.
For New Entrants and Emerging Players: The premium-to-economy price gap in organic-certified cheese powder variants opens white-space entry for specialized Danish and Dutch suppliers with transparent supply chain credentials. Target frozen and shelf-stable ready-to-eat meal producers in Germany and France seeking authentic dairy taste without cold-chain dependency. Qualify through direct-to-manufacturer e-commerce platforms with full certification documentation to bypass entrenched wholesale distribution.
For Investors and Strategic Acquirers: Multi-year exclusive supply agreements bundling R&D collaboration rights are the leading indicator that technical application service capabilities are consolidating toward defensible margin pools. Five-to-ten year viability favors targets with backward integration into milk powder supply and enzymatic modification IP. Monitor EFSA evaluation timelines for novel flavor intensity processes as inflection signals for premium positioning windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Patent-protected salt-masking capabilities enable reduced-sodium snack seasoning contracts with FDA-compliant manufacturers. |
| Protected Designation of Origin Certification | Parmigiano-Reggiano powder authenticity claims support pricing premiums unavailable to generic hard cheese alternatives in Italian-themed lines. |
| Technical Application Center Expansion | Customer-facing innovation facilities in Bavaria and Copenhagen anchor long-term supply agreements with EU clean-label reformulators. |
| Natural Carrier System Substitution | REACH-compliant anti-caking agent replacements qualify suppliers for premium procurement from transparency-mandated European brands. |
| Backward Integration into Dairy Supply | Captive milk solid sourcing insulates margin compression from commodity whey price volatility in standardized powder grades. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across spray-drying operations managers, snack manufacturer procurement leads, dairy ingredient R&D directors, and EU regulatory affairs specialists. FDA processed cheese identity standards, EFSA novel food evaluations, USDA grading protocols, and Health Canada sodium reduction guidance provided regulatory boundary conditions. Bottom-up volume modeling across product type, application, and end-user segments converged with top-down value reconciliation from dairy commodity price indices.
Data-stream reconciliation between production capacity surveys, import-export trade flows, and customer procurement pattern analysis established baseline volume estimates across the projection horizon. Segmentation dimensions modeled include cheese variety, functional application, buyer scale tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating enzymatic technology adoption curves and clean-label reformulation mandates. Forecast inputs included quick-service restaurant chain expansion rates, frozen meal format growth, and microencapsulation technology penetration timelines.
Inputs from dairy processing trade associations and food manufacturer procurement databases were available through the study window; gaps in proprietary formulation service contract terms introduce uncertainty bands around technical application center revenue attribution. Forecasts reflect assumptions regarding EFSA evaluation timelines, EU Food Information to Consumers enforcement intensity, and sodium reduction mandate progression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Resistant Starch Market
Ingredients
Insect-Based Ingredients Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Olive Oil Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
Astragalus Root Extract Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
United Kingdom Protein Market
Ingredients
Native Starch Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Global Apricot Oil Market
Ingredients
Camelina Oil Market
Ingredients
Psyllium Husk Powder Market