
 Cocoa Liquor Market | 2026-2036
Cocoa Liquor Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Liquor Market Analysis
Artisan confectionery manufacturers is collapsing as a demand category, while industrial bakeries and beverage producers expand procurement volumes. Barry Callebaut AG anchors European processing capacity through integrated bean sourcing networks. Cargill, Incorporated dominates North American supply chains with extensive West African origination infrastructure. Mars Incorporated leverages vertical integration from farm-gate to finished chocolate, securing preferential liquor access.
Cocoa liquor is the pure, ground paste of fermented, dried, roasted, and winnowed cocoa nibs, containing approximately 50-58% cocoa butter by mass and serving as the foundational intermediate for all chocolate manufacturing. The paste undergoes hydraulic pressing or further refining to separate butter from cocoa solids, determining its ultimate application in confections or coatings. Dark chocolate applications command premium positioning due to elevated cocoa content requirements and consumer preference for intense flavor profiles. Beverage applications represent the fastest-expanding segment as specialty drinking chocolate and functional cocoa beverages gain traction in food service channels. Baking cocoa maintains mature, volume-driven demand from industrial bakeries with thinner margin structures.
FDA standards of identity in the United States prescribe minimum cocoa butter and liquor content for chocolate labeling, directly constraining formulation flexibility and ingredient substitution. The EU Deforestation Regulation and EFSA cadmium thresholds for cocoa products are tightening traceability and heavy metal compliance burdens across European supply chains. Ghana's COCOBOD and Côte d'Ivoire's Conseil du Café-Cacao administer farmgate pricing and export licensing that govern origin-country market access. Stakeholders must monitor evolving origin-country regulatory harmonization and invest in supply chain digitization to maintain compliant sourcing positions.
Market Dynamics
EU Deforestation Regulation enforcement is compressing sourcing timelines and forcing traceability infrastructure investments across European processing networks. Compliance costs are restructuring procurement relationships between origin-country regulators and downstream chocolate manufacturers.
Growth Catalysts
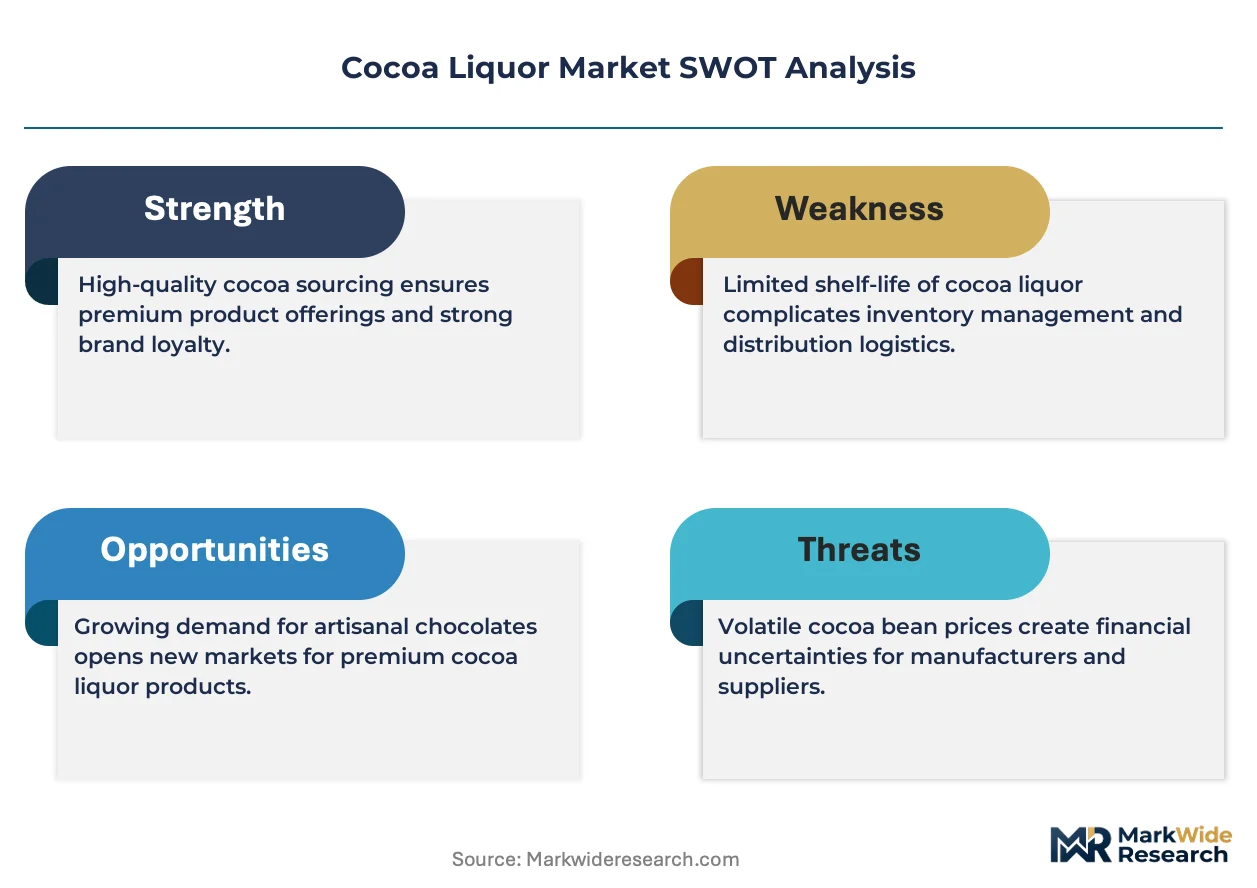
- Bean-to-bar traceability mandates:European confectionery manufacturers are retrofitting supply chains to meet EUDR geolocation requirements, expanding verified cocoa liquor procurement.
- Specialty beverage channels:Food service operators in North America are sourcing single-origin cocoa liquor for drinking chocolate menus, pulling premium-grade volumes.
- Ghana-Côte d'Ivoire farmgate coordination:Living Income Differential mechanisms are stabilizing origin-country supply commitments for forward-contracting processors.
Market Restraints
- Cadmium contamination thresholds:EFSA maximum levels for cocoa products are disqualifying certain West African origins from European food-grade applications.
- Input cost volatility:Cocoa bean futures on ICE exchange are experiencing price swings that compress margin predictability for toll-processing operators.
- Origin concentration risk:Over 60% of global bean supply flows through Abidjan and Tema port infrastructure, creating chokepoint vulnerability.
Strategic Opportunities
- Underpenetrated Southeast Asian processing:Indonesian and Malaysian grinders are expanding liquor output capacity to serve regional confectionery growth.
- Regenerative agriculture incentives:EU Green Deal farm-to-fork funding streams are subsidizing shade-grown cocoa verification for premium liquor positioning.
- Blockchain-IoT convergence:Distributed ledger systems paired with satellite monitoring are enabling real-time deforestation compliance documentation.
Industry Challenges
- Traceability system integration:Legacy ERP platforms at mid-sized processors require expensive API development to connect with EUDR-compliant data repositories.
- Heavy metal remediation timelines:Soil amendment programs to reduce cadmium uptake require 5-7 year lead times, misaligned with immediate regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Liquor Market |
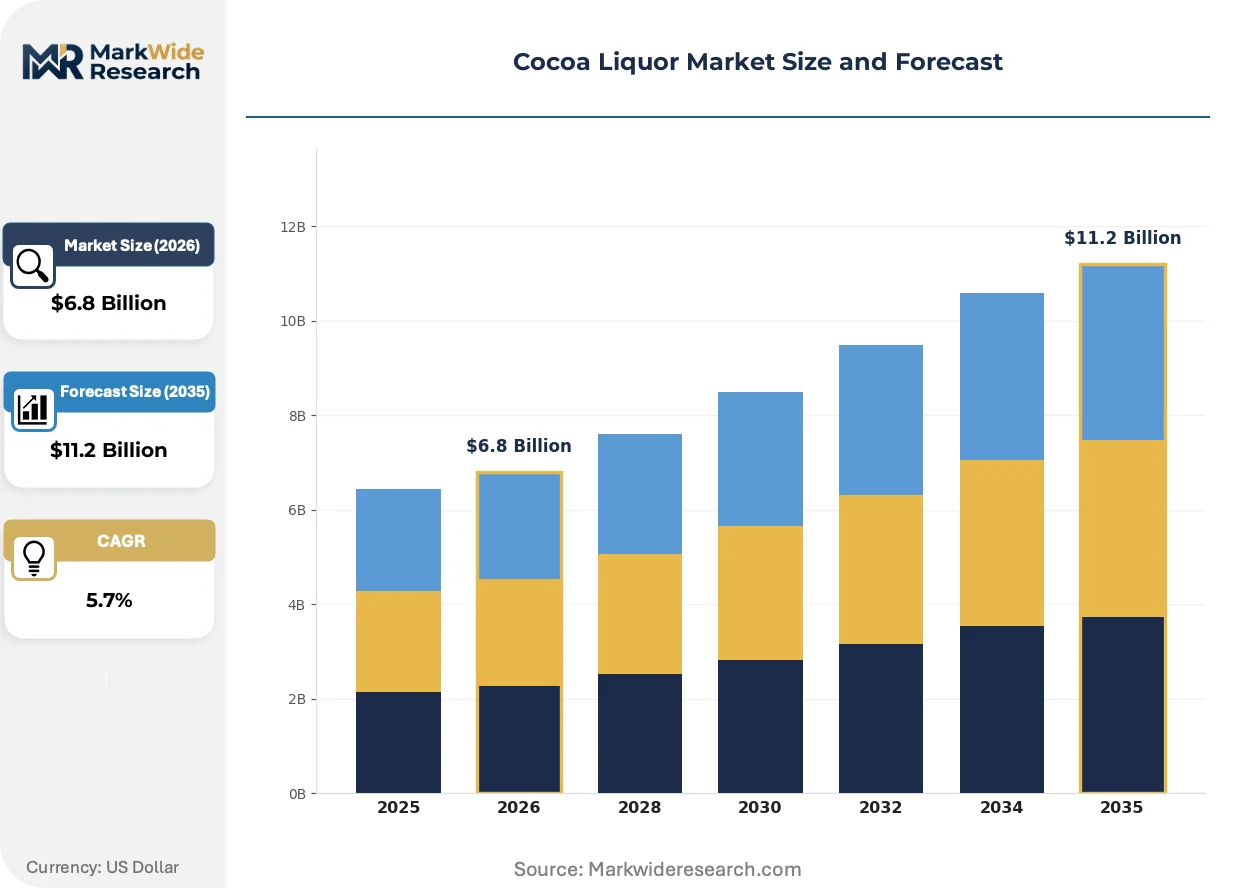
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, Unsweetened Cocoa, Baking Cocoa End User: Confectionery Manufacturers, Bakeries, Beverage Producers, Food Service Providers Application: Sweets, Beverages, Sauces, Desserts Distribution Channel: Direct Sales, Retail Stores, Online Marketplaces, Wholesale |
| Companies Covered | Mars Incorporated, Blommer Chocolate Company, Inc., Barry Callebaut AG, ECOM Agroindustrial Corp. Ltd., Fuji Oil Holdings Inc., Cargill, Incorporated, Nestlé S.A., Mondelēz International, Inc., Olam International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Liquor Market Emerging Trajectories
Processing technology and compliance architecture are diverging between mass-market and premium-tier supply chains. Equipment investments and data infrastructure are sorting manufacturers into distinct competitive tiers based on traceability depth.
Winnowing and alkalization equipment is bifurcating procurement patterns across the cocoa liquor landscape. Artisan chocolate makers are adopting small-batch stone grinding systems with batch-level origin documentation, while industrial processors deploy continuous-flow alkalizing units optimized for throughput. This technology split is enabling premium-origin storytelling at one end while compressing commodity-grade margins at the other.
EU Deforestation Regulation geolocation requirements are mandating polygon mapping of every farm plot supplying European-bound cocoa. Compliance systems must now integrate GPS coordinates with mass-balance documentation through the processing chain. Dark chocolate manufacturers with direct-origin relationships are absorbing certification costs fastest, while compound coating producers face reformulation pressures.
Specialty drinking chocolate is displacing conventional hot cocoa mixes in food service and retail channels. Coffee shop chains and boutique cafés are specifying 100% cocoa liquor bases with defined origin provenance, bypassing alkalized powder intermediates. This preference shift is most visible in urban North American and Western European markets where menu differentiation commands price premiums.
Cocoa Liquor Market Segmentation
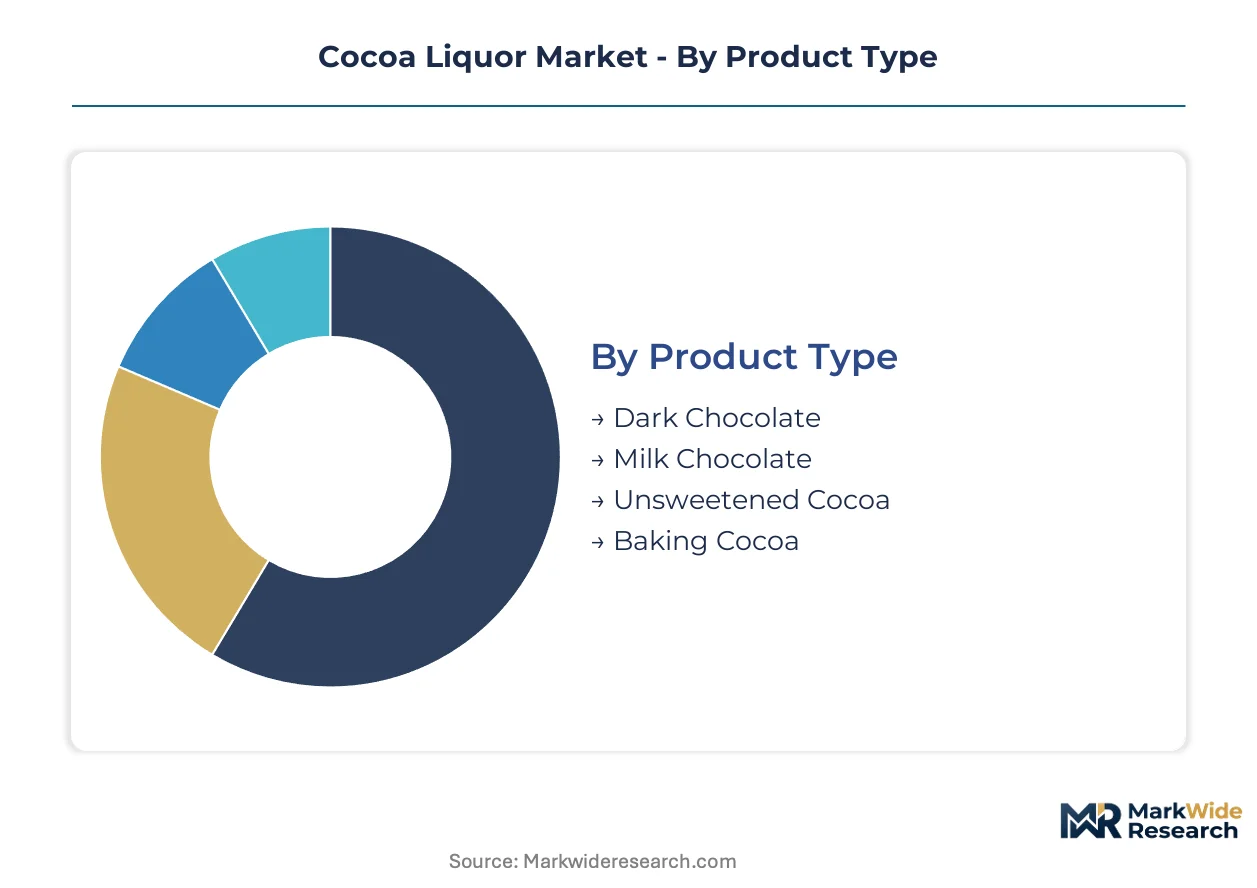
Cocoa liquor segmentation reveals how value pools concentrate across formulation chemistry, customer scale, and channel control. Understanding these fault lines exposes where processors capture margin versus where they compete on throughput.
Product Type:
Margin pools concentrate in high-cocoa-content formulations where bean quality and origin certification command premium positioning.
- Dark Chocolate:Contains 50-90% cocoa liquor with minimal added dairy, delivering intense polyphenol content and origin-specific flavor profiles. European confectionery houses in Belgium and Switzerland source single-origin liquor for 70%+ cacao bars, with EUDR traceability requirements adding compliance premiums to already elevated price points.
- Unsweetened Cocoa:Pure liquor paste with no added sweeteners, serving as the base for pharmaceutical-grade cocoa extracts and premium drinking chocolate formulations. North American specialty beverage manufacturers specify Ghana and Ecuador origins for clean-label positioning in functional beverage applications.
- Milk Chocolate:Combines cocoa liquor with condensed milk and higher sugar loads, standardizing at 10-50% cocoa content for mass-market confectionery.
- Baking Cocoa:Alkalized liquor processed to reduce acidity, supplying industrial bakeries with standardized color and flavor for cost-sensitive applications.
The dominant share belongs to dark chocolate, while unsweetened cocoa is closing the gap fastest.
End User:
Customer scale determines contract structure, with multinational confectioners locking multi-year supply agreements against spot-market exposure.
- Confectionery Manufacturers:Tier-one chocolate houses operate integrated grinding facilities or toll-processing arrangements with Barry Callebaut and Cargill, securing preferential liquor access through forward contracts tied to Living Income Differential premiums.
- Beverage Producers:Coffee chains and ready-to-drink manufacturers specify high-fat liquor for creamy mouthfeel in functional cocoa beverages, with North American food service operators driving single-origin procurement.
- Bakeries:Industrial and artisanal baking operations source alkalized liquor in bulk for standardized cocoa powder production.
- Food Service Providers:Hotels and restaurant groups procure liquor through distributor networks for in-house dessert and beverage programs.
Confectionery manufacturers retain the largest volume share, though beverage producers are expanding procurement most aggressively.
Application:
End-use chemistry dictates liquor fat content and alkalization levels, with beverage applications demanding distinct processing parameters.
- Sweets:Chocolate bars, pralines, and enrobed confections require 50-58% cocoa butter content for proper tempering and snap.
- Beverages:Drinking chocolate and cocoa mixes utilize high-fat liquor for emulsion stability, with specialty café chains in urban US and Western European markets specifying non-alkalized origins for flavor intensity.
- Sauces:Savory applications employ low-fat cocoa solids for color and subtle bitter notes.
- Desserts:Mousse and ganache formulations balance butter content for texture control.
Sweets command the established volume position, yet beverages are climbing the fastest as functional cocoa positioning expands.
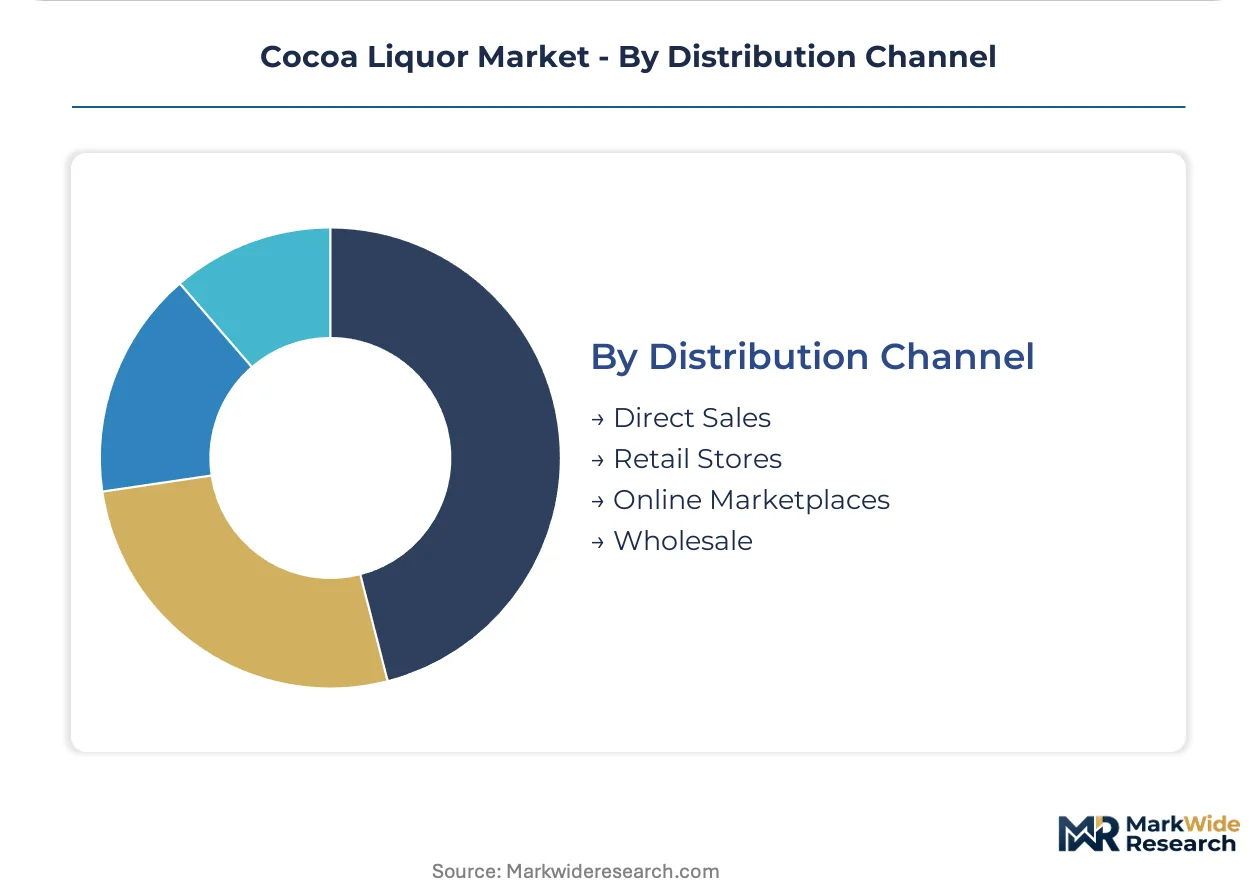
Distribution Channel:
Channel structure reflects customer procurement sophistication, with direct relationships dominating at scale and fragmentation increasing downstream.
- Direct Sales:Multinational processors contract directly with origin-country regulators and cooperative federations, bypassing intermediaries for EUDR-compliant supply chains.
- Wholesale:Regional distributors aggregate liquor volumes for mid-tier confectioners and bakeries lacking direct origination infrastructure.
- Online Marketplaces:Specialty cocoa brokers and origin cooperatives list single-origin lots for artisan chocolate makers seeking small-batch procurement.
- Retail Stores:Limited to consumer-facing cocoa products rather than industrial liquor volumes.
Direct sales anchor the largest share, while wholesale channels are gaining ground fastest among mid-sized processors retrofitting for compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over sixty percent of cocoa bean supply moves through Abidjan and Tema port infrastructure, concentrating processing capacity and regulatory leverage in West African origin countries. European and North American manufacturers retrofit supply chains to meet traceability mandates. Asian grinders expand capacity to serve regional confectionery demand.
Côte d'Ivoire
Conseil du Café-Cacao administers farmgate pricing and export licensing that governs market access for international processors. The Living Income Differential mechanism stabilizes supply commitments for forward-contracting operators. San Pedro and Abidjan anchor grinding capacity expansion as Asian and European processors establish toll-processing arrangements.
Ghana
COCOBOD's quality-controlled sourcing commands premium positioning for Ghana-origin liquor in North American beverage applications. Cadmium remediation programs target soil amendment across Western Region farms to maintain European food-grade eligibility. Tema's port infrastructure handles bulk liquor exports to Barry Callebaut and Cargill processing networks.
United States
FDA standards of identity constrain formulation flexibility for chocolate labeling, directly shaping liquor procurement specifications. Specialty beverage manufacturers in urban food service channels specify single-origin Ghana and Ecuador bases for clean-label positioning. Chicago and Pennsylvania industrial corridors concentrate chocolate manufacturing and grinding capacity.
Germany
EFSA cadmium thresholds and EU Deforestation Regulation compliance requirements reshape sourcing relationships for European confectionery houses. Hamburg and Cologne processing clusters invest in blockchain-IoT traceability infrastructure to document geolocation data. German chocolate manufacturers absorb certification costs fastest due to direct-origin relationships.
Indonesia
Southeast Asian confectionery demand expansion drives grinding capacity investment in Sulawesi and Java processing facilities. The country's national agricultural regulator oversees quality standards for regional export eligibility. Surabaya and Makassar anchor liquor output growth serving domestic and Asia-Pacific chocolate manufacturing.
Cocoa Liquor Market Vendor Landscape
Concentration sits with integrated processors and origin-country operators that control bean sourcing networks. The vendor base stratifies across three tiers: multinational grinders with West African infrastructure, regional specialists with single-origin positioning, and industrial compounders serving cost-sensitive coating applications. Two dominant competitive moves define current positioning: backward integration into farm-gate sourcing to secure EUDR-compliant supply chains, and technology licensing partnerships for traceability system deployment.
Among integrated processing specialists, Barry Callebaut AG, Cargill, Incorporated, and Mars Incorporated exemplify archetypes spanning toll-processing, agricultural origination, and vertical manufacturing. Barry Callebaut anchors European capacity through bean sourcing networks. Cargill dominates North American supply chains with West African infrastructure. Mars leverages captive supply from farm-gate to finished chocolate, securing preferential liquor access for confectionery operations.
| Leading Market Players |
|---|
| Mars Incorporated |
| Blommer Chocolate Company, Inc. |
| Barry Callebaut AG |
| ECOM Agroindustrial Corp. Ltd. |
| Fuji Oil Holdings Inc. |
| Cargill, Incorporated |
| Nestlé S.A. |
| Mondelēz International, Inc. |
| Olam International Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between European processors and Ghana's COCOBOD lock in both supply access and price visibility, insulating buyers from ICE exchange volatility while committing them to Living Income Differential premiums. These arrangements concentrate pricing power among origin-country regulators and integrated grinders with established West African infrastructure.
Pricing Analysis
The EU Deforestation Regulation dictates the pricing tier structure by imposing traceability premiums on EUDR-compliant liquor while compressing margins for non-compliant origins. Three-tier pricing structure across premium, standard, and economy levels separates single-origin certified liquor from mass-balance verified volumes and conventional untraceable paste. Cost compression in commodity-grade tiers is intensifying because alkalized baking cocoa faces substitution pressure from compound coatings. Industrial bakeries demonstrate highest price sensitivity, while specialty beverage manufacturers absorb premiums for Ghana-origin clean-label positioning.
Supply Chain Analysis
Abidjan and Tema port infrastructure underwrites global cocoa liquor distribution, channeling over sixty percent of bean supply through two chokepoints vulnerable to weather disruption and customs delays. Processing capacity concentrates in Côte d'Ivoire, Ghana, and Indonesia, with each node drawing from distinct bean quality pools. The supply chain rests on fermented bean supply, alkalizing chemical inputs, and packaging materials for bulk export. Single-source vulnerability runs through West African origination, where political coordination between COCOBOD and Conseil du Café-Cacao governs export licensing. Distribution runs through direct processor-manufacturer contracts for multinationals, wholesale aggregation for mid-tier buyers, and specialty brokers for artisan chocolate makers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cocoa liquor markets are recovering from cyclical compression as the Living Income Differential stabilizes farmgate economics and EUDR compliance investments mature into operational advantages.
For Market Incumbents: Secure EUDR-compliant supply chains through backward integration into farm-gate polygon mapping and satellite monitoring partnerships, defending against emerging Southeast Asian grinders capturing regional confectionery demand. Prioritize certification investment in cadmium remediation programs across Western Region Ghana farms to maintain European food-grade eligibility. Capacity addition in Indonesian processing hubs offers geographic diversification against origin concentration risk. For New Entrants and Emerging Players: Lead with single-origin specialty beverage positioning in North American urban food service channels, where menu differentiation commands price premiums and established processors underinvest in small-batch traceability. Target underpenetrated Southeast Asian confectionery growth through toll-processing arrangements with domestic chocolate manufacturers. Pursue blockchain-IoT verification partnerships as the go-to-market angle for EUDR-ready supply chain documentation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized processors with existing West African origination relationships and legacy ERP platforms requiring API development for EUDR compliance, capturing value from mandatory traceability infrastructure retrofitting. Long-term viability hinges on regulatory adaptation capacity rather than commodity price exposure. Watch cadmium threshold enforcement timelines as the inflection indicator for origin-country eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Gate Sourcing | Secures EUDR-compliant bean supply through direct cooperative federation contracts in Côte d'Ivoire. |
| Blockchain-IoT Traceability Deployment | Enables real-time geolocation documentation for EU Deforestation Regulation compliance verification. |
| Cadmium Remediation Program Investment | Maintains European food-grade eligibility for Ghana-origin liquor under EFSA maximum levels. |
| Southeast Asian Capacity Expansion | Captures regional confectionery demand growth through Indonesian and Malaysian grinding facilities. |
| Specialty Beverage Channel Partnership | Pulls premium-grade volumes through single-origin specifications in North American café chains. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, COCOBOD export statistics, and EU regulatory filings, combining interviews with cocoa processing plant managers, confectionery procurement leads, and origin-country cooperative directors. Secondary validation draws from FDA standards documentation, EFSA scientific opinions, and ICE exchange futures records. Bottom-up volume modeling triangulates against top-down value estimates across the cocoa liquor supply chain.
Segmentation dimensions modeled include product type chemistry, end-user scale tier, application fat content requirements, and distribution channel control level across the projection horizon. CAGRs derive from regression analysis of historical price-volume relationships and forward contract coverage ratios. Industry-specific forecast inputs incorporate Living Income Differential premium trajectories and EUDR compliance adoption curves.
Forecasts assume regulatory continuity in EU Deforestation Regulation enforcement and EFSA cadmium thresholds; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as origin-country farmgate pricing coordination and Southeast Asian processing capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
PHO Oils Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Virginiamycin Market
Ingredients
Food Ingredients Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Global Pulse Flours Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
Sweet Almond Oil Market
Ingredients
Cocoa Solids Market
Ingredients
Europe Fats and Oil Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Collagen Casings Market
Ingredients
Canola Meal Market
Ingredients
Synephrine Market
Ingredients
United States Avocado Oil Market
Ingredients
Codonopsis Extract Market