
 Fats and Oils Market | 2026-2036
Fats and Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Fats and Oils Market Analysis
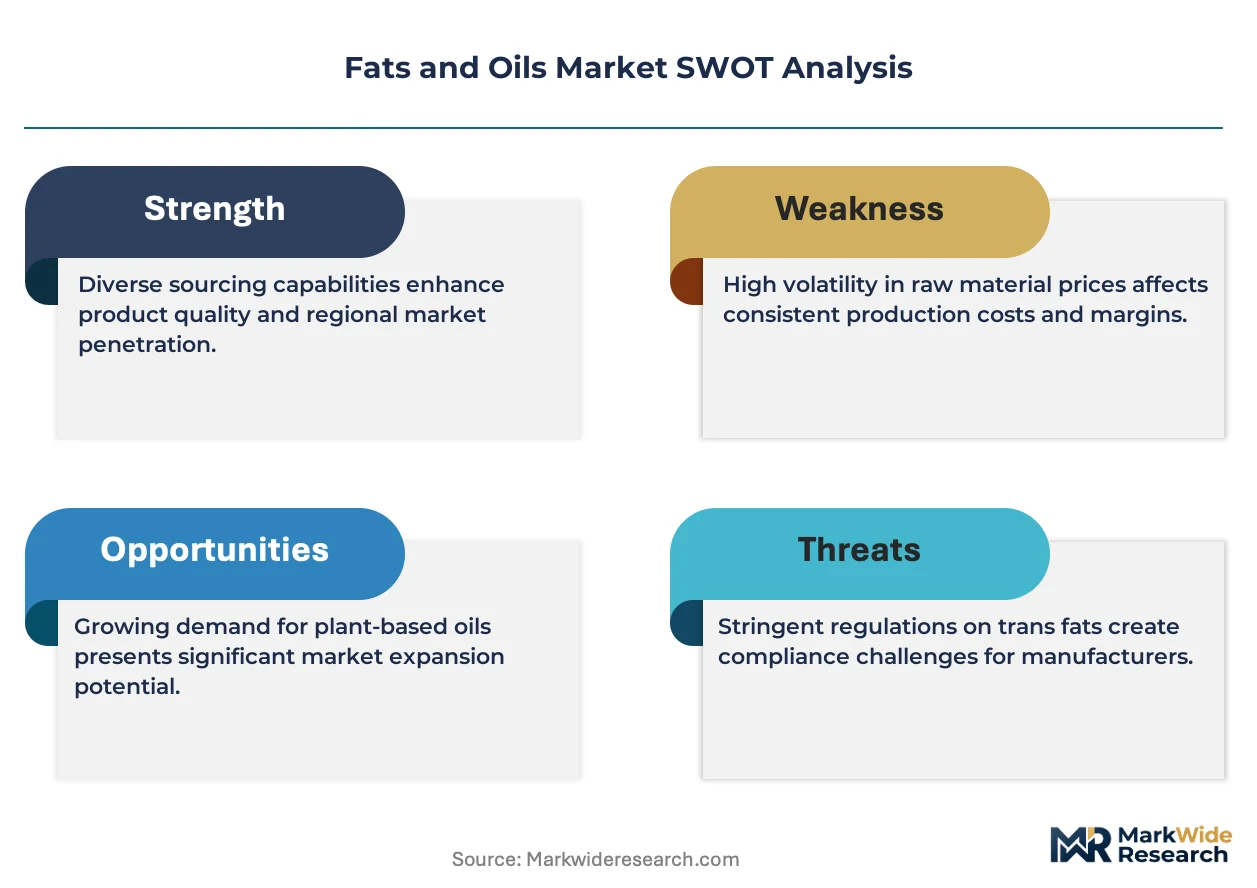
The price spread between premium specialty fats and commodity bulk oils is hardening as food manufacturers enforce stricter functional specifications. Bunge Limited leverages its North American oilseed crushing network to anchor supply security for food-service buyers. Wilmar International Limited dominates Southeast Asian palm refining with backward integration into plantation assets. AAK AB specializes in tailored lipid formulations that command technical premiums from confectionery and bakery customers.
Fats and oils comprise triglyceride-based lipids extracted from oilseeds, animal tissues, or marine sources through pressing, solvent extraction, or rendering, valued for their energy density, mouthfeel contribution, and oxidative stability in formulated products. Vegetable oils lead volume throughput due to soybean, palm, and rapeseed processing scale, while biofuels application records the fastest expansion as renewable diesel mandates tighten feedstock competition. Margarine and shortening segments occupy mature positions in developed markets where reformulation toward lower saturate levels constrains margin recovery.
EFSA sets maximum limits for 3-MCPD esters and glycidyl esters in refined vegetable oils sold within Europe, forcing capital upgrades to deodorization systems. FDA enforces Food Safety Modernization Act traceability rules that extend record-keeping burdens from import through manufacturing. REACH registrations on processing aids and refining chemicals add compliance layers for EU-bound shipments. Stakeholders must monitor feedstock cost divergence between palm and soybean oil as biofuel blending obligations in Indonesia, Brazil, and the United States intensify competition for identical lipid streams.
Market Dynamics
Renewable diesel mandates in Indonesia, Brazil, and the United States are intensifying feedstock competition between food and fuel applications, forcing processors to secure dedicated supply streams or absorb volatile input costs.
Growth Catalysts
- EFSA contaminant limits:Stricter caps on 3-MCPD esters and glycidyl esters in refined vegetable oils are accelerating capital deployment toward advanced deodorization systems across European refining facilities.
- High-oleic oil procurement:Food manufacturers are expanding clean-label product lines that require functional lipid stability without hydrogenation, pulling premium oil volumes from identity-preserved seed programs.
- Malaysian processing clusters:Deepening palm oil refining concentration around Port Klang and Pasir Gudang is compressing logistics costs for export-oriented specialty fat production.
Market Restraints
- Palm-soybean price divergence:Biofuel blending obligations across three major economies are creating asymmetric feedstock cost pressures that squeeze margin predictability for multi-oil processors.
- REACH registration burdens:Processing aids and refining chemicals require layered compliance documentation for EU-bound shipments, extending qualification timelines for new supply sources.
- Technical substitution ceiling:Bakery and confectionery applications face formulation limits when replacing saturated fats with liquid oils, constraining reformulation depth in mature markets.
Strategic Opportunities
- Renewable diesel feedstock premiums:Dedicated supply contracts for hydrotreated vegetable oil production are commanding price premiums in the United States and Brazil as mandates tighten.
- Indian packaged food expansion:Rapid urbanization and modern retail penetration are creating unmet demand for shelf-stable frying oils and structured fats in quick-service restaurant supply chains.
- Precision fermentation lipids:Convergence of synthetic biology and downstream processing is enabling cocoa butter equivalents and other high-value specialty fats outside agricultural commodity cycles.
Industry Challenges
- Deodorization engineering talent:Advanced refining equipment operation and process optimization require specialized skill sets that remain scarce outside established Malaysian and European processing hubs.
- Traceability system integration:FDA Food Safety Modernization Act record-keeping obligations from import through manufacturing demand capital-intensive digital infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fats and Oils Market |
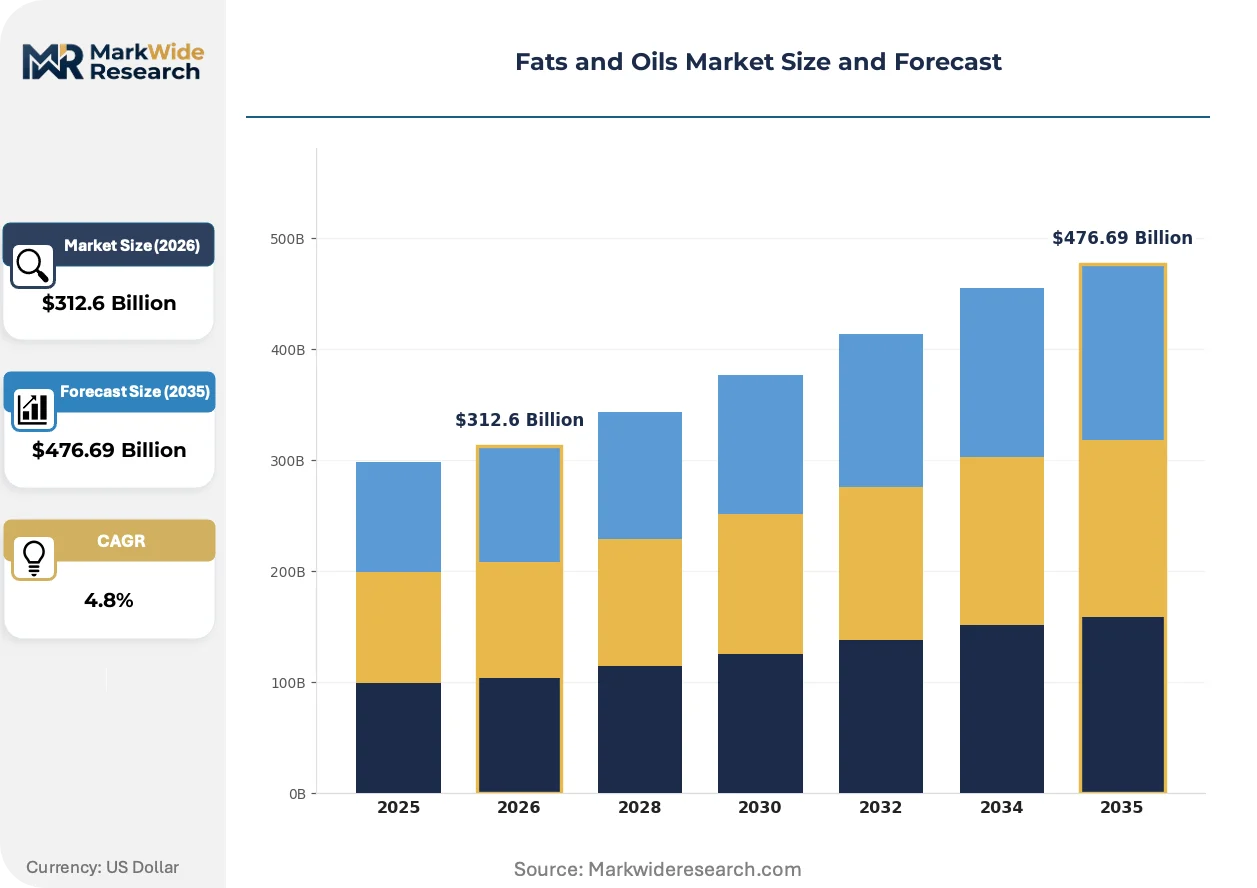
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Margarine, Shortening Application: Food Processing, Cosmetics, Biofuels, Pharmaceuticals End User: Food Manufacturers, Personal Care Companies, Biofuel Producers, Healthcare Providers Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Bunge Limited, Olam Group, Cargill Incorporated, AAK AB, Associated British Foods plc, Archer Daniels Midland Company, Fuji Oil Holdings Inc., IOI Corporation Berhad, Wilmar International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fats and Oils Market Emerging Trajectories
Processing technology convergence and regulatory chemistry constraints are compressing traditional refining economics while opening premium tiers for verified supply chains and functional lipid design.
Enzymatic interesterification is unifying fat structuring capabilities across lower-saturate feedstocks. Bakery and confectionery formulators are adopting these systems at accelerating rates to meet clean-label requirements without performance sacrifice. This technology is unifying previously separate commodity and specialty fat production lines into flexible multiproduct facilities.
REACH registrations on refining chemicals and processing aids are tightening documentation requirements for EU-bound shipments. Industrial consequence includes extended supplier qualification periods and reformulation of standard additive packages. Southeast Asian exporters are responding by establishing dedicated European compliance teams and captive laboratory testing capacity.
Buyer concentration among multinational food-service chains is compressing supplier negotiation cycles and demanding certified sustainable sourcing at volume scale. Traditional spot-market procurement through brokers is losing share to direct origination partnerships with crusher-refiners. This pattern is most visible in North American and Western European quick-service restaurant supply chains where ESG disclosure requirements now extend to ingredient tier-one suppliers.
Fats and Oils Market Segmentation
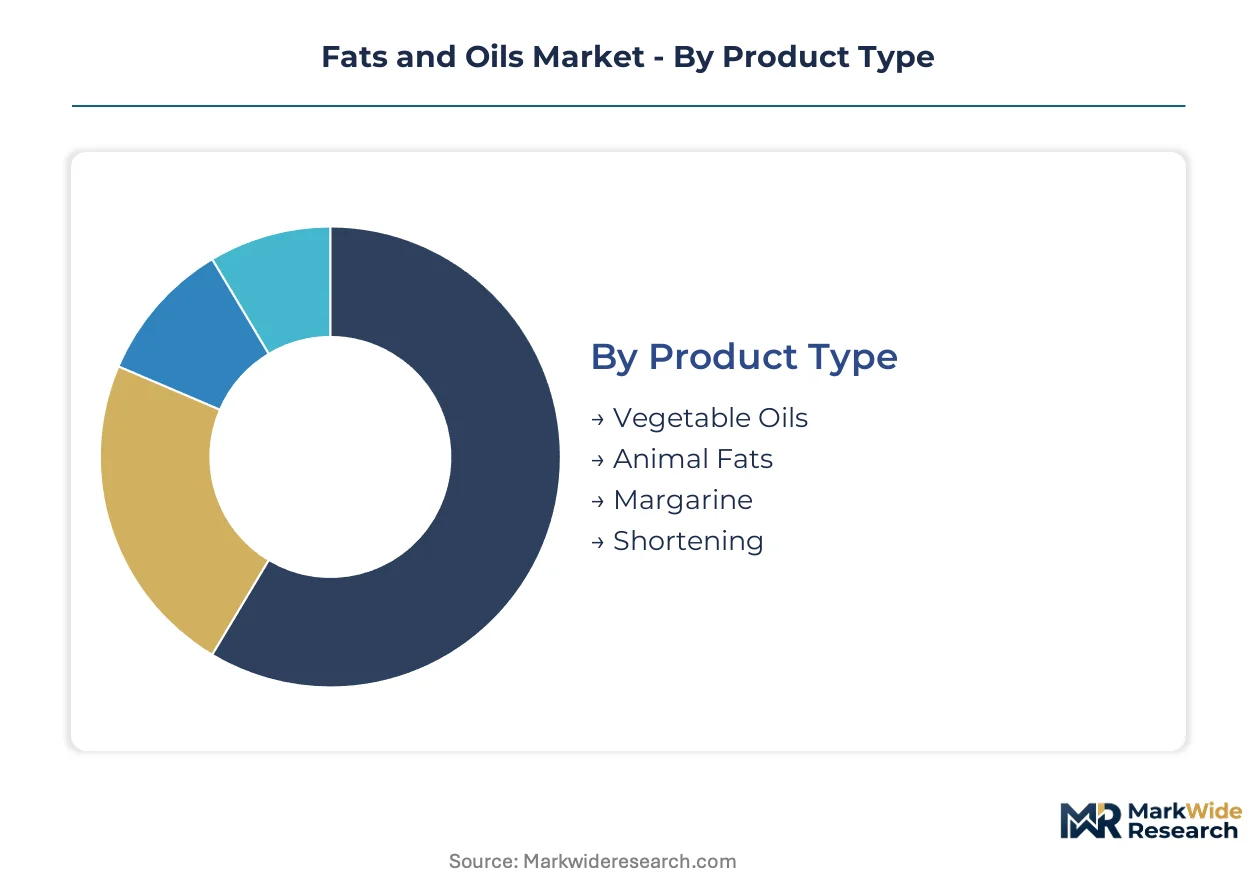
Segmentation in fats and oils reveals how divergent buyer requirements—clean-label stability, renewable fuel specifications, cosmetic emolliency—pull identical feedstocks toward radically different value chains and margin structures.
Product Type:
Buyers differentiate primarily by functional performance thresholds and reformulation flexibility rather than origin alone.
- Vegetable Oils:Triglyceride lipids extracted from soybean, palm, rapeseed, and sunflower through pressing or solvent extraction, prized for oxidative stability and neutral flavor profiles. Food manufacturers in Indonesia and Malaysia are locking in long-term supply contracts as biofuel mandates in Brazil and the United States divert soybean and palm oil streams toward hydrotreated renewable diesel production.
- Animal Fats:Rendered lipids from cattle, swine, and poultry tissues including tallow and lard, valued for saturated fat structure and high smoke points in frying applications. Rendering facilities in the United States are expanding capacity to serve both food-service buyers and emerging renewable diesel offtakers competing for identical tallow feedstock pools.
- Margarine:Water-in-oil emulsions formulated from hydrogenated or interesterified vegetable oils, positioned as butter alternatives in cost-sensitive baking and spreads applications.
- Shortening:Plasticized fat blends engineered for aeration and crumb structure in pastry and confectionery, facing reformulation pressure as EFSA and FDA tighten trans-fat labeling and contaminant limits.
Vegetable oils lead volumes today; biofuel feedstock applications are gaining share fastest.
Application:
End-use specifications diverge sharply on purity grades, traceability depth, and certification requirements.
- Food Processing:Lipid inputs spanning frying oils, spray coatings, and structured fats for bakery, confectionery, and prepared meals. EFSA maximum limits for 3-MCPD esters and glycidyl esters are forcing European refiners to deploy advanced dual-temperature deodorization systems that add capital intensity but unlock clean-label product positioning.
- Biofuels:Hydrotreated vegetable oil and renewable diesel production from soybean oil, palm oil, and waste fats. Indonesia, Brazil, and the United States have enacted tightening blending mandates that now consume feedstock volumes previously dedicated to food applications, creating dedicated supply contract premiums.
- Cosmetics:High-purity triglycerides and fatty acid derivatives for emollients, surfactants, and formulation bases. REACH registration requirements on processing aids are extending European supplier qualification timelines and favoring established Malaysian and Indonesian refiners with captive laboratory testing capacity.
- Pharmaceuticals:Excipient-grade lipids meeting USP and EP monograph standards for oral and topical drug delivery systems.
Food processing dominates current offtake; biofuels demonstrate the steepest expansion trajectory.
End User:
Procurement scale and technical specification intensity separate volume buyers from specialty formulators.
- Food Manufacturers:Multinational processors and regional bakeries requiring identity-preserved high-oleic oils for clean-label stability without hydrogenation. Quick-service restaurant chains in North America and Western Europe now mandate certified sustainable sourcing and ESG disclosure from tier-one lipid suppliers, compressing spot-market broker participation.
- Biofuel Producers:Renewable diesel refiners securing dedicated feedstock streams through long-term offtake agreements with crusher-refiners, paying premiums for supply security as food-fuel competition intensifies.
- Personal Care Companies:Cosmetic formulators sourcing pharmaceutical-grade and naturally-positioned lipid derivatives with full supply chain transparency for consumer marketing claims.
- Healthcare Providers:Institutional purchasers of clinical nutrition lipids and pharmaceutical excipients with stringent lot-level traceability requirements.
Food manufacturers anchor procurement volumes today; biofuel producers are expanding their share most aggressively.
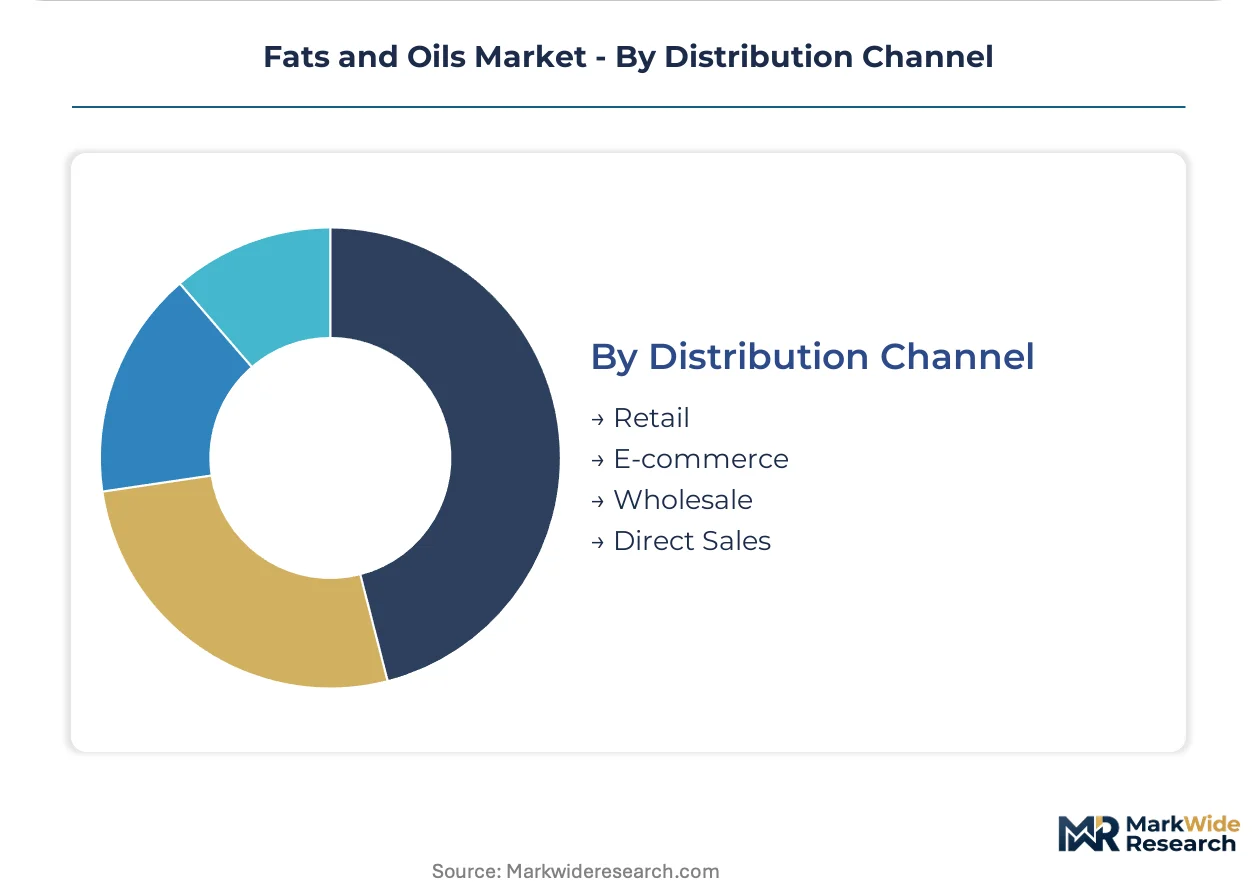
Distribution Channel:
Channel selection tracks buyer scale, specification complexity, and geographic concentration of demand.
- Wholesale:Bulk tanker and flexitank shipments from crusher-refiners to food manufacturers and biofuel producers, capturing cost efficiency through direct origination partnerships that bypass traditional broker intermediaries.
- Direct Sales:Long-term supply contracts between integrated plantation-refiners and multinational food-service chains, incorporating sustainability certification and regulatory compliance documentation.
- Retail:Packaged edible oils through supermarkets and hypermarkets, concentrated in emerging markets where urbanization drives branded consumer oil demand.
- E-commerce:Niche specialty fats and organic-certified oils for small-scale food processors and cosmetic formulators requiring low minimum order quantities.
Wholesale channels handle the greatest volume today; direct sales are climbing the fastest as buyer concentration intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia and Malaysia dominate palm oil processing capacity, while the United States anchors soybean crushing infrastructure and renewable diesel feedstock demand.
Indonesia
Biofuel blending mandates and export-oriented refining investments drive capacity expansion. The country's energy ministry enforces B35 and advancing B40 biodiesel programs that divert crude palm oil from food channels. Processing clusters around Belawan and Dumai deepen backward integration into plantation assets.
Malaysia
Port Klang and Pasir Gudang harbor zones concentrate specialty fat production for European and Asian food manufacturers. EFSA contaminant limits on 3-MCPD esters and glycidyl esters force capital upgrades to dual-temperature deodorization systems. Malaysian refiners deploy captive laboratory testing capacity to compress EU-bound shipment qualification timelines.
United States
Renewable diesel mandates in California and federal blending obligations intensify competition for soybean oil and rendered animal fats. EPA enforcement of Renewable Fuel Standard obligations creates dedicated feedstock premiums for hydrotreated vegetable oil producers. Crushing and rendering facilities across the Midwest and Gulf Coast expand capacity to serve biofuel offtakers.
Brazil
Soybean processing scale and biodiesel policy frameworks position the country as a dual-purpose feedstock supplier. ANP blending mandates tighten annually, pulling soy oil volumes toward fuel applications. Crushing clusters in Mato Grosso and Paraná states deepen logistics integration with export terminals at Santos and Paranaguá.
Germany
REACH registrations on refining chemicals and EFSA standards reshape deodorization equipment investments. Rapeseed processing facilities in Hamburg and Magdeburg upgrade contaminant control systems. Food manufacturers enforce stricter functional specifications for clean-label bakery and confectionery applications.
Fats and Oils Market Vendor Landscape
Top-tier vendors anchor integrated crushing-refining networks, while mid-scale specialists occupy tailored formulation niches. The market structures around three archetypes: plantation-integrated refiners with captive feedstock security, technology-driven specialty fat formulators, and multinational traders with origination scale. Dominant competitive moves include backward integration into plantation assets and enzymatic interesterification technology licensing.
Within the plantation-integrated tier, Wilmar International Limited and IOI Corporation Berhad exemplify Southeast Asian operators with crushing-refining scale. Bunge Limited anchors North American oilseed processing infrastructure. AAK AB occupies the specialty formulation vector, representing European technical premium positioning in confectionery and bakery lipids.
| Leading Market Players |
|---|
| Bunge Limited |
| Olam Group |
| Cargill Incorporated |
| AAK AB |
| Associated British Foods plc |
| Archer Daniels Midland Company |
| Fuji Oil Holdings Inc. |
| IOI Corporation Berhad |
| Wilmar International Limited |
| Others |
Supply Flow & Price Mechanics
Crude palm oil procurement costs in Indonesia and Malaysia cascade through three distinct pricing tiers as European refiners absorb EFSA-mandated deodorization upgrades and biofuel producers bid premiums for hydrotreated feedstock security.
Pricing Analysis
Capacity additions in Malaysia and Indonesia are reshaping price floors for commodity-grade palm oil while specialty fat premiums widen. Contract-based long-term offtake dominates biofuel feedstock procurement, with price differentiation driven by certification grade (RSPO/ISCC) and volume scale. Pricing pressure stems from renewable diesel mandates in the United States, Brazil, and Indonesia diverting identical lipid streams. Food manufacturers show highest price sensitivity; cosmetic formulators exhibit lowest.
Supply Chain Analysis
Crude palm oil supply rests on Indonesian and Malaysian plantation assets, with soybean oil feedstock anchored in United States and Brazilian crushing infrastructure. Key inputs span oilseed cultivation, solvent extraction chemicals, and dual-temperature deodorization catalysts. Single-source vulnerability concentrates in Southeast Asian port clusters around Belawan, Dumai, Port Klang, and Pasir Gudang. Distribution runs through direct origination partnerships between integrated crusher-refiners and multinational food-service chains, compressing traditional broker intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fats and Oils Market functions as a stable compounder, with renewable diesel mandates across three major economies generating persistent feedstock demand that underpins volume throughput.
For Market Incumbents: Hedge margin exposure by securing dedicated supply contracts with hydrotreated vegetable oil producers before biofuel blending obligations tighten further. Deploy capital toward enzymatic interesterification licensing to unify commodity and specialty fat production lines, defending against precision fermentation lipid substitutes. For New Entrants and Emerging Players: Precision fermentation lipid technology offers a technology-first wedge into cocoa butter equivalent and high-value specialty fat segments where agricultural commodity cycles constrain incumbent flexibility. Target Indian packaged food expansion and quick-service restaurant supply chains for shelf-stable frying oils; lead with clean-label stability claims and low minimum order quantities via e-commerce channels. For Investors and Strategic Acquirers: Consolidation pressure builds where backward integration into plantation assets separates margin-sustainable operators from spot-market exposed traders. Frame five-to-ten-year viability around feedstock security and regulatory compliance infrastructure. Target Malaysian and Indonesian refiners with captive laboratory testing capacity for EU-bound shipments. Watch biofuel mandate acceleration in Indonesia, Brazil, and the United States as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive crude palm oil supply secures margin predictability against spot price volatility in Port Klang and Dumai clusters. |
| Enzymatic Interesterification Licensing | Flexible multiproduct facilities meet EFSA contaminant limits without hydrogenation, unlocking clean-label bakery positioning. |
| Dual-Temperature Deodorization Upgrade | Advanced refining systems compress EU-bound shipment qualification timelines for Malaysian exporters facing REACH documentation. |
| Long-Term Renewable Diesel Offtake Agreement | Dedicated supply contracts with United States and Brazilian biofuel producers command premiums as mandates tighten. |
| Precision Fermentation Lipid Development | Synthetic biology convergence enables cocoa butter equivalents outside palm and soybean agricultural commodity cycles. |
Methodological Framework
Direct dialogue with refinery operations managers, plantation procurement leads, European regulatory compliance officers, and quick-service restaurant supply chain directors anchored qualitative foundations. Secondary validation drew from customs and trade data, EFSA contaminant limit documentation, EPA Renewable Fuel Standard filings, and SEC 10-K disclosures from integrated crusher-refiners. Bottom-up volume modeling across product type, application, end user, and distribution channel segments triangulated against top-down macroeconomic drivers.
Segment-level outputs across the projection horizon reflect analytical frameworks incorporating grade tier, end-use industry, regional production hub, and certification status dimensions. CAGRs were derived from feedstock cost trajectory modeling, biofuel mandate schedule analysis, and clean-label reformulation adoption curves. Key inputs included palm-soybean price divergence scenarios and deodorization equipment deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biofuel policy acceleration, EFSA contaminant limit revisions, and precision fermentation lipid scale-up. Forecasts reflect documented assumptions on mandate schedules and technology cost curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydroxytyrosol Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Pea Fiber Market
Ingredients
Almond Ingredients Market
Ingredients
Casein Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Lupine Peptides Market
Ingredients
Marine Peptides Market
Ingredients
Botanical Extracts Market
Ingredients
Oak Chips White Extract Market
Ingredients
South America Lipid Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Yeast Derivatives Market