
 Caramel Ingredient Market | 2026-2036
Caramel Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Caramel Ingredient Market Intelligence
The beverage segment's growth trajectory is decoupling from the more mature confectionery category, creating new application frontiers for caramel ingredients. Cargill leverages its extensive supply chain to offer a wide portfolio of liquid and powdered caramels for this evolving mix. Kerry Group plc specializes in customized flavor systems for dairy and beverage clients, while Sethness Roquette differentiates through its production of high-color-intensity caramel for specific industrial applications.
Caramel ingredients are food additives produced through the controlled heating of carbohydrates, a process known as caramelization. These ingredients provide color, flavor, and texture, with specifications often defined by color intensity and viscosity. While liquid caramel formats dominate in volume for beverage and sauce applications, powdered caramel gains traction in the bakery sector due to its superior shelf life and suitability for dry mixes.
Market access is governed by food additive regulations, with bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) setting standards for purity and labeling. In countries like India, the FSSAI enforces specific guidelines on colorants and flavorings, impacting import strategies. Suppliers must now navigate diverging regional definitions of 'natural' and 'clean-label' to maintain broad market acceptance.
Market Dynamics
The central force shaping the caramel ingredient market is the consumer-led demand for clean-label and natural products. This pressure compels manufacturers to navigate divergent regional definitions of 'natural' set by bodies like the FDA and EFSA, directly influencing ingredient sourcing and production methods.
Growth Catalysts
- Beverage Sector Expansion:The proliferation of ready-to-drink coffees, flavored milks, and specialty alcoholic drinks creates sustained demand for liquid caramel ingredients that provide both color and a distinct flavor profile sought by consumers.
- Clean-Label Formulations:A strong consumer preference for transparent and simple ingredient lists is pushing food manufacturers to adopt caramel colors perceived as more 'natural' than synthetic alternatives, particularly in bakery and confectionery goods.
- Confectionery Production Scale:High-volume confectionery and bakery manufacturing centers, especially within the United States, serve as a consistent demand anchor for both liquid and powdered caramel formats for use in fillings, coatings, and toppings.
Market Restraints
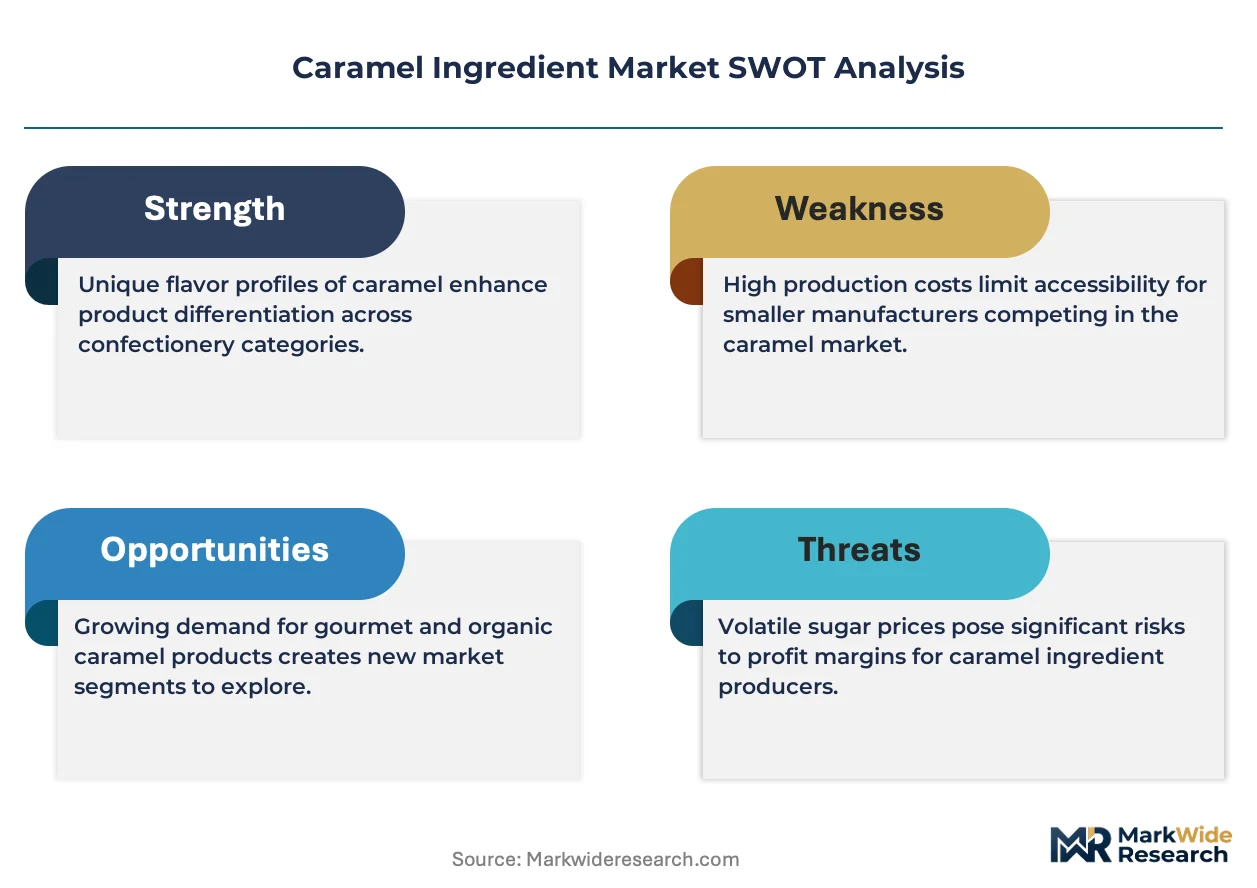
- Input Price Volatility:The market is exposed to fluctuations in the price of raw materials, primarily sugars derived from corn, wheat, and sugarcane, which can compress manufacturer margins and create pricing instability for end-users.
- Regulatory Heterogeneity:Diverging standards for caramel color classification and labeling between the US FDA and the European EFSA create significant compliance complexities and costs for suppliers operating across both markets.
- Substitution from Natural Alternatives:In applications where color is the primary function, caramel faces competition from other natural colorants like annatto, beet juice, and fruit extracts, which can offer cleaner labels in specific food categories.
Strategic Opportunities
- Plant-Based Applications:The fast-growing plant-based food and beverage category, including oat milk lattes and almond-based desserts, presents a significant opportunity for customized caramel flavor and color systems tailored to non-dairy formulations.
- High-Intensity Color Development:There is an opportunity to develop and market highly concentrated caramel colors, like those produced by Sethness Roquette, for industrial applications where minimal dosage is required to achieve a dark, rich hue.
- Emerging Market Penetration:Untapped potential exists in developing food processing hubs across Southeast Asia and Latin America, where a rising middle class and evolving dietary habits are creating new demand for processed foods and beverages.
Industry Challenges
- Batch-to-Batch Consistency:Maintaining precise and consistent color intensity and viscosity across large-scale production batches is a persistent technical challenge that requires significant process control and quality assurance investment to meet industrial client specifications.
- Navigating 'Natural' Definitions:Suppliers face the operational challenge of reformulating and documenting products to align with varying and often ambiguous 'clean-label' and 'natural' criteria demanded by retailers and consumers in different international markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caramel Ingredient Market |
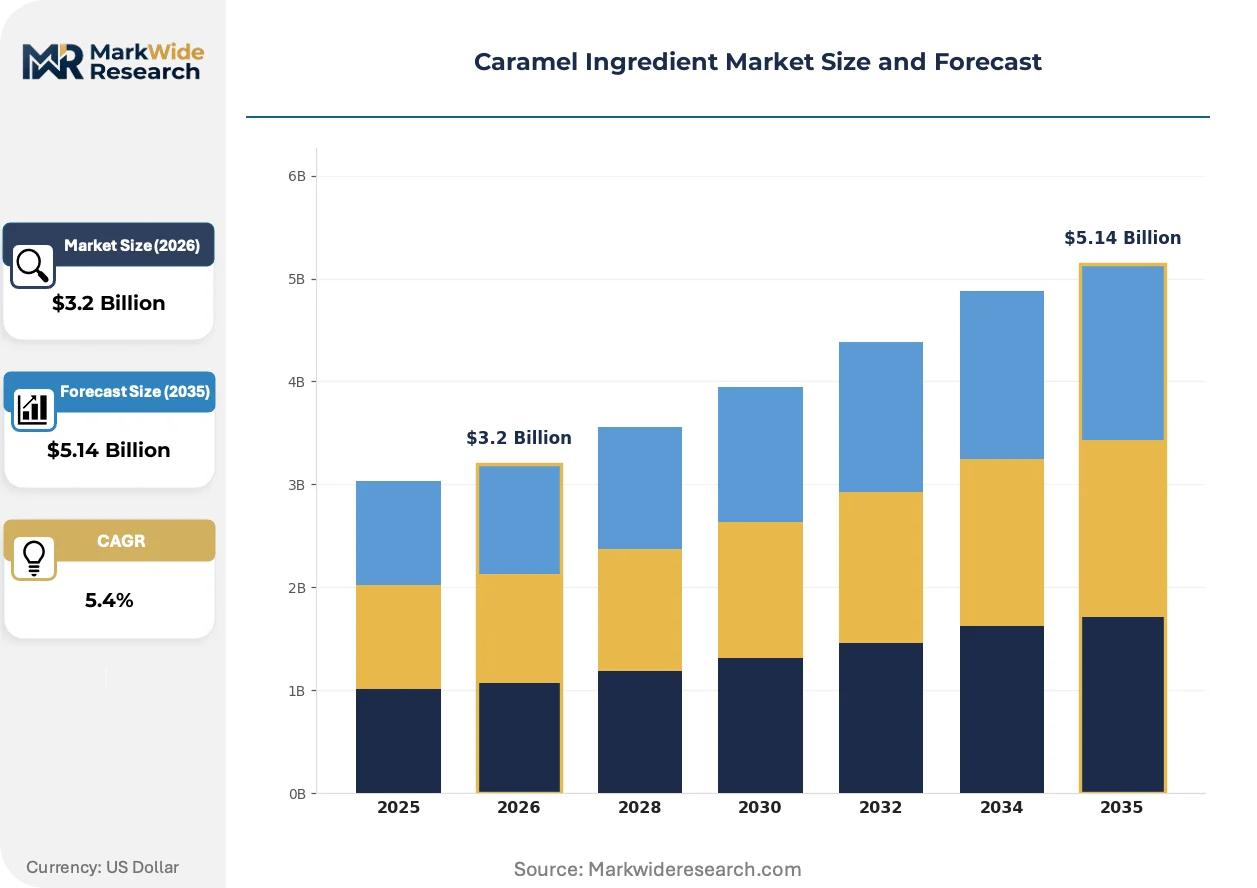
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Caramel, Powdered Caramel, Caramel Syrup, Caramel Concentrate, Caramel Extract Application: Confectionery, Bakery Products, Beverages, Dairy Products, Sauces & Dressings End User: Food Manufacturers, Beverage Producers, Confectionery Makers, Dairy Processors, Sauce Manufacturers Packaging Type: Plastic Bottles, Glass Jars, Pouches, Sachets, Bulk Containers |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Kerry Group plc, Sensient Technologies Corporation, Tate & Lyle PLC, Puratos Group, Sethness Roquette, Ingredion Incorporated, D.D. Williamson Caramel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caramel Ingredient Market Strategic Shifts & Innovations
Caramel's functional role is expanding beyond a simple commodity, driven by innovations in processing technology and a demand for tailored solutions. This evolution transforms it from a basic colorant into a sophisticated ingredient designed for specific performance and labeling requirements.
Spray-drying technology enables the creation of powdered caramel ingredients with superior shelf life and solubility. The bakery and dry-mix food sectors are rapidly adopting these powders for their ease of handling and incorporation into products like cake mixes and seasonings. This advancement is integrating material science principles into food production, enabling the formulation of complex, shelf-stable consumer goods that were previously difficult to manufacture.
Heightened scrutiny from food safety authorities, including the US FDA and the European EFSA, is formalizing rules around the labeling of food additives. This regulatory pressure forces producers to increase transparency regarding carbohydrate sources and processing methods used in caramel production. The clean-label segment is most affected, compelling suppliers to either reformulate or clearly specify the caramel class to maintain access to health-conscious consumer markets.
A notable behavioral shift sees large-scale food and beverage companies increasingly requesting bespoke caramel solutions instead of buying off-the-shelf products. This co-development model often bypasses traditional distributors, fostering direct partnerships between manufacturers and specialized ingredient suppliers. This collaborative approach to procurement is most visible within the North American specialty beverage sector and for premium dessert applications in Europe.
Caramel Ingredient Market Segmentation
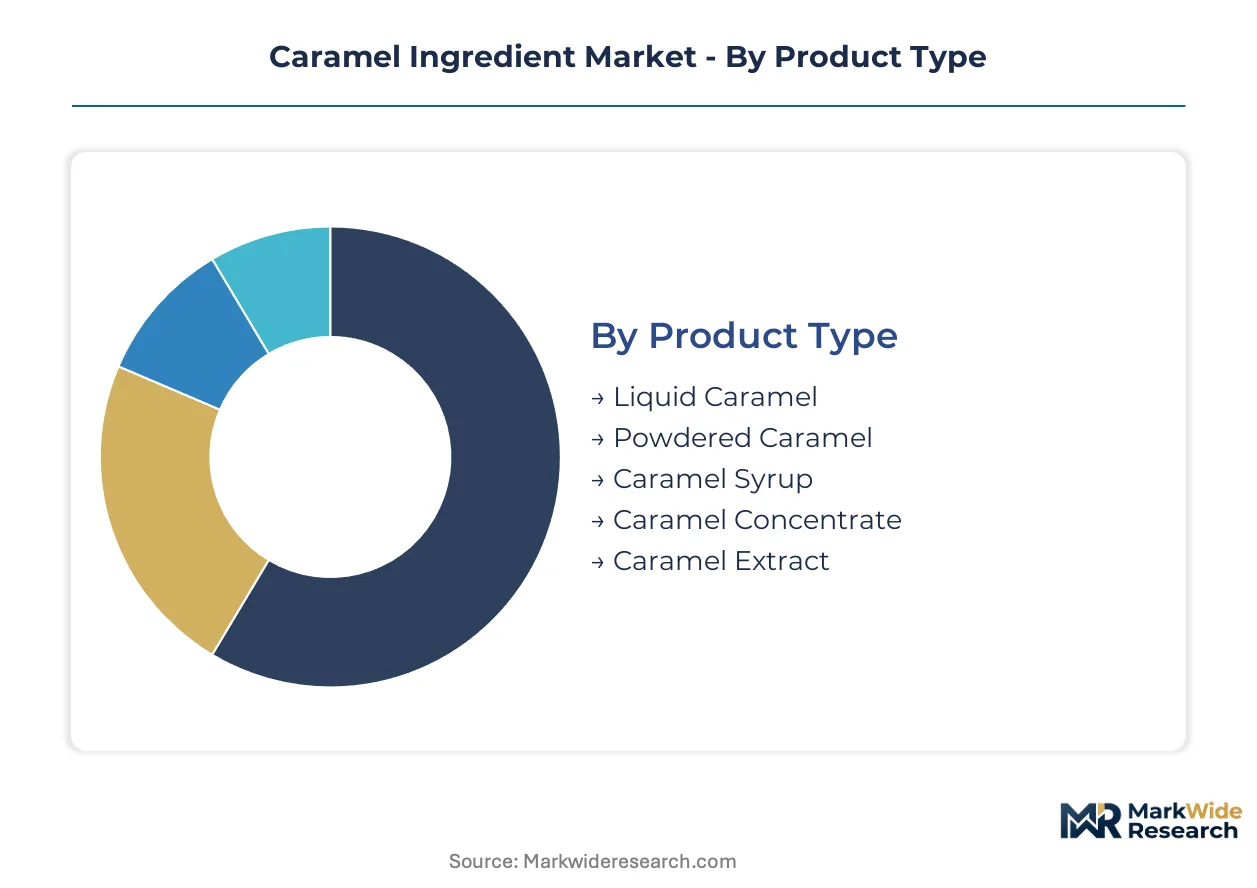
The caramel ingredient market exhibits diverse structural characteristics across its product forms, applications, and end-user base. Understanding these segments is crucial for identifying where value accumulates and how operational strategies adapt.
Product Type:
The integration depth of caramel ingredients varies by physical form, from standalone flavorings to embedded functional components.
- Liquid Caramel:This format, dissolved in water, offers ease of dispersion and consistent color and flavor integration in wet applications. Demand concentrates in the beverage sector for visual appeal and distinct flavor.
- Powdered Caramel:Produced via spray-drying, this form provides superior shelf life and stability, ideal for dry mixes and bakery products. Its use gains traction due to ease of handling in cake mixes.
- Caramel Syrup:A viscous liquid sweetener, often used in dessert toppings and coffee flavorings.
- Caramel Concentrate:Highly concentrated liquid offering intense color and flavor, requiring minimal dosage for industrial use.
- Caramel Extract:Primarily imparts flavor rather than color, used in culinary and confectionery applications.
Volume placements concentrate in Liquid Caramel; the faster expansion belongs to Powdered Caramel.
Application:
The market for caramel ingredients is defined by distinct application profiles, each demanding specific functional properties related to color, flavor, and texture.
- Beverages:This segment uses caramel for coloring and flavoring in ready-to-drink coffees, flavored milks, and specialty alcoholic drinks. New product lines in North America create sustained demand.
- Confectionery:Caramel ingredients are fundamental in candies, chocolates, and sweet treats, providing texture, color, and a rich flavor. High-volume manufacturing centers in the United States anchor consistent demand.
- Bakery Products:Used in cakes, cookies, and pastries for color, flavor, and moisture retention in dry mixes.
- Dairy Products:Enhances flavor and color in yogurts, ice creams, and milk-based desserts, requiring stable formulations.
- Sauces & Dressings:Contributes color and a distinctive sweet-savory note to various savory sauces and salad dressings.
The dominant consumption pattern resides in Confectionery, while Beverages exhibits the steepest expansion trajectory.
End User:
Caramel ingredient suppliers tailor offerings to specific end-user categories, characterized by distinct procurement volumes and technical requirements.
- Food Manufacturers:This broad category encompasses producers of various processed foods, utilizing caramel for diverse applications. They require large-scale, consistent supply and adherence to FDA standards.
- Beverage Producers:These clients integrate caramel into drink formulations, demanding liquid forms with specific color intensities and stability. Clean-label focus influences ingredient selection.
- Confectionery Makers:Require caramel for flavor, color, and texture in high-volume candy and chocolate production.
- Dairy Processors:Incorporate caramel into yogurts, ice creams, and flavored milks, prioritizing dairy-stable ingredients.
- Sauce Manufacturers:Use caramel to enhance color and add a rich flavor profile to both savory and sweet sauces.
The largest purchasing volumes are generated by Food Manufacturers, with Beverage Producers demonstrating significant market dynamism.
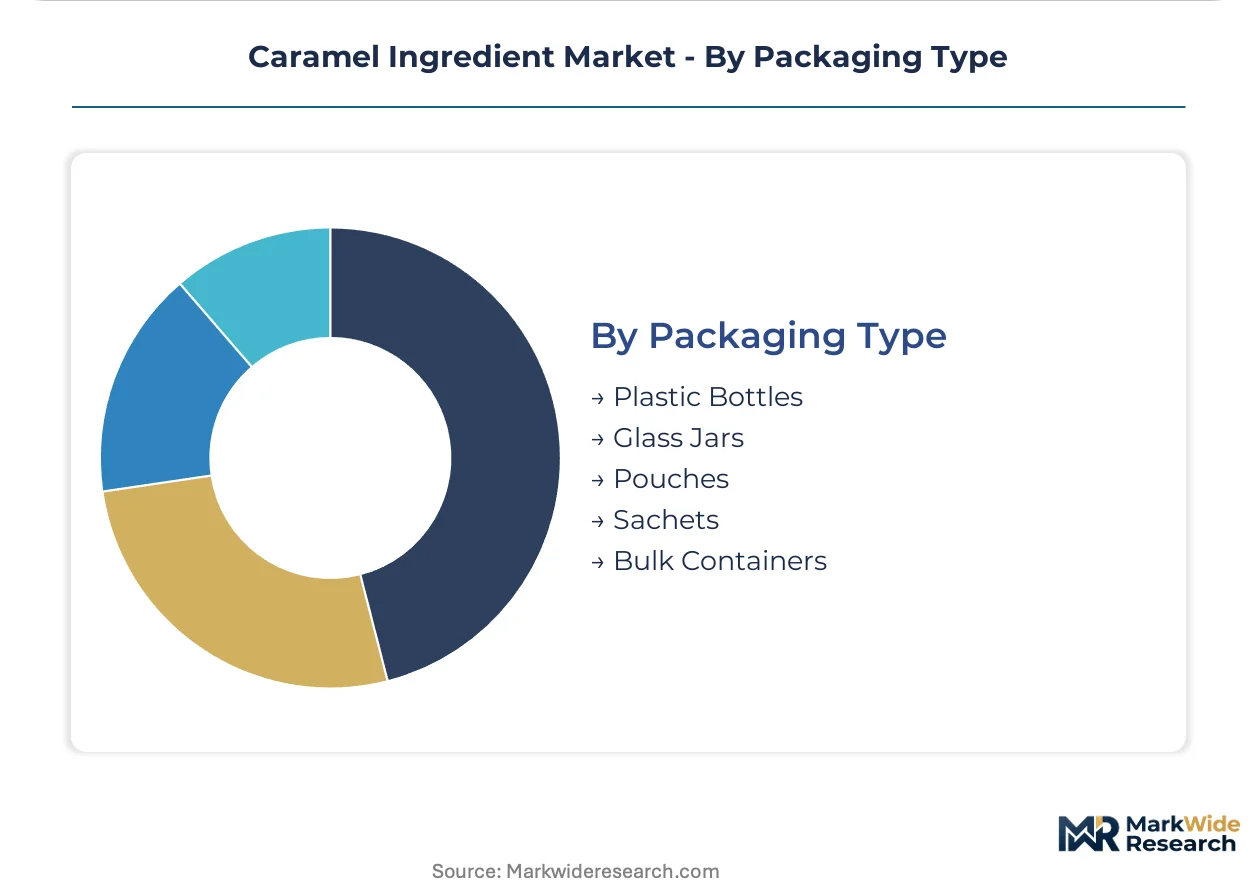
Packaging Type:
Packaging for caramel ingredients reflects end-user operational scale and requirements for preservation, handling efficiency, and distribution.
- Bulk Containers:These large-volume vessels, including drums and totes, serve industrial food and beverage manufacturers requiring substantial quantities. They optimize supply chain efficiency.
- Plastic Bottles:Common for retail and smaller commercial applications, these containers offer convenience and lighter weight for direct consumer use. Prevalence is notable in North American specialty beverages.
- Glass Jars:Preferred for premium products and retail, offering excellent barrier properties and perceived quality for specialty sauces.
- Pouches:Flexible and lightweight, gaining traction for single-serve or smaller commercial use, reducing waste.
- Sachets:Small, individual packets catering to portion control and convenience, often found in foodservice.
Industrial scale operations predominantly rely on Bulk Containers, while Plastic Bottles are expanding quickly in consumer-facing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its concentrated large-scale bakery and confectionery production centers, anchors significant caramel ingredient demand. This robust manufacturing base drives consistent demand for both liquid and powdered caramel formats. Global suppliers strategically focus on these high-volume markets for sustained growth.
United States
Consumer preference for clean-label formulations drives demand in the United States beverage and confectionery sectors. The US Food and Drug Administration (FDA) sets strict standards for caramel ingredient purity and labeling. Major food processing hubs, particularly across the Midwest, integrate caramel into new product lines.
Germany
European confectionery and dairy manufacturers in Germany seek customized caramel solutions for flavor and color applications. The European Food Safety Authority (EFSA) regulates caramel color classification and usage. Bavaria's strong food and beverage industry emphasizes premium caramel for its extensive product development.
India
India's expanding middle class fuels demand for processed foods, driving caramel ingredient use in confectionery and new beverage lines. The Food Safety and Standards Authority of India (FSSAI) enforces specific guidelines for food colorants and flavorings. Food processing zones in Maharashtra are increasingly adopting caramel for diverse product formulations.
Brazil
Brazilian bakery and dairy sectors show rising demand for caramel ingredients to enhance color and flavor in local products. The Agência Nacional de Vigilância Sanitária (ANVISA) oversees food additive approvals and labeling. São Paulo's extensive food manufacturing base represents a significant market for bulk liquid caramel.
China
Chinese confectionery producers and sauce manufacturers require caramel for both color and flavor in high-volume applications. The State Administration for Market Regulation (SAMR) establishes national food additive standards, influencing ingredient imports. The Yangtze River Delta region, a major food production hub, integrates caramel into its diverse food product portfolio.
Caramel Ingredient Market Key Industry Players
Top-tier vendors anchor the premium and specialty caramel ingredient market, while mid-sized regional players cater to volume-driven segments. The market exhibits a tiered structure, with a few large integrated suppliers and numerous specialized niche producers. Strategic archetypes include global ingredient powerhouses, flavor system innovators, and high-intensity color specialists. Capacity expansion and strategic partnerships are dominant competitive moves among these diverse entities.
Specialists in comprehensive ingredient solutions, such as Cargill, occupy a significant position by leveraging extensive supply chains for diverse caramel formats. Kerry Group plc exemplifies the flavor system innovator archetype, focusing on customized solutions for dairy and beverage clients. Sethness Roquette, a European-based entity, anchors the high-intensity color segment, providing specialized caramel for industrial applications requiring minimal dosage. These players demonstrate distinct approaches to market engagement.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Sensient Technologies Corporation |
| Tate & Lyle PLC |
| Puratos Group |
| Sethness Roquette |
| Ingredion Incorporated |
| D.D. Williamson Caramel |
| Others |
Cost & Logistics Intelligence
Consumer-led clean-label preferences compel caramel ingredient suppliers to reformulate and document products. This demand for specialized ingredients elevates production costs, influencing pricing structures across various market segments.
Pricing Analysis
Premium pricing applies to short lead times for highly customized caramel solutions, contrasting with discounts for spot inventory. The dominant pricing model involves contract-based long-term offtake agreements for industrial clients. Price differentiation stems from customization level for bespoke flavor systems and specific quality grades, such as high-color-intensity caramel. Pricing softness reflects intense competition from natural alternatives and raw material price volatility, making high-volume food manufacturers highly price-sensitive.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke pattern facilitate efficient caramel ingredient delivery to major food processing hubs. Geographic supply concentration for raw materials centers on regions producing corn, wheat, and sugarcane, notably the United States, Europe, and Brazil. The supply chain relies on these agricultural inputs, creating a structural risk of input price volatility. Distribution runs through direct sales for large industrial clients and specialized ingredient distributors for smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The caramel ingredient market operates as a supply-constrained story, particularly for specialized, high-intensity caramel colors. Limited production capacity for these advanced formulations props pricing for industrial applications.
For Market Incumbents: Deploy capacity addition for specialized, high-intensity caramel colors to meet industrial demand. Incumbents must invest in R&D for caramel alternatives that align with diverging 'natural' definitions, mitigating substitution threats from other natural colorants. Enhancing supply chain resilience against input price volatility also secures long-term market position. This approach addresses regulatory heterogeneity across key markets like the US and EU.
For New Entrants and Emerging Players: Capture white-space opportunities within the fast-growing plant-based food and beverage category. New entrants should target customized caramel flavor and color systems tailored for non-dairy formulations, offering clear differentiation. Penetration is most effective in emerging food processing hubs across Southeast Asia and Latin America. A direct partnership model with regional food manufacturers offers a viable go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized ingredient suppliers given the sustained demand for clean-label formulations. Long-term viability hinges on companies with strong R&D capabilities in high-intensity colors or natural caramel alternatives. Acquisition targets should focus on entities demonstrating batch-to-batch consistency and regulatory compliance across diverse markets. Increased regulatory harmonization on 'natural' definitions serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Intensity Caramel | Addresses industrial demand for minimal dosage colorants in specific applications. |
| R&D in Plant-Based Formulations | Develops tailored caramel solutions for non-dairy and vegan product categories. |
| Direct Partnership Model Adoption | Fosters collaborative co-development with key food and beverage manufacturers for bespoke ingredients. |
| Certification Investment for Clean-Label | Aligns caramel products with consumer preferences and evolving regulatory standards. |
| Geographic Expansion into Southeast Asia | Captures rising demand from an expanding middle class and evolving dietary habits. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic literature underwrites the qualitative findings. Primary interviews with R&D directors, procurement leads, and food scientists provided direct market insights. Secondary validation included FDA filings, EFSA reports, and FSSAI guidelines. A bottom-up and top-down triangulation approach ensured data accuracy.
Rate-of-change decomposition formed the basis of the quantitative forecast model across the analysis window. The model segmented the market by product type, application, end user, packaging type, and regional regulatory clusters. Compound annual growth rates derived from historical data reflected projected market shifts. Raw material price forecasts and new product launch pipelines served as key inputs.
The model holds under conditions of a stable regulatory environment and consistent consumer trends. Deviation in sudden shifts to clean-label definitions or major raw material supply disruptions would shift the forecast. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Camelina Oil Market
Ingredients
Meat Starter Culture Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Black Seed Oil Market
Ingredients
Hops Market
Ingredients
Fermented Rennet Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Europe Corn Glucose Market
Ingredients
Cocoa Market
Ingredients
Protein Hydrolysate Market
Ingredients
Cognitive Ingredients Market
Ingredients
North America Cocoa Products Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Jojoba Oil Market