
 Salt Market | 2026-2036
Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Salt Market Analysis
Multi-source procurement from both captive mines and third-party suppliers is expanding across the salt industry. K+S AG leverages its vertical integration into potash and magnesium co-production to sustain cost advantages in European de-icing markets. Tata Chemicals Limited anchors its position through backward integration into Sambhar Lake brine extraction, while Cargill Inc. competes via its control of North American evaporated-salt capacity and food-grade certification networks.
Salt is sodium chloride obtained through solar evaporation, rock mining, or vacuum evaporation, typically refined to 99% purity or higher for food and industrial applications. Solar-evaporated sea salt dominates volume production, though vacuum-refined salt commands premium positioning in pharmaceutical and food-grade segments. Rock salt leads the industrial application category, particularly for highway de-icing and chemical feedstock, while pharmaceutical-grade salt carries the highest margin pool due to USP and EP certification requirements. The food and beverage application segment differentiates through iodization, anti-caking additives, and grain-size specifications tailored to processed meat and bakery formulations.
The FDA governs food-grade salt purity and iodization standards in the United States, while the EPA regulates brine discharge and extraction permits for solar evaporation facilities. REACH and the EU Green Deal shape European market access by mandating carbon footprint disclosures and restricting energy-intensive vacuum evaporation methods. Stakeholders must monitor evolving iodization mandates in emerging economies and the shift toward low-sodium reformulations that could redirect demand from commodity table salt toward potassium-enriched and specialty mineral salts.
Market Dynamics
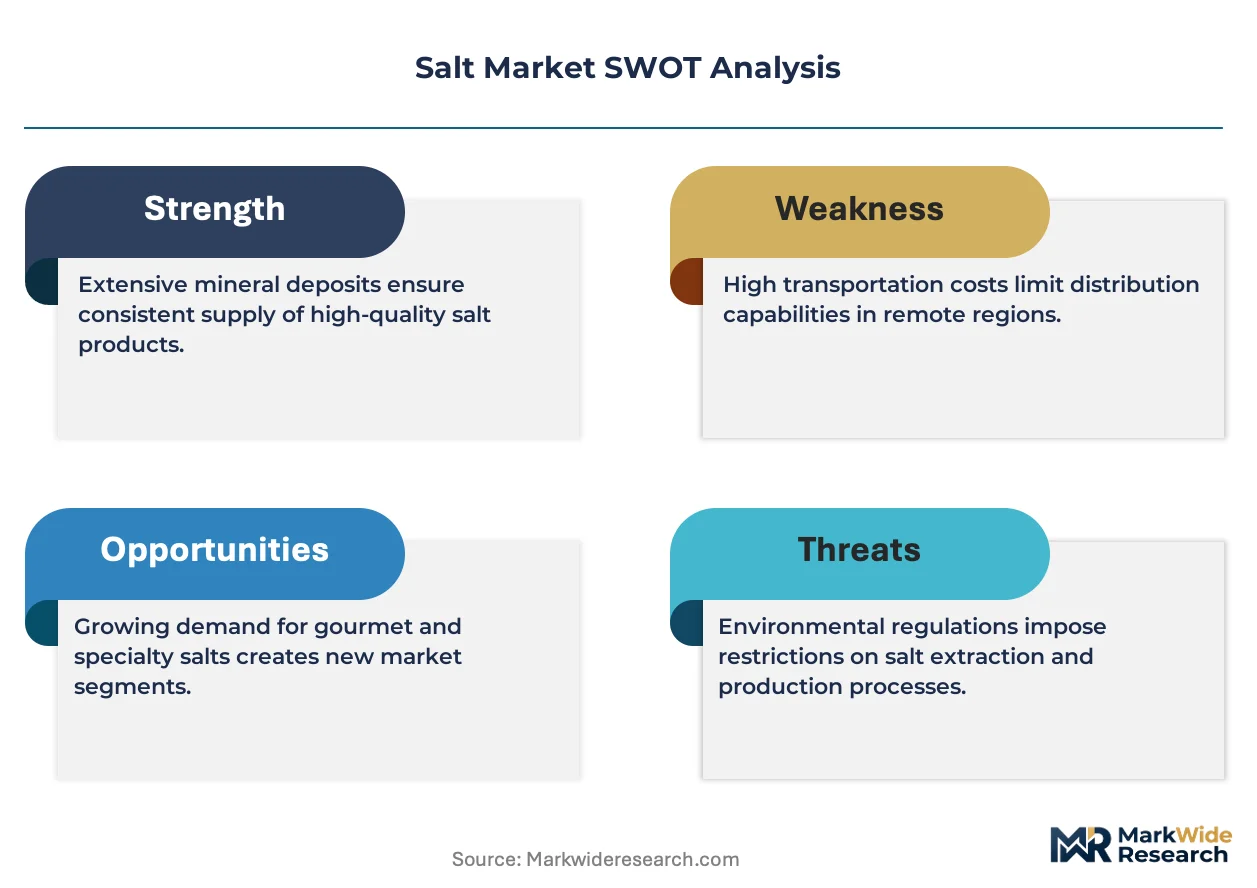
The EU F-Gas Regulation and Green Deal are compressing allowable energy intensity for vacuum evaporation facilities, forcing processors to reconfigure brine concentration methods or absorb carbon border adjustment costs.
Growth Catalysts
- Clean-label food processing:Specialty salt demand accelerates as manufacturers eliminate artificial additives from processed meat and bakery formulations. Grain-size specifications now drive premium positioning.
- PLI scheme infrastructure:India's production-linked incentive program for food processing builds bulk storage and handling capacity, pulling imported and domestic salt volumes into integrated supply chains.
- Iodization mandates:National health programs in emerging economies expand fortified salt distribution, creating contracted offtake for pharmaceutical-grade processors holding USP and EP certifications.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings directly impact vacuum evaporation economics, squeezing margin pools for pharmaceutical-grade producers dependent on thermal refining.
- Brine discharge permitting:EPA and state-level environmental regulators restrict solar evaporation expansion in coastal zones, concentrating production in permitted legacy sites with limited expansion headroom.
- Potassium chloride substitution:Low-sodium reformulations in packaged foods displace sodium chloride volumes in specific application segments, redirecting R&D investment toward mineral salt blends.
Strategic Opportunities
- Pharmaceutical-grade certification:USP and EP compliance creates defensible margin pools as generic drug manufacturers consolidate supplier bases around audited salt sources.
- Solar evaporation retrofits:Membrane pre-concentration technology convergence with traditional pond systems cuts energy intensity before thermal finishing, qualifying facilities for EU carbon border adjustments.
- Direct-to-foodservice distribution:Specialty and finishing salt producers bypass commodity traders, building e-commerce and specialty distributor channels for chef and restaurant segments.
Industry Challenges
- Process engineering talent scarcity:Brine chemistry and evaporative systems expertise concentrates at legacy facilities, constraining technical staffing for new plant commissioning and optimization.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and national regulator approvals for iodized and pharmaceutical grades extend product launch cycles by 18-24 months.
- Legacy pond infrastructure integration:Solar evaporation sites with decades-old levee and crystallizer designs require phased reconstruction to meet modern seismic and environmental standards without halting production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salt Market |
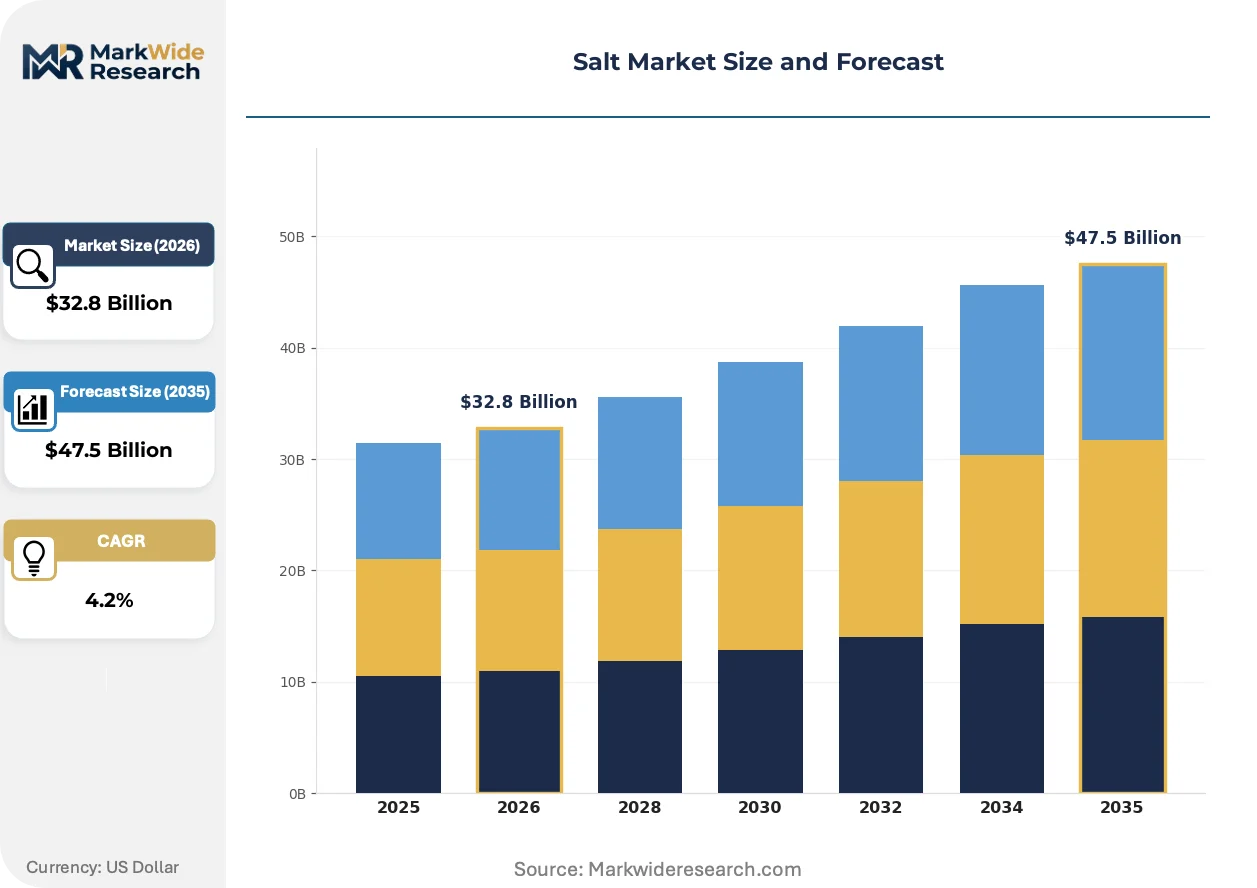
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Salt, Sea Salt, Himalayan Salt, Rock Salt Application: Food & Beverage, Industrial, Pharmaceutical, Water Treatment Distribution Channel: Online Retail, Supermarkets, Wholesalers, Convenience Stores End User: Households, Food Manufacturers, Restaurants, Healthcare Institutions |
| Companies Covered | K+S AG, Tata Chemicals Limited, Cargill Inc., QEMETICA, Ahir Salt Industries, China National Salt Industry Corporation, INEOS Enterprises Salt, Dominion Salt, Compass Minerals International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salt Market Emerging Trajectories
Processing technology and regulatory compliance requirements are compressing the technology gap between commodity and specialty salt production, while buyer consolidation reshapes procurement patterns.
Membrane pre-concentration systems are unifying brine treatment workflows across solar and vacuum evaporation facilities. Food-grade and pharmaceutical processors deploy nanofiltration and reverse osmosis to reduce thermal energy loads before final crystallization. This convergence is collapsing the capital cost differential between commodity sea salt and refined vacuum salt, enabling mid-scale entrants to compete on certification rather than scale alone.
REACH and the EU Green Deal now mandate granular carbon footprint disclosures for imported salt and chemical feedstocks. Processors must document energy sources and transport emissions across the value chain or face exclusion from public procurement and large industrial buyer vendor lists. German and Dutch chemical manufacturers are responding by sourcing from solar-evaporation sites with verified renewable energy certificates, shifting volume away from gas-dependent vacuum facilities.
Food manufacturers now bundle salt procurement with broader ingredient platform contracts, consolidating supplier relationships from dozens to single-digit approved vendors. This concentration favors processors with multi-grade certification capabilities and integrated logistics networks. The shift is most pronounced in North American processed meat and European bakery verticals, where procurement teams prioritize audit efficiency and supply security over unit cost minimization.
Salt Market Segmentation
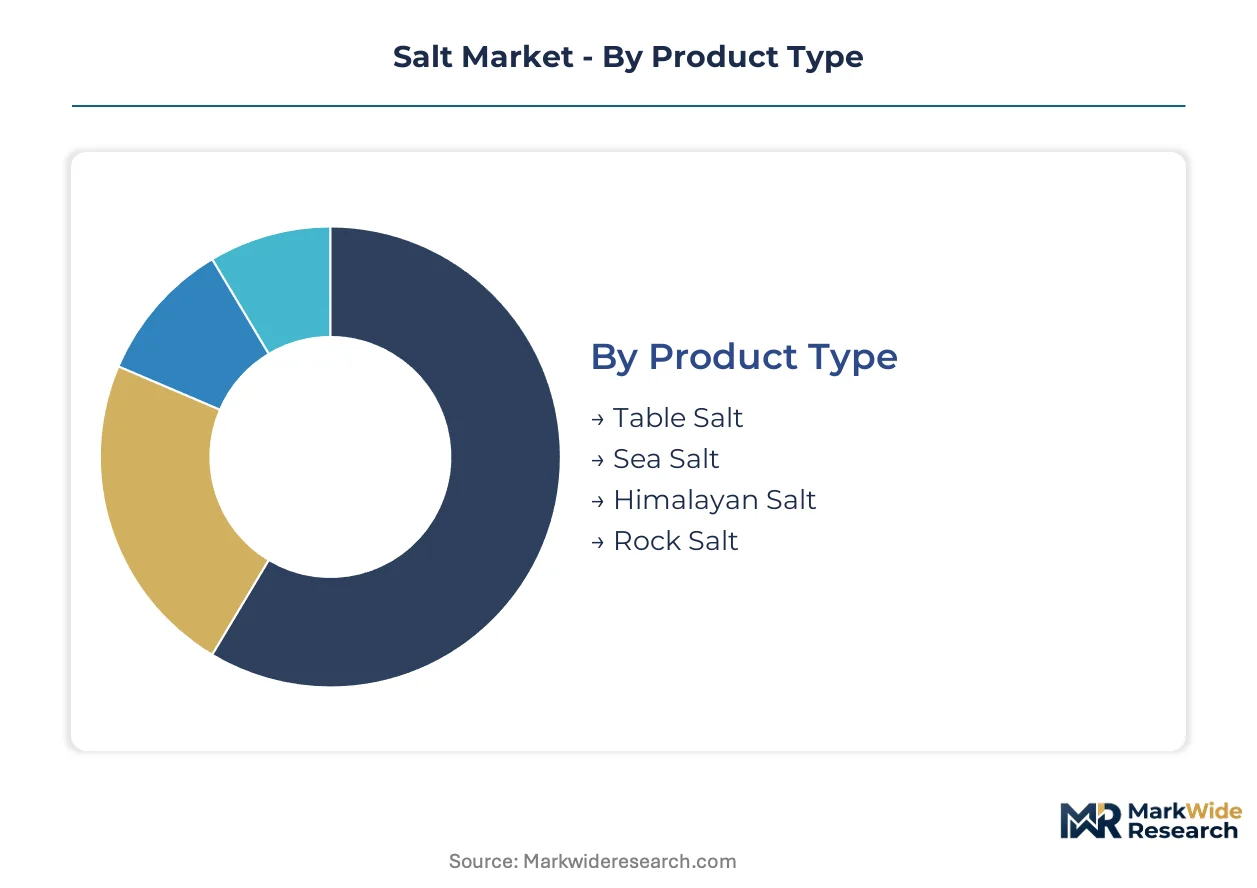
Salt market segmentation reveals how purity grades, certification requirements, and logistics configurations fragment what appears as a commodity trade. Processors configure production lines around specific end-use specifications rather than attempting universal coverage.
Product Type:
Extraction and refining technology defines cost structures and margin potential across salt categories.
- Table Salt:Vacuum-evaporated sodium chloride refined to 99.9% purity with iodine fortification and anti-caking additives. Food manufacturers in India and Brazil source this grade under national health program contracts tied to FSSAI and ANVISA iodization mandates.
- Sea Salt:Solar-evaporated product retaining trace minerals and variable grain structures. Clean-label bakery and processed meat formulations in Germany and the Netherlands specify this grade for its minimal processing narrative, though REACH carbon disclosure requirements now filter sourcing to renewable-powered evaporation sites.
- Himalayan Salt:Pink-hued rock salt mined from Pakistan's Khewra deposits, marketed for trace iron and potassium content. Premium positioning in direct-to-consumer channels and specialty foodservice drives pricing multiples above refined grades.
- Rock Salt:Crushed halite deposits with 95-98% purity, dominating highway de-icing in the United States and chemical feedstock applications. EPA brine discharge restrictions on solar expansion have renewed interest in mined alternatives for industrial buyers.
Mature deployment sits with rock salt for bulk industrial offtake. Newer deployment is concentrated in Himalayan and specialty sea salts for premium foodservice and wellness positioning.
Application:
End-use specifications diverge sharply on purity thresholds, documentation requirements, and volume scale.
- Food & Beverage:Formulation-grade salt with controlled grain-size distribution for processed meat emulsions and bakery yeast regulation. India's PLI scheme for food processing infrastructure is pulling bulk refined volumes into integrated supply chains serving domestic and export manufacturers.
- Industrial:Chlor-alkali feedstock and textile dyeing applications prioritize volume scale over certification. German chemical manufacturers now require documented renewable energy certificates for salt sourcing under EU Green Deal procurement rules.
- Pharmaceutical:USP and EP-certified sodium chloride for injectable solutions and dialysis fluids. Generic drug manufacturers in the United States and Europe are consolidating supplier bases around audited sources with multi-jurisdiction compliance.
- Water Treatment:Regeneration salt for ion-exchange systems in municipal and industrial softening. Specifications focus on purity consistency rather than food-grade certification, with regional distributors capturing fragmented demand.
Pharmaceutical-grade certification commands the steepest expansion trajectory as supplier consolidation and audit requirements raise barriers to entry.
Distribution Channel:
Channel selection reflects buyer scale, certification documentation needs, and inventory turnover requirements.
- Online Retail:Direct-to-consumer specialty salts and subscription-based replenishment for households and small restaurants. Himalayan and finishing salt producers bypass commodity traders through e-commerce platforms with traceability storytelling.
- Supermarkets:Packaged table salt and premium sea salt SKUs for household consumption. Retail consolidation in North America and Europe has reduced shelf space for regional brands in favor of multi-grade certified processors with national distribution.
- Wholesalers:Bulk industrial and foodservice volumes with pallet-scale logistics. Food manufacturers bundle salt procurement with broader ingredient platform contracts, consolidating supplier relationships from dozens to single-digit approved vendors.
- Convenience Stores:Emergency replenishment and single-unit table salt sales. Limited SKU depth restricts presence to commodity iodized grades with minimal brand differentiation.
Wholesaler relationships anchor industrial and food manufacturer procurement. Online channels are gaining share fastest among specialty salt producers seeking margin protection outside commodity pricing.
End User:
User type determines specification complexity, contract structure, and switching costs.
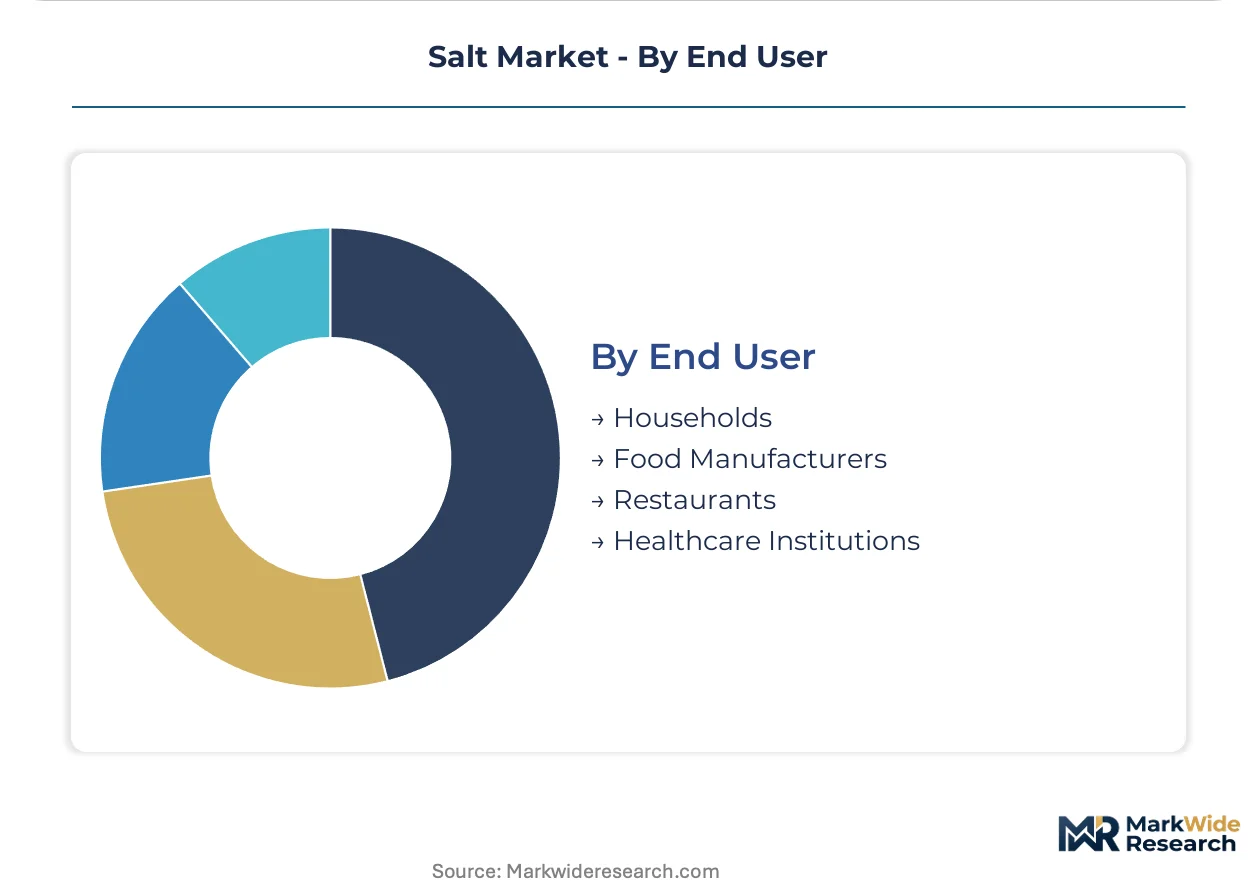
- Households:Price-sensitive consumption of iodized table salt with occasional premium experimentation. India's national iodization program distributes fortified salt through subsidized channels, creating contracted offtake for pharmaceutical-grade processors.
- Food Manufacturers:Large-scale buyers with formulation-specific grain-size and purity requirements. Processed meat and bakery verticals in North America prioritize audit efficiency and supply security over unit cost minimization.
- Restaurants:Finishing salt and specialty sea salt demand from chef-driven procurement. Direct distributor relationships and specialty foodservice platforms enable bypass of commodity traders for premium positioning.
- Healthcare Institutions:Pharmaceutical-grade sodium chloride for patient nutrition and dialysis applications. USP certification and lot traceability requirements limit supplier pools to audited processors with dedicated healthcare distribution.
Healthcare and food manufacturer segments concentrate premium-grade procurement. Restaurant and household channels are expanding most quickly for specialty and direct-to-consumer positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sambhar Lake in Rajasthan and Khewra mines in Pakistan anchor the raw-material base for South Asian salt supply. Brine extraction from coastal Gujarat and solar evaporation infrastructure in Tamil Nadu complement these inland deposits. European chemical manufacturers source from Mediterranean solar facilities and North Sea rock salt mines under tightening carbon disclosure mandates.
United States
Highway de-icing contracts and chlor-alkali feedstock demand drive bulk rock salt consumption. EPA brine discharge restrictions limit coastal solar expansion, concentrating production in permitted legacy sites around the Great Lakes. Compass Minerals International Inc. operates extensive evaporated-salt capacity serving food-grade and industrial markets from Midwestern facilities.
Germany
REACH and the EU Green Deal mandate granular carbon footprint documentation for imported chemical feedstocks. German processors source solar-evaporated salt with verified renewable energy certificates, shifting volume from gas-dependent vacuum facilities. K+S AG leverages potash and magnesium co-production from domestic mines to sustain cost advantages in European de-icing markets.
India
The PLI scheme for food processing infrastructure accelerates bulk refined salt offtake into integrated supply chains. FSSAI iodization mandates create contracted procurement for pharmaceutical-grade processors holding domestic certification. Tata Chemicals Limited anchors its position through backward integration into Sambhar Lake brine extraction serving domestic and export manufacturers.
China
Dual carbon goals and MIIT energy efficiency standards compress allowable intensity for vacuum evaporation facilities. China National Salt Industry Corporation controls domestic solar and rock salt production serving chemical and food processing verticals. Shandong and Jiangsu provinces concentrate membrane pre-concentration technology deployment to reduce thermal loads before crystallization.
Netherlands
EU F-Gas Regulation enforcement drives reconfiguration of brine concentration methods at Rotterdam-area chemical clusters. Dutch food manufacturers bundle salt procurement with broader ingredient platform contracts, consolidating supplier relationships toward multi-grade certified processors. INEOS Enterprises Salt operates integrated logistics networks serving Benelux industrial and pharmaceutical customers.
Salt Market Vendor Landscape
Capacity expansion dominates the current landscape as processors retrofit solar evaporation sites with membrane pre-concentration technology. The vendor base organizes around three strategic archetypes: diversified mining conglomerates with potash and magnesium co-production, vertically integrated chemical processors with captive salt units, and specialty refiners focused on USP and EP certification. M&A activity concentrates on pharmaceutical-grade asset acquisition, while strategic partnerships link solar operators with renewable energy certificate providers to satisfy EU procurement rules.
Among diversified mining conglomerates, K+S AG exemplifies the integrated model combining rock salt extraction with fertilizer and magnesium value chains. Tata Chemicals Limited and China National Salt Industry Corporation occupy positions within the state-linked and regionally dominant tier, anchoring supply security for domestic food processing and chemical manufacturing. Cargill Inc. represents the multinational agribusiness archetype with North American evaporated-salt capacity and established food-grade certification networks serving processed meat and bakery formulations.
| Leading Market Players |
|---|
| K+S AG |
| Tata Chemicals Limited |
| Cargill Inc. |
| QEMETICA |
| Ahir Salt Industries |
| China National Salt Industry Corporation |
| INEOS Enterprises Salt |
| Dominion Salt |
| Compass Minerals International Inc. |
| Others |
Supply Flow & Price Mechanics
Natural gas and electricity costs cascade through vacuum evaporation economics, compressing margins for pharmaceutical-grade processors while solar-evaporated sea salt retains cost advantage in food-grade tiers. Energy price volatility feeds directly into contract renegotiations between German chemical manufacturers and their salt suppliers.
Pricing Analysis
Certification-bundled pricing separates USP-grade pharmaceutical salt from unbundled commodity rock salt for highway de-icing. Three-tier pricing structure across premium, standard, and economy levels reflects purity grade, certification level, and volume scale differentiation. Pricing pressure stems from EU carbon border adjustments penalizing gas-dependent vacuum facilities. Food manufacturers exhibit lowest price sensitivity due to bundled ingredient platform contracts, while municipal de-icing procurement remains most price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements from food manufacturers and pharmaceutical buyers mandate multi-supplier qualification across India, Pakistan, and Germany. Raw material dependencies center on Sambhar Lake brine, Khewra rock deposits, and North Sea halite mines. Supply chain risk concentrates in brine discharge permitting restrictions limiting coastal solar expansion. Distribution runs through wholesaler networks for industrial offtake and specialty distributors for direct-to-foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permitted legacy pond capacity constraints prop pricing power for solar-evaporated grades as EPA and coastal regulators block greenfield expansion.
For Market Incumbents: Anchor market position through membrane pre-concentration retrofits at existing solar facilities, cutting energy intensity before EU carbon border adjustments bite. Deepen captive brine extraction control to offset potassium chloride substitution threats in low-sodium reformulation segments. Prioritize multi-jurisdiction FDA-EFSA certification maintenance to defend against audited supplier consolidation by generic drug manufacturers. For New Entrants and Emerging Players: Membrane technology convergence with traditional pond systems offers entry into mid-scale pharmaceutical-grade production without vacuum evaporation capital intensity. Target direct-to-foodservice distribution for Himalayan and specialty sea salts, bypassing commodity trader margins. Pursue renewable energy certificate partnerships with Mediterranean solar operators to qualify for German chemical manufacturer procurement lists. For Investors and Strategic Acquirers: USP and EP certification acquisition activity among generic drug manufacturers is the leading indicator that pharmaceutical-grade salt assets will command scarcity premiums. Frame five-to-ten year viability around carbon-adjusted cost positioning rather than scale alone. Monitor EU F-Gas Regulation enforcement timelines as inflection signal for stranded vacuum facility risk.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Pre-Concentration Retrofit | Reduces thermal energy loads at solar facilities ahead of EU carbon border adjustments. |
| Multi-Jurisdiction Certification Investment | FDA and EFSA simultaneous approval cuts product launch cycles for pharmaceutical processors. |
| Backward Integration into Brine Extraction | Sambhar Lake control secures raw material supply for Indian food processing PLI offtake. |
| Direct-to-Foodservice Channel Buildout | Specialty salt producers bypass commodity traders to capture chef-driven premium pricing. |
| Renewable Energy Certificate Partnership | Verified solar sourcing qualifies processors for German chemical manufacturer vendor lists. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at evaporation facilities, procurement leads at chlor-alkali manufacturers, pharmaceutical quality directors, and specialty foodservice distributors combined with FDA import alerts, ECHA REACH registrations, and Indian FSSAI iodization program reports. Bottom-up production capacity modeling and top-down demand segmentation triangulated volume estimates.
Granularity-level modeling tracked extraction technology, purity grade tier, end-use application, and regional regulatory cluster throughout the forecast period. CAGRs derived from weighted average of historical volume trends and projected capacity additions across solar, vacuum, and rock mining methods. Energy price scenarios and carbon border adjustment timelines fed into pharmaceutical-grade margin projections.
Several conditions sit outside the modeled scope, including abrupt iodization mandate reversals in emerging economies and breakthroughs in potassium chloride taste masking for low-sodium formulations. Deviation in EPA brine discharge permitting timelines or EU F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Cheese Ingredients Market
Ingredients
India Protein Market
Ingredients
Kilned Malt Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Ice Cream Bases Market
Ingredients
Campesterol Market
Ingredients
Fig Ingredient Market
Ingredients
Bleached Flour Market
Ingredients
India Olive Oil Market
Ingredients
Baobab Ingredient Market
Ingredients
Cottonseed Oil Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
Safflower Oil Market
Ingredients
Yeast and Yeast Extract Market