
 Interesterified CBE Market | 2026-2036
Interesterified CBE Market Size, Share, and Industry Trends Forecast 2026-2036
Interesterified CBE Market Foresight
The EU Deforestation Regulation is pivoting European confectionery procurement toward fully traceable interesterified CBE supply chains. Bunge Limited leverages its South American oilseed processing network to secure certified feedstock flows. AAK AB differentiates through enzymatic interesterification technology leadership in specialty fat formulations. Wilmar International Limited controls integrated palm oil refining capacity across Malaysian and Indonesian estates.
Interesterified cocoa butter equivalent denotes a structured lipid produced by rearranging fatty acid positions on glycerol backbones using chemical or enzymatic catalysts, yielding slip melting points between 32°C and 37°C that mimic natural cocoa butter crystallization behavior. Specialty Blends command premium positioning where manufacturers require precise polymorphic stability for enrobed chocolate applications. Partial Blend formulations anchor volume demand among cost-sensitive bakery shortening producers seeking cocoa butter extension without full replacement. The Fats & Oils application segment sustains the deepest margin pools due to technical specification density and long-term supply contracts.
EMA food contact guidelines, REACH chemical safety frameworks, and EFSA novel food assessments collectively determine European market access conditions for interesterified fat ingredients. FDA GRAS self-determination pathways and FEMA flavor substance evaluations shape US commercialization timelines for new CBE compositions. Stakeholders must monitor evolving deforestation traceability mandates and enzyme process patent expiries to calibrate capacity investments and formulation roadmaps.
Market Dynamics
Enzymatic interesterification is displacing chemical catalysis as the dominant production pathway, compressing processing temperatures from 200°C to below 80°C and enabling precise sn-2 positional specificity for cocoa butter crystallization mimicry.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation traceability for palm-derived feedstocks is accelerating certified supply chain investments across Malaysian and Indonesian processing clusters.
- Confectionery coatings:Chocolate manufacturers are reformulating enrobed products to reduce cocoa butter content while maintaining snap and gloss performance.
- Enzymatic process advances:Lipase immobilization technologies are reducing catalyst consumption and enabling continuous-flow reactor designs.
Market Restraints
- Palm oil price volatility:Crude palm oil futures on Bursa Malaysia Derivatives expose processors to margin compression during El Niño supply disruptions.
- Feedstock concentration risk:Southeast Asian plantation estates control over 85 percent of global palm oil exports, creating single-source dependency.
- REACH registration costs:ECHA substance evaluation fees and extended safety data requirements burden small-scale European compounders.
Strategic Opportunities
- Indian confectionery expansion:FSSAI food additive approvals for interesterified fats in chocolate compounds open formulation access to a 1.4 billion consumer market.
- Bakery shortening blends:Partial CBE incorporation in laminated dough applications addresses trans-fat elimination mandates without full formulation overhaul.
- CSRD sustainability reporting:Corporate supply chain disclosure requirements create premium positioning for fully traceable, enzymatically processed specialty grades.
Industry Challenges
- Enzyme biocatalyst supply:Immobilized lipase production capacity concentrates among Danish and Japanese biotechnology suppliers, creating procurement bottlenecks.
- Polymorphic stability certification:Confectionery manufacturers require 12-18 month shelf-life validation protocols before approving new CBE suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interesterified CBE Market |
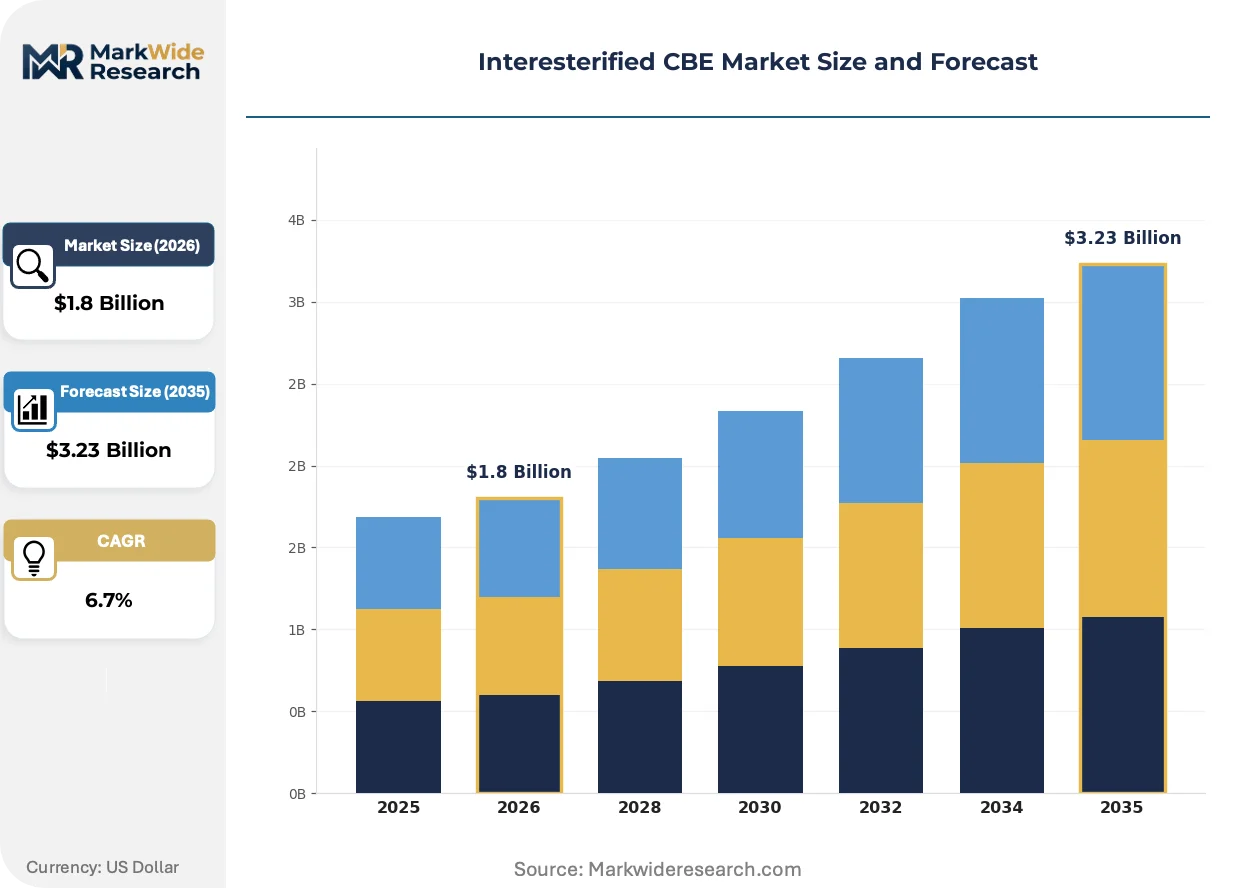
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Blend, Partial Blend, Specialty Blends, Unique Compositions End User: Food Industry, Bakery Products, Dairy Alternatives, Confectionery Application: Fats & Oils, Creamers, Margarine, Shortenings Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Bunge Limited, Archer-Daniels-Midland Co., AAK AB, Mewah International Inc, 3F Industries Limited, Fuji Oil Holdings, Wilmar International Limited, IOI Corporation Berhad, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interesterified CBE Market Shifts & Advancements
Process intensification and regulatory traceability mandates are converging to reshape competitive advantage around enzymatic precision and supply chain transparency rather than scale economies alone.
Continuous enzymatic interesterification using packed-bed reactor configurations is modularizing production economics for mid-scale processors. Specialty fat compounders in Belgium and the Netherlands are retrofitting batch plants with plug-flow systems. This architecture is compressing capital requirements and enabling distributed manufacturing closer to European confectionery customers.
REACH Annex XIV authorization procedures for chemical catalyst residues are tightening specification tolerances for food-grade fat derivatives. ECHA substance evaluation workflows now prioritize glycerol ester categories used in infant formula applications. German and Swiss chocolate manufacturers are advancing enzymatic-only procurement policies to preempt regulatory friction.
Confectionery procurement teams are consolidating supplier panels around vertically integrated processors with captive plantation certification. Tier-one chocolate brands in France and Italy now require geolocation coordinates for every palm oil shipment. This concentration is displacing spot-market traders and favoring Malaysian estate groups with blockchain-enabled traceability infrastructure.
Interesterified CBE Market Segmentation
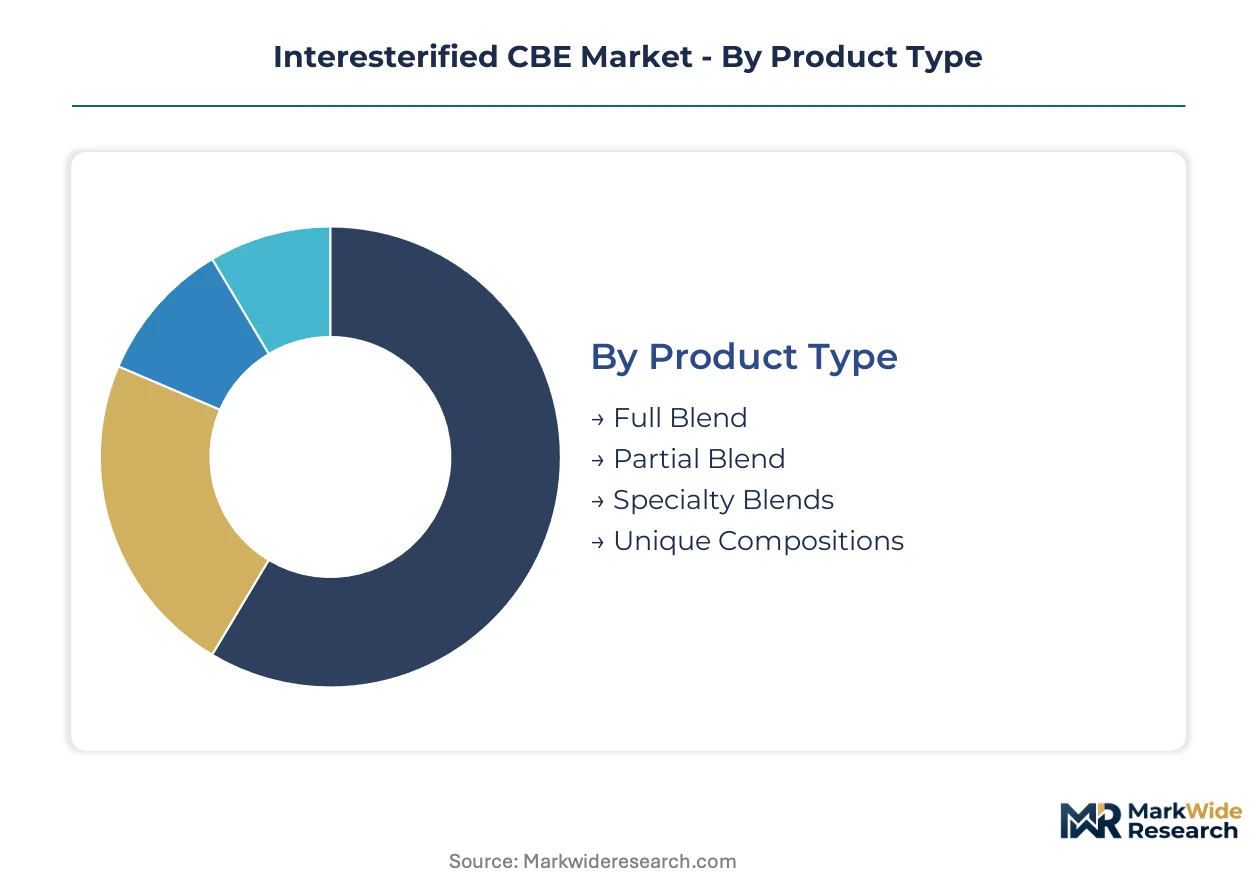
Interesterified CBE formulations fragment across functional performance tiers, each commanding distinct procurement workflows and specification densities. Supply chain configuration varies sharply by segment, with enzymatic processing capacity concentrating in specialty grades while chemical routes anchor volume production.
Product Type:
Malaysian and Indonesian plantation groups control feedstock flows into each product tier, with enzymatic capacity allocating disproportionately toward higher-margin formulations.
- Specialty Blends:These formulations deliver precise sn-2 positional specificity for polymorphic stability in enrobed chocolate applications. Belgian and Dutch compounders dominate demand for enzymatically processed grades with full geolocation traceability under EU Deforestation Regulation mandates.
- Partial Blend:Manufacturers incorporate these for cocoa butter extension in cost-sensitive bakery shortenings without full replacement. Indian and Southeast Asian margarine producers drive volume procurement, prioritizing trans-fat elimination compliance over crystallization precision.
- Full Blend:Complete cocoa butter replacement formulations for confectionery coatings requiring snap and gloss performance.
- Unique Compositions:Custom-tailored lipid structures for infant formula and pharmaceutical excipient applications.
Partial Blend absorbs the bulk of installed capacity; Specialty Blends is expanding most quickly.
End User:
Customer procurement sophistication divides the market, with tier-one chocolate brands demanding 12-18 month shelf-life validation protocols.
- Confectionery:Enrobed product manufacturers reformulate to reduce cocoa butter content while maintaining sensory performance. French and Italian chocolate houses now require blockchain-enabled geolocation coordinates for every palm oil shipment.
- Food Industry:Broad industrial food manufacturers source CBE for compound coatings and filling fats.
- Bakery Products:Laminated dough producers incorporate partial CBE for trans-fat elimination without formulation overhaul.
- Dairy Alternatives:Plant-based creamer and ice cream manufacturers utilize CBE for fat body and mouthfeel replication.
Confectionery commands the deepest margin pools; Dairy Alternatives is climbing the fastest on plant-based formulation trends.
Application:
Technical specification density varies by application, with Fats & Oils sustaining long-term supply contracts while margarine operates on shorter procurement cycles.
- Fats & Oils:Technical fat bases for industrial compounders and specialty lipid refiners. REACH Annex XIV authorization procedures for chemical catalyst residues tighten specification tolerances for these food-grade derivatives.
- Shortenings:Bakery and pastry applications requiring plastic fat functionality.
- Margarine:Table and industrial spreads utilizing CBE for crystallization control.
- Creamers:Non-dairy coffee whiteners and beverage fat systems.
Fats & Oils anchors contract volumes; Creamers is gaining share fastest on ready-to-drink beverage expansion.
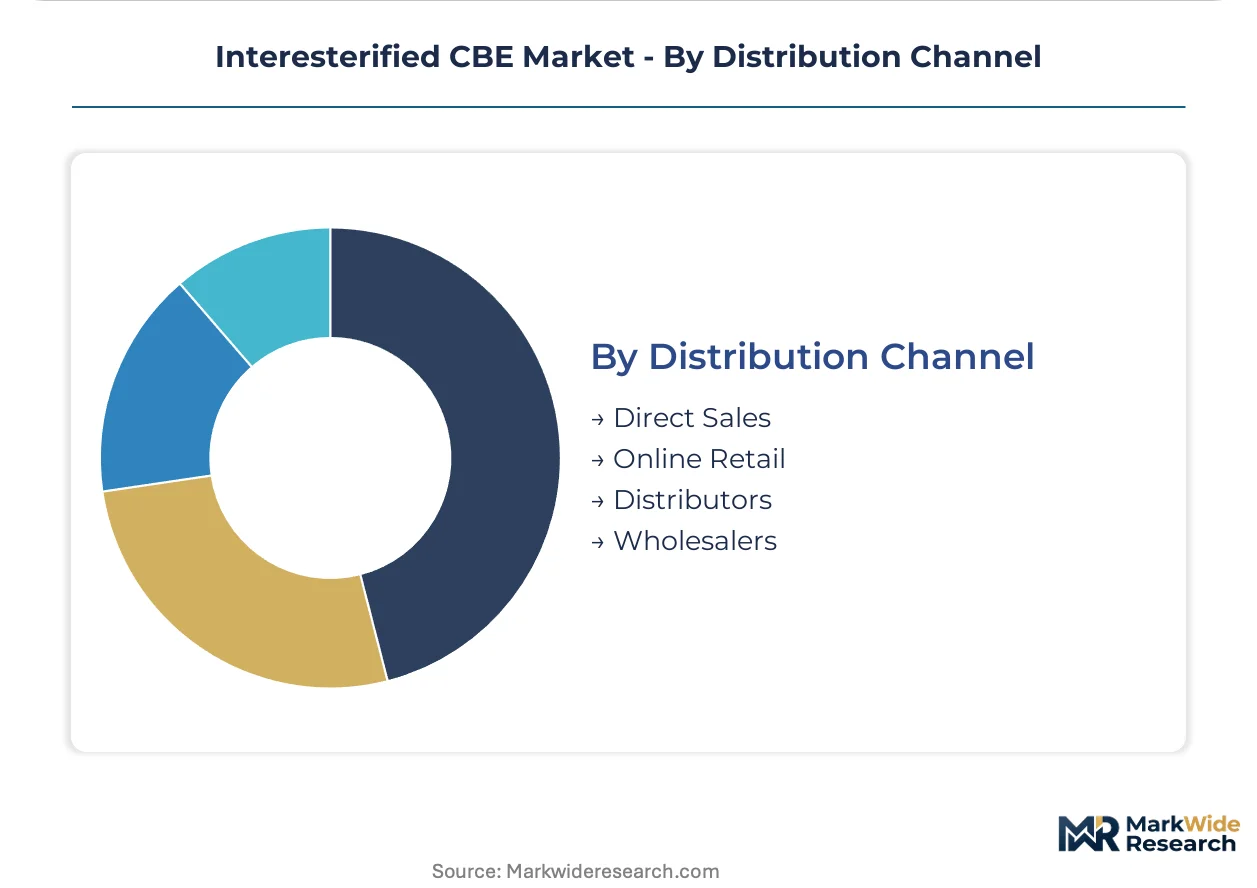
Distribution Channel:
Channel selection correlates with customer scale and formulation complexity, with direct relationships dominating specialty grades.
- Direct Sales:Vertically integrated processors with captive plantation certification supply tier-one confectionery brands directly. German and Swiss manufacturers advance enzymatic-only procurement policies through these channels.
- Distributors:Regional compounders and mid-scale food manufacturers access CBE through specialty chemical distributors.
- Wholesalers:Volume bakery and margarine producers source through commodity fat wholesalers.
- Online Retail:Small-scale artisan chocolate makers and research institutions procure sample quantities.
Direct Sales captures the highest value flows; Online Retail is expanding most quickly for sampling and small-batch access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia and Indonesia process the bulk of global palm oil feedstock, while European confectioners and North American food manufacturers absorb the highest-value finished product flows. This geographic split concentrates upstream margins in Southeast Asian plantation estates and downstream premiums in Western formulation laboratories.
Malaysia
Specialty enzymatic CBE production clusters around Port Klang and Pasir Gudang refining complexes serving EU Deforestation Regulation-compliant supply chains. The Malaysian Palm Oil Board enforces MSPO certification standards that now incorporate geolocation traceability for every export batch. Wilmar International Limited and IOI Corporation Berhad operate integrated refining capacity across Johor and Sabah estates with blockchain-enabled shipment tracking.
Indonesia
Volume chemical interesterification dominates Riau and North Sumatra processing hubs supplying Indian and Chinese bakery compounders. The Indonesian Sustainable Palm Oil certification system faces alignment pressure with EU Deforestation Regulation geolocation mandates. Dumai and Belawan port complexes handle bulk CBE exports to FSSAI-regulated Indian confectionery manufacturers expanding chocolate compound production.
Germany
Belgian and Dutch compounders serve German chocolate manufacturers advancing enzymatic-only procurement policies under REACH Annex XIV catalyst residue restrictions. The Federal Institute for Risk Assessment evaluates novel lipid structures for infant formula applications. Cologne and Hamburg house specialty fat laboratories conducting 12-18 month polymorphic stability validation for tier-one confectionery brands.
United States
Food manufacturers reformulate enrobed products under FDA GRAS self-determination pathways for reduced cocoa butter content. The Institute of Shortening and Edible Oils maintains processing standards for interesterified fat applications. Chicago and New Jersey processing centers source Malaysian-certified feedstock for North American confectionery coating production.
India
FSSAI food additive approvals for interesterified fats in chocolate compounds opened formulation access to domestic confectionery expansion. Gujarat and Maharashtra house margarine producers driving Partial Blend volume procurement for trans-fat elimination compliance. Mumbai refiners blend Southeast Asian palm fractions with local oilseed processing for cost-sensitive bakery shortening applications.
Interesterified CBE Market Competitive Landscape
The competitive structure tilts toward integrated plantation-to-refinery conglomerates with captive certification infrastructure. Three archetypes dominate: Southeast Asian estate groups controlling upstream feedstock flows, European specialty compounders commanding enzymatic technology premiums, and North American agribusiness houses with continental distribution networks. Capacity expansion and strategic partnerships constitute the primary competitive moves, with blockchain traceability investments now separating premium-tier suppliers from commodity processors.
Among Southeast Asian estate-integrated processors, Wilmar International Limited and IOI Corporation Berhad occupy positions anchored to Malaysian and Indonesian plantation certification infrastructure. Fuji Oil Holdings exemplifies the Japanese trading house archetype with regional refining footprints. AAK AB represents European enzymatic technology leadership within specialty fat formulation tiers. These named entities illustrate how geographic origin and corporate structure align with distinct value chain positioning rather than interchangeable commodity competition.
| Leading Market Players |
|---|
| Bunge Limited |
| Archer-Daniels-Midland Co. |
| AAK AB |
| Mewah International Inc |
| 3F Industries Limited |
| Fuji Oil Holdings |
| Wilmar International Limited |
| IOI Corporation Berhad |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Tier-one confectionery manufacturers in France and Italy anchor pricing power through blockchain-enabled geolocation mandates, forcing contract structures that reward certified enzymatic grades over spot-market chemical alternatives. This buyer concentration compresses margins for commodity processors while securing premium flows for integrated plantation groups.
Pricing Analysis
Margin tightening in Partial Blend formulations reflects crude palm oil futures volatility on Bursa Malaysia Derivatives during El Niño disruptions. Three-tier pricing structure across enzymatic specialty, chemical standard, and unverified economy levels separates buyers by certification completeness. Cost-down pressure on chemical-route processors accelerates as REACH Annex XIV residue restrictions trigger reformulation costs. Volume-sensitive Indian margarine producers exhibit highest price elasticity; German chocolate houses accept substantial premiums for full traceability.
Supply Chain Analysis
EU Deforestation Regulation geolocation mandates are reshaping sourcing toward Malaysian MSPO-certified estates and Indonesian ISPO-aligned plantations. Feedstock draws from Southeast Asian palm oil clusters, with immobilized lipase biocatalysts sourced from Danish and Japanese biotechnology suppliers. Single-source dependency on Southeast Asian plantation estates concentrates risk during regulatory alignment delays. Distribution runs through vertically integrated processors with captive certification infrastructure serving tier-one confectionery brands directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme biocatalyst production capacity concentrates among limited biotechnology suppliers, propping pricing for specialty enzymatic grades and creating supply-constrained conditions for precision-formulation tiers.
For Market Incumbents: Extend backward integration into immobilized lipase production partnerships to secure catalyst supply against Danish and Japanese supplier bottlenecks. Deepen captive plantation certification infrastructure across Johor and Sabah estates to preempt EU Deforestation Regulation compliance gaps. Lock long-term offtake agreements with tier-one confectionery brands before polymorphic stability validation protocols freeze supplier panels. For New Entrants and Emerging Players: Launch via distributed enzymatic processing using modular packed-bed reactor configurations serving mid-scale European compounders retrofitting batch plants. Target Indian FSSAI-approved chocolate compound manufacturers expanding production for domestic confectionery growth. Differentiate through blockchain-enabled traceability infrastructure that larger estate groups deploy slowly. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Belgian and Dutch compounders with enzymatic technology licenses and established shelf-life validation protocols. Long-term viability hinges on regulatory alignment between Southeast Asian certification systems and EU geolocation mandates. Watch for ECHA substance evaluation prioritization shifts on glycerol ester categories as inflection signal for chemical-route asset obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Capacity Expansion | Continuous-flow reactor investments enable modular production economics for mid-scale European processors. |
| Blockchain Traceability Infrastructure | Geolocation tracking satisfies EU Deforestation Regulation mandates for French and Italian chocolate manufacturers. |
| Backward Integration into Biocatalyst Supply | Captive lipase production secures enzyme access against Danish and Japanese supplier concentration. |
| Long-term Supply Agreement | Contract structures with tier-one brands lock volumes before 12-18 month validation protocols freeze panels. |
| Green Manufacturing Transition | Enzymatic processing below 80°C displaces 200°C chemical routes under REACH Annex XIV pressure. |
Research Methodology
Multi-period observation of palm oil futures volatility, enzymatic patent expiries, and regulatory alignment timelines anchored the trend analysis, supplemented by interviews with specialty fat compounders, plantation certification officers, confectionery procurement directors, and ECHA regulatory affairs specialists. Secondary validation drew from Malaysian Palm Oil Board export statistics, Bursa Malaysia Derivatives trading data, ECHA substance evaluation workflows, and FSSAI food additive approval registers. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Input-output matrices mapped feedstock flows from Riau and North Sumatra processing hubs through Belgian and Dutch formulation laboratories to German and Italian chocolate manufacturers. Segmentation dimensions spanned product type tiers, end-user procurement sophistication, application technical density, and distribution channel control levels. CAGRs derived from elasticity-adjusted demand curves incorporating cocoa butter price substitution effects and trans-fat elimination mandate compliance timelines. Forecast inputs included El Niño cycle probability distributions and REACH Annex XIV authorization schedules.
The model assumes enzymatic interesterification displacement of chemical catalysis as dominant pathway; alternative chemical catalyst innovation or lipase production breakthroughs would alter the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and plantation certification adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Astragalus Root Extract Market
Ingredients
Bromelain Ingredient Market
Ingredients
Europe Protein Market
Ingredients
United States Avocado Oil Market
Ingredients
Europe Corn Glucose Market
Ingredients
L-Arabinose Market
Ingredients
Lentils Flour Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Torula Yeast Market
Ingredients
Passion Fruit Powder Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Ice Cream Ingredients Market