
 Mung Bean Starch Market | 2026-2036
Mung Bean Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Mung Bean Starch Market Insights
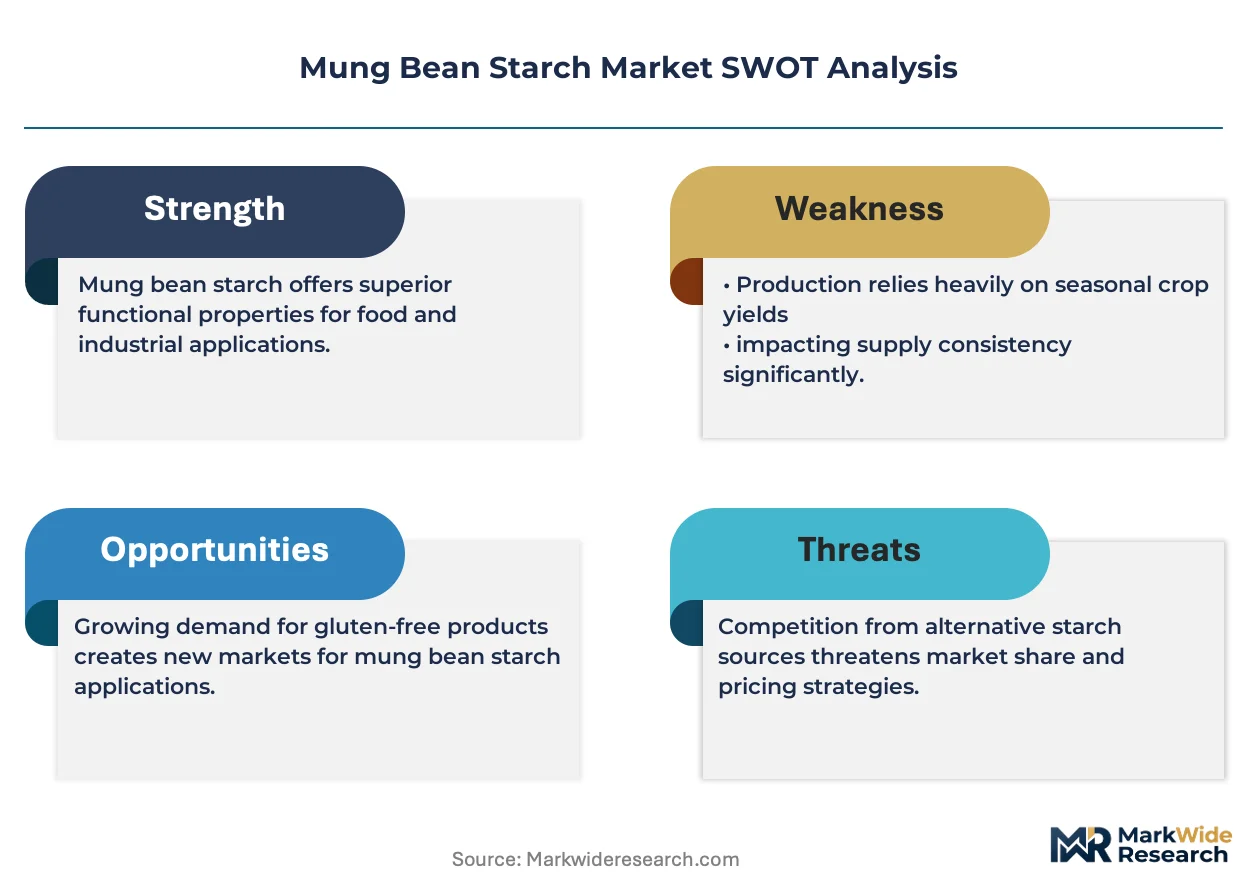
The shift from outsourced bean procurement to captive mung bean farming is hardening across major suppliers. Ingredion leverages long-term grower contracts in Asia to secure non-GMO bean streams. Cargill anchors its position through direct sourcing partnerships with Thai and Myanmar agricultural cooperatives. Tate & Lyle competes by specializing in high-purity modified starch grades for pharmaceutical excipient applications.
Mung bean starch is a carbohydrate polymer extracted from Vigna radiata seeds, containing approximately 25-28% amylose and exhibiting peak gelatinization temperatures near 65-70°C, rendering it indispensable for transparent noodle sheets and biodegradable film formulations. Native starch dominates food processing applications due to its clean-label appeal among Asian noodle manufacturers, while modified starch commands premium positioning in pharmaceutical tablet binding where cross-linked variants resist shear degradation during high-speed compression. Pregelatinized starch is gaining traction in instant food formulations as manufacturers seek cold-water dispersibility without cooking infrastructure.
China's SAMR enforces GB standards for food-grade starch purity that restrict heavy metal content and microbial thresholds, directly filtering small-scale processors from supermarket supply chains. The FDA's GRAS designation framework and evolving EPA guidelines on agricultural runoff from bean cultivation shape export eligibility for US-bound shipments. Stakeholders must monitor how EU REACH compliance costs for imported starch derivatives alter European market access thresholds relative to domestic pulse processors.
Market Dynamics
Captive mung bean cultivation is hardening supply chains across Southeast Asia as processors abandon spot-market procurement. China's SAMR enforcement of GB standards for heavy metal limits and microbial purity is filtering small-scale processors from supermarket supply chains.
Growth Catalysts
- Clean-label noodle manufacturing:Transparent sheet production for vermicelli and glass noodles in Vietnam and Thailand relies on native starch with minimal processing. Asian food manufacturers prioritize single-ingredient labeling for export to European retailers.
- EU REACH compliance tailwinds:Import restrictions on chemically modified starches create preference windows for naturally extracted alternatives. European pharmaceutical formulators source high-purity grades for tablet binding applications.
- Biodegradable film R&D:Mung bean amylose content near 28% enables thermoplastic processing without synthetic additives. Packaging engineers in South Korea and Japan test starch-based barrier coatings for fresh produce.
Market Restraints
- Input cost volatility:Mung bean prices fluctuate with monsoon patterns across Myanmar and India's central plains. Processors lack hedging instruments for pulse commodity exposure.
- Supply concentration risk:Over half of global modified starch capacity clusters in Shandong and Jiangsu provinces. Regional flooding or power rationing disrupts export fulfillment schedules.
- Technical limitation in high-shear applications:Native starch granules rupture under extrusion pressures above 150 bar. Snack manufacturers blend with tapioca or potato derivatives to achieve texture stability.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya import limited volumes of Asian-origin starch for instant noodle production. Local pulse processing infrastructure remains undeveloped.
- Pharmaceutical excipient specialization:Cross-linked variants resist degradation during high-speed tablet compression. US and European drug manufacturers seek non-GMO, allergen-free binding agents.
- Indian PLI scheme alignment:Food processing incentives under the Production Linked Incentive framework subsidize capital equipment for starch extraction units. Domestic vermicelli brands expand manufacturing footprints.
Industry Challenges
- Certification timeline compression:FSSAI licensing for Indian starch exporters requires 14-18 months for facility audits and heavy metal documentation. Delays lock working capital in inventory.
- Skill scarcity in modified starch chemistry:Cross-linking and esterification expertise concentrates among retiring technicians in Chinese state-owned enterprises. Knowledge transfer programs remain underfunded.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mung Bean Starch Market |
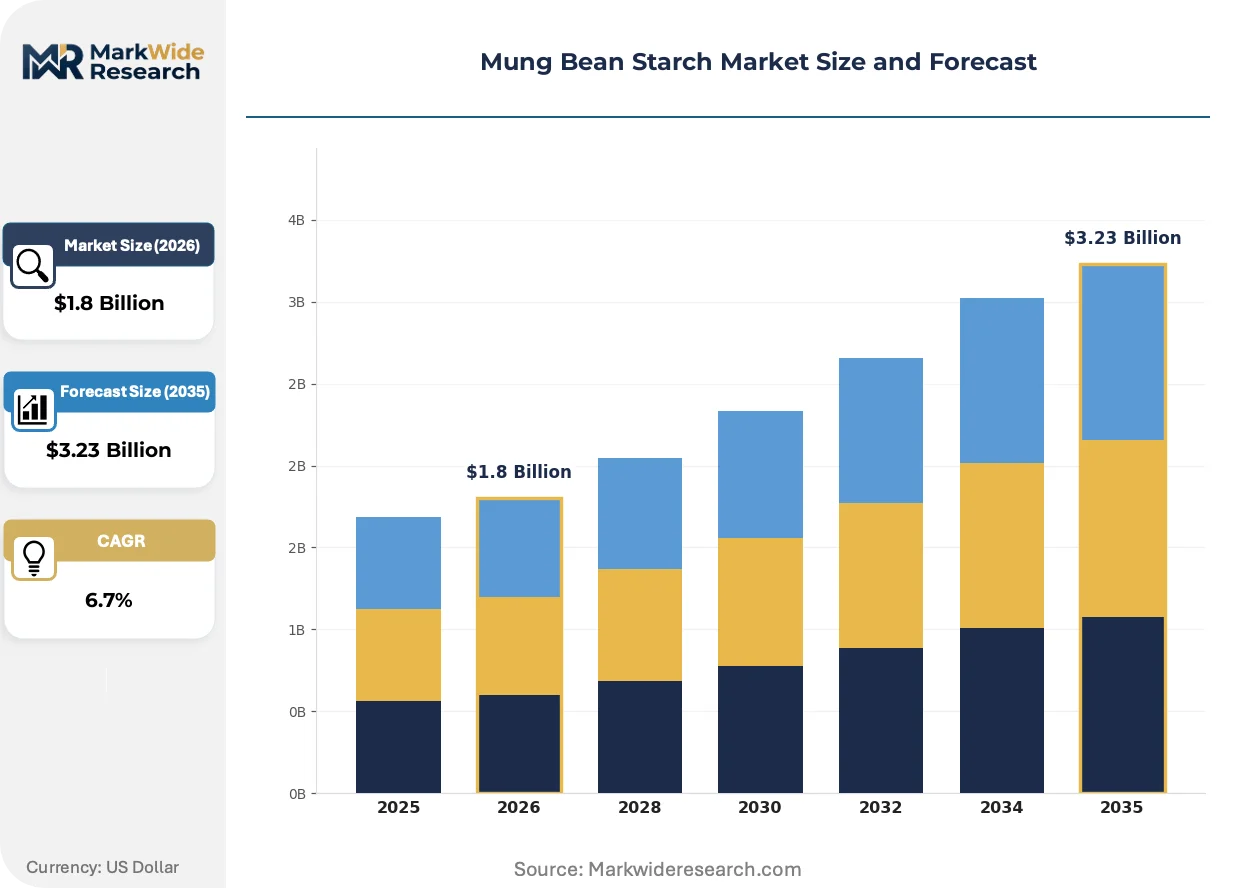
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Pregelatinized Starch, Modified Starch, Cross-linked Starch Application: Food Processing, Textile Printing, Paper Production, Pharmaceuticals, Biodegradable Packaging End User: Food Manufacturers, Textile Mills, Paper Mills, Drug Manufacturers, Packaging Firms Packaging Type: Bulk Bags, Paper Bags, Plastic Bags, Vacuum-sealed Packs, Cardboard Boxes |
| Companies Covered | Sitthinan Company Limited, Harbin Hada Starch Co., Ltd., Castle Ingredients, Relsus Pte. Ltd., Yantai Oriental Protein Tech Co., Ltd., Ingredion, Cargill, Archer Daniels Midland Company, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mung Bean Starch Market Trends and Innovations
Processing automation and regulatory harmonization are compressing batch-to-batch variation while expanding addressable applications. Technology deployment favors mid-scale facilities with capital discipline.
Enzymatic extraction systems are automating the separation of starch granules from mung bean protein and fiber matrices. Thai and Vietnamese processors retrofit existing rice starch lines with fungal amylase dosing and membrane filtration stages. The capital efficiency of these retrofits is compressing payback periods to under four years for 10,000-tonne annual facilities.
China's SAMR updated GB 31637-2023 standards for edible starch in early 2024, tightening lead limits to 0.5 ppm and mandating HACCP documentation for export certification. Industrial consequence includes accelerated consolidation among Shandong processors unable to afford atomic absorption spectrometry equipment. Pharmaceutical-grade starch shipments to Europe now require third-party laboratory verification of aflatoxin levels.
Long-term grower contracts are displacing spot-market bean procurement among Southeast Asian processors. Thai agricultural cooperatives negotiate three-year supply agreements with fixed base prices and quality premiums for non-GMO certification. The contracting model concentrates procurement leverage among processors with balance-sheet capacity to prepay planting cycles.
Mung Bean Starch Market Segmentation
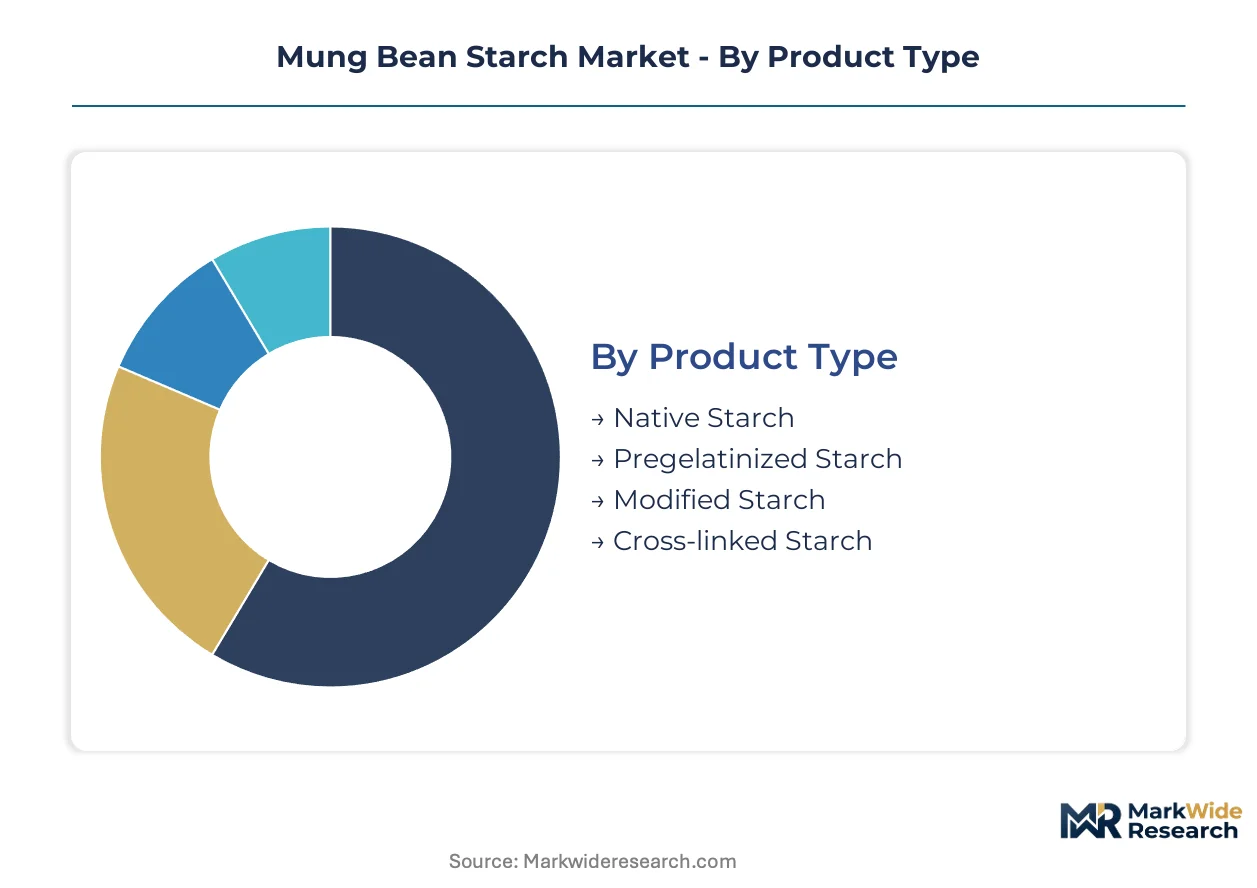
Mung bean starch processors configure product lines around gelatinization behavior and modification chemistry. Capital deployment varies sharply across extraction, modification, and pregelatinization equipment tiers. Application requirements in noodles, pharmaceuticals, and packaging drive divergent purity and functional specifications.
Product Type:
Capital intensity peaks with cross-linking reactors and esterification vessels, while native extraction demands simpler wet-milling infrastructure.
- Native Starch:Extracted through aqueous separation without chemical alteration, retaining 25-28% amylose content and peak gelatinization near 65-70°C. Vietnamese and Thai noodle manufacturers source this grade for transparent vermicelli sheets where single-ingredient labeling satisfies European retailer requirements. Clean-label positioning commands premium pricing against modified alternatives.
- Modified Starch:Subjected to etherification or esterification to enhance freeze-thaw stability and acid resistance. Shandong and Jiangsu province processors dominate installed capacity, supplying instant food manufacturers with viscosity-stable thickeners. SAMR enforcement of GB 31637-2023 heavy metal limits is filtering small-scale operators from supermarket supply chains.
- Pregelatinized Starch:Thermally treated for cold-water dispersibility, eliminating cooking infrastructure for instant formulation producers.
- Cross-linked Starch:Chemically bonded to resist shear degradation under high-speed tablet compression, serving pharmaceutical excipient applications.
Most installed capacity flows through Native Starch. Expansion is steepest in Modified Starch.
Application:
Volume concentration tracks Asian noodle manufacturing clusters, while margin concentration sits with pharmaceutical and specialty packaging segments.
- Food Processing:Transparent sheet production for glass noodles and vermicelli consumes the largest starch volumes. Thailand and Vietnam anchor demand, with processors retrofitting rice starch lines for enzymatic mung bean extraction. Fungal amylase dosing and membrane filtration stages compress payback periods for mid-scale facilities.
- Pharmaceuticals:Tablet binding applications require high-purity grades with tight microbial thresholds. European formulators source cross-linked variants under EU REACH compliance windows that restrict chemically modified alternatives. Non-GMO and allergen-free specifications command substantial premiums over food-grade material.
- Textile Printing:Sizing applications leverage starch film-forming properties for yarn protection during weaving.
- Paper Production:Surface sizing and coating operations employ mung bean starch for sheet strength and printability.
- Biodegradable Packaging:Thermoplastic processing of high-amylose starch enables barrier coatings without synthetic additives. South Korean and Japanese packaging engineers test fresh produce applications.
Food Processing absorbs the highest tonnage. Pharmaceuticals generate the steepest margin expansion.
End User:
Procurement sophistication diverges between commodity-scale food manufacturers and specification-driven drug producers.
- Food Manufacturers:Asian noodle and vermicelli producers dominate procurement volumes. Indian domestic brands expand manufacturing footprints under PLI scheme subsidies for starch extraction equipment.
- Drug Manufacturers:US and European tablet producers enforce non-GMO, allergen-free binding agent specifications with third-party laboratory verification.
- Textile Mills:Yarn sizing operations source technical-grade starch for weaving efficiency.
- Paper Mills:Coating and surface sizing applications demand consistent viscosity profiles.
- Packaging Firms:Biodegradable film developers test thermoplastic starch formulations for barrier performance.
Food Manufacturers command the largest contract volumes. Drug Manufacturers impose the most stringent qualification protocols.
Packaging Type:
Handling requirements scale with moisture sensitivity and contamination risk across the value chain.
- Bulk Bags:Intermediate bulk containers serve high-volume food processors with integrated silo systems.
- Vacuum-sealed Packs:Pharmaceutical and food-grade shipments employ oxygen-barrier packaging to prevent microbial contamination and oxidative degradation.
- Paper Bags:Multi-wall sacks address standard food-grade distribution with moderate environmental protection.
- Plastic Bags:Polyethylene liners provide moisture barriers for humid climate storage.
- Cardboard Boxes:Retail and sample quantities ship in corrugated containers with inner barriers.
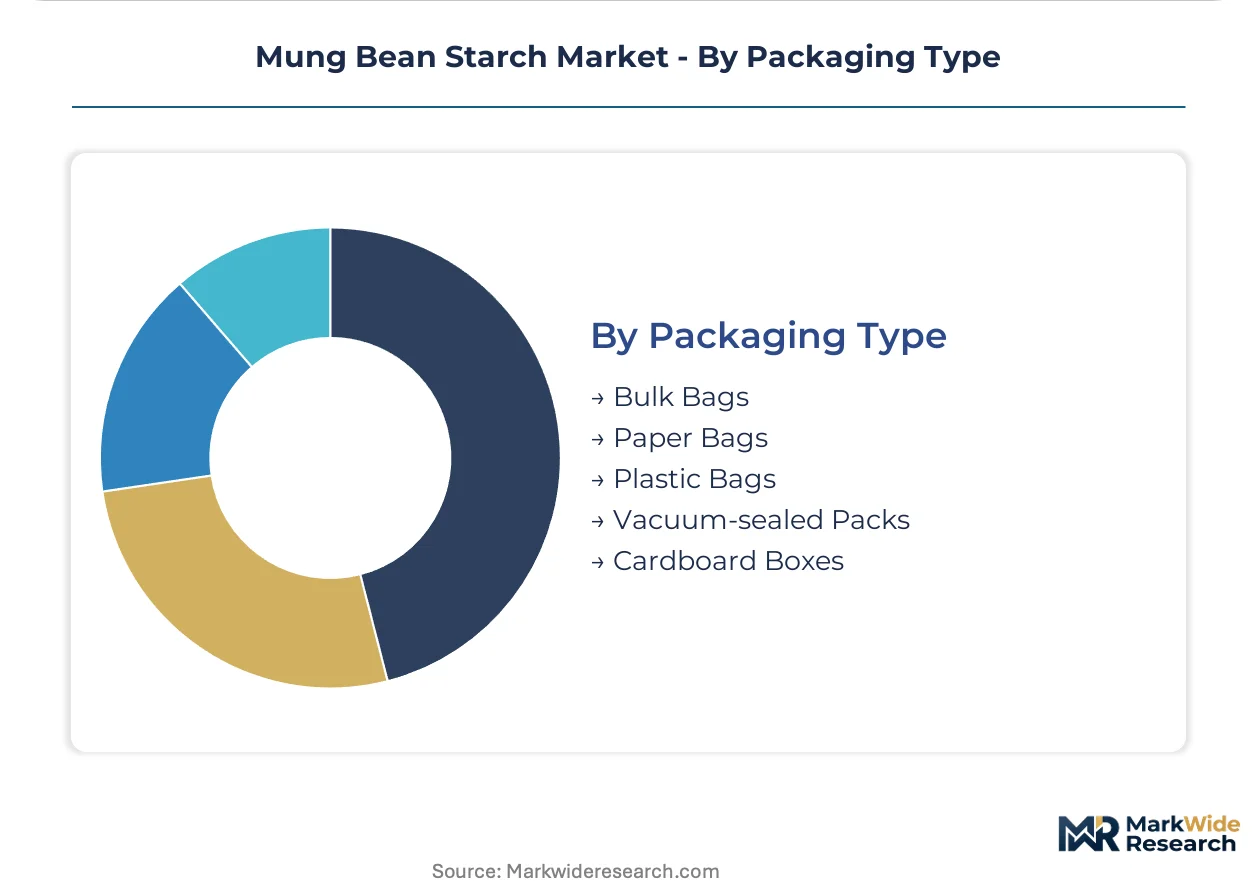
Bulk Bags move the highest tonnage through processor channels. Vacuum-sealed Packs are climbing fastest on pharmaceutical export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors global modified starch capacity, with Jiangsu forming a secondary concentration. China's SAMR enforcement of GB 31637-2023 standards is filtering small-scale processors from supermarket supply chains. India and Vietnam are emerging as concentrated demand centers for noodle and vermicelli production.
China
Vermicelli manufacturers in Shandong and Jiangsu provinces consume the largest modified starch volumes. SAMR tightened lead limits to 0.5 ppm under GB 31637-2023 in early 2024, mandating HACCP documentation for export certification. Shandong processors lacking atomic absorption spectrometry equipment face accelerated consolidation.
India
Domestic vermicelli brands expand manufacturing footprints under PLI scheme subsidies for starch extraction equipment. FSSAI licensing requires 14-18 months for facility audits and heavy metal documentation. Gujarat and Maharashtra house the majority of new capital equipment deployment for enzymatic extraction systems.
Vietnam
Transparent noodle sheet production drives native starch procurement from Thai agricultural cooperatives. Processors retrofit existing rice starch lines with fungal amylase dosing and membrane filtration stages. Ho Chi Minh City-based facilities report payback periods under four years for 10,000-tonne annual retrofits.
Thailand
Long-term grower contracts displace spot-market bean procurement among processors with balance-sheet capacity to prepay planting cycles. Agricultural cooperatives negotiate three-year supply agreements with fixed base prices and non-GMO quality premiums. Bangkok-centered distribution networks serve ASEAN export corridors.
South Korea
Packaging engineers test starch-based barrier coatings for fresh produce applications, leveraging 28% amylose content for thermoplastic processing without synthetic additives. MFDS pharmaceutical-grade specifications attract cross-linked starch imports for tablet binding. Seoul-based R&D clusters coordinate with Japanese biodegradable film developers.
Mung Bean Starch Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical excipient specialization and biodegradable packaging applications. The market exhibits moderate concentration among Asian wet-milling specialists and diversified ingredient conglomerates. Three archetypes dominate: captive bean cultivators with long-term grower contracts, modified starch chemists with cross-linking expertise, and enzymatic extraction technology providers. Capacity expansion and backward integration into captive farming represent the dominant competitive vectors.
Within the diversified conglomerate tier, Ingredion, Cargill, and Tate & Lyle exemplify contrasting geographic and functional positioning. Ingredion leverages long-term grower contracts across Asia to secure non-GMO bean streams. Cargill anchors procurement through direct sourcing partnerships with Thai and Myanmar agricultural cooperatives. Tate & Lyle occupies a specialization position in high-purity modified starch grades for pharmaceutical excipient applications, representing the premium-tier vector where cross-linked variants resist shear degradation.
| Leading Market Players |
|---|
| Sitthinan Company Limited |
| Harbin Hada Starch Co., Ltd. |
| Castle Ingredients |
| Relsus Pte. Ltd. |
| Yantai Oriental Protein Tech Co., Ltd. |
| Ingredion |
| Cargill |
| Archer Daniels Midland Company |
| Tate & Lyle |
| Others |
Pricing and Supply Chain Analysis
Mung bean procurement costs cascade through three distinct pricing tiers as raw material volatility from Myanmar and India's monsoon-dependent harvests compresses margins at the economy grade while pharmaceutical-grade premiums widen. Processors with captive farming contracts in Thailand and Vietnam capture pricing power through non-GMO certification premiums, whereas spot-market dependent operators in Shandong face margin erosion from SAMR compliance investments.
Pricing Analysis
Input-cost pass-through from mung bean spot markets drives pricing volatility across native starch tiers. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade cross-linked variants from food-grade modified starch and commodity native grades. Price differentiation hinges on certification grade and volume scale, with FSSAI-licensed Indian exporters commanding premiums over unverified Shandong processors. Cost compression in the economy tier is intensifying because SAMR-mandated heavy metal testing equipment burdens small-scale operators. Food manufacturers in Vietnam and Thailand exhibit highest price sensitivity, while European drug manufacturers show least sensitivity due to allergen-free binding agent requirements.
Supply Chain Analysis
Regional distribution centers in Bangkok, Ho Chi Minh City, and Mumbai coordinate hub-and-spoke patterns for ASEAN and South Asian delivery corridors. Geographic supply concentration clusters in China, Thailand, and Vietnam, with Shandong and Jiangsu provinces anchoring modified starch capacity. Raw material dependencies draw from Myanmar pulse harvests, Indian central plains cultivation, and Thai cooperative farming networks. Single-source vulnerability from Shandong's dominance in cross-linking reactor capacity exposes export fulfillment to regional flooding or power rationing. Distribution runs through agricultural cooperative contracts with three-year fixed-base pricing agreements displacing spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mung bean starch offers margin-expansion potential as enzymatic extraction retrofits compress processing costs and pharmaceutical-grade premiums widen for cross-linked excipient variants.
For Market Incumbents: Hedge against input volatility by securing long-term grower contracts with Thai and Myanmar agricultural cooperatives before monsoon-driven spot price spikes. Invest in atomic absorption spectrometry equipment to meet SAMR's GB 31637-2023 lead limits and filter smaller competitors from supermarket supply chains. Defensive consolidation through acquiring retiring Chinese state-owned enterprise technicians' cross-linking expertise addresses skill scarcity in modified starch chemistry. For New Entrants and Emerging Players: Direct-to-pharmaceutical channels bypass established food-grade distribution networks and capture premium positioning for non-GMO, allergen-free binding agents. Target underpenetrated African markets in Nigeria and Kenya where instant noodle production lacks local pulse processing infrastructure. Partner with Indian domestic vermicelli brands expanding under PLI scheme subsidies for starch extraction equipment deployment. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale enzymatic extraction specialists because capital-efficient retrofits of existing rice starch lines compress payback periods below four years. Long-term viability over the five-to-ten year window rests on backward integration into captive mung bean farming securing non-GMO certification premiums. Watch for FSSAI licensing timeline compression in India as the inflection indicator for working capital efficiency improvements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Farming | Long-term grower contracts with Thai cooperatives secure non-GMO bean streams and pricing power. |
| Pharmaceutical Excipient Specialization | Cross-linked starch production for European tablet manufacturers commands allergen-free premiums. |
| Enzymatic Extraction Retrofit | Fungal amylase dosing and membrane filtration stages compress payback periods for mid-scale facilities. |
| SAMR Compliance Investment | Atomic absorption spectrometry equipment filters small-scale Shandong processors from supermarket channels. |
| PLI Scheme Alignment | Indian domestic vermicelli brands expand manufacturing footprints with subsidized starch extraction equipment. |
Research Methodology
Coverage spans China, India, Vietnam, Thailand, and South Korea, with primary inputs from each regional cluster combining interviews with wet-milling plant managers, pharmaceutical procurement leads at European tablet manufacturers, Thai agricultural cooperative representatives, and Vietnamese noodle processing executives. Secondary validation draws from SAMR GB standard filings, FSSAI licensing databases, ASEAN customs trade records, and Indian PLI scheme disclosure documents. Bottom-up facility capacity assessments and top-down demand modeling from end-use industries ensure triangulation integrity.
Granularity-level modeling disaggregates volume and value outputs by product type, application, end user, and packaging format across the projection horizon. Segmentation dimensions include native versus modified versus pregelatinized starch grades, food processing versus pharmaceutical versus biodegradable packaging applications, and bulk bag versus vacuum-sealed distribution channels. CAGRs derive from historical capacity deployment patterns and projected PLI scheme uptake in India. Industry-specific forecast inputs incorporate monsoon variability indices for Myanmar and Indian pulse harvests and SAMR enforcement intensity timelines.
Monsoon failure, SAMR regulatory tightening acceleration, and EU REACH compliance cost escalation are the dominant revision risks for forecast trajectories. Forecasts reflect documented assumptions on enzymatic extraction technology adoption rates and pharmaceutical-grade certification timeline compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fucoidan Extract Market
Ingredients
Yeast Flakes Market
Ingredients
Calendula Oil Market
Ingredients
Egg Albumin Protein Market
Ingredients
High Oleic Oil Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Pork Skin Gelatin Market
Ingredients
Global Egg White Peptide Market
Ingredients
India Protein Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Casein Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Mung Bean Protein Market
Ingredients
Microbial Food Ingredients Market
Ingredients
Rose Hips Extract Market
Ingredients
Corn Oil Cake Market