
 Man-Made Sausage Casing Market | 2026-2036
Man-Made Sausage Casing Market Size, Share, and Industry Trends Forecast 2026-2036
Man-Made Sausage Casing Market Analysis
REACH compliance is shifting the cost-of-entry calculus for European casing suppliers. Viscofan Group leverages its integrated collagen supply chain to sustain margin stability under evolving chemical disclosure rules. Kalle GmbH anchors its competitive position through specialized fiber casing technology that dominates industrial meat processing lines in Central Europe.
Man-made sausage casings are engineered tubular structures manufactured from cellulose, collagen, plastic polymers, or fiber blends, designed to contain ground meat or plant-based fillings during cooking, smoking, or storage processes. These casings typically measure 15-50mm in diameter and operate across temperature ranges from refrigerated storage through thermal processing up to 120°C. Collagen casings lead volume share due to their edible properties and cost efficiency in high-speed industrial stuffing operations, while cellulose variants command premium positioning in smoked and dried sausage applications where peelability determines processing throughput. Plastic casings occupy a mature niche in large-diameter processed meats where moisture barrier performance outweighs sustainability concerns.
EMA food contact material guidelines, FDA food additive regulations, and China's GB standards collectively shape product formulation limits, migration testing protocols, and market access requirements across the three largest production geographies. BIS certification requirements in India and FSSAI packaging norms further fragment compliance obligations for multinational casing suppliers. Stakeholders must monitor accelerating regulatory divergence between biodegradable material mandates in Europe and performance-driven standards in Asia-Pacific to align R&D allocation with emerging certification requirements.
Market Dynamics
EU Green Deal packaging disclosure mandates are compressing procurement timelines for European meat processors while China's Shandong province consolidates supply-side concentration through integrated collagen extraction-to-casing production corridors.
Growth Catalysts
- REACH chemical disclosure expansion:ECHA's evolving substance restrictions force casing reformulation toward bio-derived inputs, opening procurement contracts for compliant collagen suppliers.
- Industrial meat processing automation:High-speed stuffing line adoption in Germany and Poland demands edible casings with calibrated diameter consistency above manual alternatives.
- Cellulose casing peelability performance:Smoked sausage processors in Central Europe prioritize cellulose variants that reduce labor hours in post-cooking removal operations.
Market Restraints
- Collagen raw material concentration:Bovine and porcine hide supply chains cluster in specific tanning regions, exposing processors to livestock disease quarantine disruptions.
- Plastic casing sustainability liability:Polyamide and PVDC variants face mounting Extended Producer Responsibility fees under EU packaging waste directives.
- Cross-border certification fragmentation:India's BIS food contact material testing diverges from FDA migration protocols, forcing dual compliance investments for export-oriented suppliers.
Strategic Opportunities
- Plant-based sausage expansion:Alternative protein processors require neutral-flavor casings that mask off-tastes from pea or soy isolates, creating formulation partnerships.
- Small-diameter collagen innovation:Snack stick and breakfast link segments remain underserved by current 20mm+ diameter production lines.
- China's dual carbon policy alignment:SAMR green manufacturing incentives reward casing producers adopting enzymatic processing over chemical-intensive extraction.
Industry Challenges
- Food safety certification velocity:FSSAI, FDA, and EFSA simultaneous audit demands strain quality assurance staffing at mid-cap casing manufacturers.
- Legacy equipment compatibility:Existing stuffing and clipping machinery requires casing diameter tolerances that conflict with next-generation biodegradable material stretch properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Man-Made Sausage Casing Market |
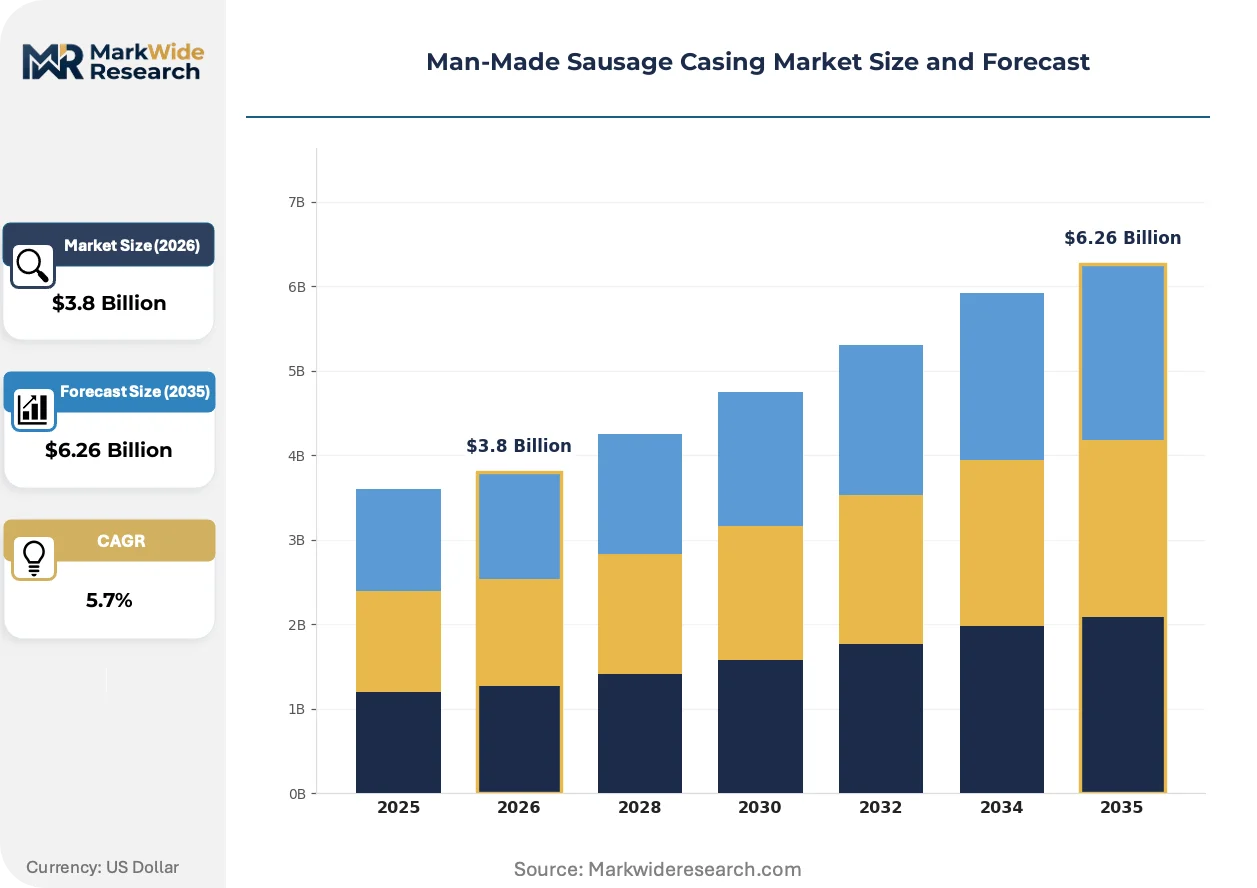
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Collagen, Plastic, Fiber Application: Meat Processing, Vegetarian Products, Convenience Foods, Snacks End User: Food Manufacturers, Retailers, Food Service, Butchers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Others |
| Companies Covered | Viscofan Group, Viskase Companies Inc., Kalle GmbH, ViskoTeepak, Devro plc, Nitta Casings Inc., Shenguan Holdings (Group) Limited, FABIOS S.A, Columbit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Man-Made Sausage Casing Market Emerging Trajectories
Active material science breakthroughs and regulatory disclosure mandates are compressing product development cycles while reshaping procurement specifications across meat processing tiers.
Edible film technology is integrating alginate-pectin composite layers into collagen casing substrates to enhance moisture retention during thermal processing. Premium sausage manufacturers in Northern Italy and Bavaria are piloting these formulations for extended shelf-life positioning. The structural consequence is that casing suppliers with in-house biopolymer R&D capabilities are capturing specification-setting authority previously held by meat processors.
REACH Annex XVII restrictions on microplastics are forcing casing producers to eliminate synthetic polymer additives from fiber casing binders. Industrial consequence includes accelerated R&D allocation toward lignocellulose reinforcement alternatives. Central European processors operating under EU Green Deal timelines are most affected, with several converting cellulose lines ahead of formal enforcement dates.
Direct procurement relationships between meat processors and collagen extraction facilities are displacing traditional distributor-mediated supply chains. Large-scale processors in Germany's Lower Saxony and China's Shandong are establishing volume-commitment contracts that bypass regional casing converters. This pattern concentrates margin capture at the extraction-to-casing integration tier while compressing distributor roles to logistics-only functions.
Man-Made Sausage Casing Market Segmentation
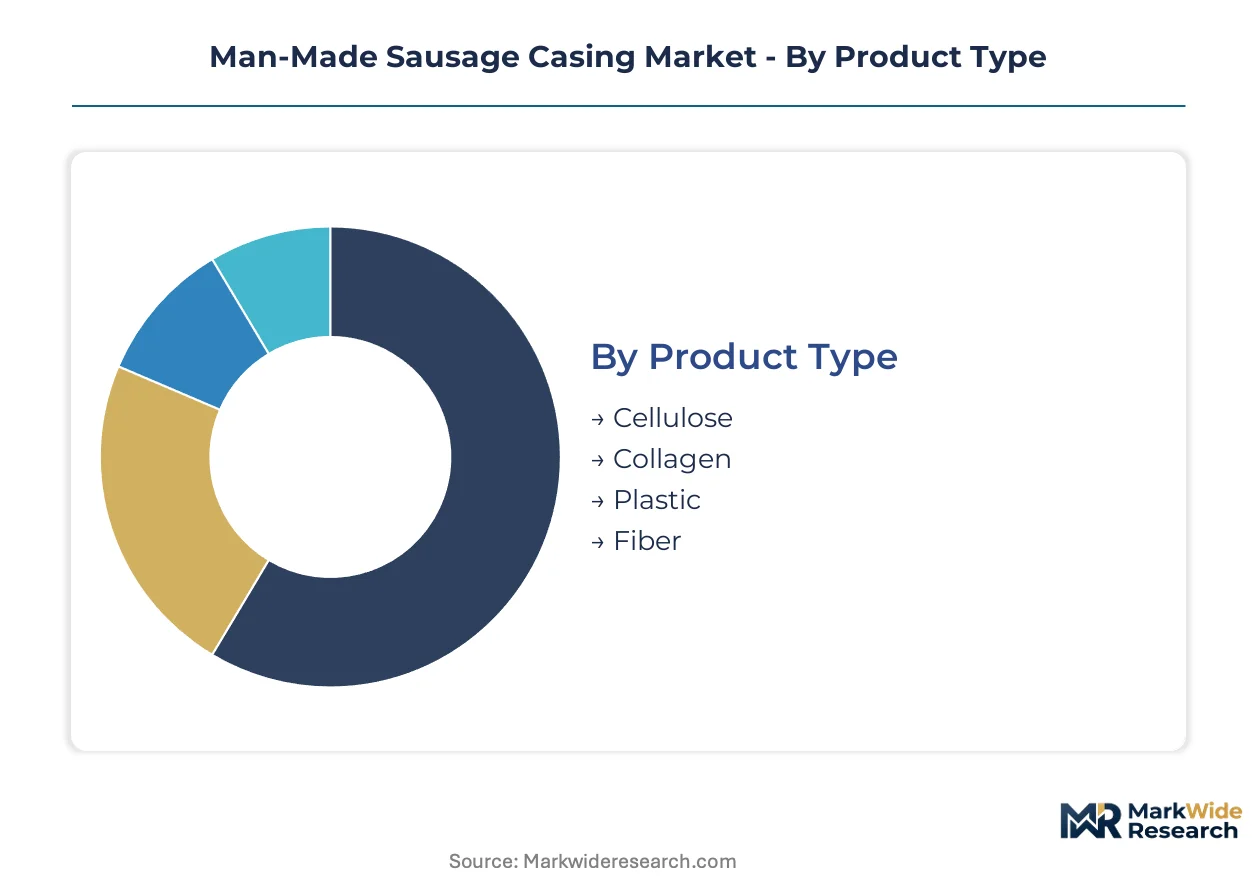
Segmentation in man-made sausage casings determines procurement specifications, regulatory compliance pathways, and equipment compatibility requirements. Product type selection dictates thermal processing limits and edible versus peelable end-use applications. Distribution channel and end-user configurations shape margin capture and volume throughput across industrial versus artisanal processing tiers.
Product Type:
Volume concentration favors edible variants for high-speed industrial stuffing, while premium positioning attaches to specialized barrier and peelability performance.
- Collagen:Manufactured from bovine or porcine hide extrusion, these edible casings offer calibrated diameter consistency for automated clipping lines. Demand concentrates in Germany's Lower Saxony meat processing corridor, where EU Green Deal packaging mandates accelerate procurement of bio-derived, compliant inputs.
- Cellulose:Derived from wood pulp regeneration, these non-edible casings deliver superior peelability post-smoking. Smoked sausage processors in Central Europe prioritize these variants to reduce labor hours in removal operations and maintain throughput on industrial lines.
- Plastic:Polyamide and PVDC constructions provide moisture barrier performance for large-diameter processed meats. EU Extended Producer Responsibility fees now compress margins for these variants.
- Fiber:Reinforced cellulose or synthetic fiber blends serve specialty applications requiring enhanced tensile strength. REACH Annex XVII microplastic restrictions are forcing lignocellulose reinforcement R&D.
Mature deployment sits with Collagen. Newer deployment is concentrated in Fiber as regulatory pressure accelerates bio-derived binder development.
Application:
Industrial meat processing anchors volume demand, while alternative protein and convenience formats represent reformulation partnership opportunities.
- Meat Processing:Traditional pork, beef, and poultry sausage manufacturing consumes the majority of collagen and cellulose volumes. Germany and Poland drive automation adoption requiring diameter-tolerance precision.
- Vegetarian Products:Pea and soy isolate-based sausages require neutral-flavor casings masking off-tastes. Formulation partnerships between casing suppliers and alternative protein processors are expanding most quickly in this segment.
- Convenience Foods:Pre-cooked and ready-to-eat sausage applications demand extended shelf-life barrier properties. Alginate-pectin composite layers are piloting in Northern Italy and Bavaria.
- Snacks:Small-diameter snack sticks and breakfast links remain underserved by standard 20mm+ production lines, creating innovation white space.
Scale concentration remains with Meat Processing. Specification-setting authority is shifting toward Vegetarian Products as alternative protein processors demand customized barrier performance.
End User:
Direct procurement relationships are displacing distributor-mediated supply chains at the largest volume tiers.
- Food Manufacturers:Industrial-scale processors establish volume-commitment contracts bypassing regional converters. China's Shandong province and Germany's Lower Saxony anchor this procurement pattern.
- Retailers:Private-label sausage programs require casing suppliers meeting multiple jurisdiction certification simultaneously. FSSAI, FDA, and EFSA audit demands strain quality assurance staffing.
- Food Service:Restaurant and institutional catering channels prioritize cost efficiency over premium barrier performance. Standard collagen variants dominate.
- Butchers:Artisanal processors favor natural casings but adopt man-made alternatives for diameter consistency. Specialty stores and direct distribution serve this fragmented tier.
Margin capture concentrates with Food Manufacturers. Relationship intensity is climbing fastest with Retailers as private-label programs expand.
Distribution Channel:
Channel selection determines certification documentation requirements and order fulfillment velocity.
- Online Retail:Direct-to-processor platforms serving small-batch manufacturers and specialty sausage startups. Documentation transparency requirements align with EU packaging disclosure mandates.
- Supermarkets:Consolidated procurement for retail-branded sausage programs. Volume scale supports dedicated inventory positions and just-in-time delivery.
- Specialty Stores:Equipment and casing bundles for artisanal butchers and regional processors. Technical consultation services differentiate this channel.
- Others:Distributor-mediated logistics for fragmented geographic markets. Role compression to pure logistics functions as direct procurement expands.
Volume throughput anchors with Supermarkets. Channel development investment is concentrating in Online Retail as small-processor digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Lower Saxony meat processing corridor concentrates collagen casing procurement as EU Green Deal mandates accelerate bio-derived input adoption. China's Shandong province anchors supply-side integration through collagen extraction-to-casing production corridors. The United States maintains automation-driven demand for diameter-consistent edible casings.
Germany
Industrial meat processors in Lower Saxony and Bavaria drive automated stuffing line adoption requiring calibrated collagen casings. REACH Annex XVII chemical disclosure rules compel reformulation toward bio-derived binders. Kalle GmbH anchors fiber casing production in Hesse, supplying Central European smoked sausage processors.
China
Shandong province's integrated tanning-to-casing facilities supply both domestic meat processors and export channels. SAMR green manufacturing incentives reward enzymatic collagen extraction over chemical-intensive methods. Qingdao and Weihai cluster domestic casing producers serving European and Japanese export specifications.
United States
Large-scale meatpackers in the Midwest and Southeast prioritize high-speed edible casing procurement for automated clipping lines. FDA food additive regulations govern migration testing protocols for collagen and cellulose variants. Chicago and Omaha anchor distributor-mediated supply chains now compressing under direct procurement pressure.
Poland
Meat processing automation in the Greater Poland and Silesia regions drives demand for diameter-tolerant collagen casings. EU packaging waste directives impose Extended Producer Responsibility fees on plastic casing imports. Poznan-based processors convert cellulose lines ahead of formal microplastic restriction enforcement dates.
India
Domestic sausage manufacturing expansion in Maharashtra and Gujarat strains casing supply chains. FSSAI food contact material testing diverges from FDA protocols, forcing dual compliance investments for export-oriented suppliers. Mumbai and Ahmedabad host emerging distributor networks serving fragmented regional meat processors.
Man-Made Sausage Casing Market Vendor Landscape
German producers anchor the premium technology tier; Chinese specialists hold volume-scale positions through integrated supply chains. The vendor base stratifies across three tiers: multinational integrated collagen suppliers, regional fiber casing specialists, and emerging plant-based formulation developers. Consolidation pressure concentrates at the extraction-to-casing integration tier. Capacity expansion and backward integration into raw material supply represent the dominant competitive vectors.
Among Spain-based multinationals, Viscofan Group occupies a position exemplifying integrated collagen supply chain control. German GmbH-structured specialists Kalle GmbH represent the fiber casing technology archetype. Within Chinese-listed producers, Shenguan Holdings (Group) Limited anchors the domestic supply-side concentration narrative.
| Leading Market Players |
|---|
| Viscofan Group |
| Viskase Companies Inc. |
| Kalle GmbH |
| ViskoTeepak |
| Devro plc |
| Nitta Casings Inc. |
| Shenguan Holdings (Group) Limited |
| FABIOS S.A |
| Columbit Group |
| Others |
Supply Flow & Price Mechanics
Backward integration into collagen extraction-to-casing production corridors anchors supply position and pricing power for dominant processors in China's Shandong province and Germany's Lower Saxony. REACH chemical disclosure mandates and EU Green Deal packaging rules compress margins for non-integrated distributors while rewarding volume-commitment contracts that bypass regional converters.
Pricing Analysis
Volume-scale collagen contracts trade at thin margins calibrated to automated clipping line throughput, while premium cellulose variants for smoked sausage applications capture wider spreads based on peelability performance and labor-hour savings. Three-tier pricing structure across premium alginate-pectin composites, standard edible collagen, and economy fiber blends reflects certification grade and diameter tolerance precision. Pricing pressure stems from Extended Producer Responsibility fees compressing plastic casing margins under EU packaging waste directives. Small-batch artisanal butchers exhibit highest price sensitivity, whereas industrial meat processors in Germany and Poland prioritize diameter consistency over unit cost.
Supply Chain Analysis
Freight cost exposure concentrates procurement gravity near collagen extraction facilities in Shandong province, Lower Saxony, and the American Midwest. Raw material supply draws from bovine and porcine hide tanning clusters in specific livestock regions, cellulose pulp regeneration mills, and polyamide resin production. Single-source vulnerability from livestock disease quarantine disruptions in concentrated tanning geographies threatens input continuity. Distribution runs through direct volume-commitment contracts displacing traditional distributor-mediated logistics, with regional converters compressing to pure fulfillment functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where REACH Annex XVII microplastic restrictions and dual compliance investments for FSSAI-FDA divergence force weaker regional converters into exit or acquisition.
For Market Incumbents: Hedge against synthetic polymer liability by accelerating lignocellulose reinforcement R&D ahead of formal enforcement dates. Secure captive collagen extraction capacity in Shandong or Lower Saxony to defend margin position against direct-procurement displacement. Threat of enzymatic processing competitors capturing SAMR green manufacturing incentives demands pre-emptive certification investment. For New Entrants and Emerging Players: Small-diameter snack stick processors remain underserved by incumbent 20mm+ production lines, creating specification-setting opportunity. Alternative protein sausage manufacturers require neutral-flavor casing partnerships masking pea and soy isolate off-tastes, a penetrable segment with formulation collaboration as entry angle. Plant-based barrier performance customization offers faster qualification path than competing for industrial meat processor volume contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational integrated collagen suppliers seeking Shandong extraction assets. Long-term viability favors extraction-to-casing integration tier over distributor-only logistics functions. Signal to monitor is FSSAI audit queue velocity indicating quality assurance staffing strain at mid-cap targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collagen Extraction | Captures margin at tanning-to-casing tier while securing REACH-compliant bio-derived input supply. |
| Enzymatic Processing Technology Adoption | Aligns with SAMR green manufacturing incentives and reduces chemical disclosure liability under ECHA rules. |
| Small-Diameter Production Line Investment | Addresses underserved snack stick segment where current 20mm+ capacity creates specification gap. |
| Dual Certification Compliance Infrastructure | Enables simultaneous FSSAI and FDA qualification for export-oriented suppliers targeting fragmented markets. |
| Alginate-Pectin Composite R&D Partnership | Positions premium shelf-life extension for convenience food processors in Northern Italy and Bavaria. |
Methodological Framework
Trade association filings, customs records, and ECHA substance restriction databases formed the secondary backbone, supplemented by primary interviews with casing plant managers, meat processor procurement leads, tanning facility technical directors, and distribution channel partners. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity disclosures and regional meat processing automation adoption rates.
Historical trendline analysis of collagen extraction throughput, cellulose regeneration capacity, and industrial stuffing line installation patterns informed projection assumptions across the analysis window. Segmentation dimensions modeled include product type, application category, end-user scale tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH enforcement timelines and SAMR incentive program uptake.
Revisions become necessary when livestock disease quarantine events disrupt concentrated tanning supply zones, when FSSAI-FDA protocol divergence accelerates beyond dual compliance capacity, or when enzymatic processing cost curves cross chemical extraction economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Peanut Butter Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Canned Food Market
Packaged Foods
Hummus Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Pasta and Noodles Market