
 Bleached Flour Market | 2026-2036
Bleached Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Bleached Flour Market Analytics
North American milling capacity is hardening as Ardent Mills leverages its integrated grain elevator network across the Great Plains. General Mills sustains brand strength through specialty flour formulations for industrial bakeries. Archer Daniels Midland Company anchors its position with bulk supply contracts to food processing plants.
Bleached flour is wheat flour treated with oxidizing agents such as benzoyl peroxide or chlorine gas to whiten the endosperm and modify gluten strength for predictable baking performance. The process lowers pH and improves starch gelatinization, making it essential for cakes, pastries, and chemically leavened goods. All-purpose flour dominates volume shipments due to its versatility across bakeries and home cooking segments, while cake flour commands premium positioning in specialty retail channels. Bulk packaging leads industrial procurement for food processing applications, though retail packs are gaining traction through online retailers serving home bakers.
The FDA governs bleaching agent tolerances and labeling under 21 CFR 137, while the EPA monitors effluent discharge from milling operations. In Europe, EFSA and REACH restrict certain chlorine-based treatments and mandate full additive traceability. Stakeholders must monitor evolving chemical thresholds across multiple jurisdictions to sustain market access and avoid reformulation costs.
Market Dynamics
Commercial bakeries across Southeast Asia are consolidating procurement around bleached flour specifications that guarantee consistent dough performance, while EU regulatory tightening on additive disclosure forces simultaneous supply chain restructuring for export-oriented millers.
Growth Catalysts
- REACH additive traceability mandates:European millers investing in certified bleaching processes gain preferential access to food processing contracts requiring full chemical lineage documentation.
- Indonesian milling capacity expansion:New integrated facilities in Java and Sumatra reduce import dependency and lower landed costs for domestic commercial bakeries.
- Enzymatic bleaching alternatives:Oxidase-based treatments bypass chlorine restrictions while delivering equivalent gluten modification for cake flour production.
Market Restraints
- Wheat price volatility:Input cost swings tied to Black Sea supply disruptions compress margins for millers lacking forward-contract coverage.
- EU F-Gas Regulation phase-down:Chlorine gas handling restrictions raise capital requirements for European facilities still dependent on traditional bleaching chemistry.
- Clean-label substitution:Unbleached flour with natural whitening agents captures shelf space in premium retail channels targeting ingredient-conscious consumers.
Strategic Opportunities
- Vietnamese industrial bakery growth:Foreign direct investment into frozen dough production creates demand for high-volume, specification-consistent flour supply.
- Online retail channel expansion:Direct-to-home baker platforms in Indonesia bypass traditional distributor markups and build brand recognition among amateur bakers.
- EFSA novel food approval pathways:Early entrants securing positive opinions for enzymatic bleaching agents establish regulatory moats against later competitors.
Industry Challenges
- Certified food safety auditor scarcity:Mills expanding into EU export markets face 12-18 month queues for BRCGS or IFS certification audits.
- Legacy equipment retrofit costs:Converting chlorine-based bleaching lines to benzoyl peroxide or enzymatic systems requires substantial capital outlay with multi-year payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bleached Flour Market |
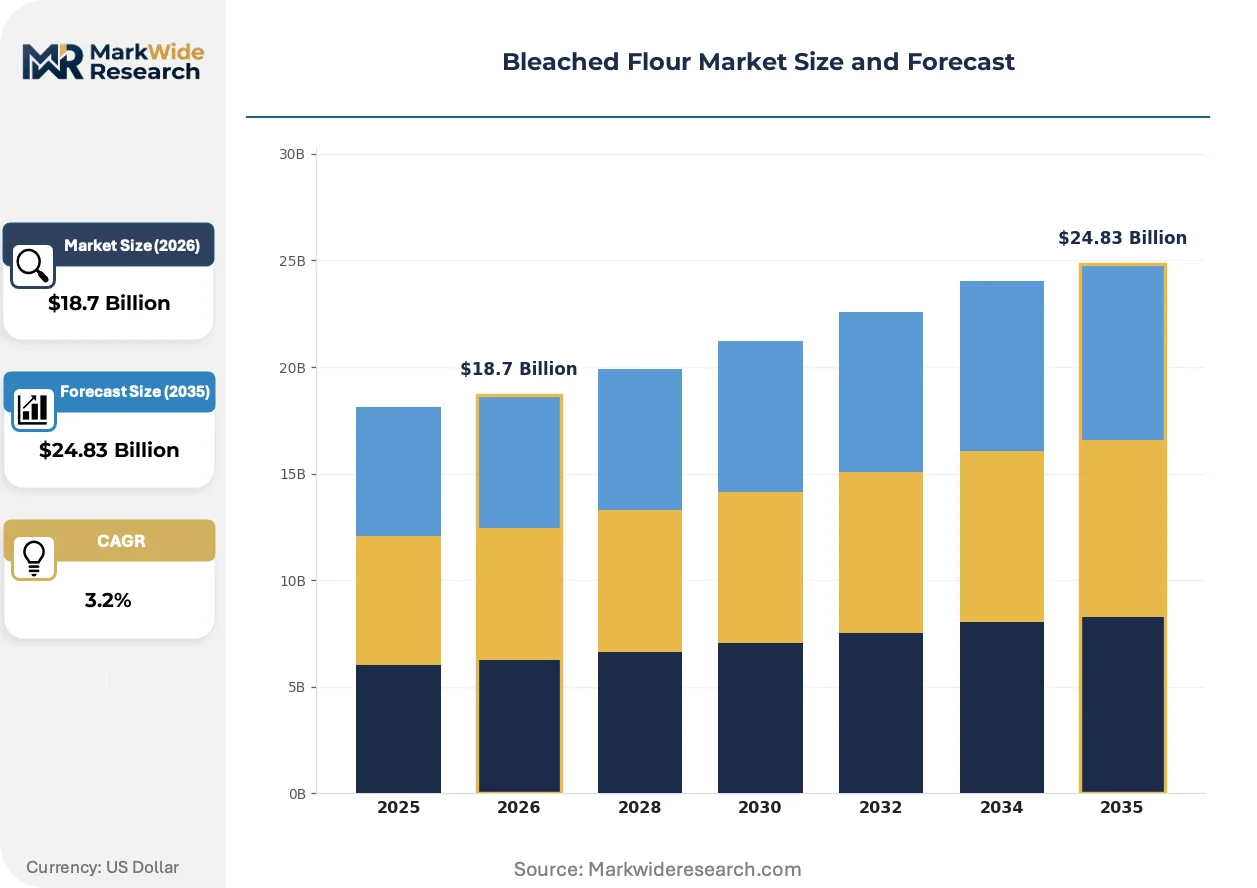
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $24.83 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Flour, Cake Flour, Bread Flour, Pastry Flour End User: Bakeries, Restaurants, Home Cooking, Food Processing Packaging Type: Bags, Boxes, Bulk Packaging, Retail Packs Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale Distributors |
| Companies Covered | Ardent Mills, General Mills, Archer Daniels Midland Company, Manildra Group, Allied Pinnacle, Nisshin Flour Milling, Interflour Group, Goodmills Group, King Arthur Baking Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bleached Flour Market Evolving Landscape
Active reformulation across bleaching chemistry and packaging formats is compressing traditional competitive advantages while opening entry points for specialized regional suppliers.
Enzymatic bleaching systems using glucose oxidase and lipoxygenase are expanding into industrial cake and pastry production. Mid-sized Vietnamese bakeries have adopted these platforms at accelerating rates since 2023. The technology is expanding into markets where chlorine restrictions already apply, enabling regional millers to serve export contracts without dual-process facilities.
EFSA and REACH are tightening disclosure thresholds for benzoyl peroxide residuals and mandating quantitative labeling of all oxidizing agents. European food processors now require millers to submit complete additive dossiers as a condition of contract renewal. Cake flour formulations targeting specialty retail face the steepest compliance burden, driving consolidation toward integrated milling operations with in-house analytical capabilities.
Home baking ingredient procurement is fragmenting across direct-to-consumer platforms and specialty food retailers. Traditional grocery distribution in Indonesia and Vietnam is losing volume share to e-commerce aggregators offering recipe-bundled flour SKUs. This channel rotation is most pronounced in Jakarta and Ho Chi Minh City, where delivery infrastructure supports just-in-time inventory for small commercial kitchens.
Bleached Flour Market Segmentation
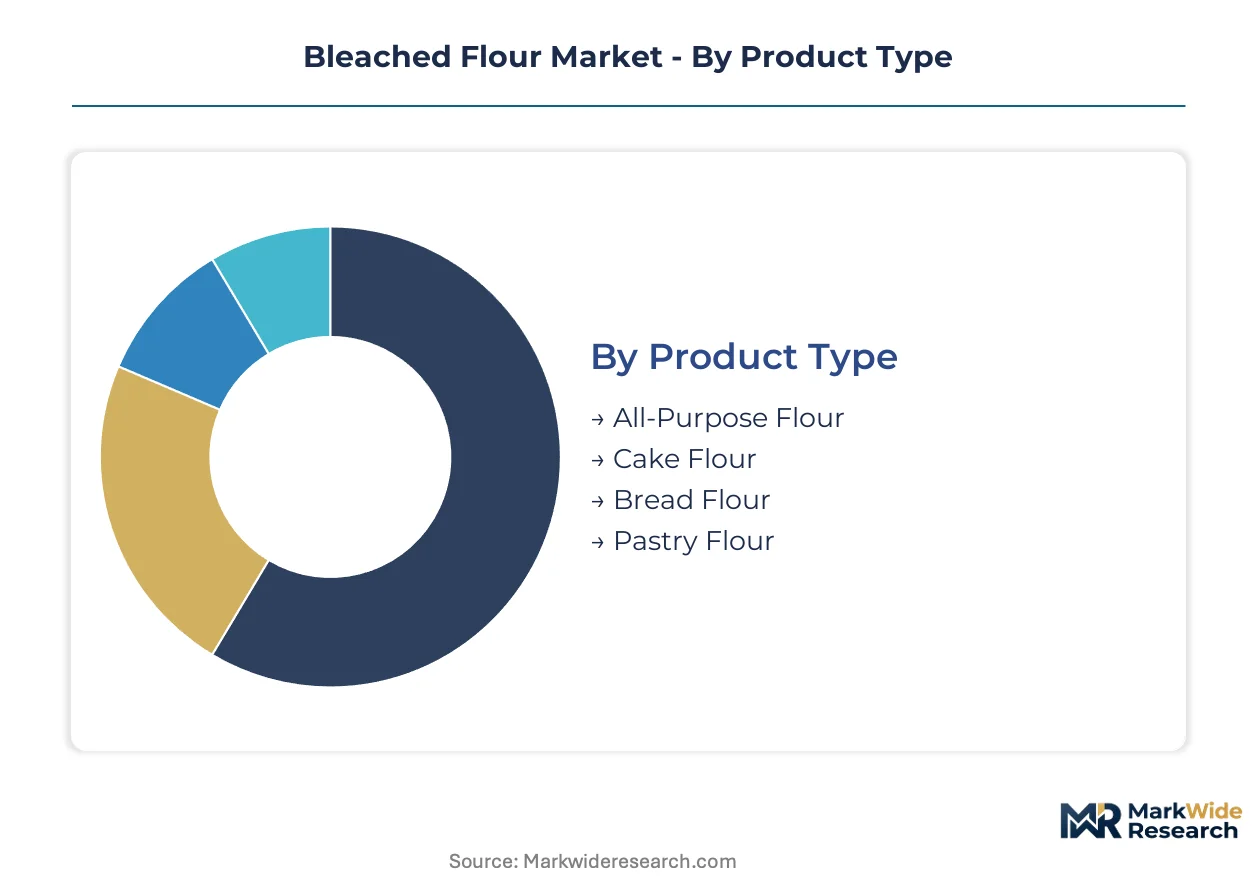
Bleached flour specifications diverge sharply across end-use applications, with industrial bakeries demanding tight tolerances for protein content and ash levels while home cooks prioritize convenience and recipe consistency. Understanding these segment boundaries enables millers to align capital deployment with the highest-margin procurement channels.
Product Type:
Standardization dominates at the commodity tier while premium segments reward customized protein specifications and specialized treatment protocols.
- All-Purpose Flour:Versatile mid-protein formulation (10-12%) treated with benzoyl peroxide for consistent whitening across ambient storage conditions. Commercial bakeries in Indonesia and Vietnam specify this grade for multi-product lines where dough rheology must remain predictable across temperature fluctuations. Procurement concentrates around bulk contracts with integrated mills possessing in-house elevator networks.
- Cake Flour:Low-protein, chlorinated or enzymatically bleached flour with pH reduced to 5.0-5.5 for enhanced starch gelatinization and fine crumb structure. Specialty retail channels in Ho Chi Minh City and Jakarta drive premium positioning, with EFSA additive traceability mandates forcing reformulation toward oxidase-based alternatives.
- Bread Flour:Higher protein content (12-14%) with minimal bleaching to preserve gluten strength for yeast-leavened applications.
- Pastry Flour:Intermediate protein specification (8-10%) balancing tenderness with structural integrity for laminated doughs.
Most installed capacity flows through All-Purpose Flour. Expansion is steepest in Cake Flour as enzymatic bleaching platforms bypass regulatory restrictions.
End User:
Volume scale inversely correlates with specification stringency, with food processors demanding certified safety documentation that smaller channels cannot support.
- Bakeries:Industrial and artisanal operations requiring consistent batch performance for scaled production. Southeast Asian commercial bakeries consolidate procurement around bleached flour with guaranteed dough extensibility metrics, particularly for frozen dough export operations serving convenience retail chains.
- Food Processing:Manufacturers of packaged cakes, cookies, and bread mixes demanding additive dossiers for EU export compliance. BRCGS and IFS certification requirements create supplier consolidation as uncertified mills lose contract eligibility.
- Restaurants:Foodservice operations prioritizing cost efficiency over specification granularity for breading and thickening applications.
- Home Cooking:Amateur bakers purchasing through e-commerce aggregators and specialty retailers, with recipe-bundled SKUs gaining traction in Indonesian urban markets.
Food Processing commands the tightest margin compression from certification costs. Home Cooking exhibits the steepest channel shift toward direct-to-consumer platforms.
Packaging Type:
Unit economics favor bulk formats for industrial accounts while retail convenience drives premium pricing for smaller pack sizes.
- Bulk Packaging:Tanker trucks and flexible intermediate bulk containers serving food processing plants and large commercial bakeries. Indonesian integrated mills leverage this format to displace import dependency through domestic supply chain shortening.
- Retail Packs:1-5 kg paper or plastic bags targeting home bakers through online channels and specialty food retailers. Vietnamese e-commerce platforms bundle these with recipe cards and measuring tools, bypassing traditional distributor markups.
- Bags:Standard 25-50 kg woven polypropylene sacks for mid-sized bakeries and foodservice distributors.
- Boxes:Corrugated retail packaging for premium cake flour positioning in specialty channels.
Bulk Packaging carries the heaviest capital requirements for logistics infrastructure. Retail Packs are expanding most quickly as urban delivery networks mature.
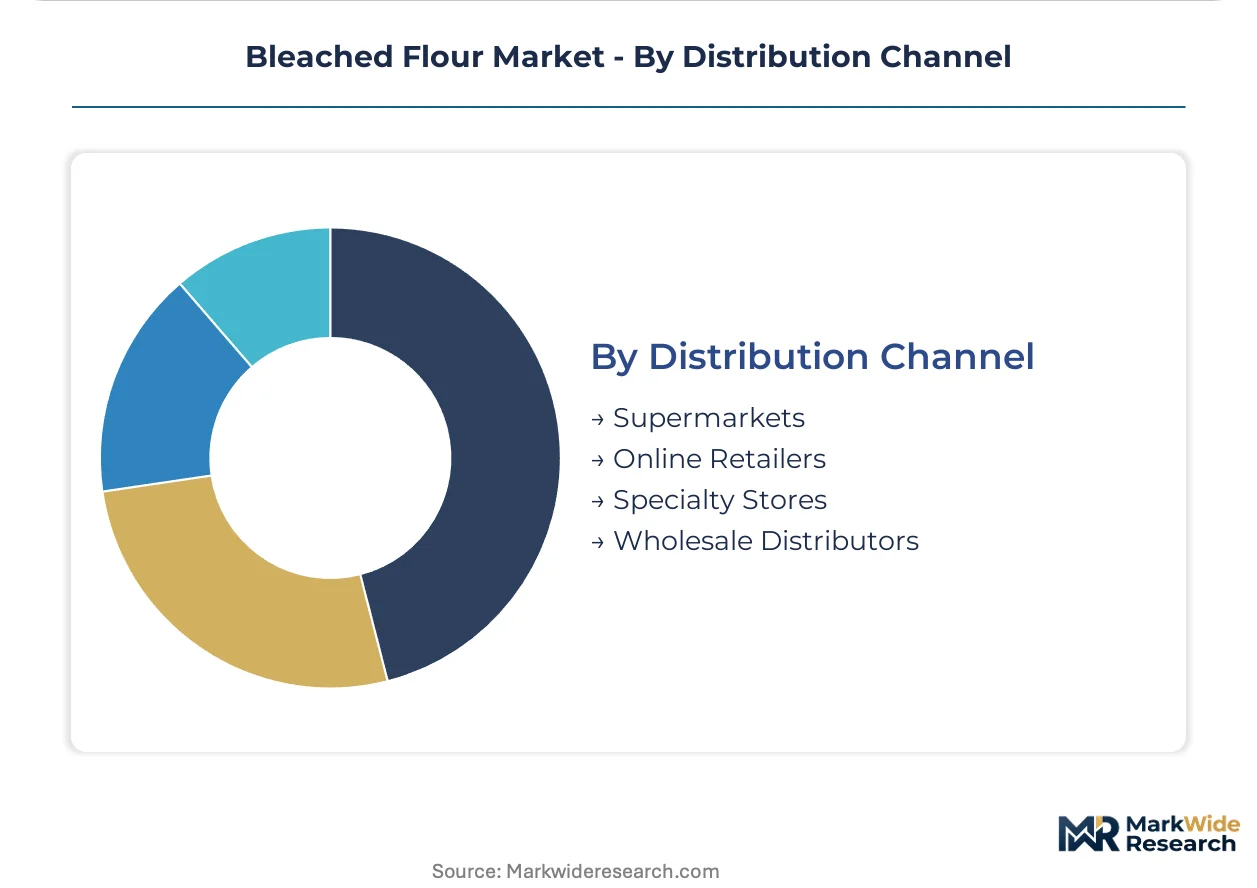
Distribution Channel:
Channel control determines margin capture, with vertically integrated mills bypassing wholesale layers to serve end-users directly.
- Online Retailers:E-commerce platforms and direct-to-home baker services in Jakarta and Ho Chi Minh City offering just-in-time inventory for small commercial kitchens. Indonesian aggregators bundle bleached flour with complementary ingredients, building brand recognition among amateur bakers.
- Wholesale Distributors:Traditional intermediaries serving regional bakeries and restaurants, losing volume share to miller-direct contracts and platform disintermediation.
- Supermarkets:Mass retail chains stocking standard all-purpose and cake flour SKUs for household consumers.
- Specialty Stores:Gourmet food retailers targeting premium cake flour segments with imported or artisan-positioned products.
Wholesale Distributors retain the largest legacy volume base. Online Retailers show the fastest share gain as urban logistics infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping bleached flour production geography. Millers in jurisdictions with permissive additive frameworks capture contract volume from EU-facing exporters burdened by REACH traceability mandates and F-Gas chlorine restrictions.
United States
Commercial bakeries in the Midwest and Southeast sustain steady procurement of benzoyl peroxide-treated all-purpose flour. The FDA governs bleaching agent tolerances under 21 CFR 137, maintaining predictable compliance costs. Integrated milling operations across Kansas and Minnesota leverage captive grain elevator networks to serve industrial food processors with bulk supply contracts.
Indonesia
New milling capacity in Java and Sumatra is displacing import dependency for domestic commercial bakeries. The national food and drug regulator enforces additive labeling standards aligned with ASEAN harmonization protocols. Jakarta's industrial bakery cluster is consolidating procurement around specification-consistent bleached flour for frozen dough export operations.
Vietnam
Foreign direct investment into frozen dough production in Ho Chi Minh City is accelerating demand for high-volume flour supply with guaranteed dough extensibility metrics. The Ministry of Health oversees food additive approvals, with enzymatic bleaching platforms gaining traction among mid-sized bakeries seeking export compliance flexibility.
Germany
EFSA and REACH restrictions on chlorine-based treatments are forcing reformulation toward benzoyl peroxide and enzymatic alternatives. The ECHA mandates full additive traceability documentation, raising capital requirements for facilities dependent on legacy bleaching chemistry. North Rhine-Westphalia's food processing corridor is consolidating supplier relationships around certified mills with in-house analytical capabilities.
Japan
Specialty cake flour demand in Tokyo and Osaka metropolitan areas supports premium positioning for low-protein, finely milled products. The Ministry of Health, Labour and Welfare regulates food additive specifications through positive list systems. Kanto region industrial bakeries are evaluating oxidase-based bleaching platforms to serve export contracts into chlorine-restricted markets.
Bleached Flour Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue enzymatic alternative certification and direct-to-consumer channel access. The vendor base stratifies across integrated multinational millers with captive grain supply, regional specialists serving single-country industrial clusters, and niche operators targeting specialty retail segments. Three archetypes dominate: scale-driven bulk suppliers, regulatory-compliance specialists, and premium-brand direct marketers. Competitive intensity concentrates on backward integration into elevator networks and certification audit queue positioning.
Among North American integrated millers, Ardent Mills and General Mills exemplify scale-driven supply archetypes with extensive grain origination infrastructure. Archer Daniels Midland Company anchors the commodity-processing tier with bulk contract relationships to industrial food plants. These entities represent the established competitive framework against which regional specialists in Southeast Asia and enzymatic technology entrants are positioning alternative value propositions.
| Leading Market Players |
|---|
| Ardent Mills |
| General Mills |
| Archer Daniels Midland Company |
| Manildra Group |
| Allied Pinnacle |
| Nisshin Flour Milling |
| Interflour Group |
| Goodmills Group |
| King Arthur Baking Company |
| Others |
Value Network & Pricing Analysis
Chicago wheat futures and Black Sea export quotations cascade through bleached flour supply chains, compressing margins at integrated mills while amplifying price volatility for distributors lacking forward-contract coverage. The interaction between commodity input swings and channel markup structures forces procurement officers to rebalance spot purchases against long-term offtake agreements.
Pricing Analysis
Distributor margin layers absorb the steepest compression when wheat basis spreads widen, forcing a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade and volume scale, with BRCGS-certified mills commanding premiums from EU-facing food processors. Pricing pressure stems from enzymatic bleaching platform adoption, which lowers capital barriers for mid-tier entrants. Industrial bakeries exhibit highest price sensitivity due to contract renegotiation cycles, while specialty retail channels show lowest sensitivity amid recipe-bundled SKU positioning.
Supply Chain Analysis
Indonesian domestic-content mandates for milling capacity expansion are reshaping sourcing patterns across Southeast Asian procurement networks. Supply concentrates in Indonesia, Vietnam, and the United States, with wheat imports drawing from Australia, Canada, and Black Sea origins. Raw material dependencies center on hard red winter wheat, benzoyl peroxide feedstock, and oxidase enzyme preparations. Single-source vulnerability runs through chlorine gas handling infrastructure facing EU F-Gas phase-down deadlines. Distribution runs through miller-direct bulk contracts, wholesale distributor networks, and platform-aggregated e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
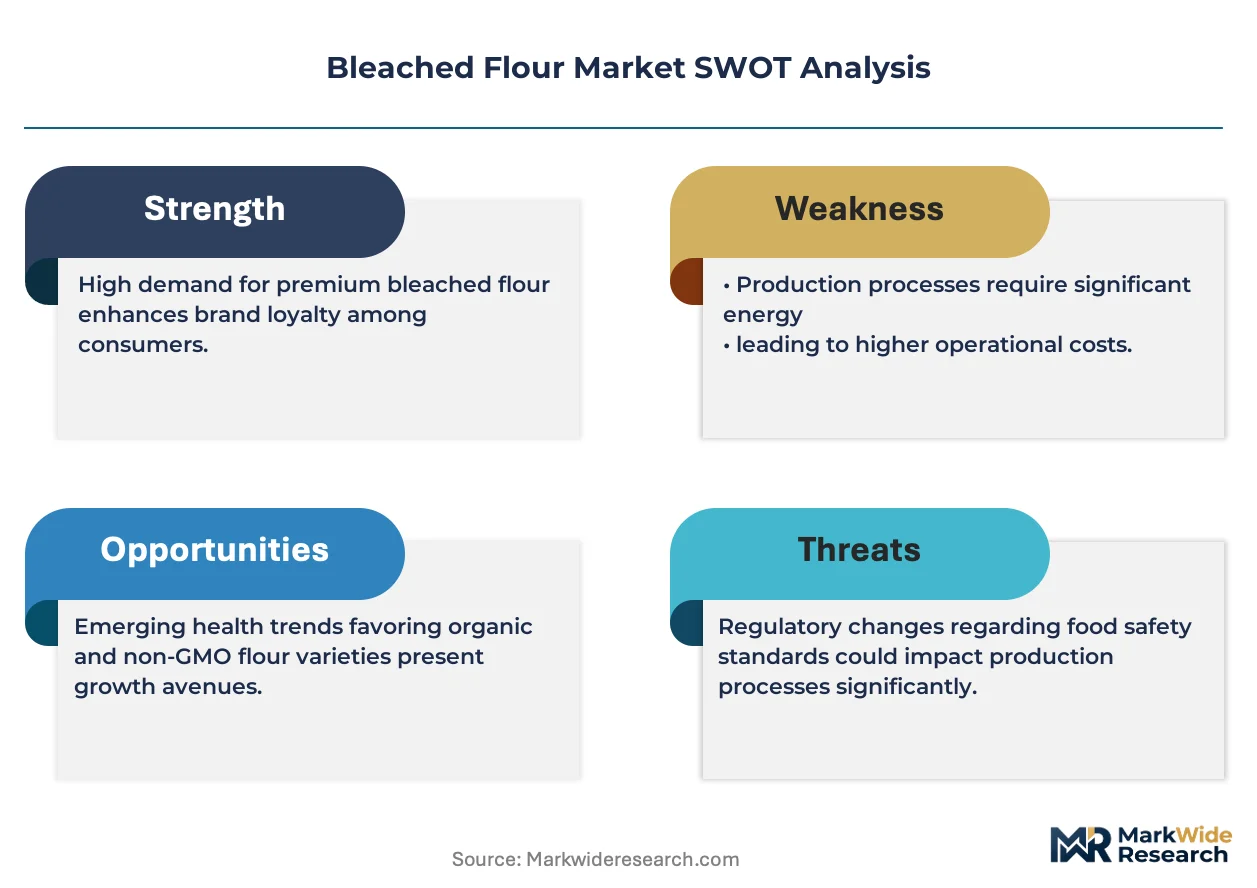
The bleached flour market compounds as a regulatory arbitrage play, with REACH additive traceability mandates and EU F-Gas restrictions creating preferential access tiers for certified operators.
For Market Incumbents: Lock in backward integration into captive grain elevator networks across the Great Plains and Java to secure supply continuity against Black Sea disruption. Prioritize BRCGS and IFS certification queue positioning to defend contract eligibility from enzymatic bleaching entrants targeting EU export channels. The threat of clean-label substitution in premium retail segments demands parallel investment in unbleached flour co-production capabilities. For New Entrants and Emerging Players: Launch via direct-to-consumer platforms in Jakarta and Ho Chi Minh City, bypassing traditional distributor markups with recipe-bundled SKUs targeting amateur bakers. The most penetrable white-space sits in mid-sized Vietnamese industrial bakeries adopting oxidase-based platforms for export compliance flexibility. A specialty cake flour positioning with EFSA novel food approval pathways establishes regulatory moats against later competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where certification audit queues exceed twelve-month backlogs and legacy chlorine-based facilities face stranded asset risk. Long-term viability favors integrated operators with in-house analytical capabilities and multi-jurisdictional additive dossier management. Acquisition targets include regional specialists with ASEAN regulatory alignment and enzymatic platform certification progress. The signal to watch is EFSA positive opinion issuance rates for novel oxidase treatments.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bleaching Platform Certification | EFSA novel food approval creates regulatory moats against chlorine-dependent competitors in EU export channels. |
| Backward Integration into Grain Elevator Networks | Captive wheat origination in Kansas and Minnesota insulates margin compression from Black Sea supply disruptions. |
| Direct-to-Consumer E-Commerce Launch | Jakarta-based aggregators bypass distributor markups while building brand recognition among recipe-driven home bakers. |
| BRCGS Certification Investment | Food processor contract eligibility hinges on audit completion as twelve-month queues exclude uncertified regional mills. |
| Dual-Process Facility Conversion | Chlorine-to-benzoyl-peroxide retrofitting preserves EU market access under REACH and F-Gas phase-down timelines. |
Research Methodology
Multiple input streams — primary interviews with mill operations managers, food processing procurement leads, and regulatory affairs directors; secondary validation through FDA 21 CFR filings, EFSA additive opinions, and ASEAN harmonization protocols; plus customs trade data and integrated mill capacity disclosures — were reconciled through bottom-up and top-down triangulation. The approach combined structured conversations across fifteen stakeholder roles with quantitative validation from grain futures databases and milling industry association reports.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user application, packaging format, and distribution channel, with regulatory jurisdiction clusters treated as a cross-cutting variable. CAGRs were derived from trend extrapolation of procurement volume patterns and capacity expansion announcements. Industry-specific forecast inputs incorporated wheat basis spread volatility and enzymatic platform adoption curves.
Several conditions sit outside the modeled scope, including unannounced regulatory threshold revisions, abrupt trade policy shifts affecting Black Sea wheat flows, and breakthroughs in non-enzymatic bleaching chemistry. Forecasts reflect documented assumptions regarding milling capacity commissioning timelines and certification audit completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sea Salt Market
Ingredients
Europe Fats and Oil Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Elecampane Root Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Interesterified CBE Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Rose Extract Market
Ingredients
Virginiamycin Market
Ingredients
Functional Flours Market
Ingredients
North America Agar Market
Ingredients
Fig Ingredient Market
Ingredients
Botanical Extracts Market
Ingredients
Thinned Starch Market