
 Functional Ingredients Market | 2026-2036
Functional Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Ingredients Market Intelligence
Direct-to-manufacturer procurement channels is reshaping how functional ingredients reach nutraceutical and food producers. Cargill, Incorporated leverages its agricultural supply chain to secure raw material cost advantages across vitamin and mineral production. BASF SE anchors its position through R&D intensity in specialty enzymes and carotenoid formulations. Kerry Group plc differentiates via integrated taste-and-nutrition platforms that bundle functional actives with flavor systems.
Functional ingredients comprise bioactive compounds, live microbial cultures, and physiologically beneficial substances engineered to deliver targeted health outcomes beyond basic nutrition. Probiotic strains require minimum viable cell counts and cold-chain stability specifications to maintain labeled potency through shelf life. Probiotics command premium positioning due to strain-specific clinical validation requirements and fermentation complexity. Dietary fibers in powder form represent the fastest-expanding application segment as beverage manufacturers reformulate for sugar reduction and digestive health claims.
FDA GRAS self-affirmation and EFSA health claims authorization create divergent compliance pathways that determine which bioactives achieve commercial scale in the United States versus European markets. China's NMPA and SAMR enforce novel food ingredient registration that extends approval timelines for imported probiotic strains and enzyme preparations. Stakeholders must monitor evolving strain-level regulatory classifications and invest in jurisdiction-specific clinical dossiers before committing to capacity expansion.
Market Dynamics
Clean-label disclosure mandates across the European Union and United States are compressing formulation timelines while probiotic strain registration requirements in China extend commercialization cycles, forcing ingredient suppliers to build jurisdiction-specific dossier capabilities before capacity commitments.
Growth Catalysts
- EFSA health claims authorization:Validated bioactive dossiers unlock premium positioning for carotenoid and fiber ingredients in European functional foods, accelerating branded ingredient partnerships with multinational food manufacturers.
- Gut-health positioning in beverages:Sugar reduction mandates drive beverage reformulation using soluble dietary fibers, creating pull-through demand for prebiotic fiber systems in carbonated and ready-to-drink categories.
- Strain-specific clinical validation:Documented efficacy for Lactobacillus and Bifidobacterium variants commands price premiums and secures multi-year supply contracts with nutraceutical formulators.
Market Restraints
- Fermentation capacity concentration:Probiotic production clusters in Denmark and France create geographic supply risk, with limited qualified contract manufacturers for high-cell-count freeze-dried preparations.
- Novel food ingredient registration:China's SAMR approval timelines for imported enzyme preparations extend 18-36 months, freezing market entry for non-domestic suppliers without local clinical data.
- Plant protein substitution:Pea and fava protein isolates displace traditional dairy-based functional proteins in sports nutrition, compressing margins for whey-derived bioactive suppliers.
Strategic Opportunities
- Postbiotic metabolite applications:Heat-killed microbial derivatives bypass cold-chain requirements, opening shelf-stable functional food categories previously inaccessible to live cultures.
- Direct-to-manufacturer digital platforms:Bypassing traditional ingredient distributors reduces procurement friction for mid-sized functional food startups in Germany and the Netherlands.
- India FSSAI novel food pathway:Streamlined approval mechanisms for documented probiotic strains create first-mover positioning in Asia's fastest-expanding functional dairy market.
Industry Challenges
- Strain banking and master cell repository management:Maintaining genetic consistency across multi-site fermentation requires specialized microbiology talent scarce outside Copenhagen and Madison research clusters.
- Cross-jurisdiction dossier harmonization:FDA GRAS self-affirmation, EFSA Article 13.5 claims, and NMPA registration demand non-overlapping clinical endpoints, tripling development expenditure for global launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Ingredients Market |
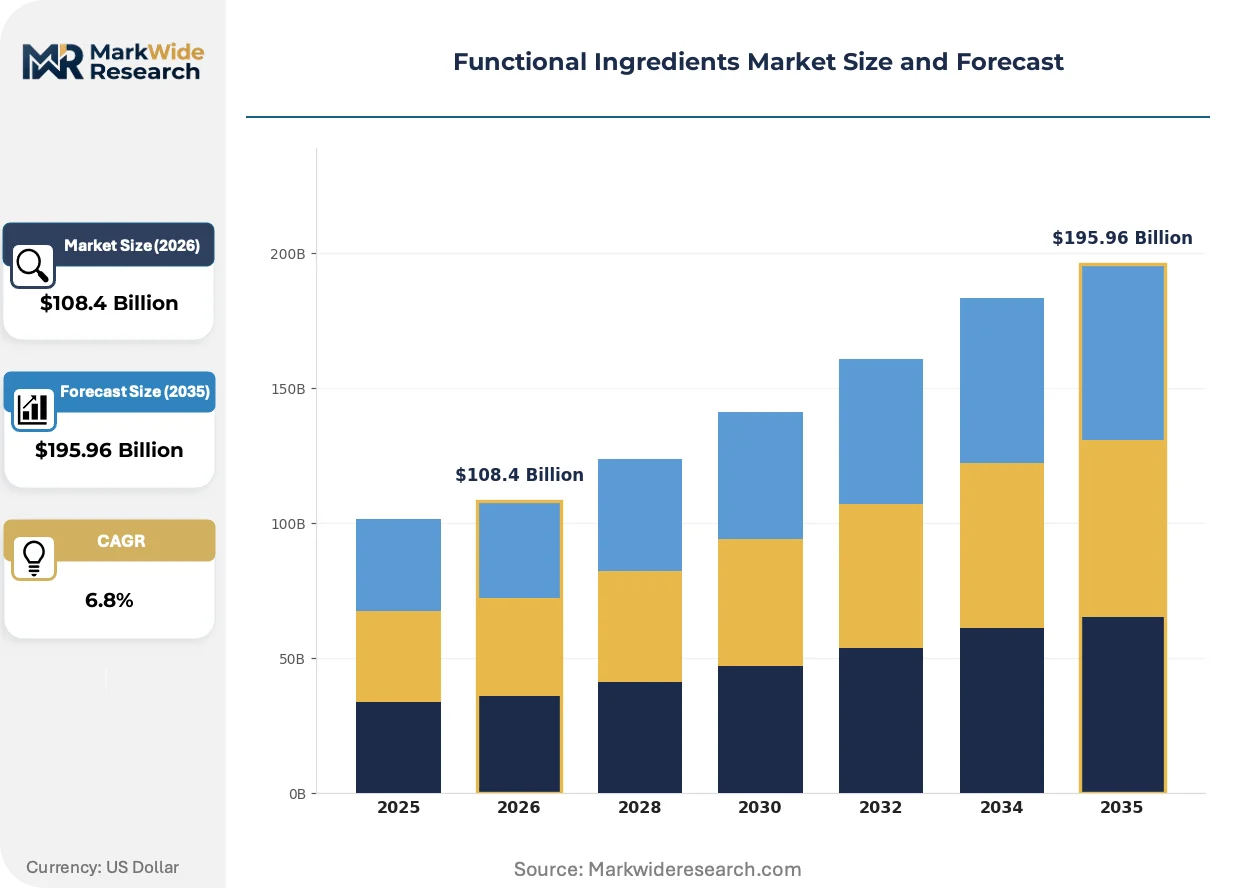
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $195.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Dietary Fibers, Probiotics, Enzymes Application: Beverages, Dietary Supplements, Clinical Nutrition, Animal Feed, Bakery Products Form: Powder, Liquid, Capsule, Tablet, Granules End User: Food & Beverage Manufacturers, Nutraceutical Companies, Animal Nutrition Firms, Pharmaceutical Producers |
| Companies Covered | Cargill, Incorporated, BASF SE, Archer Daniels Midland Company, Kerry Group plc, DSM-Firmenich AG, Arla Foods amba, Ingredion Incorporated, Tate & Lyle plc, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Ingredients Market Strategic Shifts & Innovations
Bioprocessing advances and regulatory science convergence are compressing the gap between laboratory validation and commercial scale, while digital traceability systems reshape how ingredient provenance is communicated downstream.
Precision fermentation for high-value bioactives is hybridizing pharmaceutical-grade manufacturing discipline with food-scale economics. Specialty enzyme producers in the Netherlands and California adopt single-use bioreactor trains previously reserved for monoclonal antibodies. This convergence collapses minimum viable scale thresholds, enabling mid-cap ingredient suppliers to enter carotenoid and omega-3 markets previously dominated by agricultural extraction.
REACH bioaccumulation assessments and EFSA novel food guidance are tightening toxicological data requirements for microbial fermentation products. European ingredient suppliers now commission 90-day rodent studies and human intervention trials before commercial launch. The compliance burden falls heaviest on postbiotic and paraprobiotic categories, where heat-killed cell preparations lack historical consumption evidence.
Ingredient specification sheets now carry blockchain-verified carbon intensity and water footprint data. German and Swiss chocolate manufacturers audit upstream supply chains for deforestation compliance, rejecting palm-derived emulsifiers without RSPO-IP certification. This traceability imperative favors vertically integrated agricultural processors with captive cultivation and extraction assets over trading-house intermediaries.
Functional Ingredients Market Segmentation
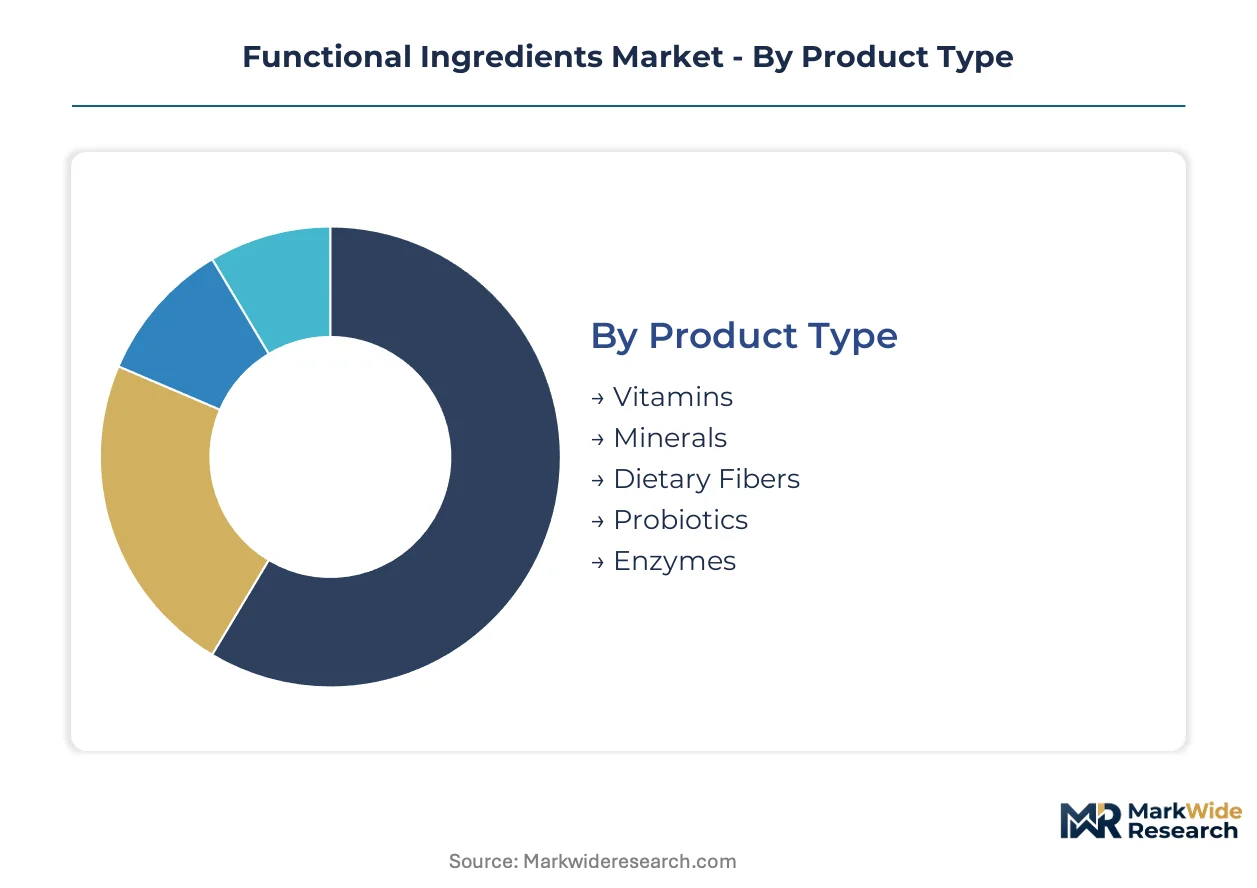
Ingredient form, application channel, and end-user technical requirements create distinct commercial pathways in the functional ingredients market. Each segmentation dimension carries specific regulatory, supply chain, and margin implications that determine competitive positioning.
Product Type:
Mature categories dominate revenue concentration while emerging segments command premium pricing through clinical validation requirements.
- Vitamins:Synthetic and natural vitamin compounds serve fortification mandates across food and supplement matrices. Demand concentrates in the United States where FDA fortification guidelines drive steady procurement from beverage manufacturers and cereal producers.
- Minerals:Chelated and inorganic mineral salts address bioavailability specifications for targeted health outcomes. Chelated forms gain traction in Germany's precision nutrition segment as EFSA-validated absorption claims unlock premium positioning.
- Dietary Fibers:Soluble and insoluble fiber systems enable sugar reduction and digestive health positioning.
- Probiotics:Live microbial cultures require strain-specific clinical dossiers and cold-chain stability protocols.
- Enzymes:Protease, lipase, and carbohydrase preparations catalyze targeted metabolic and processing functions.
Probiotics handle the majority of throughput; dietary fibers are expanding most quickly on share.
Application:
End-use channel selection determines formulation complexity, regulatory pathway, and margin structure across the value chain.
- Beverages:Ready-to-drink and functional water categories integrate heat-stable bioactives and clear-dissolving fiber systems. Sugar reduction mandates in Germany and California drive reformulation demand for prebiotic fiber fortification.
- Dietary Supplements:Capsule, tablet, and powder delivery systems require high-potency actives with validated shelf-life stability. Strain-specific probiotic supplements command premium pricing in China where NMPA registration creates supply scarcity.
- Clinical Nutrition:Medical food and enteral feeding specifications demand pharmaceutical-grade manufacturing discipline.
- Animal Feed:Enzyme and probiotic feed additives improve feed conversion ratios in poultry and swine operations.
- Bakery Products:Fiber fortification and enzyme-based dough conditioning address clean-label reformulation trends.
Beverages generate the highest volume pull; dietary supplements deliver the steepest margin expansion.
Form:
Physical delivery format dictates manufacturing compatibility, stability requirements, and downstream processing economics.
- Powder:Spray-dried and agglomerated powders enable flexible dosing and extended shelf-life for beverage and supplement applications. Powdered dietary fibers represent the fastest-climbing application segment as manufacturers reformulate for sugar reduction claims.
- Liquid:Suspension and solution formats suit ready-to-drink beverages and liquid supplement delivery. Liquid enzyme concentrates serve industrial food processing lines in Denmark and the Netherlands where precision dosing systems dominate.
- Capsule:Hard-shell and soft-gel encapsulation protects acid-sensitive actives through gastric transit.
- Tablet:Compressed tablet formats enable controlled-release and convenience positioning in supplement channels.
- Granules:Agglomerated granule systems improve flow properties and dispersibility in instant beverage applications.
Powder commands the largest production volume; liquid formats are gaining share fastest in beverage applications.
End User:
Customer type determines technical service intensity, contract structure, and regulatory compliance burden.
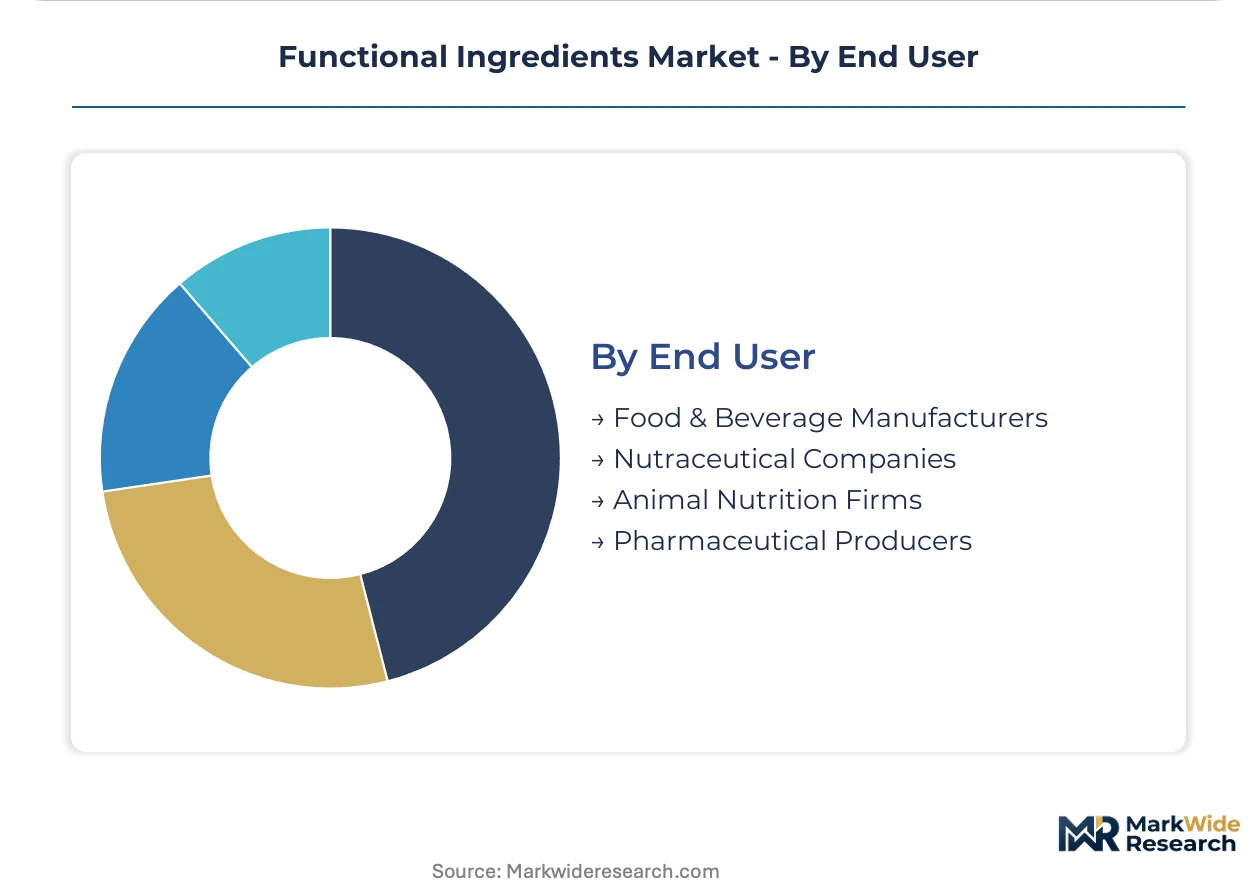
- Food & Beverage Manufacturers:Large-scale processors procure bulk actives for mass-market fortification and functional positioning. Clean-label disclosure mandates from EFSA and FDA compress formulation timelines for European and American beverage producers.
- Nutraceutical Companies:Branded supplement formulators demand strain-specific clinical dossiers and custom premix services. Kerry Group and BASF anchor supply relationships through integrated taste-and-nutrition platforms and R&D collaboration.
- Animal Nutrition Firms:Feed compounders integrate enzymes and probiotics for productivity and gut health outcomes.
- Pharmaceutical Producers:Drug manufacturers source excipient-grade bioactives for medical food and OTC applications.
Food and beverage manufacturers absorb the dominant procurement volume; nutraceutical companies drive the fastest margin expansion through premium ingredient partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA fortification guidelines and EFSA health claims frameworks anchor procurement patterns in the United States and Germany, while China's NMPA strain registration requirements and India's FSSAI novel food pathways create divergent commercialization timelines across major demand centers.
United States
Beverage manufacturers in California and Texas drive bulk vitamin and fiber procurement for sugar-reduction reformulation. FDA GRAS self-affirmation pathways enable faster ingredient launches than European equivalents. Chicago and Minneapolis host major premix operations where Cargill leverages agricultural supply chain integration.
Germany
Precision nutrition demand concentrates in Bavaria and North Rhine-Westphalia for chelated mineral applications. EFSA Article 13.5 health claims authorization unlocks premium positioning for validated bioactives. Frankfurt and Mannheim clusters specialize in fermentation-derived specialty enzymes for gut-health positioning.
China
NMPA and SAMR enforce 18-36 month approval timelines for imported probiotic strains, freezing market entry without local clinical data. Yangtze River Delta beverage producers pull soluble dietary fibers for functional water categories. Shanghai biotech parks incubate domestic strain development to bypass import registration.
India
FSSAI streamlined novel food pathways for documented probiotic strains attract first-mover investment in functional dairy. Maharashtra and Gujarat dairy cooperatives expand procurement of live cultures for traditional fermented products. Bangalore nutraceutical startups leverage direct-to-manufacturer platforms to bypass distributor markups.
Netherlands
Single-use bioreactor adoption in Rotterdam and Eindhoven enables mid-cap suppliers to enter carotenoid markets. REACH bioaccumulation assessments tighten toxicological requirements for microbial fermentation products. Wageningen University partnerships anchor enzyme R&D clusters for precision fermentation applications.
Functional Ingredients Market Key Industry Players
Agricultural conglomerates and specialty chemical producers split the market into distinct capability tiers. Consolidation pressure concentrates probiotic fermentation in Denmark and France, while dietary fiber production disperses across agricultural processing hubs. Three archetypes dominate: vertically integrated agricultural processors with captive raw material access; R&D-intensive specialty chemical houses with pharmaceutical-grade manufacturing discipline; integrated taste-and-nutrition platforms bundling functional actives with flavor systems. Capacity expansion in precision fermentation and strategic partnerships for strain-specific clinical validation represent the dominant competitive moves.
Within the agricultural-processor archetype, Cargill, Incorporated exemplifies supply chain integration from field to formulated ingredient. Among R&D-intensive chemical houses, BASF SE and DSM-Firmenich AG occupy positions defined by fermentation complexity and carotenoid formulation depth. Kerry Group plc anchors the integrated platform tier, representing the taste-and-nutrition bundling model that reduces procurement friction for mid-sized functional food manufacturers.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Archer Daniels Midland Company |
| Kerry Group plc |
| DSM-Firmenich AG |
| Arla Foods amba |
| Ingredion Incorporated |
| Tate & Lyle plc |
| Danone |
| Others |
Cost & Logistics Intelligence
Tariff exposure on imported probiotic strains from Denmark and France compresses margin structures for North American nutraceutical formulators while simultaneously widening the spread between validated premium strains and unverified commodity alternatives. This geographic concentration of fermentation capacity forces buyers to absorb cold-chain logistics premiums or pivot toward domestic toll manufacturers with higher unit costs but lower regulatory risk.
Pricing Analysis
The customization-premium spread separates strain-specific clinical dossiers from generic commodity cultures. Pricing stratifies across premium, standard, and economy tiers based on cell-count guarantees and EFSA Article 13.5 validation status. Cost compression in the economy tier is intensifying because Chinese domestic suppliers are flooding soluble fiber markets with undifferentiated inulin alternatives. Mid-sized beverage manufacturers exhibit the highest price sensitivity, while pharmaceutical-grade clinical nutrition buyers accept substantial premiums for documented bioavailability data.
Supply Chain Analysis
Supplier-financing facilities from Dutch agricultural conglomerates now extend 90-day payment terms to secure exclusive offtake agreements for prebiotic fiber systems. Raw material sourcing draws from Danish dairy whey streams, French beet sugar fermentation feedstocks, and Indian guar gum cultivation. Single-source vulnerability concentrates in Copenhagen-area master cell repositories, where genetic drift risks cascade across multiple contract manufacturers. Distribution runs through Rotterdam bulk terminals for European compounders and direct-to-manufacturer digital platforms for German functional food startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as integrated taste-and-nutrition systems displace standalone ingredient transactions, with Kerry Group's bundling model demonstrating how flavor-technology interoperability captures mid-market share.
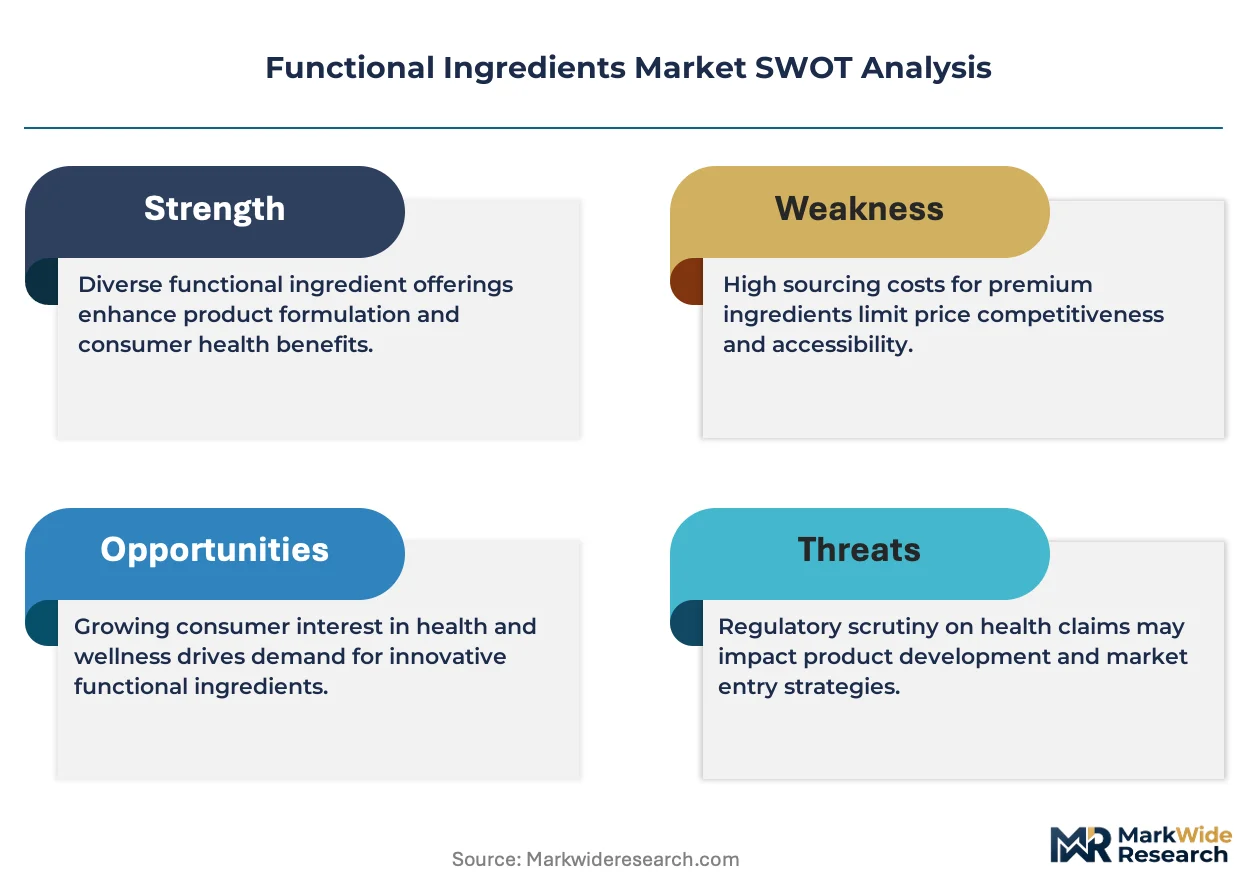
For Market Incumbents: Pre-empt margin erosion in commodity vitamins by securing captive cultivation contracts for carotenoid precursors in California's Central Valley. Plant protein substitution threatens whey-derived bioactive suppliers; defend position through precision fermentation capacity additions in the Netherlands that bypass agricultural commodity cycles entirely. For New Entrants and Emerging Players: Postbiotic metabolite applications in shelf-stable functional foods represent the most penetrable entry point, bypassing cold-chain infrastructure requirements that incumbent probiotic suppliers cannot easily abandon. India's FSSAI streamlined approval pathway for documented strains enables first-mover positioning without the 18-36 month NMPA timelines that freeze Chinese market entry. Direct-to-manufacturer digital procurement platforms in Germany and the Netherlands reduce customer acquisition costs versus traditional distributor relationships. For Investors and Strategic Acquirers: Precision fermentation specialists with pharmaceutical-grade manufacturing discipline and single-use bioreactor deployment capability offer the strongest long-term viability profile across the analysis window. Monitor EFSA novel food guidance tightening as the inflection signal; heat-killed microbial preparations lacking 90-day rodent toxicology data will face accelerated regulatory obsolescence, compressing valuations for underprepared target firms.| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Specific Clinical Dossier Investment | EFSA Article 13.5 validation unlocks premium positioning for carotenoid and fiber ingredients in European functional foods. |
| Precision Fermentation Capacity Expansion | Single-use bioreactor adoption in Rotterdam and Eindhoven collapses minimum viable scale thresholds for mid-cap suppliers. |
| Direct-to-Manufacturer Digital Platform Launch | Bypassing traditional distributors reduces procurement friction for German and Dutch functional food startups. |
| Postbiotic Metabolite Product Line Development | Heat-killed derivatives bypass cold-chain requirements, opening shelf-stable categories inaccessible to live cultures. |
| India FSSAI Novel Food Pathway Registration | Streamlined approval mechanisms for documented probiotic strains create first-mover positioning in Asia's fastest-expanding functional dairy market. |
Research Approach
Cross-validation between primary interviews with fermentation scientists, regulatory affairs directors at ingredient suppliers, beverage formulation chemists, and premix procurement managers anchors the qualitative findings against secondary validation from EFSA novel food guidance documents, FDA GRAS notification filings, NMPA registration databases, and customs trade flow records. Bottom-up strain-level demand estimates triangulate with top-down category consumption models.
Calibration against historical capacity utilization rates and announced expansion projects across Danish and French fermentation facilities ensures internal consistency. Segmentation dimensions span ingredient form, application channel, end-user technical requirements, and jurisdiction-specific regulatory pathway. CAGRs derive from elasticity-adjusted demand projections incorporating sugar-reduction mandate timelines and clean-label disclosure implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity input costs, cross-border tariff regimes, or central bank interest rate policy would shift the trajectory. Forecasts reflect documented assumptions regarding strain registration timeline stability and precision fermentation yield improvement curves; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Lovage Extract Market