
 Orange Powder Market | 2026-2036
Orange Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Orange Powder Market Analytics
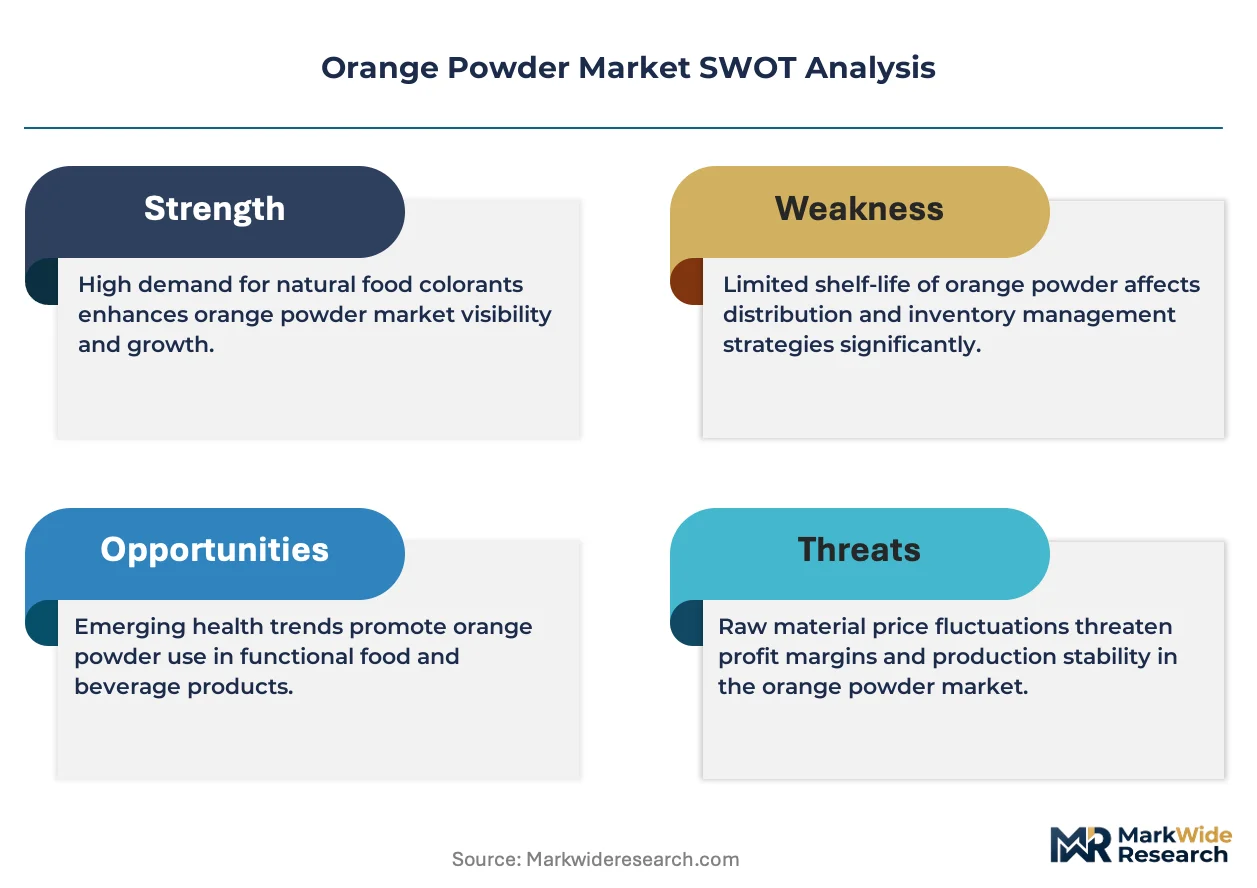
Functional beverage formulators is rotating toward orange powder as a natural colorant and flavor carrier, displacing synthetic alternatives in premium positioning. Givaudan S.A. leverages captive citrus extraction capabilities to secure raw material continuity across volatile harvest cycles. Symrise AG anchors its orange powder portfolio through integrated supply relationships with Mediterranean and Brazilian growers. Kerry Group plc differentiates via spray-drying technology leadership that preserves volatile terpene profiles for beverage applications.
Orange powder consists of dehydrated citrus sinensis pulp, peel, or juice concentrate processed into fine particulate form, typically standardized to essential oil content between 1.5% and 5.0% for flavor consistency. The material functions primarily as a natural flavoring agent, acidulant, and colorant across formulated consumer goods. Natural orange powder commands premium positioning in organic-certified food and beverage applications, while synthetic variants retain cost-sensitive share in industrial flavor compounding. Nutraceuticals represents the fastest-growing application segment, driven by vitamin C fortification and polyphenol extraction demand. The food and beverage application segment remains the volume anchor, though margin pools are thinning amid private-label competition.
EFSA purity standards and FDA GRAS self-affirmation requirements shape product specifications for cross-border ingredient trade, with compliance costs favoring scaled processors over regional traders. REACH registration obligations for imported citrus-derived substances add procedural friction for non-European suppliers accessing European compounders. Stakeholders must monitor evolving EU deforestation-free supply chain mandates, which will force traceability investments across orange powder sourcing networks.
Market Dynamics
Clean-label procurement mandates from food and beverage formulators are compressing synthetic flavorant margins while elevating natural citrus derivatives. The EU Green Deal's deforestation-free supply chain requirements are forcing traceability investments that favor scaled processors with captive sourcing networks.
Growth Catalysts
- EU Green Deal sourcing mandates:Deforestation-free certification requirements are disqualifying uncertified suppliers and consolidating procurement toward vertically integrated processors with documented orchard traceability.
- Ayurvedic nutraceutical expansion:India's domestic citrus processing capacity is accelerating orange powder adoption for vitamin C fortification and polyphenol extraction in traditional medicine formulations.
- Spray-drying technology maturation:Advanced encapsulation systems that preserve volatile terpene profiles are opening premium beverage applications previously closed to heat-degraded citrus powders.
Market Restraints
- Citrus harvest volatility:Brazilian and Mediterranean orange crop fluctuations create raw material price instability that compresses processor margins during low-yield cycles.
- REACH registration friction:ECHA compliance obligations for imported citrus-derived substances add procedural delays and documentation costs for non-European suppliers accessing EU compounders.
- Synthetic flavorant cost advantage:Artificial orange flavoring maintains price competitiveness in industrial applications where clean-label positioning carries no consumer-facing premium.
Strategic Opportunities
- India domestic market penetration:Underdeveloped organized retail and foodservice channels present first-mover advantages for branded orange powder positioning in emerging urban centers.
- EFSA Novel Food pathway:Emerging extraction technologies enabling enhanced polyphenol concentrates qualify for premium nutraceutical positioning through regulatory approval arbitrage.
- E-commerce ingredient platforms:Direct procurement channels are compressing distributor markups and enabling smaller formulators to access certified organic grades previously locked behind volume minimums.
Industry Challenges
- Terpenoid preservation expertise gap:Formulation chemists with specialized knowledge of volatile compound stabilization during thermal processing command scarcity premiums that inflate R&D overhead.
- Organic certification timeline compression:Three-year conversion periods for orchard certification create stranded asset risk when demand spikes outpace certified supply expansion.
- Cross-border documentation complexity:Divergent FDA GRAS self-affirmation and EFSA purity standard requirements force dual-track compliance systems that fragment quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orange Powder Market |
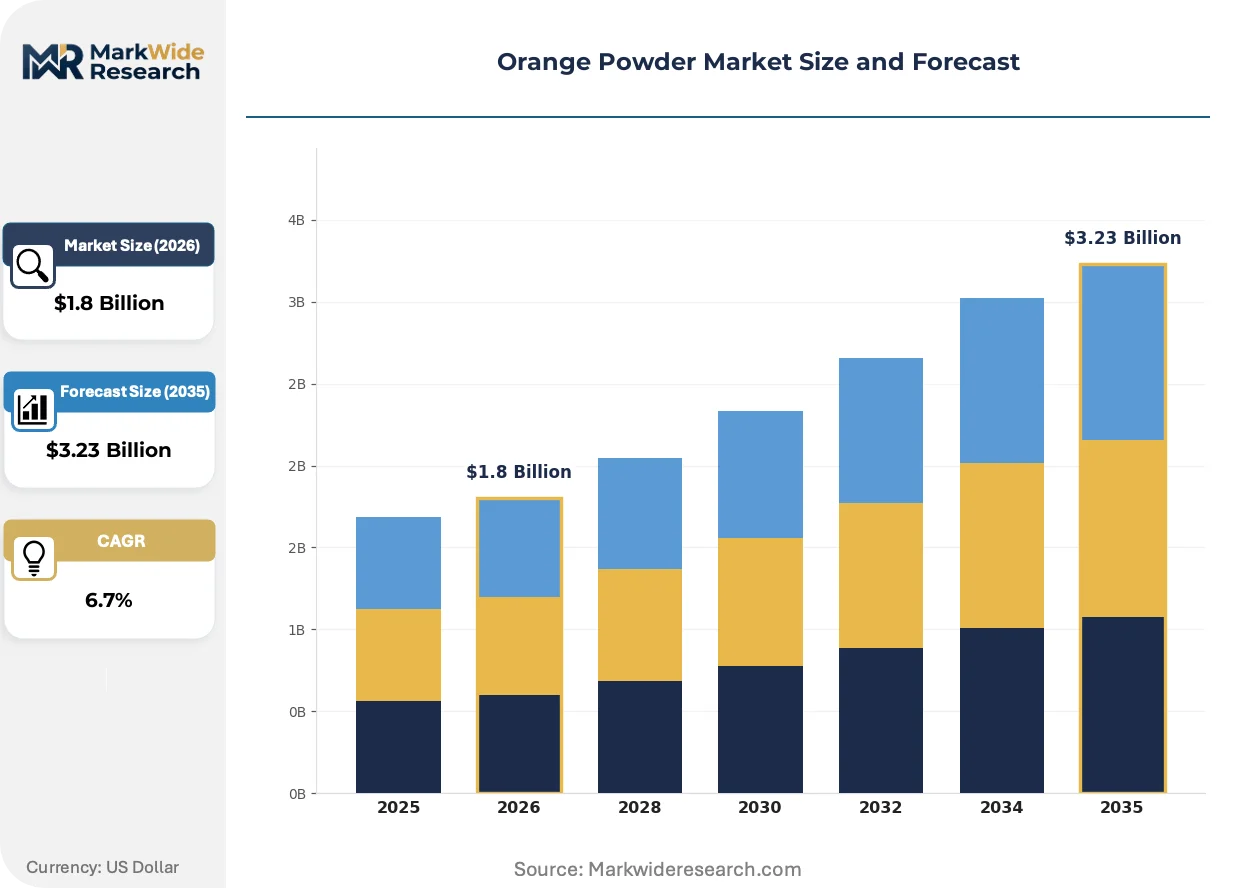
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Conventional Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals End User: Manufacturers, Retailers, Distributors, Wholesalers Distribution Channel: Online, Offline, Specialty Stores, Supermarkets |
| Companies Covered | Givaudan S.A., Symrise AG, Kerry Group plc, International Flavors & Fragrances Inc., Döhler GmbH, Procter & Gamble, Vinayak Ingredients, Nexira, Tropicana Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orange Powder Market Evolving Landscape
Processing technology convergence with sustainability mandates is reconfiguring competitive advantage around energy efficiency and waste valorization rather than scale alone. Regulatory fragmentation between jurisdictions is accelerating specification divergence that favors regional specialists over global generalists.
Low-temperature vacuum belt drying is decomposing the traditional spray-drying dominance in premium orange powder segments. Functional beverage formulators in North America and Western Europe are adopting this technology to capture heat-sensitive bioactive compounds that conventional thermal methods degrade. The structural consequence is decomposing the commodity-grade volume advantage of legacy processors, compressing their margin pools while creating premium positioning for technology-differentiated suppliers.
EFSA's evolving purity standards for citrus-derived food additives are tightening heavy metal and pesticide residue thresholds beyond Codex Alimentarius baselines. European compounders must now validate supplier testing protocols or face import detention at border inspection posts. Nutraceutical applications face the steepest compliance cost escalation, driving consolidation toward processors with in-house analytical laboratories and third-party accreditation.
Direct procurement from certified organic cooperatives is displacing traditional distributor-mediated sourcing for mid-sized formulators. Specialty food manufacturers in Germany and the Netherlands are establishing multi-year offtake agreements with specific Mediterranean grower associations, bypassing commodity traders entirely. This channel disintermediation concentrates volume commitments with traceable origin suppliers while marginalizing speculative merchants lacking orchard-level relationships.
Orange Powder Market Segmentation
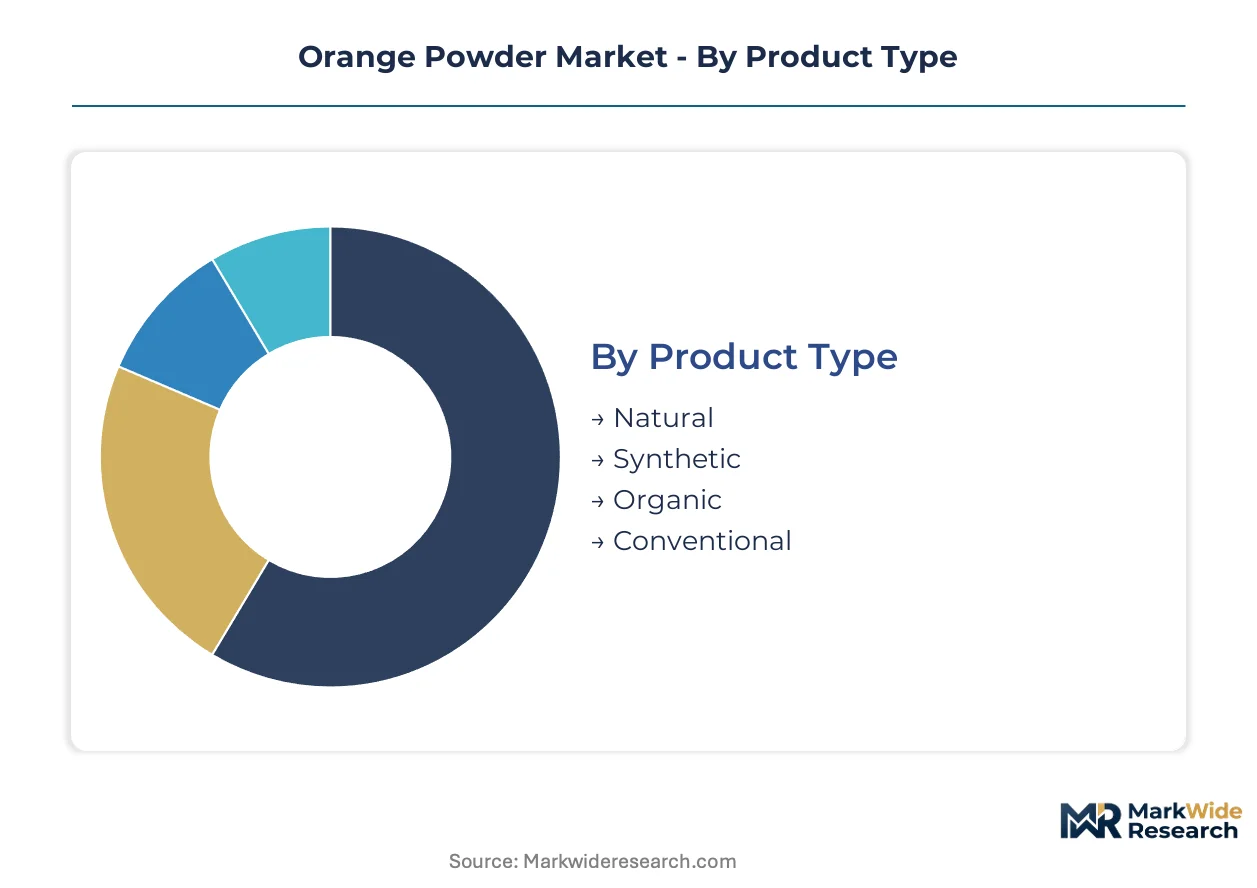
Orange powder segmentation reflects divergent compliance burdens across regulatory jurisdictions. Product-origin distinctions determine certification pathways, while application-driven purity requirements fragment procurement specifications.
Product Type:
EFSA Novel Food pathways and USDA organic equivalency agreements create divergent qualification timelines for origin-based categories.
- Natural:Dehydrated citrus sinensis pulp, peel, or juice concentrate standardized to essential oil content between 1.5% and 5.0%. Beverage formulators in Germany and the Netherlands are rotating procurement toward this grade as clean-label mandates displace synthetic alternatives in premium positioning.
- Organic:Orchard-level certification requiring three-year conversion periods under EU organic regulation and USDA NOP standards. Indian Ayurvedic manufacturers are accelerating procurement for vitamin C fortification applications, though supply expansion lags demand spikes.
- Synthetic:Artificial flavoring compounds retaining cost competitiveness in industrial applications where clean-label positioning carries no consumer-facing premium.
- Conventional:Non-certified natural grades serving price-sensitive foodservice and industrial compounders with reduced documentation requirements.
Natural orange powder handles the majority of throughput; Organic is expanding most quickly on share.
Application:
End-use specifications range from beverage-grade terpene preservation to pharmaceutical-grade heavy metal thresholds.
- Nutraceuticals:Polyphenol extraction and vitamin C fortification applications with steepest compliance cost escalation under EFSA purity standards. Indian traditional medicine manufacturers are driving volume concentration.
- Food & Beverage:Natural flavoring, acidulant, and colorant functions across formulated consumer goods. Spray-drying technology leadership determines supplier selection for volatile terpene preservation.
- Pharmaceuticals:Excipient and active ingredient applications requiring validated supplier testing protocols to avoid import detention at EU border inspection posts.
- Cosmetics:Fragrance and antioxidant applications with lower regulatory burden than ingestible grades.
Food & Beverage retains volume dominance; Nutraceuticals climbs the fastest on margin contribution.
End User:
Procurement scale determines access to certified organic grades and direct cooperative sourcing arrangements.
- Manufacturers:Formulators with captive analytical laboratories and third-party accreditation capturing consolidation benefits from EFSA compliance cost escalation.
- Distributors:Traditional channel intermediaries facing margin compression from e-commerce ingredient platforms and direct procurement trends.
- Retailers:Specialty food and organic grocery chains establishing multi-year offtake agreements with Mediterranean grower associations.
- Wholesalers:Speculative merchants lacking orchard-level relationships facing marginalization under EU deforestation-free supply chain mandates.
Manufacturers command the largest procurement volumes; Retailers are gaining share fastest through direct sourcing investments.
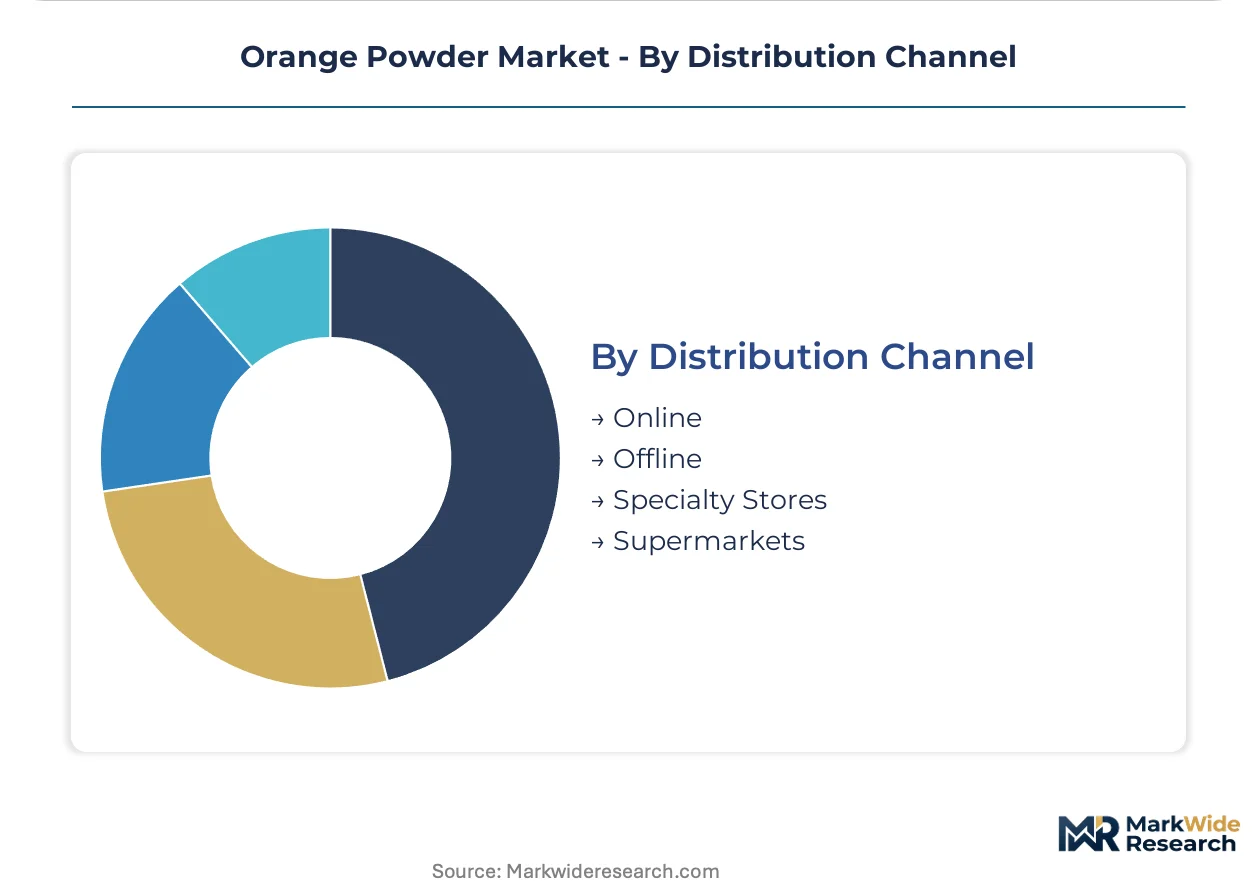
Distribution Channel:
Channel selection reflects customer scale, certification requirements, and traceability documentation needs.
- Online:E-commerce ingredient platforms compressing distributor markups and enabling smaller formulators to access certified organic grades previously locked behind volume minimums.
- Offline:Established procurement relationships with legacy processors offering commodity-grade volume advantages.
- Specialty Stores:Regional organic and natural product distributors serving mid-sized formulators with documented origin requirements.
- Supermarkets:Mass-market retail channels for consumer-packaged orange powder products with reduced specification stringency.
Offline channels maintain current volume leadership; Online is expanding most quickly on customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports raw citrus materials to European processors while India ships finished nutraceutical grades to Ayurvedic compounders across Southeast Asia. Mediterranean growers supply clean-label certified stock to German and Dutch beverage formulators under deforestation-free procurement mandates.
United States
Functional beverage startups in California and the Pacific Northwest are displacing synthetic flavorants with natural orange powder for premium positioning. FDA GRAS self-affirmation requirements shape import specifications for Brazilian and Mexican citrus derivatives. Chicago-area flavor houses concentrate procurement volume for carbonated soft drink reformulations.
Germany
Clean-label mandates from Berlin and Munich-based organic food manufacturers are compressing synthetic flavorant share. EFSA purity standards and EU Green Deal traceability requirements disqualify uncertified Mediterranean suppliers. The Hamburg-Rotterdam corridor anchors distribution infrastructure for spray-dried citrus ingredients entering compounder networks.
India
Ayurvedic nutraceutical manufacturers in Maharashtra and Gujarat are accelerating domestic orange powder adoption for vitamin C fortification. FSSAI food safety standards and DGFT import regulations govern cross-border citrus derivative trade. Nagpur's citrus belt is expanding processing capacity to capture value from traditional medicine export demand.
Brazil
São Paulo-state orange processors supply raw concentrate to European and North American formulators despite harvest volatility compressing margin stability. ANVISA pharmaceutical-grade standards and EU deforestation-free certification requirements shape export documentation burdens. The Citricos belt around São José do Rio Preto anchors captive sourcing relationships with multinational flavor houses.
Netherlands
Amsterdam and Rotterdam-based trading houses are disintermediating speculative merchants through direct cooperative sourcing from Mediterranean grower associations. REACH registration obligations for imported citrus-derived substances add procedural friction for non-European suppliers. The Randstad cluster concentrates analytical laboratory capacity for EFSA compliance validation.
Orange Powder Market Competitive Landscape
Listed leaders compete with private specialists across technology differentiation and sourcing control dimensions. The vendor base stratifies between scale-driven commodity processors and technology-differentiated premium suppliers. Three archetypes dominate: integrated flavor houses with captive citrus extraction, specialist spray-drying technology providers, and regional organic cooperative aggregators. Competitive moves concentrate on backward integration into orchard networks and low-temperature drying capacity expansion.
Among Swiss and Irish listed flavor houses, Givaudan S.A., Kerry Group plc, and Symrise AG occupy positions exemplifying integrated supply chain control. Givaudan represents the archetype of captive extraction capabilities securing raw material continuity. Kerry Group exemplifies spray-drying technology leadership preserving volatile terpene profiles. Symrise anchors Mediterranean and Brazilian sourcing relationships. German private specialists like Döhler GmbH and French ingredient distributors like Nexira sit within the regional premium tier, while Indian manufacturers including Vinayak Ingredients capture Ayurvedic nutraceutical demand growth.
| Leading Market Players |
|---|
| Givaudan S.A. |
| Symrise AG |
| Kerry Group plc |
| International Flavors & Fragrances Inc. |
| Döhler GmbH |
| Procter & Gamble |
| Vinayak Ingredients |
| Nexira |
| Tropicana Products Inc. |
| Others |
Value Network & Pricing Analysis
Spray-drying technology displacement by low-temperature vacuum belt drying simultaneously redraws supplier geography toward European technology leaders and compresses commodity-grade pricing power among legacy processors. EU Green Deal deforestation-free mandates add certification premiums that widen spreads between traceable Mediterranean supply and speculative Brazilian concentrate.
Pricing Analysis
Technology-generation pricing gaps separate legacy spray-dried grades from vacuum-belt premium tiers and emerging encapsulation formats. Three-tier pricing structure across organic-certified, natural-conventional, and synthetic-economy levels reflects certification burden and terpene preservation performance. Cost compression in commodity spray-dried segments intensifies as Brazilian harvest volatility feeds raw material instability. Industrial compounders exhibit highest price sensitivity; functional beverage formulators accept premiums for volatile compound retention.
Supply Chain Analysis
Strategic stockpile preferences dominate among European compounders buffering against Brazilian citrus harvest volatility, while just-in-time procurement persists in cosmetics and lower-grade foodservice applications. Supply concentrates in Brazil for raw concentrate, India for finished nutraceutical grades, and Mediterranean cooperatives for clean-label certified stock. Processor networks draw from citrus sinensis orchards, spray-drying capacity, and analytical certification infrastructure. Single-source vulnerability concentrates in São Paulo-state concentrate supply. Distribution runs through Rotterdam-Amsterdam trading clusters for European compounders and direct cooperative offtake for German and Dutch formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory inflection across EU and North American jurisdictions creates high-growth disruption as synthetic flavorant displacement accelerates and traceability mandates consolidate procurement toward integrated processors.
For Market Incumbents: Consolidate backward integration into Mediterranean and Brazilian orchard networks to secure deforestation-free certification continuity. Expand low-temperature vacuum belt drying capacity to capture premium beverage formulation demand. Channel control through direct cooperative offtake agreements marginalizes speculative traders lacking origin documentation.
For New Entrants and Emerging Players: Differentiate on Ayurvedic nutraceutical specialization targeting Maharashtra and Gujarat traditional medicine manufacturers. Penetrate underdeveloped Indian organized retail channels for branded consumer positioning. E-commerce ingredient platforms offer go-to-market access without volume minimum barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private Mediterranean cooperative aggregators and Indian regional processors lacking EU certification infrastructure. Long-term viability hinges on regulatory compliance scalability across EFSA Novel Food and EU Green Deal traceability mandates. Acquisition targets should demonstrate captive orchard relationships or spray-drying technology differentiation. The signal to watch is EFSA purity standard threshold tightening beyond Codex Alimentarius baselines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Networks | Captive sourcing secures deforestation-free certification continuity under EU Green Deal mandates. |
| Low-Temperature Drying Capacity Expansion | Vacuum belt technology preserves heat-sensitive terpenes for premium beverage applications. |
| Direct Cooperative Sourcing Agreements | Multi-year offtake contracts with Mediterranean growers bypass distributor markups. |
| EFSA Novel Food Regulatory Pathway | Enhanced polyphenol concentrates qualify for premium nutraceutical positioning. |
| E-Commerce Platform Partnership | Direct procurement channels unlock certified organic grades for mid-sized formulators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across beverage formulation, nutraceutical compounding, and citrus processing domains. Primary interviews engaged flavor house procurement directors, Ayurvedic manufacturer technical leads, spray-drying equipment specialists, and EU regulatory affairs consultants. Secondary validation drew from EFSA additive safety opinions, EU Green Deal implementation texts, FSSAI food safety standards, and customs trade flow records. Bottom-up volume modeling and top-down market sizing were triangulated against processor capacity disclosures.
Across the analysis window, forecasts segment by product origin, application purity grade, and end-user procurement scale. CAGRs derive from regression against citrus harvest cycles, clean-label adoption curves, and certification cost trajectories. Modeled inputs include Brazilian orange crop yield variance, EU organic conversion timelines, and spray-drying technology substitution rates.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or abrupt synthetic flavorant price collapse would require recalibration. Forecasts reflect documented assumptions regarding harvest volatility persistence and certification timeline rigidity. Revision becomes warranted when EFSA purity thresholds tighten beyond current proposal baselines or when Indian domestic processing capacity expansion outpaces demand absorption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
USA Yeast Extracts Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Cooking Oils and Fats Market
Ingredients
Sunflower Lecithin Market
Ingredients
Oyster Shell Powder Market
Ingredients
South America Feed Yeast Market
Ingredients
Camelina Oil Market
Ingredients
Rose Hips Extract Market
Ingredients
Gum Arabic Market
Ingredients
Rennet Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Arachidonic Acid Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Low Calorie Oil Market