
 Meat Alternative Market | 2026-2036
Meat Alternative Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Alternative Market Outlook
The meat alternative category is pivoting between premium whole-muscle cuts and commodity ground-format products, with price spreads widening as ingredient costs diverge. Beyond Meat leverages extrusion technology investments to sustain manufacturing scale across North American retail channels. Impossible Foods anchors its position through heme protein R&D intensity and foodservice partnerships. Tyson Foods competes via protein industry infrastructure and conventional meat distribution networks that extend into plant-based SKUs.
Meat alternatives comprise formulated protein products designed to replicate the sensory properties—texture, flavor, mouthfeel—of conventional animal meat, typically achieving 15-25 grams of protein per serving through extrusion, fermentation, or shear-cell processing. Their primary commercial purpose is to serve flexitarian consumers reducing animal product intake without abandoning familiar meal formats. Plant-based burgers dominate refrigerated case space and command premium positioning in Western retail, while mycoprotein sources represent the fastest-growing ingredient category due to complete amino acid profiles and fermentation efficiency. Frozen form factors retain volume leadership in mass-market channels, though ready-to-eat formats are capturing convenience-oriented demand in urban markets.
FDA nutrition labeling requirements and USDA organic certification standards shape product formulation thresholds and marketing claims in the United States, while EFSA novel food assessments govern mycoprotein approvals across European markets. These frameworks elevate compliance costs for new entrants but simultaneously validate safety profiles that expand retail access. Stakeholders must monitor evolving protein quality scoring methodologies and carbon labeling mandates that will soon differentiate shelf placement and procurement criteria.
Market Dynamics
Restaurant chains and institutional foodservice channels are accelerating procurement of plant-based proteins, creating demand pull that outpaces retail channel growth. This shift concentrates purchasing power among fewer buyers with stringent formulation requirements and volume commitments.
Growth Catalysts
- FDA Labeling Guidelines:Tightening ingredient disclosure requirements validate product safety profiles and expand retail access for compliant manufacturers.
- Pea Protein Extrusion:Advances in high-moisture extrusion technology enable whole-muscle texture replication at commercial scale.
- German Retail Expansion:Widened distribution for mycoprotein and pea-based products concentrates demand in Europe's largest plant-based market.
Market Restraints
- Input Cost Volatility:Pea protein isolate and coconut oil prices fluctuate with agricultural commodity cycles, compressing margin stability.
- Supply Concentration Risk:Mycoprotein fermentation capacity clusters in a handful of European facilities, creating geographic vulnerability.
- EFSA Novel Food Assessments:Extended approval timelines for new fermentation-derived proteins delay European market entry.
Strategic Opportunities
- USDA Organic Certification:Premium positioning through certified organic supply chains captures price-insensitive consumer segments.
- Ready-to-Eat Formats:Pre-cooked, shelf-stable products penetrate convenience-oriented urban markets with limited cold-chain infrastructure.
- Shear-Cell Processing:Convergence with 3D food printing enables customized texture profiles for foodservice clients.
Industry Challenges
- Extrusion Engineering Talent:Scarcity of process engineers with protein texturization expertise constrains manufacturing expansion.
- Carbon Labeling Compliance:Emerging lifecycle assessment requirements demand new data infrastructure and third-party verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Alternative Market |
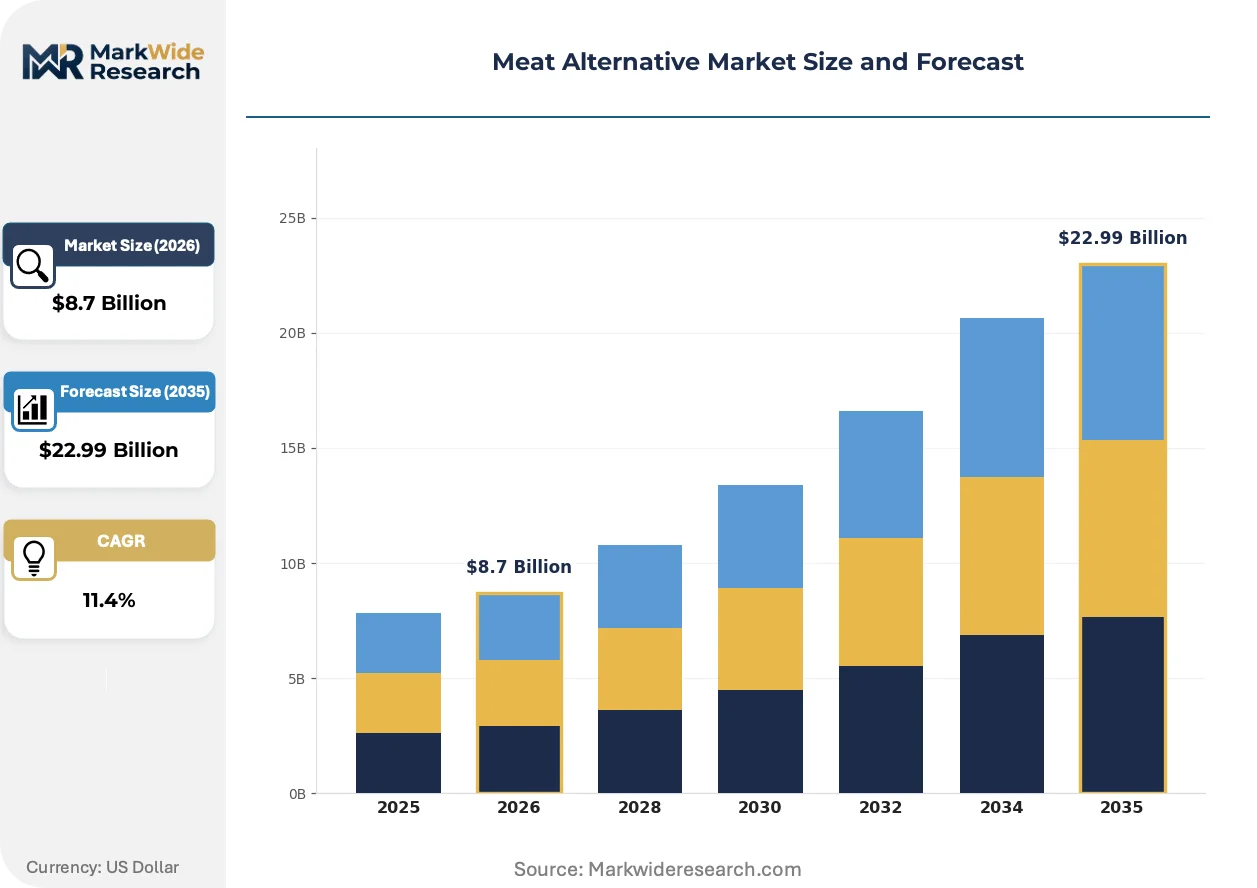
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Burgers, Meatless Sausages, Tofu Products, Seitan Source: Pea Protein, Soy Protein, Wheat Protein, Mycoprotein Form: Frozen, Refrigerated, Dried, Ready-to-Eat Consumer Segment: Vegetarians, Vegans, Flexitarians, Meat Reducers |
| Companies Covered | Beyond Meat, Impossible Foods, Quorn Foods, Tofurky, Gardein, Morningstar Farms, Tyson Foods, Nestlé, Lightlife Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Alternative Market Strategic Shifts
Protein quality scoring methodologies and carbon labeling mandates are differentiating shelf placement and procurement criteria. These measurement frameworks reward transparency and penalize opacity.
High-moisture extrusion is unifying texture engineering across plant-based whole-muscle formats. Foodservice operators in North America are adopting these products for burger and steak alternatives at accelerating pace. This unifying technology is compressing the performance gap between premium and commodity protein formats.
REACH chemical safety regulations in Europe are tightening scrutiny of processing aids and additives in novel protein formulations. Manufacturers must reformulate or source alternative inputs to maintain market access. Mycoprotein producers face the steepest compliance burden due to fermentation-derived compound complexity.
Flexitarian consumers are rotating protein purchases across animal and plant categories based on occasion rather than ideology. Retailers are responding with integrated protein sections that mix conventional and alternative products. Germany and the United Kingdom display the most advanced merchandising of this hybrid approach.
Meat Alternative Market Segmentation
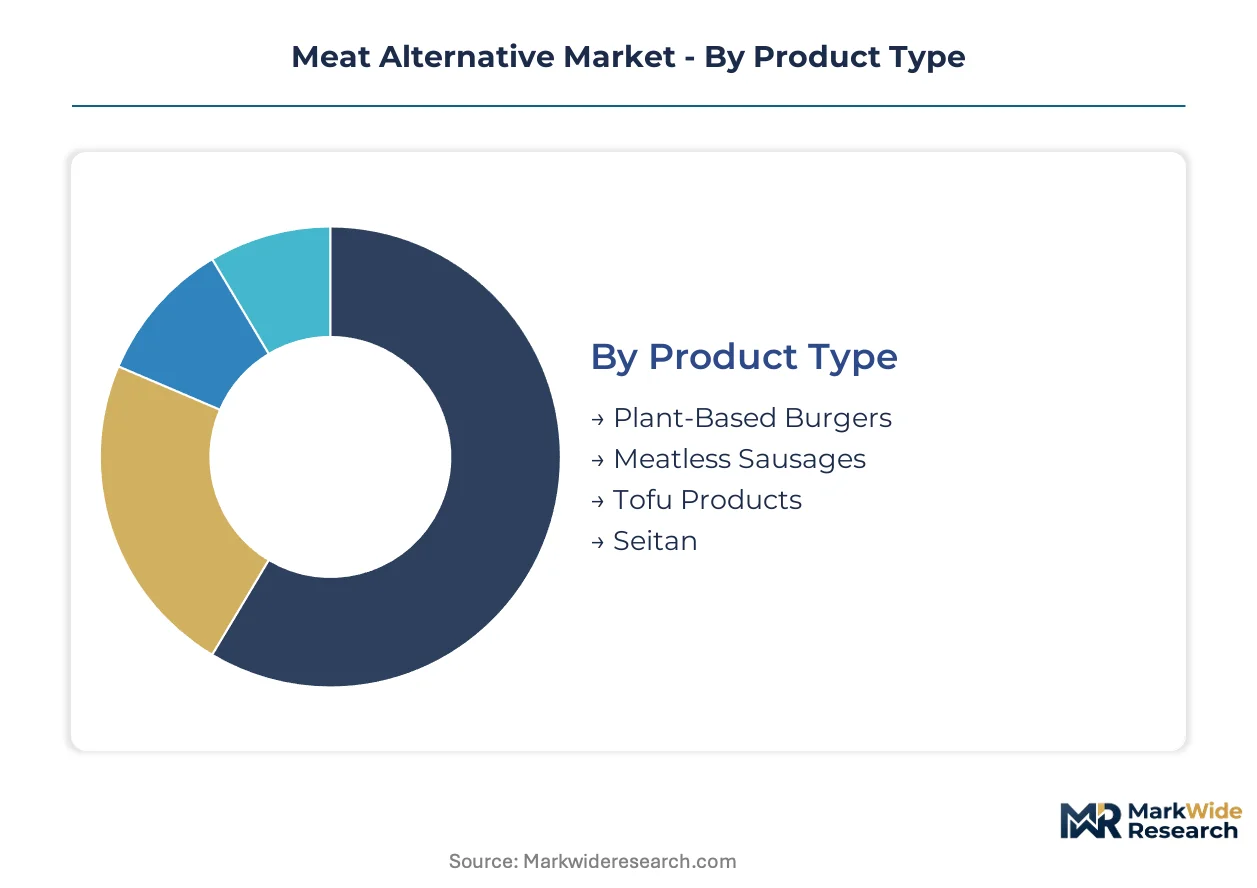
Segmentation in the meat alternative market determines capital allocation, manufacturing technology selection, and channel strategy. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across production footprints.
Product Type:
Capital intensity peaks with whole-muscle formats requiring extrusion infrastructure, while commodity ground products demand less specialized equipment.
- Plant-Based Burgers:Extruded or formed patties using pea or soy protein isolates with fat mimetic systems to replicate beef mouthfeel. Demand concentrates in North American foodservice chains where volume commitments justify dedicated production lines. High-moisture extrusion capacity constraints limit supplier switching.
- Meatless Sausages:Emulsion-style products combining protein isolates with coconut oil and methylcellulose for snap and juiciness. German and UK retail expansion drives refrigerated case placement. Casing technology and smoke application add processing complexity absent in burger formats.
- Tofu Products:Coagulated soy curd with minimal processing beyond pressing and packaging. Asian-origin production clusters dominate supply.
- Seitan:Vital wheat gluten washed and cooked to create dense, chewy textures. Artisanal production persists alongside emerging scaled facilities.
Most installed capacity flows through Plant-Based Burgers. Expansion is steepest in Meatless Sausages.
Source:
Raw material sourcing strategy separates integrated processors from toll manufacturers dependent on spot protein markets.
- Pea Protein:Yellow split pea isolate processed via wet fractionation to achieve 80-90% protein concentration with favorable amino acid scoring. Canadian and US agricultural supply chains anchor extraction capacity. FDA GRAS status and clean-label positioning accelerate retail adoption.
- Soy Protein:Defatted soy flour or concentrate with established supply infrastructure and cost advantages. Southeast Asian and South American crushing capacity supports global availability. Allergen labeling requirements constrain school and institutional penetration.
- Wheat Protein:Vital gluten recovered from starch processing with textural properties suited to seitan and hybrid formulations. European milling byproduct streams provide feedstock concentration.
- Mycoprotein:Fusarium venenatum fermentation yielding complete protein with fiber content and umami depth. UK and Netherlands production facilities supply expanding European retail distribution. EFSA novel food assessments govern new strain approvals.
Ingredient cost volatility hits Pea Protein hardest. Mycoprotein gains share fastest in premium positioning.
Form:
Cold-chain requirements dictate distribution economics and retail channel access across temperature-controlled infrastructure.
- Frozen:Blast-frozen products at -18°C preserving texture through extended shelf life. Mass-market retail and institutional foodservice dominate volume.
- Refrigerated:Fresh-case placement demanding rapid turnover and shorter dating. Western European and North American premium positioning.
- Dried:Dehydrated formats for ambient storage and emergency preparedness channels. Limited commercial scale outside Asian markets.
- Ready-to-Eat:Pre-cooked, shelf-stable or chilled products penetrating convenience-oriented urban demand with limited kitchen access.
Frozen maintains volume leadership. Ready-to-Eat climbs the fastest in metropolitan markets.
Consumer Segment:
Purchase frequency and price sensitivity diverge sharply across motivation-based segmentation, reshaping marketing investment and formulation trade-offs.
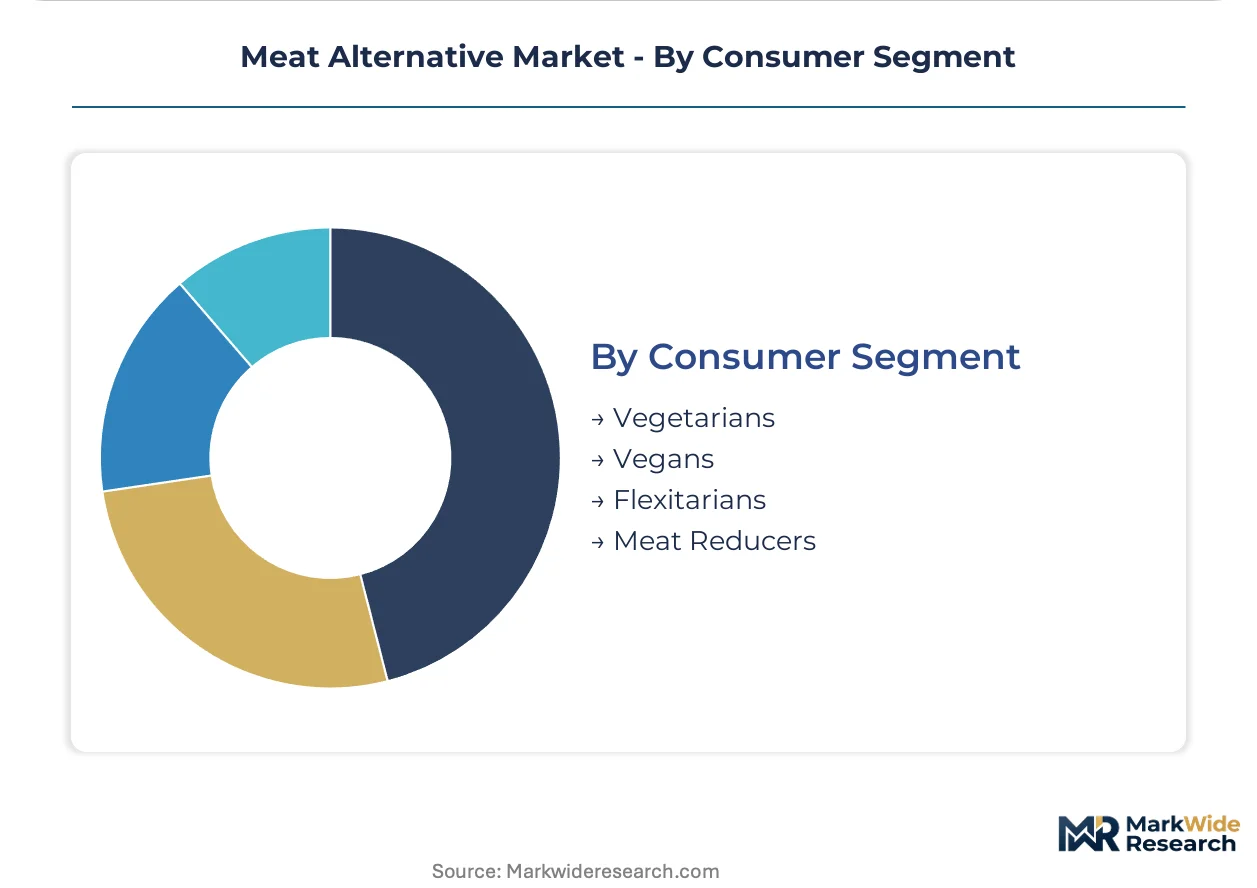
- Flexitarians:Omnivores reducing animal protein intake without dietary exclusion. Germany and UK display highest penetration. Occasion-based rotation between conventional and alternative proteins.
- Meat Reducers:Health-motivated consumers treating alternatives as periodic substitutes. Physician and nutritionist recommendations influence trial.
- Vegetarians:Longstanding abstention from meat with established brand loyalties and lower price elasticity.
- Vegans:Strictest formulation requirements excluding all animal derivatives including dairy, eggs, and honey. Certification demands elevate compliance costs.
Marketing spend concentrates on Flexitarians. Product development prioritizes Meat Reducers for mainstream conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers with protein texturization expertise concentrate in Germany, the Netherlands, and California, anchoring innovation clusters that supply formulation knowledge across three continents.
Germany
Foodservice procurement contracts and flexitarian retail demand drive mycoprotein and pea-based volume. EFSA novel food assessments govern strain approvals for fermentation-derived proteins. Berlin and Hamburg host the densest concentration of extrusion R&D facilities serving Central European distribution networks.
United States
Restaurant chain procurement and institutional foodservice channels accelerate plant-based protein adoption. FDA labeling guidelines and USDA organic certification standards shape formulation thresholds and marketing claims. California's Sacramento Valley and Illinois processing corridors anchor North American extrusion capacity expansion.
United Kingdom
Hybrid protein merchandising and flexitarian occasion-based purchasing concentrate demand in London and Manchester retail. REACH chemical safety regulations tighten scrutiny of processing aids in novel formulations. The Quorn fermentation facility in North Yorkshire supplies mycoprotein across British and Irish retail channels.
Netherlands
EFSA regulatory expertise and novel food assessment capabilities attract fermentation startups to Wageningen and Eindhoven. The country's food technology institutes validate safety profiles for European market entry. Rotterdam port infrastructure enables pea protein isolate import from Canadian agricultural supply chains.
Canada
Yellow split pea cultivation in Saskatchewan and Manitoba anchors extraction capacity for North American isolate supply. Health Canada and PMRA standards govern novel protein ingredient approvals. Vancouver and Toronto metropolitan areas concentrate plant-based product development talent and foodservice distribution.
Meat Alternative Market Competitive Environment
Top-tier vendors anchor foodservice and retail shelf space, while mid-scale specialists and ingredient suppliers occupy tiered positions below. The vendor base distributes across extrusion technology holders, fermentation operators, and conventional meat processors extending into plant-based SKUs. Three archetypes dominate: dedicated plant-based pure-plays, diversified protein conglomerates, and mycoprotein fermentation specialists. Competitive moves concentrate on high-moisture extrusion capacity expansion and strategic foodservice partnerships securing volume commitments.
Within the dedicated plant-based tier, Beyond Meat and Impossible Foods occupy positions defined by contrasting technology bets—extrusion infrastructure versus heme protein R&D intensity. Quorn Foods exemplifies the fermentation-specialist archetype through mycoprotein production anchored in European facilities. Tyson Foods represents diversified protein conglomerates leveraging conventional meat distribution networks to extend into plant-based SKUs.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Quorn Foods |
| Tofurky |
| Gardein |
| Morningstar Farms |
| Tyson Foods |
| Nestlé |
| Lightlife Foods |
| Others |
Value Chain & Pricing Dynamics
High-moisture extrusion technology adoption is compressing cost differentials between whole-muscle and ground-format production while concentrating manufacturing capacity among operators with capital-intensive equipment investments. This production-method transition simultaneously elevates fixed-cost thresholds and consolidates supplier pricing power across North American and European markets.
Pricing Analysis
Packaged-versus-bulk ingredient sourcing splits the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. Price differentiation reflects USDA organic certification premiums and extrusion technology tiers. Cost compression in commodity ground products is intensifying because pea protein isolate spot markets fluctuate with Canadian agricultural cycles. Institutional foodservice buyers exhibit lowest price sensitivity due to long-term procurement contracts, while mass-market retailers negotiate aggressively on frozen case goods.
Supply Chain Analysis
Single-source vulnerability sits with mycoprotein fermentation capacity clustered in the United Kingdom and Netherlands. Yellow split pea isolate draws from Canadian prairie cultivation and wet-fractionation facilities in Saskatchewan and Manitoba. Coconut oil for fat-mimetic systems sources from Southeast Asian processing centers. Geographic concentration risk amplifies tariff exposure on pea protein imports into European extrusion plants. Distribution runs through cold-chain logistics networks serving frozen retail cases and refrigerated fresh-case placement in urban supermarkets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where flexitarian demand rotation favors premium whole-muscle formats with superior sensory replication and clean-label positioning.
For Market Incumbents: Acquire extrusion engineering talent pools in Germany and California to defend against fermentation-derived protein substitutes. Expand high-moisture extrusion capacity in the Sacramento Valley processing corridor. Secure backward integration into yellow split pea cultivation through long-term offtake agreements with Canadian agricultural cooperatives.
For New Entrants and Emerging Players: Foodservice distributors represent the most accessible channel partnership for volume penetration. Target ready-to-eat shelf-stable formats in metropolitan markets with constrained cold-chain infrastructure. White-space opportunity concentrates in pre-cooked mycoprotein products for convenience-oriented flexitarian households.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale fermentation specialists because EFSA novel food assessment capabilities create regulatory moats around approved strain portfolios. Five-to-ten year viability hinges on carbon labeling compliance infrastructure and lifecycle assessment verification capabilities. Monitor procurement contract announcements from major North American restaurant chains as inflection indicators for volume scale validation.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Enables whole-muscle texture replication at commercial scale for foodservice burger and steak alternatives. |
| EFSA Novel Food Assessment Completion | Validates safety profiles for mycoprotein strain approvals and unlocks European retail distribution access. |
| USDA Organic Certification Investment | Captures price-insensitive consumer segments through certified supply chain differentiation. |
| Foodservice Partnership Securement | Locks volume commitments from restaurant chains with stringent formulation and procurement requirements. |
| Carbon Labeling Compliance Infrastructure | Positions products for shelf placement differentiation under emerging lifecycle assessment mandates. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with plant-based protein R&D directors, foodservice procurement managers, extrusion technology engineers, and retail category buyers. Secondary validation draws from FDA GRAS filings, EFSA novel food registers, USDA organic certification databases, and Canadian agricultural trade statistics. Bottom-up volume modeling triangulates against top-down market sizing across ingredient cost structures and channel throughput estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product format, protein source, temperature-controlled distribution tier, and consumer motivation archetype. CAGRs derive from installed capacity expansion schedules, foodservice contract announcement tracking, and retail distribution width metrics. Forecast inputs incorporate pea protein isolate spot price volatility indices and EFSA approval timeline distributions for fermentation-derived strains.
Revisions become necessary when regulatory approval delays, agricultural commodity shocks, or carbon labeling mandate acceleration materialize outside baseline assumptions. Forecasts reflect documented scenario parameters with explicit trigger thresholds for demand-shift and supply-disruption contingencies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Pet Food Microalgae Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Carragean Alternatives Market