
 Lentils Flour Market | 2026-2036
Lentils Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Lentils Flour Market Foresight
Food manufacturers seeking clean-label binders is unwinding traditional household-driven demand patterns for lentils flour. AGT Food and Ingredients anchors Canadian prairie sourcing through direct farmer contracts. Cargill leverages its global grain logistics network to secure cost-advantaged red and green lentil supply. Bob's Red Mill Natural Foods differentiates through stone-ground positioning and organic certification depth in specialty retail channels.
Lentils flour consists of milled dehulled or whole lentil seeds, typically yielding 20-25% protein content with functional starch gelatinization properties between 60-70°C, serving primarily as a gluten-free structural agent and protein fortifier in baked goods and extruded snacks. Red lentils flour dominates volume given its milder flavor profile and superior starch binding in commercial bakery formulations, while black lentils flour captures premium positioning in nutritional supplement applications targeting elevated anthocyanin content. The application split reveals baking as the established revenue base, with snack preparation representing the fastest structural expansion as extruded pulse crisps displace conventional potato and corn alternatives.
Health Canada and the FDA govern allergen labeling and protein content claims that directly shape product positioning and market access for lentils flour entrants into North American retail and foodservice channels. The EU Green Deal and REACH frameworks impose sustainability traceability requirements on imported pulse ingredients, elevating compliance costs for non-European suppliers while creating preferential access for certified organic and carbon-audited origins. Stakeholders must monitor evolving protein-content threshold definitions across jurisdictions, as these technical specifications will determine which milling fractions qualify for premium nutritional positioning versus commodity-grade pricing.
Market Dynamics
Clean-label formulation mandates from North American retailers are forcing bakery manufacturers to replace modified wheat starches with pulse-based binders, concentrating procurement power among vertically integrated millers who control certified organic lentil supply chains.
Growth Catalysts
- EU Green Deal protein diversification targets:The framework mandates 25% plant-protein inclusion in institutional food procurement by 2030, creating guaranteed offtake for lentil flour fortification in European bakery and extruded snack production.
- Extrusion technology maturation:Twin-screw extrusion systems now achieve 92% starch gelatinization at lower thermal inputs, enabling lentil flour to replace potato and corn bases in high-volume crisp manufacturing without texture degradation.
- Madhya Pradesh processing cluster expansion:Indian government-backed pulse processing infrastructure is concentrating dehulling and milling capacity near source farms, reducing export logistics costs for red lentil flour bound to gluten-free manufacturers.
Market Restraints
- Red lentil price volatility:Weather-driven yield fluctuations in Canadian prairie provinces create 18-24 month input cost cycles that compress margins for toll millers lacking forward contract coverage.
- REACH traceability compliance:EU importers must document carbon intensity and pesticide residue across three supply chain tiers, elevating certification costs for non-European origins above competitive thresholds.
- Wheat starch functional equivalence:Modified wheat derivatives retain superior freeze-thaw stability in frozen dough applications, limiting lentil flour penetration in prepared bakery segments.
Strategic Opportunities
- Black lentil anthocyanin positioning:Nutraceutical formulators in Japan and South Korea are sourcing pigment-rich fractions for functional food applications, commanding 3-4x commodity flour pricing.
- Direct-to-manufacturer e-procurement platforms:Digital marketplaces connecting Indian millers with North American specialty bakeries are compressing distributor markups and accelerating sample-to-contract cycles.
- Health Canada protein content thresholds:Pending regulatory clarity on pulse protein claim thresholds will enable "high-protein" labeling for lentil-fortified products, unlocking premium retail placement.
Industry Challenges
- Specialized milling technician scarcity:Pulse flour production requires expertise in dehulling efficiency and particle size distribution control that exceeds conventional cereal milling training programs.
- Organic certification timeline compression:Three-year transition periods for conventional lentil farms create supply gaps during demand surges, forcing manufacturers to dual-source certified and transitional grades.
- Extrusion parameter standardization:Lack of industry-wide moisture-temperature protocols for lentil flour blends forces snack manufacturers to run costly line trials for each supplier change.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lentils Flour Market |
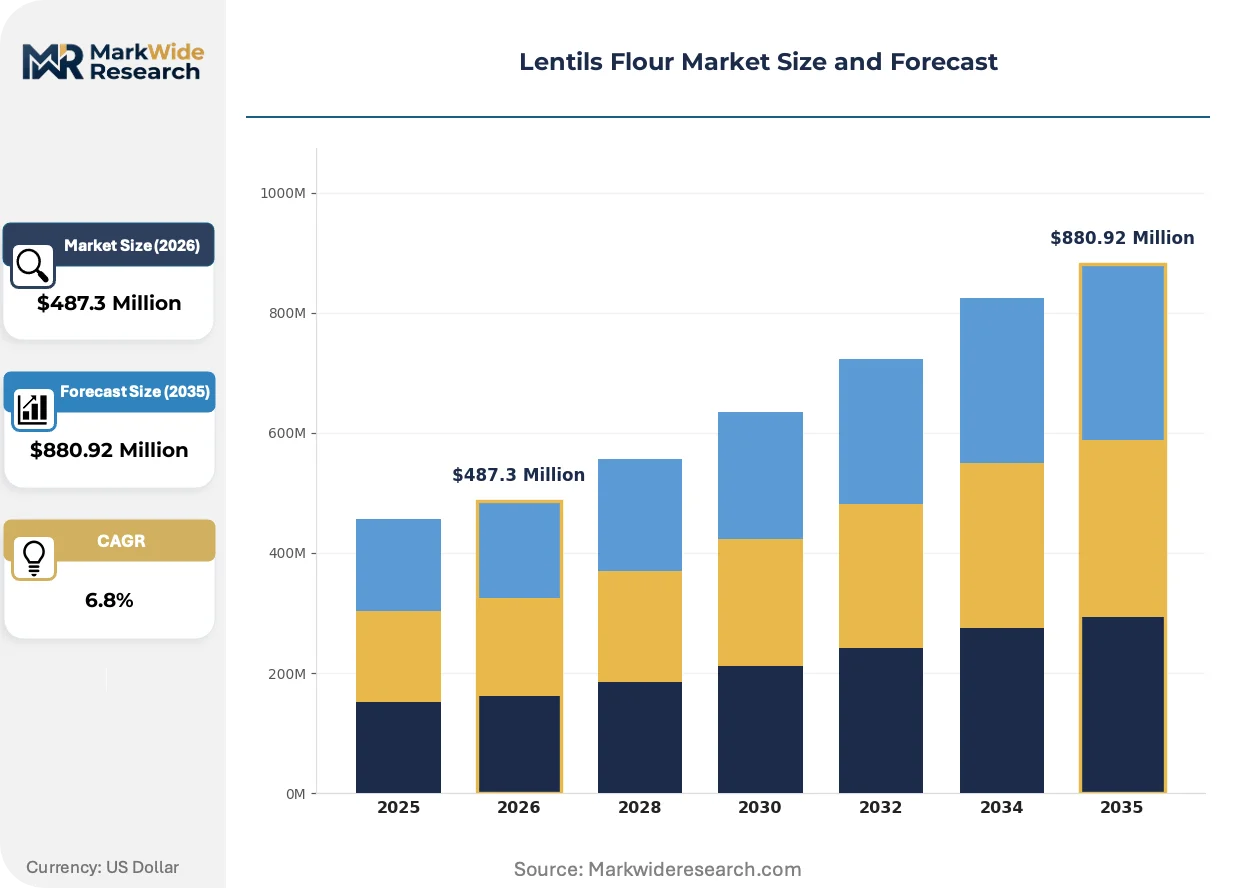
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Lentils Flour, Green Lentils Flour, Black Lentils Flour, Brown Lentils Flour Application: Baking, Cooking, Nutritional Supplement, Snack Preparation End User: Households, Food Manufacturers, Hotels & Restaurants, Health Stores Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Archer Daniels Midland Company, Ingredion Incorporated, AGT Food and Ingredients, Bunge Limited, Bob's Red Mill Natural Foods, Cargill, Ardent Mills, Martinorossi SpA, Molino Rossetto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lentils Flour Market Shifts & Advancements
Stone-milling revival intersects with precision extrusion engineering to create dual-track innovation paths, splitting the market between artisan-positioned specialty flours and mass-scale functional ingredients for processed food reformulation.
Air-classification milling technology is displacing traditional hammer milling in premium lentil flour production, enabling precise protein-starch fractionation that delivers 35%+ protein concentrates. North American contract manufacturers serving gluten-free bakery brands are retrofitting facilities with these systems to meet clean-label specifications. The capital intensity of this upgrade is compressing toll milling margins and accelerating consolidation among mid-scale processors.
REACH sustainability traceability requirements are forcing EU-bound exporters to implement blockchain-based lot tracking from farm gate to port, adding 8-12% administrative overhead to Indian and Canadian shipments. Large food manufacturers with dedicated procurement teams are absorbing these costs through long-term supply agreements, while spot-market buyers are retreating to domestic European pulse sources. The compliance burden is reshaping competitive positioning toward vertically integrated suppliers with captive certification infrastructure.
Specialty retailers are consolidating shelf-space allocation decisions through centralized category management, displacing regional distributor influence over lentil flour placement. Bob's Red Mill and comparable stone-ground brands are securing end-cap positioning through direct-store-delivery agreements that bypass traditional wholesale channels. This channel compression is most visible in Pacific Northwest and Northeast US markets where independent natural grocery chains retain significant share.
Lentils Flour Market Segmentation
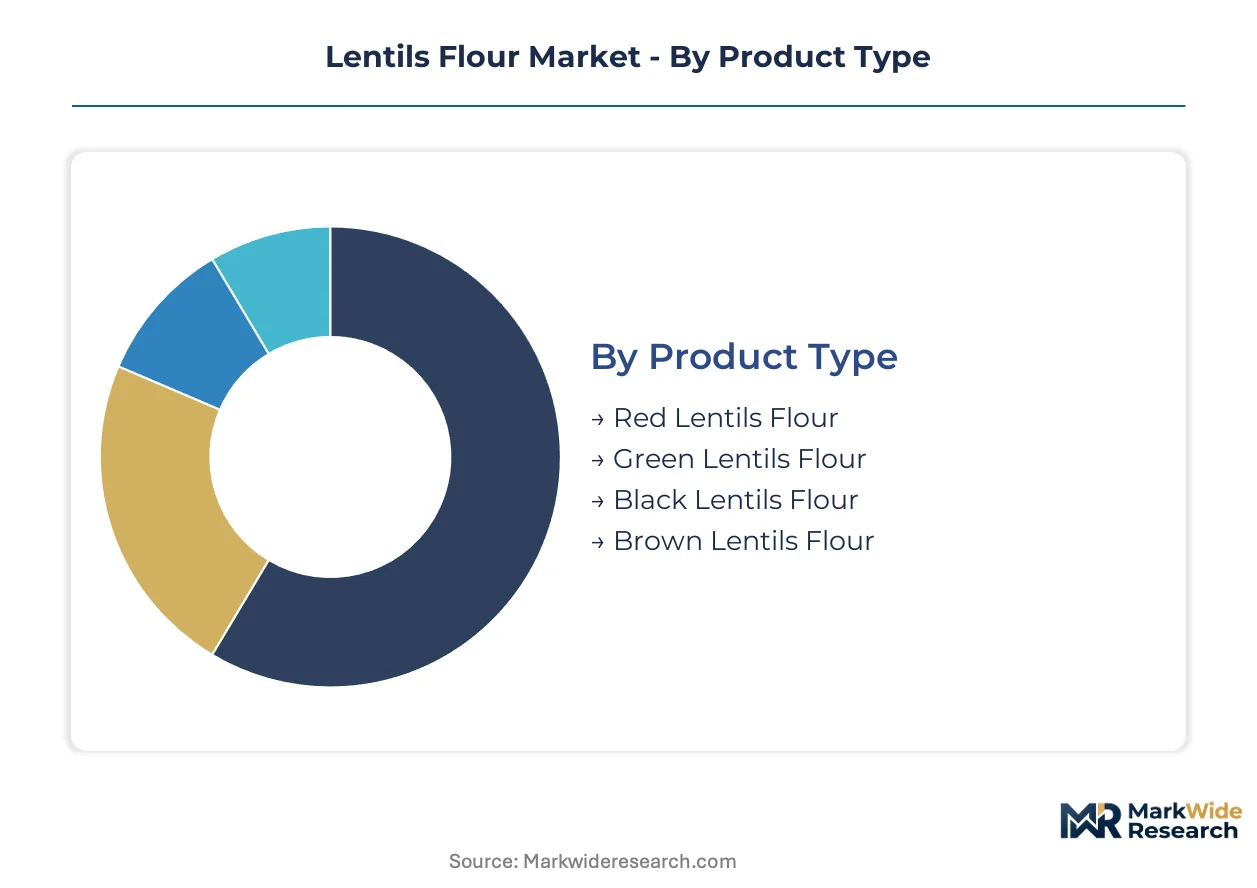
Lentils flour segmentation reveals distinct channel pathways that separate commodity bulk flows from premium specialty positioning. Product type and application splits determine whether millers sell through distributor networks or direct-to-manufacturer contracts.
Product Type:
Red lentils flour moves primarily through wholesale channels serving high-volume bakery manufacturers, while black and green varieties concentrate in specialty retail and health store distribution.
- Red Lentils Flour:Mild flavor profile and superior starch gelatinization at 60-70°C make this the default choice for gluten-free bakery formulations. North American contract manufacturers source this grade through direct farmer contracts in Canadian prairie provinces to secure price stability against weather-driven yield cycles.
- Black Lentils Flour:Anthocyanin-rich pigment content commands premium positioning in nutraceutical applications. Japanese and South Korean formulators source this grade for functional food products at pricing multiples above commodity flour levels.
- Green Lentils Flour:Earthier flavor profile suits savory applications in European institutional procurement channels aligned with EU Green Deal protein diversification targets.
- Brown Lentils Flour:Intermediate positioning between red and green varieties serves regional South Asian cooking applications through ethnic grocery distribution networks.
By volume, Red Lentils Flour leads. By growth pace, Black Lentils Flour is climbing the fastest.
Application:
Cost tier differentiation separates commodity baking applications from premium nutritional supplement positioning, with snack preparation emerging as the volume bridge between these poles.
- Baking:Established revenue base serving gluten-free bread, pastry, and pasta manufacturers. Twin-screw extrusion compatibility enables clean-label reformulation replacing modified wheat starches in frozen dough segments where freeze-thaw stability constraints persist.
- Snack Preparation:Extruded pulse crisps displace conventional potato and corn bases through 92% starch gelatinization efficiency at reduced thermal inputs. North American and European manufacturers retrofit production lines to capture clean-label positioning in retail crisp categories.
- Cooking:Traditional household and foodservice demand for thickening agents in soups and sauces flows through ethnic grocery and wholesale cash-and-carry channels.
- Nutritional Supplement:Protein fortification powders and meal replacement formulations source air-classified fractions with 35%+ protein concentrates through direct manufacturer relationships bypassing traditional distribution.
Snack Preparation commands the steepest expansion trajectory as extrusion technology maturation unlocks mass-scale substitution.
End User:
Customer type determines procurement pattern complexity, with food manufacturers demanding certified traceability while households purchase through retail intermediaries.
- Food Manufacturers:Vertically integrated millers with captive organic certification infrastructure capture long-term supply agreements from gluten-free bakery and extruded snack producers requiring REACH-compliant documentation.
- Health Stores:Stone-ground and organic-certified positioning commands end-cap placement through direct-store-delivery agreements, particularly in Pacific Northwest and Northeast US independent natural grocery channels.
- Households:Traditional demand driver for home baking and ethnic cuisine preparation, now unwinding as clean-label commercial alternatives capture share.
- Hotels & Restaurants:Institutional procurement in EU member states accelerates under mandated plant-protein inclusion targets for public sector foodservice.
Food Manufacturers dominate current procurement volume. Health Stores are gaining share fastest as specialty retail consolidates category management decisions.
Distribution Channel:
Supply concentration in Indian processing clusters and Canadian prairie origins shapes channel economics, with digital platforms compressing traditional distributor markups.
- Wholesale:Bulk flows from Madhya Pradesh and Uttar Pradesh processing clusters serve North American and European toll millers through established maritime logistics networks.
- Online Stores:Direct-to-manufacturer e-procurement platforms connecting Indian millers with specialty bakeries accelerate sample-to-contract cycles and reduce intermediary layers.
- Specialty Stores:Stone-ground brands secure premium positioning through organic certification depth and artisan milling narratives in natural grocery channels.
- Supermarkets:Mass retail placement requires scale supply agreements that favor red lentils flour grades with consistent functional specifications.
Wholesale channels handle the greatest tonnage. Online Stores are expanding most quickly as procurement digitization penetrates specialty ingredient sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian prairie provinces export red lentil flour through Vancouver and Montreal terminals to North American gluten-free manufacturers and European institutional buyers. Indian processing clusters in Madhya Pradesh and Uttar Pradesh ship dehulled fractions to Middle Eastern and Southeast Asian markets. Australian pulse belt output increasingly targets East Asian nutraceutical formulators seeking anthocyanin-rich black lentil grades.
United States
Clean-label bakery reformulation drives procurement from domestic toll millers and Canadian cross-border suppliers. FDA allergen labeling requirements and pending protein content claim thresholds shape product positioning for lentil-fortified retail goods. Pacific Northwest independent natural grocery chains concentrate stone-ground brand distribution through direct-store-delivery agreements.
Canada
AGT Food and Ingredients anchors prairie sourcing through direct farmer contracts in Saskatchewan and Alberta, securing price stability against weather-driven yield cycles. Health Canada governs protein content thresholds that determine premium nutritional labeling eligibility. Winnipeg and Saskatoon milling hubs process export-ready red lentil flour for North American and EU-bound shipments.
India
Madhya Pradesh and Uttar Pradesh processing clusters concentrate dehulling and milling capacity near source farms, reducing logistics costs for export-bound red lentil flour. FSSAI standards and DGFT export documentation requirements govern international shipments. Indore and Kanpur processing zones supply North American specialty bakeries through direct-to-manufacturer e-procurement platforms.
Germany
EU Green Deal protein diversification targets mandate plant-protein inclusion in institutional food procurement, creating guaranteed offtake for lentil flour fortification. REACH traceability requirements impose carbon intensity and pesticide residue documentation across three supply chain tiers. Hamburg port facilities handle bulk imports from Canadian and Indian origins for redistribution to European bakery manufacturers.
Japan
Nutraceutical formulators source anthocyanin-rich black lentil fractions for functional food applications at premium pricing multiples. METI standards govern food additive classifications and health claim substantiation requirements. Osaka and Tokyo metropolitan area processing facilities refine imported lentil concentrates for domestic supplement and cosmetic ingredient markets.
Lentils Flour Market Competitive Landscape
Listed leaders compete with private specialists across sourcing control and certification infrastructure dimensions. Publicly traded grain traders and ingredient conglomerates leverage global logistics networks to secure cost-advantaged supply, while family-owned millers dominate stone-ground specialty positioning. Three archetypes define competitive structure: vertically integrated prairie processors with captive farmer contracts, global traders with maritime logistics dominance, and artisan-positioned specialty brands with organic certification depth. Capacity consolidation and backward integration into pulse processing infrastructure represent the dominant competitive moves.
Among North American fabricators, AGT Food and Ingredients exemplifies the vertically integrated processor archetype through its Saskatchewan-based sourcing control. Cargill occupies a position representing global trader logistics scale across multiple grain categories. Bob's Red Mill Natural Foods anchors the specialty retail tier through stone-ground positioning and organic certification depth in natural grocery channels.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| AGT Food and Ingredients |
| Bunge Limited |
| Bob's Red Mill Natural Foods |
| Cargill |
| Ardent Mills |
| Martinorossi SpA |
| Molino Rossetto |
| Others |
Supply & Pricing Matrix
Fourteen-day port-to-mill lead times for Canadian prairie red lentil shipments concentrate pricing power among vertically integrated processors with captive farmer contracts, while Indian cluster exports compress margins for spot-market toll millers lacking forward coverage.
Pricing Analysis
Hammer-milling legacy pricing faces compression against air-classification premium tiers that command 35%+ protein concentrate multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by organic certification depth and particle size distribution precision. Cost compression in commodity red lentil flour intensifies because REACH traceability overhead elevates EU-bound shipment costs above competitive thresholds for non-integrated suppliers. Food manufacturers with long-term supply agreements exhibit lowest price sensitivity, while ethnic grocery distributors and spot-market bakery buyers demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate among North American gluten-free manufacturers hedging against Canadian prairie weather-driven yield cycles, while just-in-time procurement governs European institutional buyers with mandated EU Green Deal offtake guarantees. Geographic supply concentrates in Canada, India, and Australia. Raw material flows draw from Saskatchewan prairie red lentil farms, Madhya Pradesh dehulling clusters, and New South Wales black lentil belts. Single-source vulnerability runs through Vancouver and Montreal port terminals handling 60%+ of North American import volume. Distribution runs through vertically integrated processor direct contracts, wholesale maritime bulk, and emergent e-procurement platforms connecting Indian millers with specialty bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among North American gluten-free bakery manufacturers and European institutional foodservice operators has shifted buyer power toward volume-guaranteed contract structures that disadvantage spot-market suppliers.
For Market Incumbents: Secure captive organic certification infrastructure to defend margin position against REACH traceability cost escalation and Indian cluster price competition. Backward integration into Saskatchewan prairie farmer contracts locks in supply security against weather-driven yield volatility. Channel control through direct-store-delivery agreements with Pacific Northwest independent natural grocery chains preserves end-cap placement against distributor displacement. For New Entrants and Emerging Players: Digital marketplace service-layer gaps in sample-to-contract acceleration and blockchain lot documentation present white-space entry points. Black lentil anthocyanin fractionation for Japanese nutraceutical formulators offers the most penetrable premium tier. A direct-to-manufacturer e-procurement go-to-market angle bypasses traditional distributor markups and compresses sales cycles for North American specialty bakeries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified grain traders seeking to divest non-core pulse processing assets amid portfolio rationalization. Long-term viability hinges on certification infrastructure depth and extrusion technology compatibility for snack manufacturing substitution. Watch for Health Canada protein content threshold clarity as the inflection signal unlocking premium nutritional labeling and retail placement multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Air-Classification Milling Retrofit | Enables 35%+ protein concentrate production for clean-label bakery specifications. |
| Blockchain Traceability Implementation | Satisfies REACH three-tier documentation requirements for EU Green Deal compliance. |
| Direct Farmer Contract Expansion | Secures price stability against Canadian prairie weather-driven yield cycles. |
| Specialty Retail Channel Bypass | Direct-store-delivery agreements with independent natural grocers capture end-cap placement. |
| Black Lentil Fractionation Capacity | Captures 3-4x commodity pricing from Japanese nutraceutical formulators. |
Research Methodology
Operator-level perspectives from pulse mill operations managers, gluten-free bakery procurement directors, EU institutional foodservice buyers, and Indian cluster export coordinators anchored the qualitative base. Primary interview data combined with secondary validation from FSSAI export documentation, Health Canada protein claim filings, EU Green Deal procurement mandates, and Canadian Grain Commission trade statistics. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against red lentil price volatility bands and REACH compliance cost escalation scenarios. Segmentation dimensions modeled include lentil variety type, application category, end-user archetype, and regional regulatory cluster. CAGRs derived from installed extrusion capacity expansion trajectories and institutional procurement mandate penetration curves. Industry-specific inputs encompassed twin-screw extrusion technology maturation rates and organic certification transition timelines.
Underlying assumptions cover sustained EU Green Deal procurement enforcement, stable Canadian prairie yield patterns, and Health Canada protein threshold clarity, with deviation risk concentrated in weather-driven input cost spikes and blockchain traceability adoption lags. Forecasts reflect these documented conditions with explicit scenario boundaries. Revision becomes warranted when EU institutional procurement mandate compliance rates cross 80% threshold or when air-classification milling capacity expansion outpaces specialty bakery demand absorption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Canola Meal Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
North America Carrageenan Market
Ingredients
Kairomones Market
Ingredients
Avocado Oil Market
Ingredients
Halal Ingredients Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Moringa Ingredients Market
Ingredients
Europe Amino Acid Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Oyster Peptide Market
Ingredients
Potato Starch Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Multi-Grain Premixes Market
Ingredients
South America Protein Market